
 Hybrid Memory Cube Market | 2026-2036
Hybrid Memory Cube Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Memory Cube Market Intelligence
REACH compliance for restricted substances in semiconductor packaging is hardening the cost-of-entry calculus for new Hybrid Memory Cube suppliers seeking European market access. Micron Technology leverages its captive TSV fabrication network to sustain cost advantages in DRAM-based HMC modules. Samsung Electronics anchors the highest-volume 3D stacking capacity, while SK Hynix competes through specialized HBM-adjacent process know-how.
A Hybrid Memory Cube is a high-bandwidth memory device that stacks multiple DRAM dies vertically using through-silicon vias (TSVs) on a logic base layer, delivering memory bandwidth exceeding 320 GB/s for bandwidth-constrained computing workloads. The architecture serves primarily as a cache and buffer layer in systems where processor-memory bandwidth gaps limit performance. DRAM-based product types dominate current shipment volumes, while 3D Stacking and TSV technologies command the steepest R&D investment intensity as yield optimization remains critical. AI Processing applications within the end-use dimension are absorbing the fastest capacity additions, whereas Cloud Computing represents the most mature margin pool with established procurement specifications.
FDA oversight applies to HMC components embedded in medical imaging and diagnostic equipment, while FCC electromagnetic compatibility rules govern telecommunications deployments of memory-intensive edge devices. The EU AI Act adds algorithmic transparency requirements that cascade into memory subsystem documentation for AI training hardware sold in Europe. Stakeholders must monitor how dual-use export control classifications from the US Bureau of Industry and Security affect TSV equipment sourcing and foundry partnerships.
Market Dynamics
The Hybrid Memory Cube market is being fundamentally restructured by the collision of AI training bandwidth requirements against TSV fabrication bottlenecks, creating a supply-constraint premium for high-stack DRAM modules.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for AI hardware sold in Europe are forcing memory subsystem documentation upgrades, pulling HMC modules into certified AI training clusters.
- Data center AI processing saturation:Training workloads hitting memory bandwidth walls are redirecting capex toward 320+ GB/s memory architectures as standard server DIMMs fail to feed GPU clusters.
- TSV yield improvements:Process refinements in South Korean fabrication lines are expanding economically viable die-stacking heights, lowering per-GB cost trajectories for high-bandwidth modules.
Market Restraints
- TSV equipment concentration:Advanced via-etching and bonding toolsets cluster among three equipment vendors, creating single-source vulnerability for new market entrants.
- REACH substance restrictions:ECHA-regulated materials in semiconductor packaging harden compliance costs for suppliers seeking European market access without established chemical stewardship systems.
- High-Bandwidth Memory substitution:HBM3E architectures from adjacent memory suppliers capture overlapping bandwidth-sensitive workloads with established supply relationships.
Strategic Opportunities
- India PLI scheme incentives:Domestic semiconductor manufacturing subsidies are opening assembly and test capacity for memory module localization serving South Asian data center buildouts.
- Edge AI inference deployment:Low-power HMC variants are penetrating autonomous vehicle and industrial vision systems where on-device model execution demands cache-density improvements.
- Medical imaging equipment refresh:FDA-cleared diagnostic systems are embedding HMC buffers to handle real-time volumetric scan data, creating premium-tier demand outside traditional IT procurement channels.
Industry Challenges
- 3D stacking thermomechanical expertise:Warpage control and die-to-die bonding precision require specialized process engineering talent that remains concentrated among incumbent TSV houses.
- Dual-use export classification navigation:US Bureau of Industry and Security licensing for advanced memory fabrication equipment is extending procurement timelines and complicating foundry partnership structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Memory Cube Market |
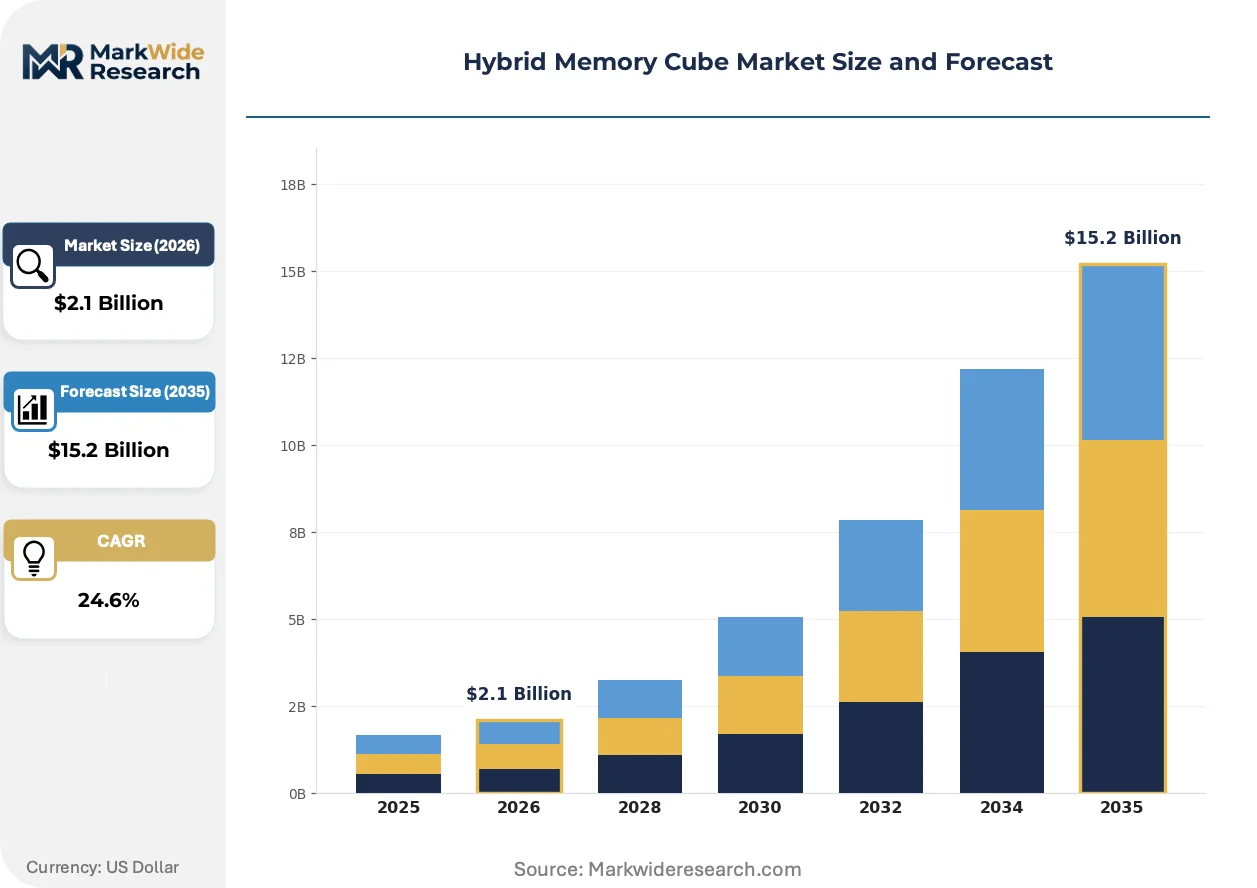
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $15.2 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash, Others Technology: 3D Stacking, TSV, On-Package Processing, Hybrid Bonding End User: High-Performance Computing, Data Centers, Consumer Electronics, Telecommunications Application: Gaming, AI Processing, Cloud Computing, Edge Computing |
| Companies Covered | Micron Technology, Samsung Electronics, SK Hynix, Intel Corporation, Advanced Micro Devices, Fujitsu, IBM Corporation, Rambus, Semtech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Memory Cube Market Strategic Shifts & Innovations
Memory architecture is bifurcating between bandwidth-optimized stacks for AI training and density-optimized configurations for inference, with TSV process innovation determining competitive position across both paths.
Hybrid bonding is absorbing the highest R&D intensity in advanced packaging as die-to-die interconnect pitch scaling enables thinner thermal profiles and higher stack heights. Cloud hyperscalers are qualifying hybrid-bonded HMC modules for next-generation training clusters, compressing the performance gap against monolithic alternatives. The technology is absorbing capital that previously flowed to interposer-based 2.5D integration, redirecting equipment vendor roadmaps toward direct bond assembly.
REACH substance restrictions are hardening material qualification requirements for semiconductor packaging sold in Europe, forcing reformulation of underfill and molding compounds. ECHA-regulated substance lists now cover critical thermal interface materials, extending supplier audit timelines by 6-12 months. Memory module vendors serving European AI hardware OEMs are responding by captive-sourcing compliant material streams and pre-certifying stack configurations.
Buyer concentration among cloud hyperscalers is compressing procurement cycles and unbundling traditional distributor relationships. Direct foundry-to-OEM contracts are displacing memory module distributors for volume HMC procurement, particularly in North American data center deployments. This pattern is most visible in training cluster buildouts where specification control and volume scale justify dedicated supply agreements over spot market purchasing.
Hybrid Memory Cube Market Segmentation
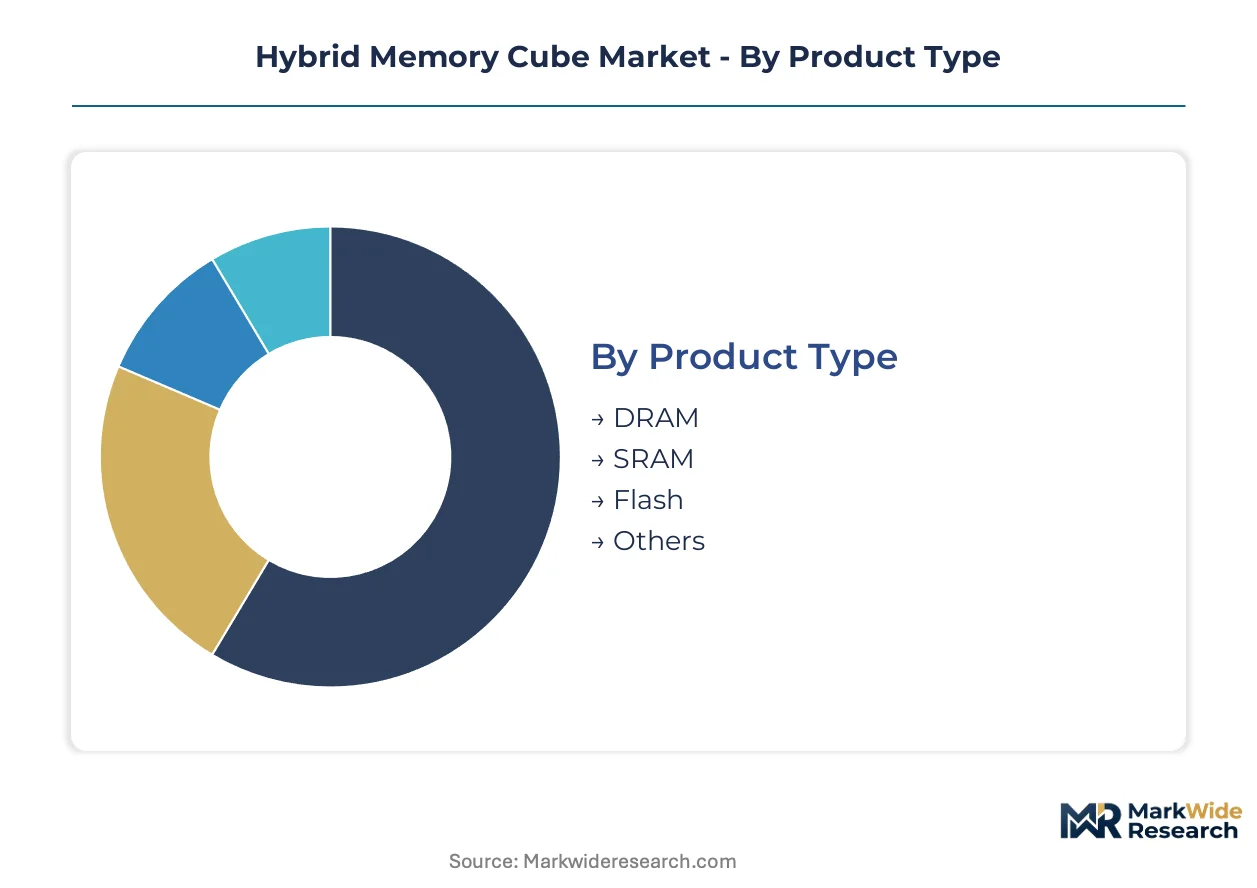
Hybrid Memory Cube procurement decisions hinge on bandwidth density requirements against thermal and cost constraints, forcing buyers to navigate trade-offs across memory cell architecture, vertical integration depth, and workload-specific latency profiles. The segmentation structure reflects how AI training clusters, cloud hyperscalers, and edge device OEMs prioritize different performance attributes when specifying memory subsystems.
Product Type:
Cost-per-bit economics and refresh power characteristics dominate buyer evaluation across memory cell technologies.
- DRAM:Charge-based volatile memory cells arranged in capacitor-transistor pairs deliver the highest bandwidth-per-watt for cache-intensive workloads. AI training clusters in South Korean and US data centers absorb the majority of high-stack DRAM modules as GPU memory bandwidth walls intensify.
- SRAM:Six-transistor cell structures eliminate refresh cycles and access latency for register-file and L3 cache applications. Aerospace and defense signal processing systems in the US and European markets specify radiation-hardened SRAM-based HMC stacks for deterministic latency requirements.
- Flash:Floating-gate non-volatile cells enable persistent memory tiers for checkpoint and recovery workloads.
- Others:Emerging memory technologies including MRAM and ReRAM occupy niche endurance-critical segments.
DRAM leads on scale; AI Processing applications drive the steepest expansion trajectory for SRAM in latency-sensitive defense systems.
Technology:
Vertical interconnect pitch and thermal management capabilities determine stack height limits and yield economics.
- 3D Stacking:Die-to-die vertical integration without intermediate substrates enables the thinnest form factors for mobile and edge deployments. Samsung Electronics and SK Hynix fabrication lines in South Korea concentrate capacity for 8+ die stacks serving AI inference accelerators.
- TSV:Through-silicon via etching and copper fill processes create electrical paths between stacked memory layers. Advanced via-etching equipment from Applied Materials, TEL, and EV Group anchors fabrication cost structures for high-bandwidth modules.
- On-Package Processing:Logic die integration at the base of memory stacks enables near-memory compute for reduced data movement.
- Hybrid Bonding:Direct oxide-to-oxide wafer bonding eliminates underfill materials and enables sub-10µm interconnect pitch.
TSV dominates current volume; Hybrid Bonding gains share fastest as cloud hyperscalers qualify next-generation training clusters.
End User:
Workload parallelism and power envelope constraints segment procurement specifications across compute environments.
- High-Performance Computing:Government and academic supercomputing facilities specify HMC modules for memory-bandwidth-bound simulation workloads. US Department of Energy exascale deployments and European EuroHPC systems in Finland and Italy drive qualification requirements for extreme-scale stacks.
- Data Centers:Cloud hyperscaler training clusters absorb the highest absolute volume of HMC modules. Microsoft, Google, and Amazon procurement specifications prioritize 320+ GB/s bandwidth with supply chain documentation for EU AI Act compliance.
- Consumer Electronics:Gaming consoles and high-end workstations represent a price-sensitive volume tier.
- Telecommunications:5G baseband processing and network function virtualization create deterministic latency requirements.
Data Centers command the largest revenue pool; High-Performance Computing shows the most rapid specification tightening for sovereign AI capacity.
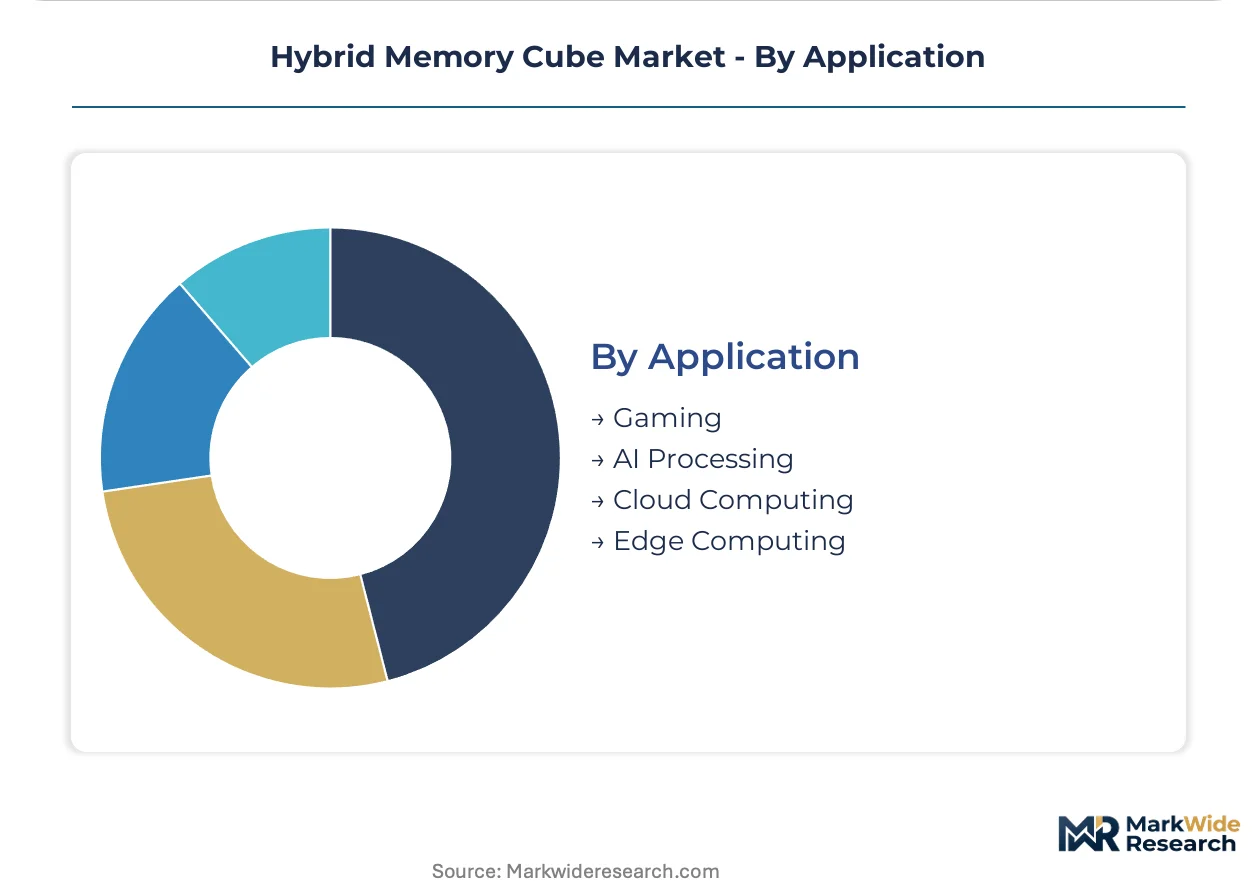
Application:
Model complexity and inference latency requirements differentiate memory architecture choices across workload types.
- AI Processing:Training workloads with trillion-parameter models saturate memory bandwidth before compute capacity. NVIDIA H100 and AMD MI300 clusters in US and Taiwanese foundry outputs specify HMC stacks as standard GPU memory companions.
- Cloud Computing:General-purpose virtualization and database workloads represent the most mature procurement segment. Established specifications and multi-source qualification reduce margin capture for differentiated HMC offerings.
- Gaming:Real-time rendering pipelines demand predictable frame latency over absolute bandwidth.
- Edge Computing:Autonomous vehicle and industrial vision systems require low-power cache density.
Cloud Computing anchors current revenue; Edge Computing climbs fastest as automotive OEMs qualify on-device inference stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSV process engineers and 3D stacking specialists cluster in South Korean fabrication corridors, with secondary concentrations in US semiconductor hubs and Japanese precision equipment zones. This talent geography shapes where high-bandwidth memory capacity scales fastest.
South Korea
AI training cluster buildouts by Naver and Kakao Enterprise absorb the majority of high-stack DRAM modules. The Ministry of Trade, Industry and Energy (MOTIE) channels national semiconductor R&D subsidies toward advanced packaging yield improvement. Samsung Electronics and SK Hynix anchor fabrication lines in Giheung and Icheon, where hybrid bonding pilot lines scale toward commercial volumes.
United States
Cloud hyperscaler procurement by Microsoft, Google, and Amazon drives qualification of next-generation HMC stacks for GPU companions. The Bureau of Industry and Security (BIS) export control classifications complicate TSV equipment sourcing timelines for domestic foundry partnerships. Boise, Idaho and Manassas, Virginia host captive DRAM fabrication networks serving defense-cleared and commercial AI hardware OEMs.
Japan
Precision equipment vendors supply advanced via-etching and bonding toolsets to global TSV fabrication lines. The Ministry of Economy, Trade and Industry (METI) coordinates semiconductor manufacturing base strengthening subsidies under the Semiconductor and Digital Industry Strategy. Tokyo and Osaka prefectures concentrate equipment vendor headquarters and process engineering talent pools for die-to-die interconnect scaling.
China
Domestic AI chip designers source HMC modules through foundry partnerships as indigenous TSV capacity scales. The Ministry of Industry and Information Technology (MIIT) governs semiconductor self-sufficiency targets under national technology independence frameworks. Yangtze Memory Technologies and ChangXin Memory Technologies anchor DRAM fabrication in Wuhan and Hefei, with packaging partners qualifying high-stack configurations for local server OEMs.
Germany
Industrial automation and automotive OEMs specify HMC buffers for edge AI inference in manufacturing vision systems. The Federal Motor Transport Authority (KBA) and EU AI Act compliance requirements cascade into memory subsystem documentation for AI-enabled automotive hardware. Dresden's Silicon Saxony cluster hosts wafer fabrication and advanced packaging R&D centers serving European data center and industrial equipment markets.
Hybrid Memory Cube Market Key Industry Players
The competitive structure tilts toward vertically integrated memory fabricators with captive TSV capacity. Market concentration remains high as yield optimization expertise and equipment access create barriers for new entrants. Two strategic archetypes dominate: IDM players with full-stack integration from DRAM cells to module assembly, and fabless designers partnering with foundry-based packaging houses. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure TSV toolset allocation and foundry slot commitments.
Among South Korea-based fabricators, Samsung Electronics and SK Hynix occupy positions as scale-driven archetypes with captive 3D stacking capacity. Micron Technology exemplifies the IDM-with-packaging-integration model, anchoring US-based DRAM fabrication with module assembly networks. These three companies represent the primary supply sources for cloud hyperscaler qualification programs and sovereign AI capacity buildouts across North American, European, and Asia-Pacific markets.
| Leading Market Players |
|---|
| Micron Technology |
| Samsung Electronics |
| SK Hynix |
| Intel Corporation |
| Advanced Micro Devices |
| Fujitsu |
| IBM Corporation |
| Rambus |
| Semtech Corporation |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in South Korea anchor DRAM wafer supply, translating state-coordinated R&D subsidies into disciplined capacity expansion that limits spot-market volatility and sustains premium pricing for AI-training-grade HMC stacks. This ownership pattern compresses margin pressure on fabless module assemblers while concentrating pricing power among integrated fabricators with captive TSV lines.
Pricing Analysis
Unbundled TSV processing services command substantial premiums over captive in-house fabrication, with contract foundries pricing die-stacking separately from DRAM wafer supply. Three-tier pricing structure across premium AI-training, standard cloud-computing, and economy edge-inference tiers separates modules by stack height and thermal grade. Cost compression in the economy tier is intensifying because automotive OEMs are qualifying domestic packaging houses in India and Vietnam. Cloud hyperscalers exhibit the least price sensitivity due to bandwidth-constrained workload economics, while industrial vision system integrators negotiate aggressively on per-module costs.
Supply Chain Analysis
Workforce-availability constraints in Giheung and Icheon fabrication corridors are tightening process engineering talent competition, forcing equipment vendors to extend installation timelines for advanced via-etching toolsets. Supply concentrates in South Korea, the United States, and Japan, with secondary packaging capacity scaling in Taiwan and Malaysia. The chain draws from high-purity copper feedstock, photoresist chemicals, and silicon interposer substrates. Single-source vulnerability in advanced bonding equipment from Applied Materials, TEL, and EV Group creates procurement risk for new entrants. Distribution runs through direct foundry-to-OEM contracts for cloud hyperscalers, with distributor channels serving mid-tier industrial and automotive buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korean fabrication dominance and emerging Indian assembly incentives, where PLI scheme subsidies compress landed costs for South Asian data center deployments against European REACH compliance burdens.
For Market Incumbents: Hedge TSV equipment concentration risk by qualifying secondary bonding tool vendors in Japan and diversifying hybrid bonding pilot lines across multiple South Korean sites. Samsung Electronics and SK Hynix should accelerate captive underfill compound sourcing to preempt REACH substance restriction disruptions in European AI hardware procurement.
For New Entrants and Emerging Players: Begin with automotive edge inference modules in Germany and Japan, where KBA documentation requirements and METI production subsidies create accessible qualification pathways. Target medical imaging buffer applications as the most penetrable segment, leveraging FDA 510(k) predicate device strategies to bypass full premarket review timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among fabless HMC designers with established foundry partnerships but no captive TSV capacity, as equipment access constraints discount their strategic optionality. Long-term viability hinges on hybrid bonding yield improvement trajectories over the projection horizon. Watch BIS export control classification expansions as the critical inflection signal for equipment sourcing risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Yield Ramp | Samsung Electronics and SK Hynix pilot lines in Giheung compress thermal profiles for cloud hyperscaler qualification. |
| REACH-Compliant Material Captive Sourcing | Micron Technology's in-house underfill formulation secures European AI Act documentation for training cluster sales. |
| India PLI Scheme Localization | Assembly and test capacity in South Asia serves Naver and Kakao Enterprise data center buildouts with reduced landed costs. |
| Dual-Use Export Control Navigation | US Bureau of Industry and Security licensing timelines reshape foundry partnership structures for advanced memory fabrication. |
| Medical Imaging Equipment Partnership | FDA-cleared diagnostic OEMs embed HMC buffers for real-time volumetric scan handling outside IT procurement channels. |
Research Approach
Coverage spans South Korea, the United States, Japan, Germany, and India, with primary inputs from each market's semiconductor fabrication and packaging ecosystem. Primary interviews with TSV process engineers, cloud hyperscaler procurement officers, automotive platform architects, medical device regulatory affairs leads, and advanced packaging equipment vendor sales directors combined with secondary validation from SEC 10-K filings, ECHA substance restriction updates, BIS export classification notices, and hyperscaler capex disclosure transcripts. Bottom-up module shipment estimates triangulated against top-down AI training cluster infrastructure spend projections.
Rate-of-change decomposition separates volume growth from price trajectory movements across the analysis window. Segmentation dimensions modeled include memory cell technology, vertical integration depth, stack height tier, end-use workload parallelism, and regional regulatory compliance cluster. CAGRs derived from installed base replacement cycles and AI training model complexity scaling assumptions. Industry-specific inputs encompass GPU memory bandwidth wall saturation points and TSV yield improvement curves from South Korean fabrication line disclosures.
Several conditions sit outside the modeled scope, including sudden BIS entity list expansions affecting equipment vendors, ECHA substance restriction list amendments with retroactive packaging compliance deadlines, and sovereign AI capacity buildout accelerations by national governments. Forecasts reflect assumptions about hybrid bonding commercialization timelines and cloud hyperscaler procurement specification stability. Material deviation in TSV equipment lead times or REACH compliance cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
DRAM Market
Memory Chips
China Flash Memory Market
Memory Chips
Digital RF Memory Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Memory Interface Chip Market
Memory Chips
DDR SDRAM Market
Memory Chips
Memory Chip Market
Memory Chips
Next Generation Memory Market
Memory Chips
Memory IC Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Automotive DRAM Market
Memory Chips
Static RAM Market
Memory Chips
Nano RAM Market
Memory Chips
GDDR6 Market
Memory Chips
Japan Flash Memory Market