
 Smartphone Memory Chip Market | 2026-2036
Smartphone Memory Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Memory Chip Market Insights
The EU Green Deal is shifting procurement criteria for smartphone memory suppliers serving European OEMs. Samsung Electronics leverages captive wafer capacity to anchor its vertical cost structure. SK Hynix competes aggressively in high-bandwidth memory stacks for premium handsets. Micron Technology navigates export licensing complexity while sustaining R&D intensity in advanced nodes.
Smartphone memory chips are non-volatile and volatile semiconductor storage devices fabricated through photolithographic processes on silicon wafers, with NAND Flash cells stacked in 3D architectures exceeding 200 layers to achieve terabit-scale densities in sub-square-centimeter footprints. Their primary commercial purpose is to enable persistent data retention, rapid application loading, and seamless multitasking in battery-constrained mobile devices. NAND Flash dominates unit volumes as the default storage medium across mid-range and flagship tiers, while DRAM margin pools concentrate in LPDDR5X configurations serving AI-accelerated camera and on-device inference workloads. Triple-Level Cell technology captures mainstream cost-optimized segments, whereas Single-Level Cell variants occupy enterprise-graded reliability niches with limited smartphone penetration.
REACH restrictions on hazardous substances in electronics and the EU AI Act's transparency mandates for on-device processing are tightening material disclosure and traceability requirements across memory supply chains. South Korea's METI-aligned industrial policy and China's SAMR antitrust reviews are reshaping capacity allocation and cross-border technology licensing. Stakeholders must monitor how geopolitical segmentation of semiconductor equipment access redraws competitive boundaries between integrated Korean producers and emerging Chinese memory ventures.
Market Dynamics
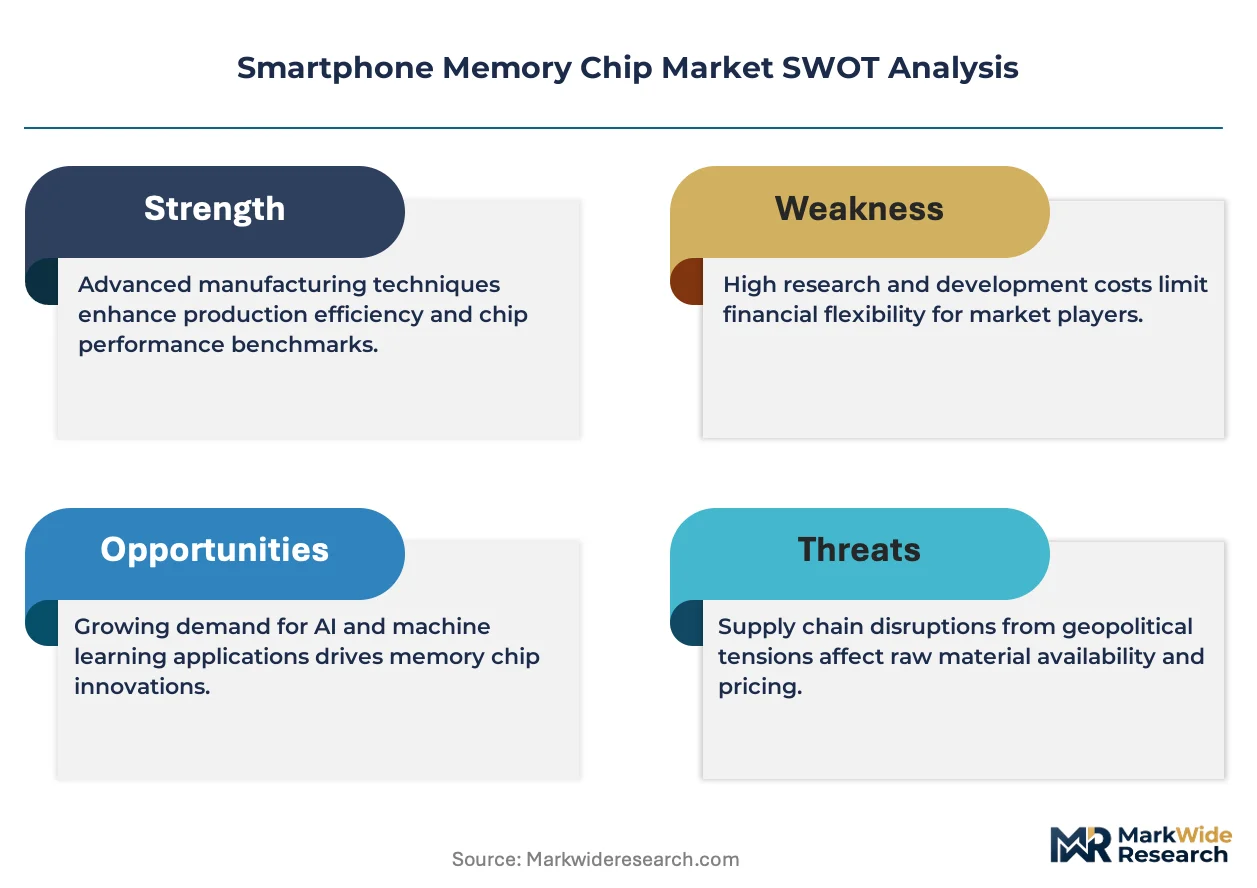
Memory chip architecture is compressing under the weight of on-device AI inference demands, forcing NAND and DRAM suppliers to recalibrate layer counts and bandwidth specifications simultaneously.
Growth Catalysts
- LPDDR5X DRAM proliferation:AI-accelerated camera pipelines and real-time inference workloads in flagship handsets are pulling high-bandwidth memory configurations into mainstream premium tiers.
- China's dual carbon goals:GB standards for fab energy efficiency are accelerating process node transitions that incidentally improve memory density per watt.
- South Korean cluster effects:Concentrated R&D spillovers between Samsung Electronics and SK Hynix are compressing development cycles for 3D NAND layer stacking.
Market Restraints
- Extreme ultraviolet lithography dependency:ASML equipment access bottlenecks constrain capacity expansion for advanced nodes regardless of capital availability.
- Pyongtaek-Suwon supply corridor concentration:Geological and geopolitical risks to this single geography threaten global DRAM buffer stock reliability.
- Triple-Level Cell endurance ceilings:QLC alternatives remain commercially uncompetitive for write-intensive mobile workloads, capping cost-down trajectories.
Strategic Opportunities
- India handset manufacturing:PLI scheme incentives for local assembly are creating captive demand for memory modules qualified under BIS certification pathways.
- Automotive-grade memory crossover:AEC-Q100 reliability standards developed for connected vehicles are migrating into ruggedized industrial handset segments.
- EU Green Deal procurement:Ecodesign requirements for circularity and carbon disclosure are favoring suppliers with verified Scope 3 data across European OEM supply bases.
Industry Challenges
- Atomic-scale process engineering talent:The finite pool of specialists capable of 200+ layer etch profile optimization is constraining foundry yield ramp timelines.
- Legacy LPDDR4 integration friction:Mid-range handset platforms maintaining backward compatibility face PCB routing complexity and power budget trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Memory Chip Market |
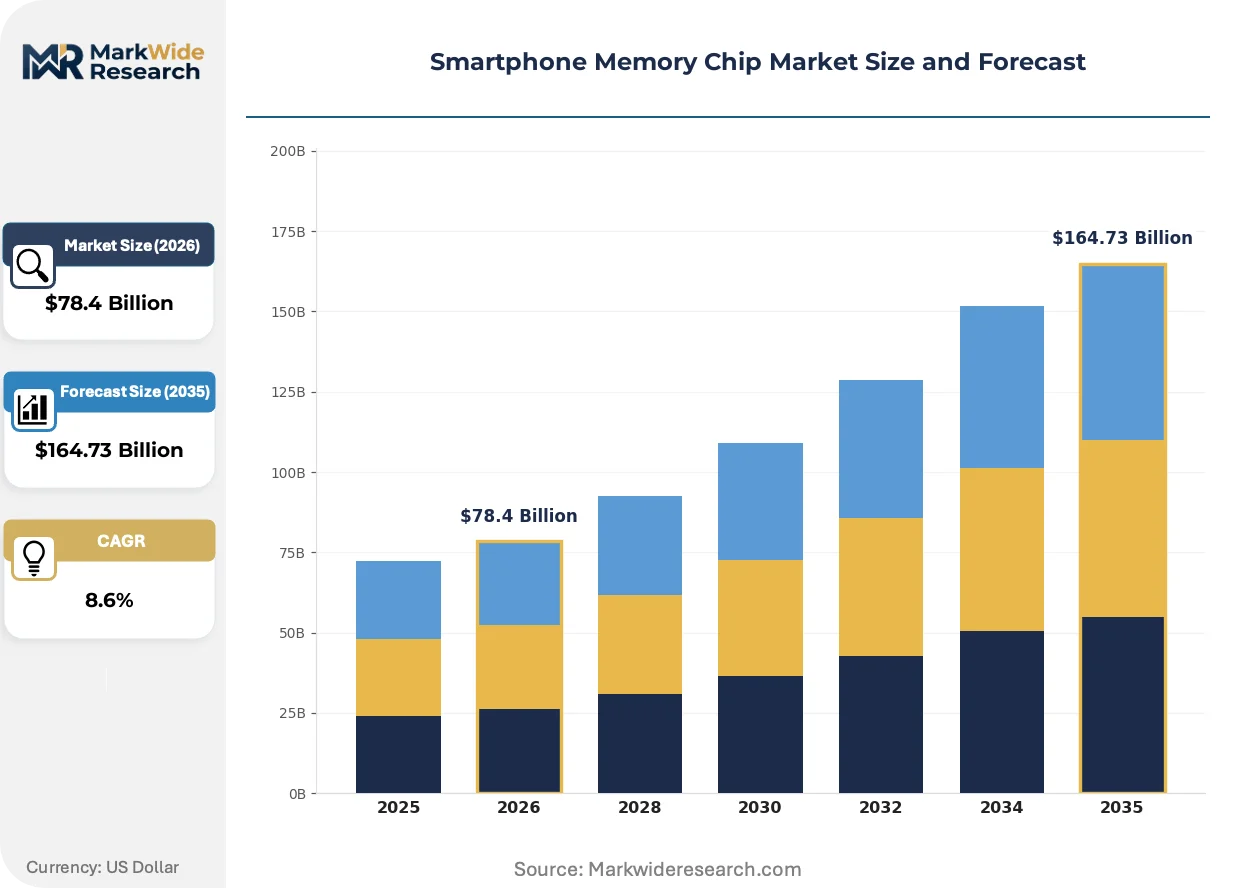
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, NAND Flash, eMMC Technology: 3D NAND, Single-Level Cell, Multi-Level Cell, Triple-Level Cell Capacity: 4GB, 8GB, 16GB, 32GB End User: OEMs, Aftermarket Providers, Mobile Device Manufacturers, Retail |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Kioxia Holdings Corporation, Western Digital Corporation, Winbond Electronics, Toshiba Memory, Intel Corporation, ADATA Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Memory Chip Market Trends and Innovations
Memory subsystem design is converging around unified memory architectures that collapse historical boundaries between storage and working memory, driven by AI workload homogenization across device tiers.
Hybrid bonding technology is unifying DRAM and NAND controller logic into vertically stacked packages. Flagship OEMs are qualifying these configurations for 2025 handset platforms. This integration is unifying the historical separation between storage and memory subsystems, compressing board area requirements while elevating thermal design complexity for device engineers.
REACH restrictions on hazardous substances are tightening material disclosure requirements for memory module substrates and encapsulants. ECHA substance candidate list updates are forcing reformulation of underfill materials and solder alloys. European OEM procurement teams are responding with supplier audit mandates that cascade through South Korean and Taiwanese packaging houses.
Direct-to-fab sourcing contracts are displacing traditional distribution channels for high-volume handset OEMs. Tier-one manufacturers are negotiating wafer-level agreements that bypass module assemblers. This pattern is most visible in South Korea, where Samsung Electronics and SK Hynix maintain captive packaging capacity that enables end-to-end margin capture for strategic accounts.
Smartphone Memory Chip Market Segmentation
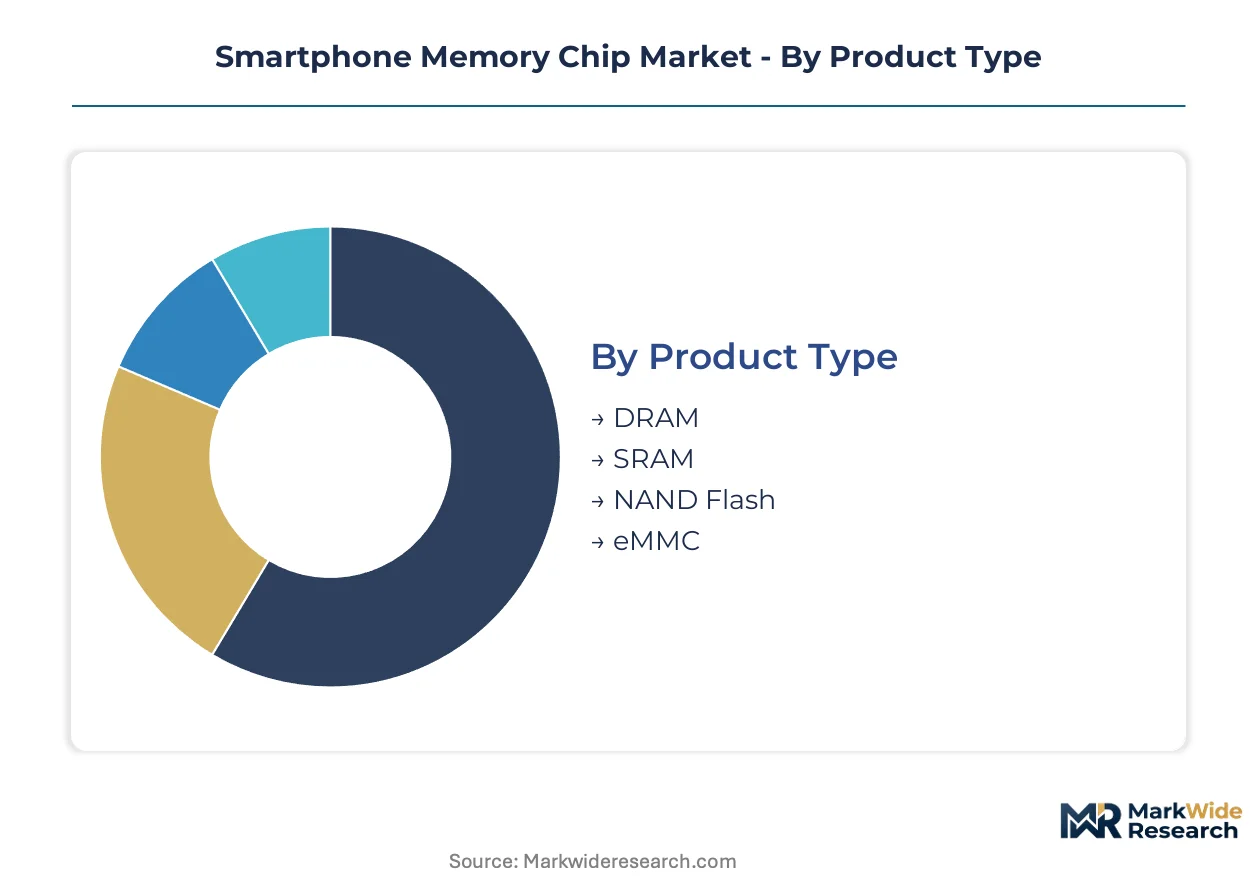
Smartphone memory chip segmentation reflects divergent certification burdens across product architectures. DRAM and NAND Flash carry distinct REACH material disclosure requirements, while capacity tiers trigger different BIS qualification pathways for India-bound modules.
Product Type:
DRAM modules require CE marking for European OEM integration, whereas NAND Flash faces additional ECHA substance scrutiny for encapsulant materials. SRAM and eMMC occupy lighter regulatory footprints but impose distinct procurement qualification protocols.
- DRAM:Volatile memory fabricated through stacked capacitor architectures delivers sub-100 nanosecond access latencies for active application execution. LPDDR5X configurations dominate AI-accelerated camera pipelines in Samsung Electronics and SK Hynix wafer supply agreements, constrained by extreme ultraviolet lithography equipment access bottlenecks.
- NAND Flash:Non-volatile storage employing charge-trap flash cells in 3D architectures exceeding 200 layers enables terabit-scale densities. Pyongtaek-Suwon corridor concentration threatens buffer stock reliability for write-intensive mobile workloads, compressing cost-down trajectories against Triple-Level Cell endurance ceilings.
- SRAM:Six-transistor cell arrays provide cache-level speed for processor-local data buffering with higher bit-cost than DRAM alternatives.
- eMMC:Embedded MultiMediaCard controllers integrate NAND Flash with management logic for mid-range handset platforms prioritizing PCB routing simplicity over peak bandwidth.
NAND Flash sits at the top of the volume ranking, with LPDDR5X DRAM climbing the fastest.
Technology:
Layer stacking density and cell-level bit encoding determine energy-efficiency compliance against China's GB standards for fab operations.
- 3D NAND:Vertical channel hole etching through 200+ alternating oxide-nitride pairs achieves terabit-per-square-centimeter densities. Samsung Electronics and SK Hynix concentrate R&D spillovers in South Korea's memory cluster, compressing development cycles for next-generation layer counts.
- Triple-Level Cell:Three-bit-per-cell encoding captures mainstream cost-optimized segments across mid-range smartphone tiers. Write endurance limitations cap penetration into enterprise-graded reliability niches, leaving Single-Level Cell variants to occupy premium industrial handset applications.
- Single-Level Cell:One-bit-per-cell configuration maximizes endurance cycles for automotive-grade memory crossover into ruggedized industrial segments.
- Multi-Level Cell:Two-bit-per-cell balance of density and longevity serves legacy platform compatibility requirements in volume handset markets.
Triple-Level Cell dominates unit economics, with 3D NAND gaining share fastest through layer-stacking advances.
Capacity:
Module density tiers align with handset OEM pricing stratification and AI workload memory footprints.
- 16GB:LPDDR5X configurations at this density threshold enable on-device inference for generative AI features in flagship tiers. EU AI Act transparency mandates for processing disclosure intensify procurement scrutiny of 16GB module traceability across European OEM supply bases.
- 32GB:Premium storage configurations differentiate ultra-flagship models with unified memory architectures collapsing historical boundaries between DRAM and NAND subsystems. Hybrid bonding technology integration elevates thermal design complexity for device engineers qualifying 2025 handset platforms.
- 8GB:Mid-range workhorse density faces legacy LPDDR4 integration friction through PCB routing complexity and power budget trade-offs.
- 4GB:Entry-tier density serves cost-constrained markets with direct-to-fab sourcing contracts displacing traditional distribution channels.
16GB modules sit at the top of the volume ranking, with 32GB climbing the fastest.
End User:
Procurement authority concentration determines contract structure and margin capture mechanics across the value chain.
- Mobile Device Manufacturers:Tier-one OEMs negotiate wafer-level agreements bypassing module assemblers through captive packaging capacity in South Korea. Samsung Electronics leverages this vertical cost structure to anchor strategic account relationships.
- OEMs:Original equipment manufacturers integrate qualified memory subsystems into finished handset designs with BIS certification requirements for India PLI scheme participation.
- Aftermarket Providers:Repair and upgrade channels face REACH restriction compliance for hazardous substance documentation in module substrates and solder alloys.
- Retail:Consumer-direct channels carry lighter regulatory burdens but impose inventory velocity requirements incompatible with advanced node allocation constraints.
Mobile Device Manufacturers sit at the top of the volume ranking, with OEMs climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers specializing in 200+ layer etch optimization concentrate in South Korea's Pyongtaek-Suwon corridor, anchoring the industry's most advanced captive production networks. Equipment physicists fluent in extreme ultraviolet lithography cluster in Dutch and German research hubs feeding Asian fabs. Materials scientists developing low-carbon encapsulants populate European polymer institutes responding to REACH reformulation mandates.
South Korea
AI-accelerated camera pipelines in Samsung Electronics and SK Hynix flagship supply agreements pull LPDDR5X DRAM into premium tiers. METI-aligned industrial policy channels R&D subsidies toward 3D NAND layer stacking advances. The Pyongtaek-Suwon corridor compresses development cycles through concentrated spillovers between captive wafer and packaging facilities.
China
Domestic handset OEMs expanding storage configurations drive captive demand for locally qualified memory modules. GB standards for fab energy efficiency accelerate process node transitions under dual carbon goals enforcement. Yangtze Memory Technologies anchors emerging 3D NAND ventures in Wuhan's optoelectronics cluster despite equipment access constraints.
United States
FCC certification requirements for RF-integrated memory subsystems shape qualification protocols for India-bound handset platforms. EPA hazardous substance tracking intersects with REACH-aligned material disclosure demands from European OEM procurement teams. Idaho and California host Micron Technology's advanced node R&D operations navigating export licensing complexity.
Japan
Kioxia Holdings maintains charge-trap flash expertise developed through Toshiba Memory heritage in Yokohama and Kitakami. JIS standards for semiconductor reliability intersect with automotive-grade memory crossover opportunities. METI technology roadmaps coordinate materials science consortia advancing hybrid bonding interconnects for 2025 handset platforms.
Germany
European OEM procurement teams enforce Ecodesign circularity mandates through supplier audit cascades reaching South Korean packaging houses. KBA automotive reliability standards migrate into ruggedized industrial handset segments requiring AEC-Q100 qualified memory. Dresden's silicon cluster hosts equipment calibration labs supporting ASML lithography deployment across EMEA fabs.
Smartphone Memory Chip Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin capture models. The market consolidates around three strategic archetypes: integrated Korean conglomerates with captive wafer-to-module pipelines, US-based technology licensors navigating geopolitical equipment constraints, and Taiwanese packaging specialists qualifying hybrid bonding configurations. Competitive moves center on direct-to-fab sourcing contract negotiation and backward integration into substrate materials.
Within the integrated producer tier, Samsung Electronics and SK Hynix exemplify the captive capacity archetype through end-to-end Pyongtaek-Suwon corridor operations. Micron Technology occupies a position bridging US-based R&D intensity with Asian manufacturing partnerships. These three anchors represent divergent responses to extreme ultraviolet lithography equipment access bottlenecks reshaping competitive boundaries.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Kioxia Holdings Corporation |
| Western Digital Corporation |
| Winbond Electronics |
| Toshiba Memory |
| Intel Corporation |
| ADATA Technology |
| Others |
Pricing and Supply Chain Analysis
Extreme ultraviolet lithography equipment depreciation flows through wafer cost structures into module pricing tiers, with Samsung Electronics and SK Hynix leveraging captive Pyongtaek-Suwon corridor capacity to compress cost-down trajectories for strategic accounts while independent packaging houses absorb margin pressure from direct-to-fab sourcing displacement.
Pricing Analysis
Wafer-level agreements versus module-level procurement splits the market into bundled captive supply and unbundled merchant purchasing. Three-tier pricing structure across premium LPDDR5X, standard LPDDR4X, and economy LPDDR4 tiers reflects EU AI Act traceability certification burdens and BIS qualification pathway costs. Cost compression in mid-range densities intensifies because legacy platform compatibility requirements sustain demand for older nodes with depreciated equipment. Mid-range handset OEMs exhibit highest price sensitivity, while flagship manufacturers prioritize bandwidth specifications over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European and Indian handset OEMs require qualification of secondary suppliers beyond Samsung Electronics and SK Hynix, compressing procurement timelines. Silicon wafers draw from Japanese and German substrate specialists, while ASML lithography systems and KLA process control equipment anchor equipment dependencies. Single-source vulnerability concentrates in the Pyongtaek-Suwon corridor's geological and geopolitical exposure. Distribution runs through direct-to-fab contracts displacing traditional module assembler channels for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's on-device processing transparency mandates compound procurement complexity for memory suppliers, transforming regulatory compliance into a demand driver for qualified module traceability across European OEM supply bases.
For Market Incumbents: Anchor strategic positioning through backward integration into substrate materials and encapsulant formulations responding to REACH restriction updates. Defend against emerging Chinese memory ventures by accelerating hybrid bonding technology qualification timelines for 2025 handset platforms. Prioritize captive packaging capacity expansion in South Korea's memory cluster to maintain end-to-end margin capture against direct-to-fab pricing pressure.
For New Entrants and Emerging Players: India's PLI scheme for local handset assembly opens a window for BIS-certified memory module qualification pathways serving domestic OEMs. Target mid-range density tiers where legacy LPDDR4 integration friction sustains demand for qualified second-source suppliers. Pursue automotive-grade memory crossover opportunities as AEC-Q100 reliability standards migrate into ruggedized industrial handset segments with lighter incumbent concentration.
For Investors and Strategic Acquirers: Roll-up economics work for specialized packaging houses because hybrid bonding technology integration elevates thermal design complexity beyond captive foundry capabilities. Focus acquisition screening on substrate material specialists with verified Scope 3 carbon disclosure data qualifying for EU Green Deal procurement. Watch ASML equipment access licensing decisions as the inflection indicator redrawing competitive boundaries between integrated Korean producers and equipment-constrained emerging ventures.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Qualification | Enables unified memory architectures collapsing DRAM-NAND subsystem boundaries for 2025 flagship platforms. |
| Direct-to-Fab Sourcing Contract Negotiation | Bypasses module assemblers to capture wafer-to-module margins for high-volume handset OEM accounts. |
| REACH-Compliant Material Reformulation | Addresses ECHA substance candidate list updates for encapsulants and solder alloys in European supply chains. |
| BIS Certification Pathway Investment | Qualifies memory modules for India's PLI scheme incentives driving local handset assembly demand. |
| Automotive-Grade Memory Crossover Development | Migrates AEC-Q100 reliability standards into ruggedized industrial handset segments requiring extended temperature operation. |
Research Methodology
Multiple input streams — semiconductor equipment supplier disclosures, handset OEM procurement director interviews, and foundry utilization datasets — were reconciled against trade flow records and regulatory filing repositories. Primary discussions with memory subsystem architects, fab operations managers, and European OEM supply chain directors informed capacity allocation assumptions. Secondary validation drew from SEC 10-K equipment capex disclosures, South Korean METI industrial production indices, and ECHA substance registration databases. Bottom-up wafer supply modeling and top-down handset shipment forecasts were cross-referenced for triangulation.
Historical capacity expansion patterns were cross-referenced against panel input from process engineers and packaging specialists to construct the projection framework. Segmentation dimensions modeled include memory architecture type, layer stacking density tier, cell-level bit encoding technology, module capacity configuration, and end-user procurement authority structure. CAGRs were derived from supply-demand balance equations incorporating equipment lead time constraints and node transition timelines. Forecast inputs included EUV lithography equipment delivery schedules and GB standards compliance transition curves for Chinese fab operations.
Revisions become necessary when ASML equipment access restrictions tighten, REACH substance candidate list updates expand, or geological disruptions threaten Pyongtaek-Suwon corridor operations. Forecasts reflect assumptions regarding process node transition pacing and dual-sourcing qualification timelines. Deviation in extreme ultraviolet lithography equipment licensing decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
DRAM Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Nano RAM Market
Memory Chips
Memory Module Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Mobile DRAM Market
Memory Chips
Memory Chip Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
In-Memory Grid Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market