
 DDR SDRAM Market | 2026-2036
DDR SDRAM Market Size, Share, and Industry Trends Forecast 2026-2036
DDR SDRAM Market Intelligence
The transition to the DDR5 standard is reorganizing the competitive landscape for high-performance memory modules. Samsung Electronics leverages its immense manufacturing scale to lead this technological shift. Micron Technology differentiates with its focus on memory solutions for data centers and automotive applications. SK Hynix competes through significant R&D investments in next-generation memory architectures, including High Bandwidth Memory.
Double Data Rate Synchronous Dynamic Random-Access Memory (DDR SDRAM) is a class of memory integrated circuits used in computing. It achieves high bandwidth by transferring data on both the rising and falling edges of the clock signal. While the DDR4 type still constitutes a large portion of the market, DDR5 represents the fastest-growing segment due to new server and workstation deployments. Demand from data centers and cloud service providers as end users is eclipsing traditional desktop computer applications in market value.
Compliance with environmental regulations like the EU's RoHS directive and China's GB standards for electronics is mandatory for market access. These standards govern the use of hazardous substances in manufacturing, influencing material sourcing and supply chain management. Vendor success will hinge on navigating the complex power-performance trade-offs inherent in next-generation memory controller and module designs.

Market Dynamics
The central dynamic shaping the DDR SDRAM market is the technological transition toward the DDR5 standard. This shift, driven by the intense bandwidth and efficiency demands of hyperscale data centers and artificial intelligence workloads, is creating a clear performance and value divide across the memory landscape.
Growth Catalysts
- DDR5 Adoption in Data Centers:The rollout of new server platforms supporting the DDR5 standard is a primary catalyst, as hyperscale cloud providers upgrade infrastructure to handle escalating data processing and AI training requirements.
- Advanced Computing Workloads:The proliferation of artificial intelligence, machine learning, and high-performance computing applications necessitates memory with higher bandwidth and density, directly fueling demand for next-generation DDR SDRAM.
- Edge Computing Expansion:Growth in edge computing deployments for applications like autonomous vehicles and industrial IoT creates new demand for high-reliability and low-latency memory modules outside of traditional centralized data centers.
Market Restraints
- High Capital Intensity:Manufacturing advanced DDR SDRAM requires enormous capital investment in semiconductor fabrication plants (fabs) and cutting-edge lithography equipment, creating high barriers to entry and concentrating supply.
- Power and Thermal Constraints:Increasing memory speeds and densities create significant challenges related to power consumption and heat dissipation, particularly in densely packed server racks, which can limit performance and increase operating costs.
- Supply Chain Concentration:The market's reliance on a small number of dominant manufacturers for DRAM chips creates vulnerability to supply disruptions, geopolitical tensions, and price volatility, posing a risk to system builders and end users.
Strategic Opportunities
- Automotive Applications:The growing complexity of in-vehicle infotainment (IVI) systems and Advanced Driver-Assistance Systems (ADAS) presents a significant opportunity for specialized, high-reliability automotive-grade DDR memory.
- Compute Express Link (CXL) Integration:The emergence of the CXL standard allows for new, more flexible system architectures where memory can be pooled and shared, creating opportunities for innovative memory module designs that go beyond traditional DIMMs.
- Data Localization Mandates:Regulations requiring in-country data storage, such as those being implemented in India and Brazil, are spurring the construction of new regional data centers, creating geographically targeted demand for server memory.
Industry Challenges
- Regulatory Compliance Burden:Adherence to a complex patchwork of global environmental regulations, including the EU's RoHS directive and China's GB standards, requires constant monitoring and investment in compliant material sourcing and manufacturing processes.
- Interoperability with Legacy Systems:Integrating newer DDR5 modules with existing server infrastructure built around the DDR4 standard poses significant technical challenges, requiring extensive validation to ensure system stability and performance.
- Signal Integrity Engineering Talent:A shortage of engineers with specialized skills in high-speed digital design and signal integrity analysis can constrain the ability of companies to develop and validate next-generation memory controllers and modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DDR SDRAM Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $220.97 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: DDR, DDR2, DDR3, DDR4, DDR5 Technology: Synchronous DRAM, Double Data Rate, Low Power DDR, Graphics DDR, Registered DIMM, Unbuffered DIMM Application: Desktop Computers, Laptop Systems, Servers, Gaming Consoles, Network Equipment, Workstations End User: Original Equipment Manufacturers, Data Centers, Cloud Service Providers, Telecom Operators, System Integrators, Consumer Electronics |
| Companies Covered | Kingston Technology Company, PATRIOT MEMORY, Samsung Electronics, Intelligent Memory Limited, Alliance Memory, SK Hynix, Crucial, Analog Devices, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DDR SDRAM Market Strategic Shifts & Innovations
Specialization of memory architectures is defining the market's evolution. Instead of a one-size-fits-all approach, memory solutions are increasingly tailored to specific workloads, from high-capacity server modules to ultra-high-bandwidth packages for AI accelerators, creating distinct performance tiers.
High Bandwidth Memory (HBM) vertically stacks DRAM dies to deliver exceptional data throughput within a compact physical footprint. High-performance computing (HPC) clusters and systems for AI training are the primary adopters of this technology. The rise of HBM for these specialized, performance-critical tasks is fragmenting the market, creating a premium tier that is architecturally distinct from the commodity DDR SDRAM used in mainstream servers.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide detailed disclosures on environmental impacts. This regulation forces companies to track and report the carbon footprint and water usage across their entire value chain, from silicon wafer production to final assembly. Suppliers serving the European enterprise market are most affected, pushing them to invest in greener manufacturing and more transparent supply chain reporting.
Enterprise buyers are shifting their purchasing behavior to favor memory that is pre-validated and certified for specific server platforms from major OEMs. This trend reduces the significance of the component spot market for corporate customers, who now prioritize system stability and vendor support over unit cost. The shift is most visible in regulated industries like finance and healthcare, where reliability and long-term support are non-negotiable requirements.
DDR SDRAM Market Segmentation

The DDR SDRAM market structure reflects the diverse performance and power requirements across computing environments. Different memory types and technologies serve distinct end-user applications, influencing design choices and procurement strategies. Understanding these segments clarifies the competitive dynamics and future growth trajectories within the industry.
Type:
Regulatory compliance with directives like the EU's RoHS and China's GB standards significantly influences the materials and manufacturing processes for each DDR type. This differentiation ensures global market access for compliant memory modules.
- DDR5:This advanced memory standard offers higher bandwidth and improved power efficiency compared to its predecessors. Demand concentrates in hyperscale data centers and new server platforms for AI and machine learning workloads.
- DDR4:Still constituting a substantial portion of the market, DDR4 provides a balance of cost-effectiveness and performance for many mainstream applications. Its continued presence supports a wide range of existing server and desktop infrastructure.
- DDR:The original Double Data Rate memory, DDR is largely phased out in new systems.
- DDR2:An older generation, DDR2 memory is primarily found in legacy systems requiring basic functionality.
- DDR3:This type offers a performance upgrade over DDR2 and remains relevant for older enterprise and consumer computing platforms.
Established volume favors DDR4; emerging adoption for high-performance computing favors DDR5.
Technology:
The cost tiering across memory technologies dictates their suitability for various applications, balancing performance against manufacturing complexity and price points.
- Double Data Rate:This fundamental technology allows data transfer on both the rising and falling edges of the clock signal, enhancing bandwidth. It forms the basis for all modern DDR SDRAM types, critical for general computing.
- Registered DIMM:Featuring a register chip that buffers control and address signals, Registered DIMMs improve signal integrity and allow for higher memory capacities. Demand concentrates in enterprise servers and workstations that require stability and scalability.
- Synchronous DRAM:The foundational memory type that synchronizes operations with the system clock for improved performance.
- Low Power DDR:Designed for mobile devices and embedded systems, Low Power DDR prioritizes energy efficiency.
- Graphics DDR:Optimized for high-speed data transfer in graphics processing units, Graphics DDR is essential for gaming and professional visualization.
- Unbuffered DIMM:Directly connects to the memory controller without a buffer, offering lower latency for consumer desktops and laptops.
Performance requirements dictate the choice between Registered DIMM for high throughput and Unbuffered DIMM for general computing.
Application:
Specific application demands drive the design and performance characteristics of DDR SDRAM, tailoring memory solutions to diverse operational environments.
- Servers:These systems require high-capacity, high-bandwidth, and reliable memory modules to handle intensive data processing and virtualization. Hyperscale data centers and cloud service providers are the primary end users.
- Workstations:Used for demanding professional tasks like CAD, video editing, and scientific simulations, workstations need robust memory with error correction capabilities. Engineering and creative industries rely on these configurations.
- Desktop Computers:Standard DDR SDRAM modules support general-purpose computing and multitasking for personal use.
- Laptop Systems:Compact and energy-efficient memory solutions are crucial for portable computing devices.
- Gaming Consoles:High-speed memory is integrated into gaming consoles to render complex graphics and facilitate smooth gameplay.
- Network Equipment:Routers, switches, and other network devices use specialized memory for packet buffering and data forwarding.
High-performance computing drives demand for Servers, while consumer devices rely on Desktop Computers and Laptop Systems.
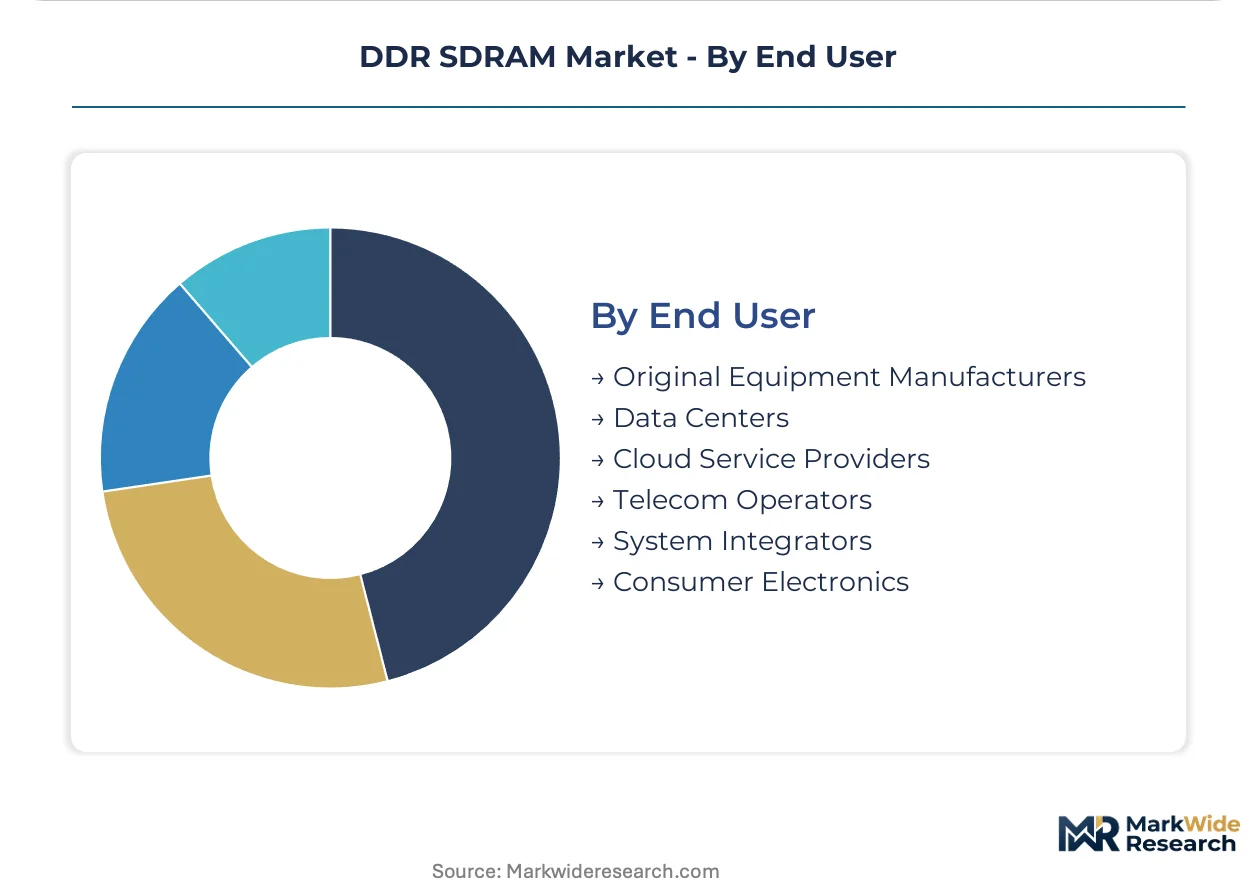
End User:
Volume purchasing by key end users shapes the competitive landscape, influencing pricing and product development priorities across the DDR SDRAM market.
- Data Centers:These facilities demand vast quantities of high-performance, high-density DDR SDRAM to support their compute and storage infrastructure. The transition to DDR5 is particularly pronounced in this segment.
- Cloud Service Providers:Operating at hyperscale, cloud providers require efficient and scalable memory solutions for their global networks of servers. Their infrastructure upgrades significantly impact market demand.
- Original Equipment Manufacturers:OEMs integrate DDR SDRAM into a wide array of computing and electronic devices for various markets.
- Telecom Operators:Telecommunications infrastructure, including 5G base stations, utilizes specialized memory for network functions and data processing.
- System Integrators:These firms assemble custom computing solutions for businesses, incorporating DDR SDRAM based on client specifications.
- Consumer Electronics:Devices like smart TVs, set-top boxes, and embedded systems use DDR SDRAM for operational memory.
Infrastructure expansion by Data Centers and Cloud Service Providers accounts for the largest market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DDR SDRAM market exhibits varying demand elasticity across geographies. While some regions prioritize cost-effectiveness for mainstream applications, others focus on high-performance, next-generation memory for advanced computing. This differentiation influences procurement strategies and technological adoption rates globally.
United States
The United States drives demand through hyperscale data centers, advanced AI workloads, and expanding edge computing deployments. The CHIPS and Science Act provides incentives for domestic semiconductor manufacturing, including memory production. Silicon Valley in California sees continuous innovation in memory integration for AI accelerators and server platforms.
China
Demand drivers include extensive data center expansion, cloud services, and domestic AI development across China. China's GB standards for electronics mandate material compliance, impacting DDR SDRAM component sourcing. Shenzhen serves as a manufacturing and innovation hub, driving new memory module designs for its vast electronics ecosystem.
South Korea
Global leadership in memory chip manufacturing, advanced computing infrastructure, and 5G deployment are key demand drivers in South Korea. Government initiatives support R&D in next-generation memory architectures, aligning with national industrial policies. The Gyeonggi Province, surrounding Seoul, hosts major memory producers and research institutes, advancing HBM and DDR5 technologies.
Germany
Automotive electronics, industrial IoT, and specialized high-performance computing (HPC) for research drive demand in Germany. Compliance with the EU's RoHS directive is critical for market access, influencing material selection for DDR modules. Munich, a hub for automotive and industrial technology, integrates advanced DDR memory into sophisticated embedded systems.
Japan
Supercomputing, industrial automation, and expanding data storage needs for local enterprises are significant demand drivers in Japan. METI promotes advanced materials research and semiconductor manufacturing capabilities to secure critical supply chains. Tokyo's technology sector drives demand for high-reliability memory solutions in enterprise servers and specialized computing.
DDR SDRAM Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the DDR SDRAM market. The industry structure is highly concentrated at the DRAM chip manufacturing level, with significant vertical integration among the largest players. Strategic archetypes include integrated device manufacturers, specialized memory module assemblers, and niche solution providers. Dominant competitive moves involve continuous R&D investment in next-generation standards and strategic partnerships for platform validation.
At the scale-driven end, Samsung Electronics and SK Hynix represent the integrated device manufacturers that dominate DRAM chip production. These South Korean-based companies leverage immense capital investment and advanced fabrication capabilities to supply global demand. Micron Technology, a US-based entity, also occupies a significant position among the primary chip producers, specializing in memory solutions for data centers and automotive applications. These firms establish the foundational supply for memory modules across various computing segments. Their extensive portfolios and manufacturing prowess underpin the market's technological progression.
| Leading Market Players |
|---|
| Kingston Technology Company |
| PATRIOT MEMORY |
| Samsung Electronics |
| Intelligent Memory Limited |
| Alliance Memory |
| SK Hynix |
| Crucial |
| Analog Devices |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
EU's RoHS directive and China's GB standards gate DDR SDRAM market access, influencing material sourcing and supply chain qualification. This regulatory compliance drives price differentiation for modules meeting stringent environmental and safety criteria.
Pricing Analysis
After-sales support and long-term service contracts drive significant lifetime value for DDR SDRAM modules. The dominant pricing structure for enterprise buyers is shifting towards contract-based long-term agreements, prioritizing value over unit cost. Price differentiation stems from performance tiering (DDR5 versus DDR4) and OEM pre-validation for specific server platforms. Pricing softness can occur in the legacy DDR4 segment due to commoditization. Traditional desktop and laptop consumers remain the most price-sensitive segment.
Supply Chain Analysis
Strategic stockpiling of critical components is preferred by major system builders to mitigate supply disruptions. Supply concentration centers primarily in South Korea and the United States, where dominant manufacturers produce core DRAM chips. The industry depends on a steady supply of silicon wafers and specialized chemicals for advanced fabrication. Single-source vulnerability for cutting-edge lithography equipment poses a structural supply chain risk. Distribution runs through direct sales to hyperscale data centers and OEMs, alongside system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DDR SDRAM market presents a significant service-attach opportunity, with long-term validation and support contracts expanding faster than raw hardware sales. Enterprise buyers prioritize system stability and vendor support, creating recurring revenue streams.
For Market Incumbents:Compound investments in next-generation memory architectures, particularly DDR5 and HBM, to maintain technological leadership against emerging memory standards like CXL. Leverage immense manufacturing scale to drive cost efficiencies and secure long-term supply agreements with hyperscale cloud providers. Deepen vertical integration into memory controller and module design to mitigate signal integrity engineering talent shortages. Strategic partnerships for platform validation will defend market share against specialized niche providers.
For New Entrants and Emerging Players:Automotive-grade memory certification fast-tracks offer new entrants a path to penetrate specialized, high-reliability markets. Target the underpenetrated edge computing segment with low-latency, energy-efficient modules for industrial IoT and autonomous vehicles. Develop innovative CXL-enabled memory module designs to address flexible system architectures. Focus on delivering custom, pre-validated solutions for niche applications to differentiate from volume manufacturers.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized memory module assemblers and niche solution providers focusing on high-reliability or CXL-enabled designs. The market exhibits long-term viability, driven by the indispensable role of memory in AI and data center infrastructure for the next decade. Acquisition targets include firms with strong intellectual property in next-generation memory controllers or advanced packaging. The signal to watch is the accelerated commercial deployment of CXL-enabled platforms across hyperscale data centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Next-Generation Memory R&D | Drives performance leadership in DDR5 and High Bandwidth Memory for AI and data center workloads. |
| Expand Semiconductor Fabrication Capacity | Secures long-term supply for escalating global demand and reduces reliance on external foundries. |
| Form OEM Platform Validation Partnerships | Ensures compatibility and performance for critical server and workstation deployments, building buyer trust. |
| Develop Specialized Automotive Memory | Captures new demand from autonomous vehicles and advanced driver-assistance systems requiring high reliability. |
| Diversify Material Sourcing Channels | Mitigates geopolitical risks and regulatory compliance burdens in the complex global supply chain. |
Research Approach
Desk research of SEC 10-K filings, industry association reports, and hyperscaler capex disclosures preceded structured interviews with CTOs, memory module design engineers, and OEM supply chain managers. This primary and secondary research was triangulated through both bottom-up market sizing and top-down validation. The approach ensured robust data collection and cross-verification from diverse industry perspectives.
Variance decomposition determined the influence of key drivers and restraints across the analysis window. Segmentation dimensions modeled included DDR type, memory technology, application, and end-user segments, alongside memory controller architecture advancements. Compound Annual Growth Rates were derived from historical trends and projected future demand from AI workloads. Key forecast inputs included semiconductor fabrication capacity utilization rates and data center expansion plans.
Decision-makers should treat outputs as directional under assumptions of stable geopolitical conditions and consistent technological progression in silicon manufacturing; material deviation would warrant model refresh. Forecasts acknowledge potential disruptions from supply chain concentration or rapid shifts in memory controller design. Revision becomes warranted when major geopolitical events or new memory standards significantly alter market dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Japan Flash Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Nano RAM Market
Memory Chips
Memory Market
Memory Chips
Memristor Market
Memory Chips
ECC Memory Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
China Flash Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Digital RF Memory Market
Memory Chips
Ferroelectric RAM Market