
 Global Heterogeneous Mobile Processing and Computing Market | 2026-2036
Global Heterogeneous Mobile Processing and Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heterogeneous Mobile Processing and Computing Market Intelligence
Software-defined features accessible via firmware updates and subscription models are recalibrating the value proposition beyond initial hardware sales. Qualcomm Inc. leverages its extensive patent portfolio in mobile connectivity to integrate diverse processing units into its chipsets. Apple Inc. differentiates through its tightly controlled hardware and software ecosystem, optimizing performance for its proprietary devices. Meanwhile, Nvidia Corporation extends its expertise from high-performance computing into the mobile edge computing space, targeting advanced AI workloads.
Heterogeneous mobile processing and computing refers to systems that integrate multiple types of specialized processors, such as CPUs, GPUs, and NPUs, onto a single chip or package. This architecture allows tasks to be assigned to the most efficient core, optimizing for performance and power consumption in battery-powered devices. System on Chip (SoC) solutions represent the dominant integration level, driven by the manufacturing scale of smartphones and tablets. Within use cases, machine learning and augmented reality applications are creating demand for specialized Neural Processing Units (NPUs) and high-throughput GPUs.
Competition and interoperability standards from the US Federal Trade Commission (FTC) and the European Commission influence platform dynamics and market access. Additionally, China's Ministry of Industry and Information Technology (MIIT) sets technical requirements and network access licenses for devices sold within its borders. Navigating these divergent regulatory landscapes while managing the increasing complexity of SoC design will be a central challenge for all ecosystem participants.
Market Dynamics
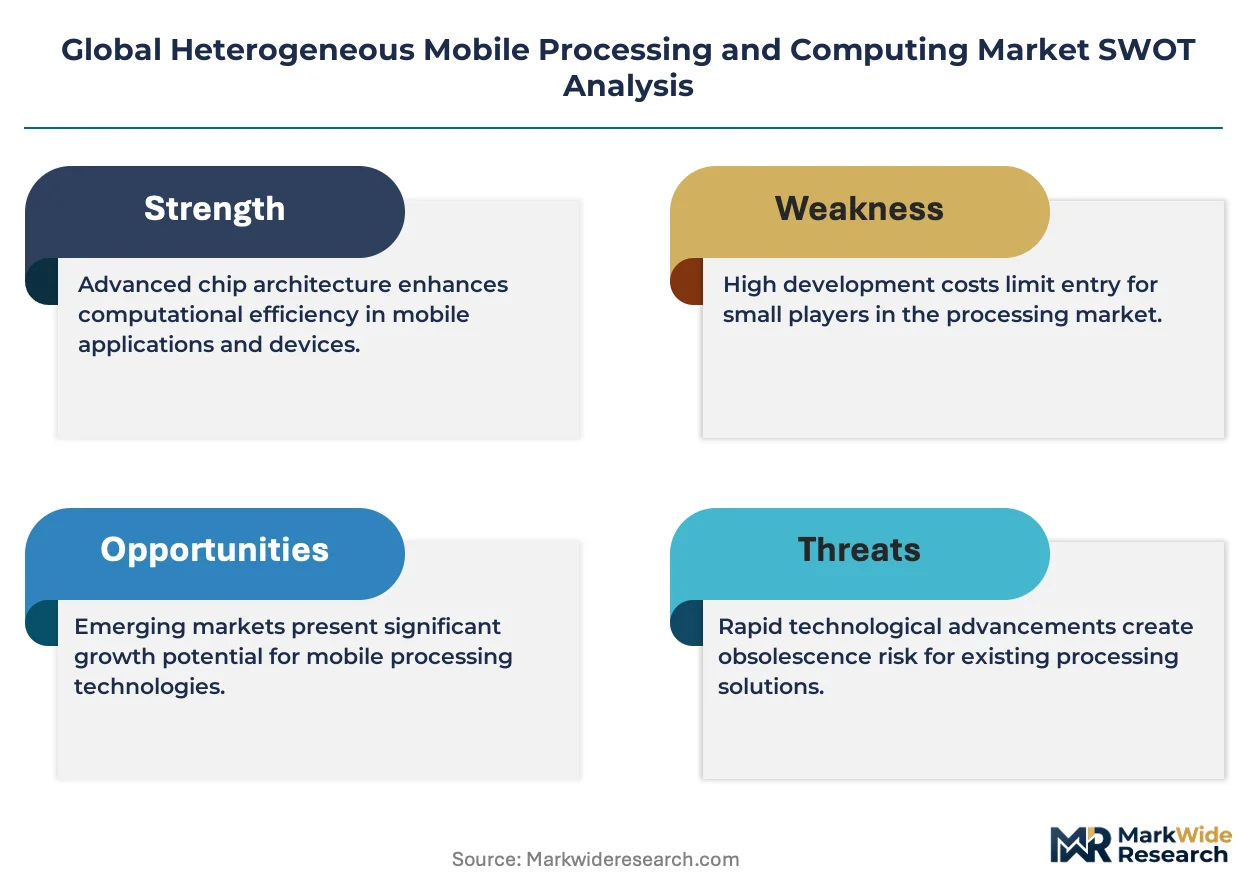
The central dynamic shaping the market is the architectural race to manage escalating processing demands from on-device AI and immersive applications within the strict power and thermal envelopes of mobile form factors, driving rapid innovation in System on Chip design.
Growth Catalysts
- On-Device AI:The proliferation of applications requiring local machine learning inference, from computational photography to real-time translation, necessitates the integration of specialized Neural Processing Units (NPUs) into mobile SoCs, creating direct demand for heterogeneous architectures.
- Augmented Reality Applications:Demand from the AR sector for low-latency, high-fidelity rendering requires SoCs with powerful, high-throughput GPUs and dedicated vision processors, pulling the market toward more complex and specialized chip designs.
- National Technology Initiatives:Policies in China, such as those promoted by the MIIT, encourage the domestic development of advanced semiconductors, stimulating local design and manufacturing of complex heterogeneous processors to achieve technological self-reliance.
Market Restraints
- Manufacturing Cost Escalation:The immense capital expenditure required for next-generation fabrication technologies, such as extreme ultraviolet (EUV) lithography, limits the number of foundries capable of producing advanced SoCs, increasing costs for chip designers.
- Foundry Concentration Risk:Geographic concentration of leading-edge semiconductor foundries in Taiwan and South Korea creates significant supply chain vulnerability, exposing the entire mobile ecosystem to geopolitical and logistical disruptions.
- Thermal Management Limits:Integrating increasingly powerful CPU, GPU, and NPU cores onto a single die generates substantial heat, posing a fundamental physical constraint that limits sustained performance in passively cooled devices like smartphones.
Strategic Opportunities
- Automotive Computing Platforms:The transition to software-defined vehicles creates a significant opportunity for high-performance, safety-certified heterogeneous processors to power in-vehicle infotainment, advanced driver-assistance systems (ADAS), and autonomous driving functions.
- EU AI Act Compliance:Forthcoming regulations like the EU AI Act may create demand for processors with hardware-level security, privacy, and explainability features, offering a path for differentiation based on verifiable trust and compliance. *Edge Computing Infrastructure: The expansion of 5G networks enables more powerful edge computing devices in industrial and enterprise settings, opening a new market for mobile processing architectures optimized for ruggedness and specific AI workloads beyond consumer electronics.
Industry Challenges
- SoC Verification Complexity:Verifying the correct interaction and data flow between multiple specialized processing cores is an immense engineering challenge, leading to longer design cycles and a scarcity of qualified verification engineers. *Divergent Regulatory Compliance: Navigating the conflicting technical standards and data governance rules set by bodies like the US FTC, the European Commission, and China's MIIT complicates global product launches and increases compliance overhead.
- Intellectual Property Entanglement:The market is characterized by dense patent thickets and cross-licensing agreements for essential technologies like CPU architectures and wireless connectivity, creating a constant risk of litigation and high licensing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heterogeneous Mobile Processing and Computing Market |
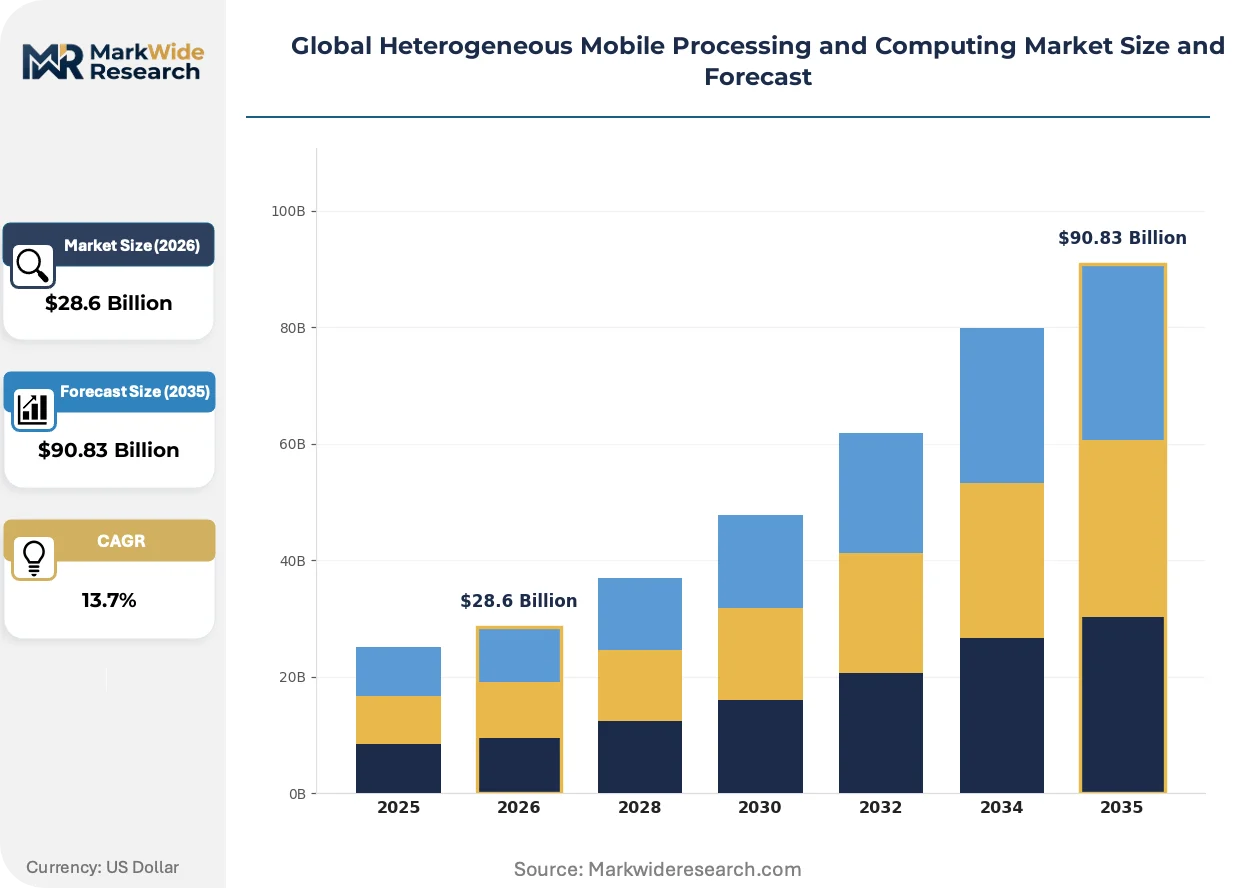
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, DSP, FPGA, NPU, ASIC Integration Level: System on Chip, Multi-Chip Module, Package on Package, Discrete Components Use Case: Gaming, Augmented Reality, Machine Learning, Edge Computing, Video Processing, Natural Language Processing End User Industry: Consumer Electronics, Telecommunications, Aerospace, Defense, Automotive Tier-1 Suppliers, Semiconductor Fabricators |
| Companies Covered | Qualcomm Inc., Apple Inc., Advanced Micro Devices Inc., Nvidia Corporation, MediaTek Inc., ARM Holdings PLC, Samsung Electronics Co. Ltd., Texas Instruments Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heterogeneous Mobile Processing and Computing Market Strategic Shifts & Innovations
The co-evolution of hardware specialization and software-based business models is redefining value in the mobile computing ecosystem. Chip architectures are becoming more diverse to handle specific workloads, while firmware updates and subscriptions unlock new revenue streams beyond the initial device sale.
On-chip Neural Processing Units (NPUs) are dedicated hardware accelerators designed for low-power execution of machine learning models. Smartphone manufacturers and edge device producers are rapidly adopting NPUs to enable features like advanced image processing and voice assistants without relying on cloud connectivity. The integration of these specialized cores is rewriting performance metrics, shifting the focus from raw CPU speed to efficient AI task acceleration.
Regulatory frameworks such as the European Commission's Digital Markets Act (DMA) are compelling changes in platform architecture. The DMA's mandates for interoperability and prohibitions on self-preferencing directly challenge tightly controlled hardware and software ecosystems. In response, vertically integrated device makers must re-evaluate their SoC designs to securely enable greater third-party software access and functionality.
A clear shift toward firmware-enabled features delivered via subscription models is altering how hardware capabilities are monetized. This disrupts the traditional model of a one-time hardware purchase by allowing manufacturers to unlock or enhance processor performance and features post-sale. This trend is most prominent in the premium smartphone and automotive sectors, where software updates can activate pre-existing but dormant silicon capabilities.
Global Heterogeneous Mobile Processing and Computing Market Segmentation
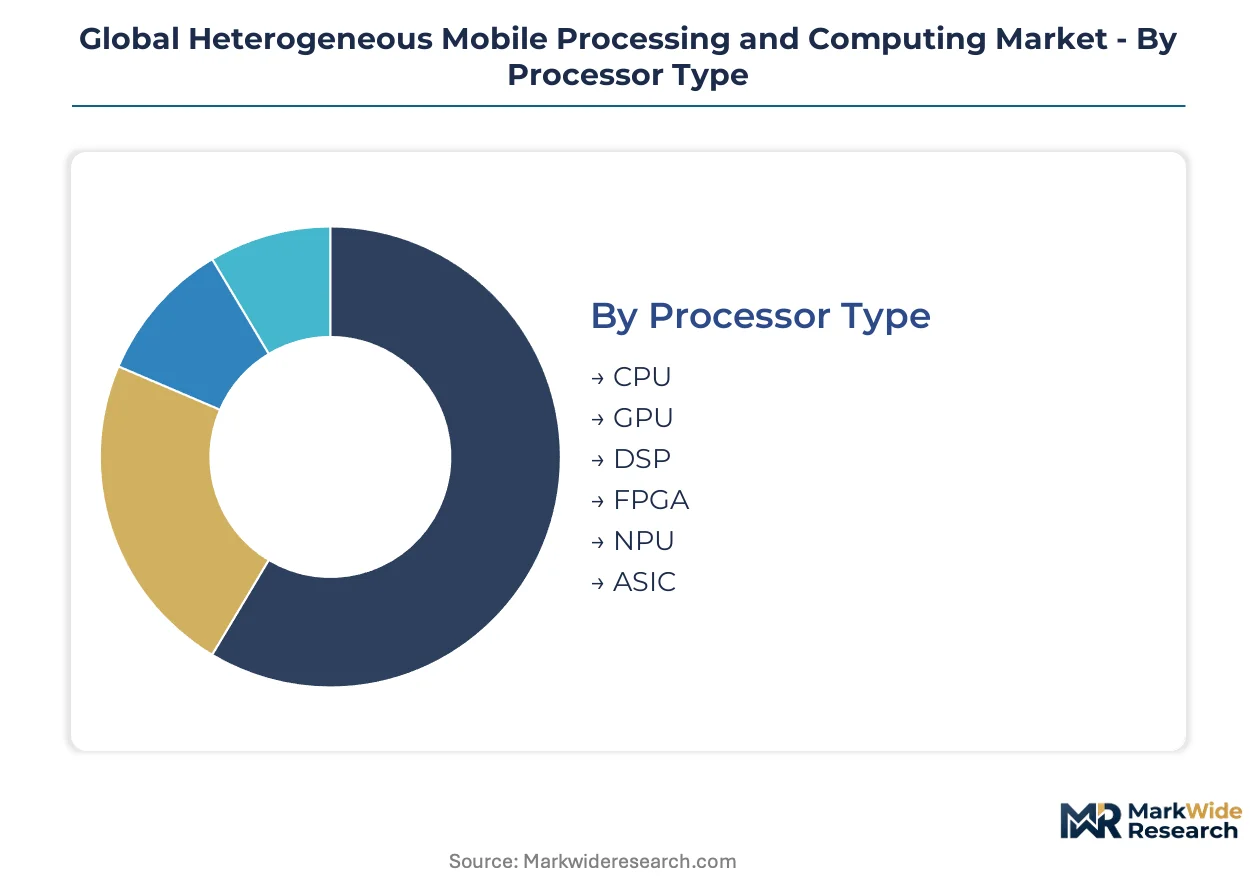
The heterogeneous mobile processing and computing market is analyzed through distinct functional and architectural lenses. Understanding these segments reveals where specialized hardware demand originates and how integration strategies evolve. This detailed classification aids in identifying key growth pockets and technological shifts across the ecosystem.
Processor Type:
The market differentiates processing units based on their architectural design and specific workload optimization. Each processor type addresses distinct computational requirements.
- NPU:Neural Processing Units are specialized accelerators for efficient, low-power machine learning model execution. Demand concentrates in smartphones and edge AI, driven by real-time inference.
- GPU:Graphics Processing Units excel at parallel processing for complex visuals and high-throughput computations. Augmented reality and advanced gaming drive significant demand in mobile SoCs.
- CPU:Central Processing Units provide general-purpose compute, orchestrating system tasks.
- DSP:Digital Signal Processors optimize repetitive arithmetic, used in audio, video, and communications.
- FPGA:Field-Programmable Gate Arrays offer reconfigurable logic for custom acceleration.
- ASIC:Application-Specific Integrated Circuits are custom chips for singular functions, maximizing efficiency.
CPU leads on scale; NPU leads on momentum.
Integration Level:
The approach to integrating diverse processing units significantly impacts device performance, power consumption, and manufacturing complexity. Different integration levels address varying design priorities.
- System on Chip:SoCs integrate major components onto a single die for maximum efficiency and compact form factors. Smartphone and tablet manufacturing drives widespread global adoption.
- Multi-Chip Module:MCMs combine multiple integrated circuits within a single package for flexibility and performance scaling. High-performance edge devices utilize this.
- Package on Package:PoP technology stacks multiple IC packages vertically, minimizing footprint.
- Discrete Components:Separate chips for each function offer maximum design flexibility but consume more space.
System on Chip solutions represent the prevailing standard, evolving towards greater integration.
Use Case:
Application requirements directly dictate the necessary heterogeneous processing capabilities, driving demand for specialized hardware. Each use case presents unique computational and latency challenges.
- Augmented Reality:AR applications require intense, low-latency graphics rendering and real-time sensor fusion, necessitating powerful GPUs and dedicated vision processors. Consumer electronics companies push this demand.
- Machine Learning:On-device machine learning inference demands efficient NPU and DSP capabilities to process complex algorithms locally. AI features in mobile devices drive this segment globally.
- Gaming:Mobile gaming requires high-performance GPUs and efficient CPUs for immersive experiences.
- Edge Computing:Processing data closer to its source needs robust, power-efficient heterogeneous processors for real-time analytics.
- Video Processing:Encoding, decoding, and enhancing video content relies on specialized hardware accelerators.
- Natural Language Processing:NLP tasks like translation and voice assistants leverage NPUs and DSPs.
Augmented Reality and Machine Learning applications are expanding most quickly, transforming mobile device capabilities.
End User Industry:
Different industries leverage heterogeneous mobile processing and computing for distinct operational and product development needs. Each sector's specific requirements shape the adoption patterns of these advanced architectures.
- Consumer Electronics:This industry represents the largest volume driver, integrating heterogeneous processors into smartphones, tablets, and wearables. Global demand for advanced mobile devices fuels this segment.
- Automotive Tier-1 Suppliers:These suppliers integrate heterogeneous processors into advanced driver-assistance systems (ADAS), infotainment, and autonomous driving platforms. The shift to software-defined vehicles creates significant opportunities.
- Telecommunications:The telecom sector uses these processors in network infrastructure and client devices for 5G capabilities.
- Aerospace:Aerospace demands ruggedized, high-reliability heterogeneous processors for mission-critical systems.
- Defense:The defense industry employs specialized computing for secure communications and advanced weapon systems.
- Semiconductor Fabricators:These companies produce the advanced silicon chips powering heterogeneous mobile processing solutions.
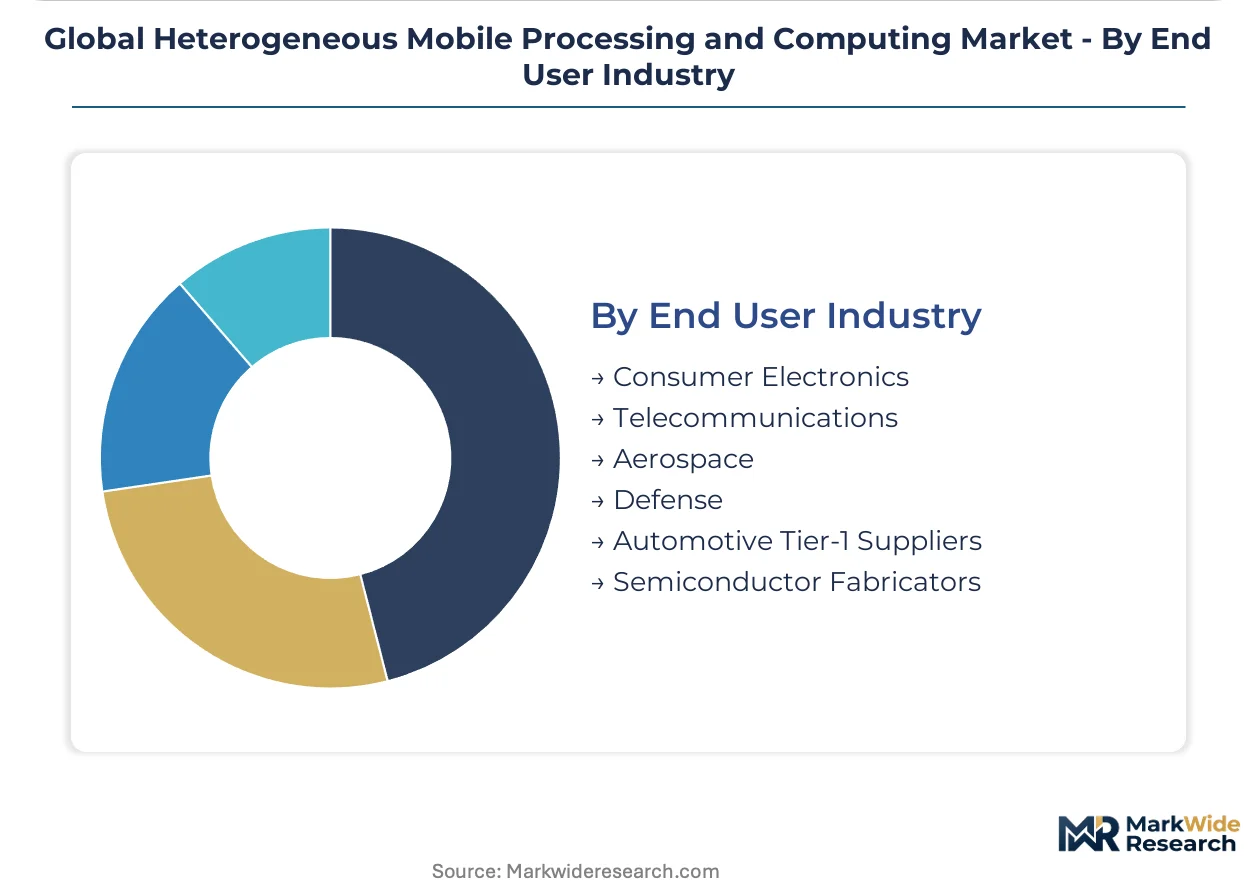
Consumer Electronics remains the primary volume driver, while Automotive Tier-1 Suppliers are increasingly influential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and China present distinct yet powerful forces shaping the global heterogeneous mobile processing and computing market. Both nations prioritize advanced semiconductor development, albeit through different economic and regulatory frameworks. This strategic divergence influences innovation and supply chain dynamics across the ecosystem.
United States
Demand for heterogeneous processors in the United States stems from robust innovation in on-device AI and augmented reality applications. The US Federal Trade Commission (FTC) influences platform dynamics and market access through competition and interoperability standards. Silicon Valley and Austin serve as key technology clusters, driving significant investment in advanced SoC design.
China
China's market expansion is propelled by national technology initiatives and the rapid adoption of mobile AI features. The Ministry of Industry and Information Technology (MIIT) sets technical requirements and network access licenses for devices sold within its borders. The Yangtze River Delta region, including Shanghai, fosters domestic semiconductor design and manufacturing capabilities.
South Korea
South Korea demonstrates strong demand for high-performance SoCs, particularly for premium smartphones and advanced consumer electronics. The country's Ministry of Science and ICT supports R&D into next-generation semiconductor technologies and AI integration. Major technology hubs like Seoul and Gyeonggi province lead in advanced memory and NPU development.
Germany
Germany's market for heterogeneous processors is increasingly driven by automotive computing platforms and industrial edge applications. The upcoming EU AI Act may create demand for processors with hardware-level security and explainability features. Bavaria and Stuttgart are centers for automotive electronics, integrating sophisticated AI into vehicles.
Taiwan
Taiwan remains critical due to its foundry concentration, supplying advanced semiconductor manufacturing for global mobile processors. The Ministry of Economic Affairs promotes investment in cutting-edge fabrication technologies like EUV lithography. The Hsinchu Science Park is a global hub for chip design and manufacturing, supporting diverse heterogeneous architectures.
Global Heterogeneous Mobile Processing and Computing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the heterogeneous mobile processing market. This market exhibits a tiered structure, with a few dominant integrated device manufacturers coexisting with specialized IP licensors and fabless design houses. Strategic archetypes include vertically integrated ecosystem players, pure-play semiconductor designers, and high-performance computing specialists. Companies employ strategic partnerships and continuous R&D investment to maintain their technological edge.
Vertically integrated ecosystem players, such as Apple Inc., optimize heterogeneous processing for their proprietary device portfolios, ensuring tight hardware-software co-design and performance. Qualcomm Inc. exemplifies a leading pure-play semiconductor designer, focusing on mobile connectivity and diverse processing unit integration for a broad client base. Nvidia Corporation represents a high-performance computing specialist, extending its expertise from data centers into advanced AI workloads for mobile edge computing applications. These distinct approaches underscore the varied strategies adopted by market participants to capture value and differentiate their offerings in a complex technological landscape.
| Leading Market Players |
|---|
| Qualcomm Inc. |
| Apple Inc. |
| Advanced Micro Devices Inc. |
| Nvidia Corporation |
| MediaTek Inc. |
| ARM Holdings PLC |
| Samsung Electronics Co. Ltd. |
| Texas Instruments Inc. |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Next-generation fabrication technologies, such as extreme ultraviolet lithography, simultaneously reshape cost economics by demanding immense capital expenditure and concentrate supply within a few specialized foundries.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for advanced heterogeneous processors. A hybrid pricing model combines per-unit transactional fees for integrated chips with licensing and royalty agreements for underlying intellectual property. Price differentiation stems from performance tiers and the brand premium associated with leading chip designers. Cost compression in the consumer electronics segment is intensifying due to high volume demands and intense competition. Automotive Tier-1 suppliers exhibit lower price sensitivity due to stringent reliability requirements and longer product lifecycles.
Supply Chain Analysis
Refurbishment and recycling initiatives for mobile devices introduce reverse logistics flows for heterogeneous processors. Geographic supply concentration centers on Taiwan and South Korea for manufacturing, complemented by design hubs in the United States. The supply chain draws from critical raw materials like rare earth elements and relies on specialized lithography equipment. Single-source vulnerability for advanced fabrication tools represents a significant supply chain risk. Distribution runs through direct sales to large original equipment manufacturers and a network of specialized distributors for smaller device makers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with significant cost differentials between advanced semiconductor manufacturing in Asia and design centers in North America and Europe.
For Market Incumbents: Hedge against increasing regulatory fragmentation by investing in adaptable SoC architectures. Deepen intellectual property portfolios in specialized processing units like NPUs and vision processors. This strategic move counters emerging fabless competitors focusing on niche AI workloads. Pursue strategic partnerships for guaranteed access to cutting-edge foundry capacity in South Korea.
For New Entrants and Emerging Players: Open-source hardware platforms offer a path to market entry by reducing initial development costs. Target specialized edge AI applications in industrial IoT devices, which remain a penetrable segment. Focus on developing custom accelerators for specific workloads, leveraging a go-to-market strategy built on partnerships with system integrators. This approach avoids direct competition with established players in high-volume consumer electronics.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized IP licensors and smaller fabless design houses focused on niche AI acceleration. Long-term viability hinges on sustained demand for on-device AI capabilities across diverse applications. Target acquisition archetypes include NPU IP developers and firms specializing in advanced verification software. The signal to watch is consolidation among these verification tool vendors, indicating maturation and standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen NPU Architecture R&D | Enhances on-device AI performance, differentiating mobile processors in a competitive market. |
| Secure Foundry Capacity Agreements | Mitigates supply chain risks and ensures production for next-generation heterogeneous chips. |
| Invest in Software-Defined Vehicle Platforms | Captures new demand for high-performance processors in the rapidly evolving automotive sector. |
| Expand Edge AI Solution Portfolio | Addresses the growing need for localized processing in industrial and enterprise settings. |
| Acquire Verification Software Specialists | Streamlines complex SoC design cycles and improves time-to-market for advanced chipsets. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This approach combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. We engaged SoC architects, device OEMs, foundry executives, and AI application developers. Secondary data sources included company financial reports, patent databases, government technology policy documents, and industry association publications, all triangulated with bottom-up and top-down analyses.
Volume and value forecasts were modeled at granular levels across processor types, integration levels, and end-user industries. This analytical framework projects market dynamics across the analysis window. Segmentation dimensions included processor type, integration level, use case, end-user industry, and regional adoption patterns. Compound annual growth rates were derived by analyzing historical growth trends and projected technological advancements, with key inputs including semiconductor CapEx and smartphone shipment forecasts.
Geopolitical shifts, rapid technological obsolescence, and regulatory enforcement changes are the dominant revision risks for these forecasts. Forecasts reflect assumptions documented through extensive research and expert consultation. Practitioners should monitor supply chain disruptions, shifts in consumer demand for AR/AI, and new regulatory mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Global Microprocessor and GPU Market