
 Memory Module Market | 2026-2036
Memory Module Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Module Market Intelligence
Specialized packaging engineers and lithography technicians is reorganizing output schedules across leading memory fabs. Samsung Electronics leverages captive wafer capacity to anchor its DRAM leadership. SK Hynix sustains aggressive HBM3E ramp timelines to compete in AI accelerator sockets. Micron Technology specializes in vertically integrated NAND and DRAM production to control cost curves.
A memory module is a printed circuit board assembly populated with integrated circuit memory chips, typically organized in ranks with defined pin configurations, clock speeds, and voltage thresholds to interface with host processors via standardized buses. Its primary purpose is to expand volatile or non-volatile storage capacity in computing systems while meeting signal integrity and thermal constraints. DRAM modules command the largest revenue pool as server refresh cycles accelerate, while Flash Memory in SSD form factors captures the fastest volume growth as data centers displace mechanical drives. NVDIMM technology occupies a premium niche where persistent memory bridges latency gaps between DRAM and NAND in financial trading platforms.
The US Federal Communications Commission and the Environmental Protection Agency shape module electromagnetic compatibility and hazardous substance thresholds, while China's Ministry of Industry and Information Technology enforces domestic content and energy-efficiency benchmarks that filter into procurement specifications. South Korea's METI-aligned standards and Japan's JIS certification requirements add compliance layers for cross-border shipments. Stakeholders must monitor how module power budgets and materials declarations evolve under tightening multi-jurisdiction rules.
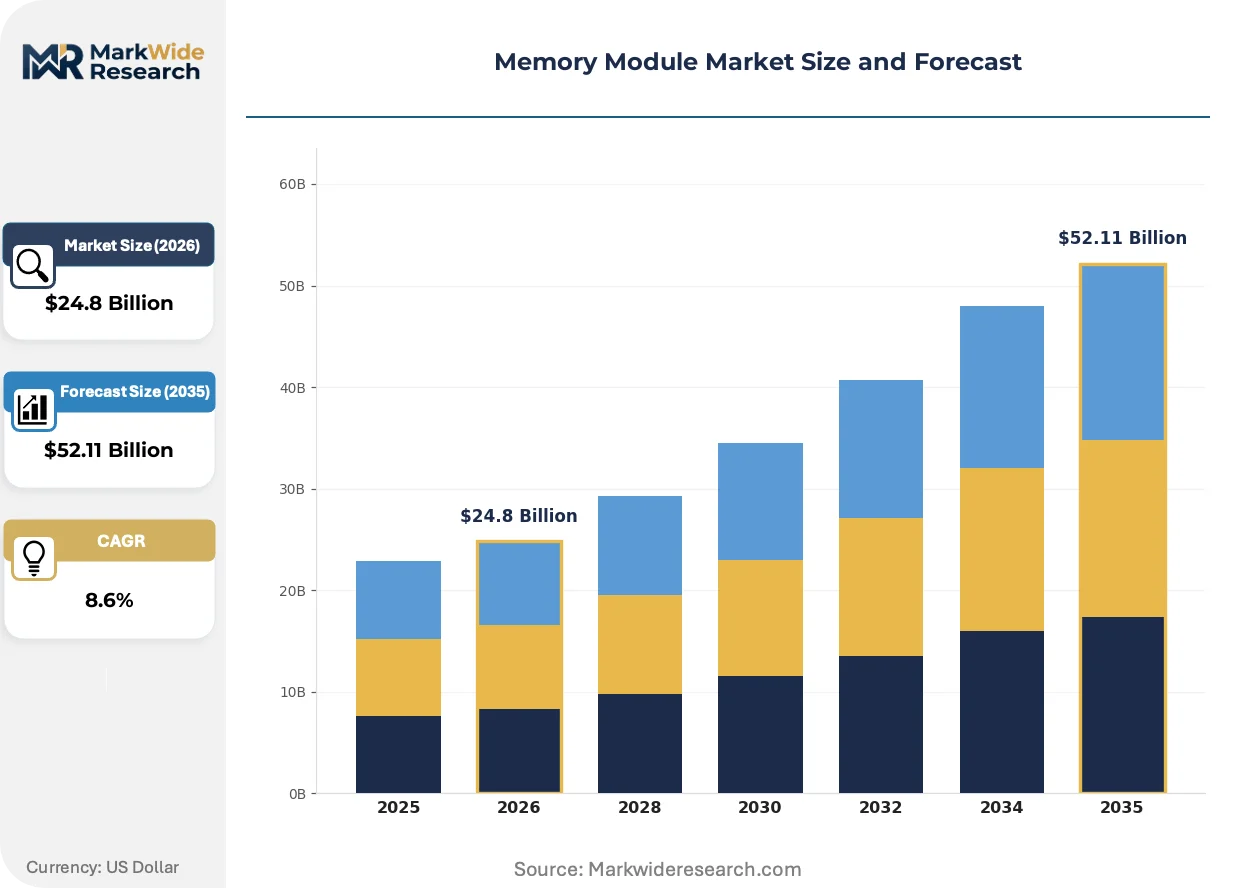
Market Dynamics
High-Bandwidth Memory 3E (HBM3E) stack architectures are compressing module form factors while multiplying pin density requirements, forcing substrate suppliers and packaging houses to synchronize roadmaps with foundry lithography nodes.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale data centers in the United States and China are commissioning multi-exaflop GPU arrays that consume HBM3E modules in 12-stack configurations, creating pull-through demand for配套 registered DIMMs.
- China's Dual Carbon Mandates:MIIT energy-efficiency benchmarks for data center PUE ratios below 1.3 are filtering into module procurement specifications, favoring low-voltage DDR5 and advanced power management ICs.
- Automotive Zonal Architectures:Centralized compute platforms in electric vehicles require GDDR6 and LPDDR5 modules with AEC-Q100 qualification, opening new sockets previously served by discrete DRAM packages.
Market Restraints
- Advanced Substrate Bottlenecks:Ajinomoto Build-up Film (ABF) substrate capacity constraints in Taiwan and Japan are elongating lead times for high-layer-count memory modules beyond 26 weeks.
- EUV Lithography Concentration:Single-source dependency on ASML EUV scanners for sub-1α DRAM nodes creates vulnerability to equipment delivery delays or export control restrictions.
- Legacy DDR4 Inventory Overhang:Enterprise server refresh delays are extending DDR4 module service life, compressing DDR5 ASP recovery and fab conversion economics.
Strategic Opportunities
- India Data Center Buildout:PLI scheme incentives for electronics manufacturing are attracting module assembly and test investments to Chennai and Bengaluru corridors, creating captive supply for domestic cloud operators.
- Compute Express Link (CXL) 3.0 Adoption:Memory pooling architectures enabling fabric-attached DRAM are creating attach-rate expansion for CXL-enabled modules in financial services and scientific computing.
- NVDIMM-P Persistent Memory:Battery-backed and capacitor-backed non-volatile DIMMs are penetrating high-frequency trading platforms where sub-microsecond recovery from power loss commands 10-15x DRAM pricing premiums.
Industry Challenges
- Packaging Engineer Scarcity:TSV (through-silicon via) microbumping and hybrid bonding expertise concentrates at Samsung, SK Hynix, and TSMC, constraining second-source qualification timelines for module integrators.
- Multi-Jurisdiction Compliance Burden:Simultaneous FCC Part 15 electromagnetic compatibility, EU RoHS substance restrictions, and China GB standards for hazardous materials declarations extend certification cycles by 4-6 months.
- Signal Integrity at 6400 MT/s:DDR5-6400 module designs require PCB layer counts exceeding 12 layers and on-die ECC, squeezing margin for commodity module assemblers without captive substrate capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Module Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash Memory,EEPROM Application: Consumer Electronics, Automotive, Data Centers, Telecommunications End User: OEMs, Cloud Providers, System Integrators, Retailers Technology: DDR, LPDDR, GDDR, NVDIMM |
| Companies Covered | Western Digital, Intel Corporation, Samsung Electronics, Marvell Technology, Lam Research, SK Hynix, Kioxia, Kingston Technology, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Module Market Strategic Shifts & Innovations
Memory module architectures are splitting between bandwidth-optimized HBM stacks for AI accelerators and capacity-optimized DIMMs for general-purpose servers, with packaging technology becoming the primary differentiation lever.
HBM3E with 12-layer DRAM stacks and 9.6 Gbps per-pin signaling is bifurcating the high-performance module landscape. NVIDIA and AMD AI accelerators consume 80-90% of available HBM3E supply, leaving minimal volume for scientific computing and networking applications. This concentration is forcing module suppliers to choose between HBM qualification investments that require $50M+ capex commitments or retreating to commodity DDR5 markets with compressed margins.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are eliminating perfluorinated compounds from module cleaning processes. German and Dutch module assemblers are converting to aqueous and plasma-based cleaning chemistries, adding 8-12% to processing costs. Automotive module suppliers with AEC-Q100 qualification are most affected, as trace contamination tolerances tighten simultaneously with solvent transitions.
Hyperscale buyers are consolidating memory module procurement through direct foundry relationships rather than distributor channels. Amazon Web Services, Microsoft Azure, and Google Cloud are negotiating wafer-level agreements with Samsung and SK Hynix, bypassing traditional module integrators for 30-40% of their HBM and high-capacity DDR5 requirements. This disintermediation is most advanced in the United States, where cloud capital expenditure concentration enables volume commitments that justify direct engagement.
Memory Module Market Segmentation
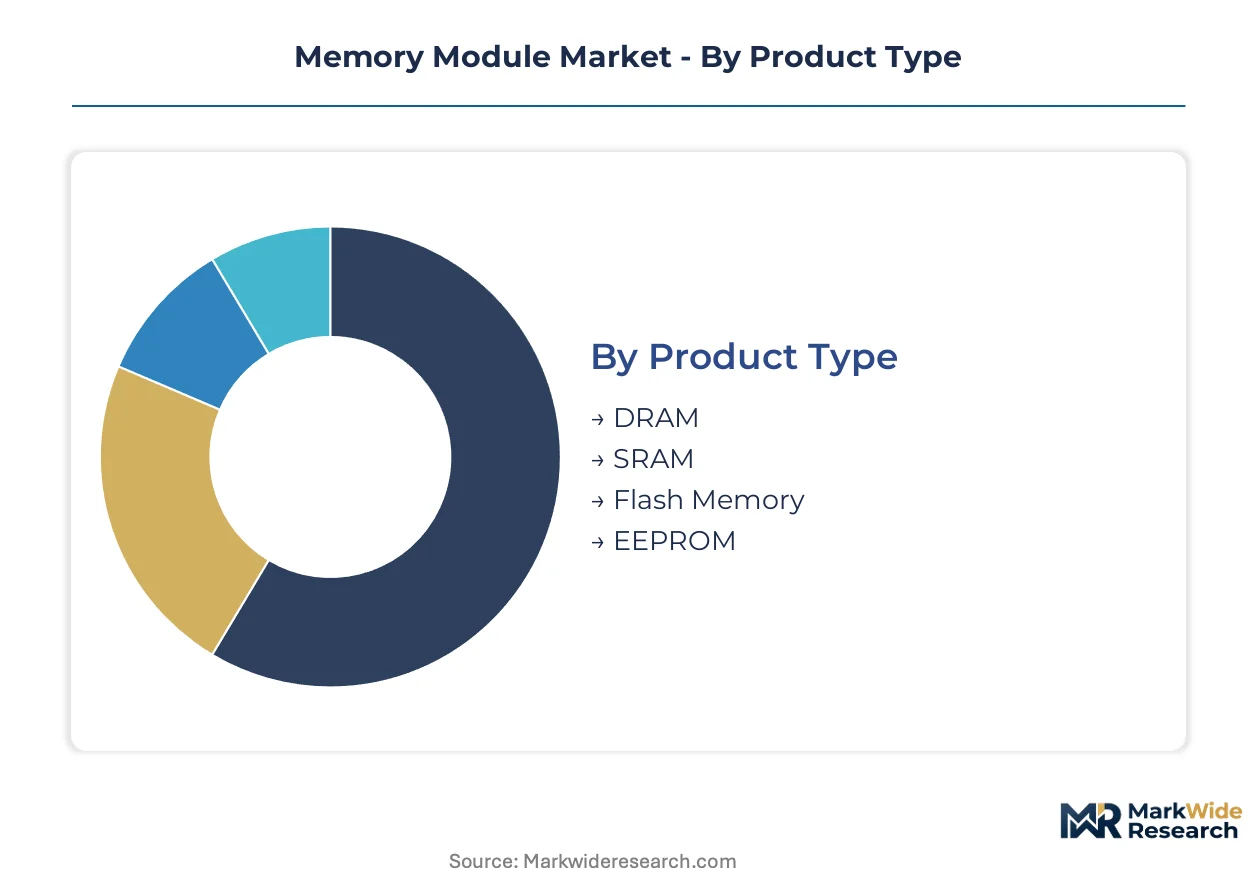
Memory module segmentation reveals how substitution pressures between volatile and non-volatile technologies reshape procurement patterns. Understanding these category boundaries exposes where module suppliers can defend margin pools against emerging memory-class alternatives.
Product Type:
Flash memory faces the most acute substitution pressure as 3D NAND bit density improvements displace lower-capacity DRAM in edge computing sockets.
- DRAM:Capacitor-based volatile memory requiring constant refresh cycles, organized in ranks with defined RAS/CAS timing parameters. Server refresh cycles in United States hyperscale facilities are pulling registered DIMM configurations toward DDR5-5600 and beyond. DDR4 inventory overhangs in enterprise channels compress near-term pricing power.
- Flash Memory:Floating-gate or charge-trap non-volatile storage in NAND configurations, packaged as SSDs or discrete BGA modules. Data center displacement of mechanical drives in South Korea's semiconductor corridor accelerates volume concentration here. QLC density gains threaten TLC margin structures in consumer applications.
- SRAM:Six-transistor cell architecture delivering fastest access latencies without refresh overhead, deployed in CPU cache hierarchies. Cache coherency protocols in AI training clusters sustain specialized demand despite cost premiums over DRAM alternatives.
- EEPROM:Electrically erasable programmable read-only memory with byte-level write granularity, serving firmware storage and calibration data retention. Automotive zonal architectures in Germany's electric vehicle supply chain embed these modules for persistent configuration storage.
DRAM anchors the volume base while Flash Memory gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity consumer modules from qualified automotive and data center grades commanding 3-5x ASP premiums.
- Data Centers:Hyperscale compute and storage infrastructure demanding registered DIMMs with ECC and thermal sensors across extended temperature ranges. China's MIIT PUE benchmarks below 1.3 filter into low-voltage DDR5 procurement specifications for new builds in Beijing and Shanghai corridors.
- Automotive:AEC-Q100 qualified modules with ISO 26262 functional safety coverage for zonal compute platforms. GDDR6 and LPDDR5 configurations in electric vehicle centralized architectures displace discrete DRAM packages previously distributed across multiple ECUs.
- Consumer Electronics:Standard unbuffered DIMMs and SODIMMs for client computing, gaming, and mobile devices. Inventory digestion in PC OEM channels elongates replacement cycle visibility.
- Telecommunications:Ruggedized modules with extended temperature specifications for baseband processing and edge routing infrastructure. 5G RAN deployments in India's urban corridors create qualified module demand with domestic content requirements.
Data Center applications command the premium tier while Automotive climbs the fastest toward qualification-intensive supply positions.
End User:
Customer type concentration determines whether procurement flows through distribution or direct foundry engagement, reshaping margin capture for module integrators.
- Cloud Providers:Hyperscale operators negotiating wafer-level agreements with Samsung and SK Hynix for 30-40% of HBM and high-capacity DDR5 requirements. Amazon Web Services and Microsoft Azure in the United States bypass traditional module channels for AI training cluster builds.
- OEMs:Original equipment manufacturers assembling servers, workstations, and client devices with validated module supplier lists. Dell and HPE maintain qualified vendor programs with 12-18 month certification cycles.
- System Integrators:Value-added resellers configuring custom server and storage platforms for enterprise and mid-market deployment. Regional integrators in India's Bengaluru corridor leverage PLI scheme incentives for domestic assembly.
- Retailers:E-commerce and brick-and-mortar channels serving enthusiast and upgrade markets with unbuffered DIMM and SODIMM configurations. Newegg and Amazon segment pricing across performance tiers without qualification overhead.
Cloud Providers concentrate procurement leverage while System Integrators expand most quickly in emerging geography corridors.
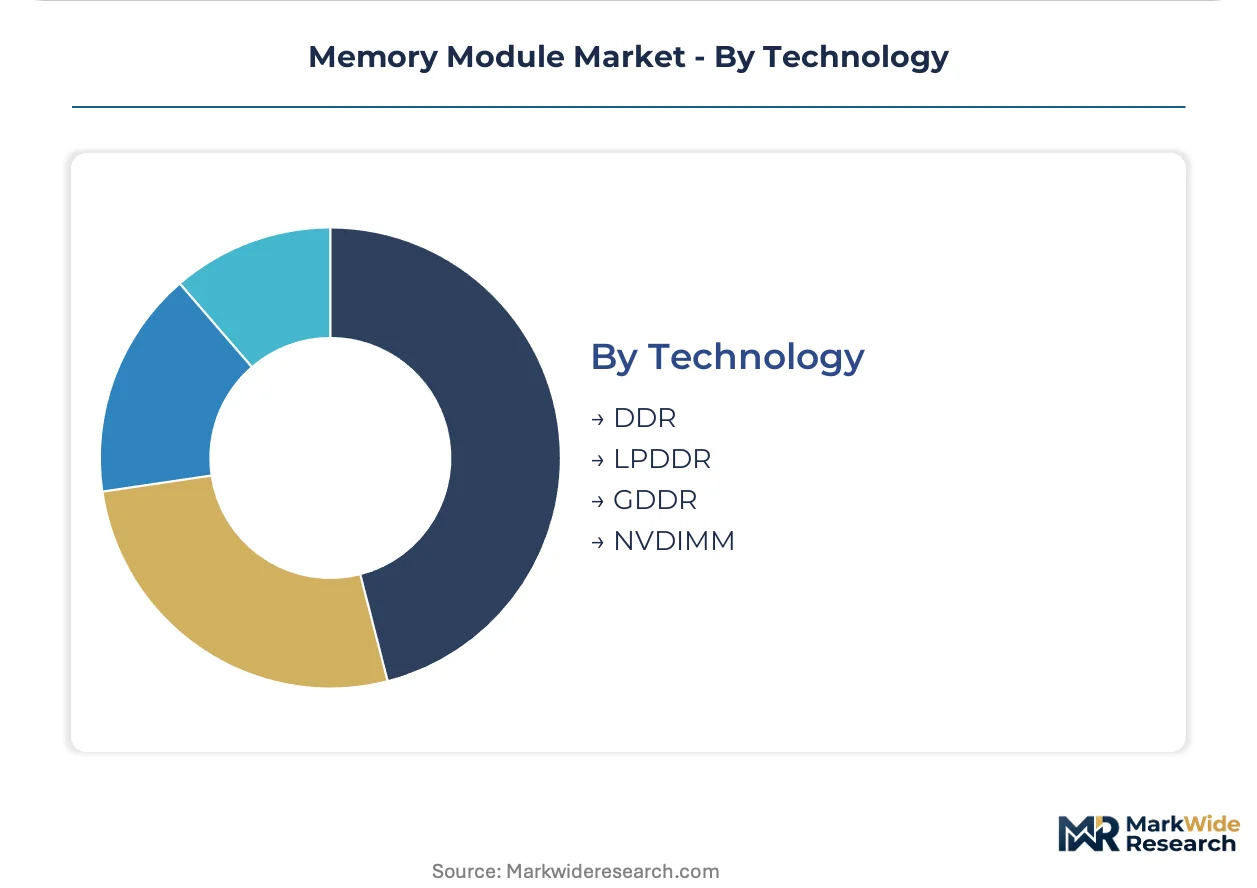
Technology:
Technology maturity curves separate established DDR generations from emerging interface standards redefining memory fabric architectures.
- DDR:Synchronous DRAM with double data rate signaling across five generations, with DDR5-6400 now penetrating server sockets. Signal integrity requirements at 6400 MT/s force 12-layer PCB designs that squeeze commodity assembler margins.
- NVDIMM:Non-volatile DIMM configurations combining DRAM speed with NAND persistence through battery or capacitor backup. Financial trading platforms in Chicago and London command 10-15x DRAM pricing premiums for sub-microsecond recovery from power loss.
- LPDDR:Low-power double data rate variants with aggressive voltage scaling for mobile and edge AI applications. LPDDR5X at 8533 Mbps enables on-device inference in flagship smartphone platforms.
- GDDR:Graphics-oriented memory with wider interfaces and higher per-pin bandwidth for GPU and AI accelerator attachment. GDDR6X in NVIDIA gaming products and GDDR6 in automotive visualization sustain parallel demand tracks.
DDR maintains the installed base while NVDIMM scales fastest in premium latency-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Memory module consumption patterns diverge sharply across geographies. United States hyperscale operators prioritize HBM3E bandwidth for AI training clusters, while Chinese procurement emphasizes low-voltage DDR5 compliance with MIIT energy mandates. South Korean fabs anchor high-volume supply, with European and Indian demand growing from automotive and data center buildouts respectively.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud commission multi-exaflop GPU arrays consuming 80-90% of global HBM3E supply. FCC Part 15 electromagnetic compatibility rules filter into module specifications for domestic cloud infrastructure. Northern Virginia and Phoenix data center corridors concentrate procurement leverage, with direct foundry agreements bypassing traditional distribution channels.
China
MIIT enforces data center PUE ratios below 1.3, reshaping procurement toward low-voltage DDR5 and advanced power management ICs. Dual carbon goals accelerate legacy equipment retirement in Beijing and Shanghai corridors. Yangtze River Delta module assemblers face REACH-aligned substance declarations for export-bound shipments to European markets.
South Korea
Samsung Electronics and SK Hynix anchor captive wafer capacity for DRAM and HBM production. METI-aligned standards govern cross-border module shipments to Japan. Seoul Capital Area and Busan-Ulsan corridors concentrate packaging expertise, with TSV microbumping and hybrid bonding capabilities constraining second-source qualification timelines.
Germany
Automotive zonal architectures in electric vehicle supply chains demand GDDR6 and LPDDR5 modules with AEC-Q100 qualification. EU RoHS substance restrictions and F-Gas Regulation phase-downs eliminate perfluorinated compounds from module cleaning processes. Bavaria and Baden-Württemberg industrial clusters absorb 8-12% processing cost increases from aqueous chemistry transitions.
India
PLI scheme incentives attract module assembly and test investments to Chennai and Bengaluru corridors. TRAI spectrum allocations and 5G RAN deployments create qualified module demand with domestic content requirements. System integrators leverage tariff advantages to supply captive demand from domestic cloud operators expanding in Mumbai and Hyderabad markets.
Memory Module Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in memory module supply. Samsung Electronics and SK Hynix control captive wafer capacity and advanced packaging nodes, while module integrators without substrate fabrication capabilities compete on assembly efficiency and certification velocity. Three archetypes define competitive positioning: vertically integrated semiconductor conglomerates, fabless module specialists with qualified vendor status, and contract assemblers serving regional demand pockets. Capacity expansion and direct hyperscale procurement relationships constitute the dominant competitive moves, with cloud operators disintermediating traditional distribution for 30-40% of high-performance requirements.
Among integrated semiconductor conglomerates, Samsung Electronics, SK Hynix, and Micron Technology exemplify the tier that controls lithography nodes and substrate capacity. These entities anchor supply for HBM3E and advanced DDR5 configurations, with their captive production determining availability timelines for downstream module integrators. Kingston Technology represents the specialist tier, occupying a position as a qualified vendor for enterprise and consumer channels without wafer fabrication ownership. Western Digital and Kioxia exemplify NAND-focused players whose flash memory expertise translates into SSD module supply, though their competitive position depends on foundry partnerships for DRAM-adjacent portfolios. Intel Corporation and Marvell Technology occupy positions at the semiconductor IP and controller level, with their architectures shaping module interface specifications without direct memory chip production.
| Leading Market Players |
|---|
| Western Digital |
| Intel Corporation |
| Samsung Electronics |
| Marvell Technology |
| Lam Research |
| SK Hynix |
| Kioxia |
| Kingston Technology |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
AEC-Q100 automotive qualification gates both supply qualification and price differentiation simultaneously, separating qualified module suppliers from commodity assemblers by 3-5x ASP multiples while filtering procurement pools for electric vehicle zonal architectures.
Pricing Analysis
Long-term offtake agreements dominate HBM3E procurement between hyperscale cloud operators and captive wafer producers, while spot-market transactions persist for DDR4 legacy inventory and consumer-grade modules. Price differentiation rests on certification tier—AEC-Q100 automotive qualification and JEDEC compliance separate premium sockets from unbuffered DIMM commodity tiers. Cost compression in DDR4 channels intensifies because enterprise server refresh delays extend service life and compress DDR5 conversion economics. System integrators in India exhibit highest price sensitivity due to PLI scheme margin constraints, whereas financial trading platforms demonstrate lowest sensitivity for NVDIMM-P persistent memory commanding 10-15x DRAM pricing premiums.
Supply Chain Analysis
Strategic stockpiling of ABF substrate and advanced packaging capacity characterizes leading memory fabs, while just-in-time inventory models dominate downstream module assemblers without captive substrate fabrication. Supply concentrates in South Korea, Taiwan, and Japan for DRAM wafer output and high-layer-count substrate fabrication. Raw material dependencies center on silicon wafers, Ajinomoto Build-up Film, and EUV photoresist chemistries. Single-source vulnerability to ASML EUV scanner availability creates equipment delivery risk for sub-1α node transitions. Distribution runs through direct foundry relationships for 30-40% of hyperscale HBM and high-capacity DDR5 requirements, bypassing traditional module integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compute Express Link 3.0 interoperability is reconfiguring memory module procurement around fabric-attached pooling architectures, creating platform-economics inflection as ecosystem control shifts from DIMM suppliers to CXL switch and controller vendors.
For Market Incumbents: Consolidate packaging engineer expertise in TSV microbumping and hybrid bonding to defend HBM3E qualification timelines against second-source pressure. Deepen captive substrate capacity in South Korea's Seoul Capital Area to offset ABF supply bottlenecks elongating lead times. Channel control through direct hyperscale relationships protects margin pools from distributor disintermediation.
For New Entrants and Emerging Players: CXL-enabled module integration services represent a service-layer gap where incumbents under-serve financial services and scientific computing segments. Target India's Chennai and Bengaluru corridors for module assembly and test investments leveraging PLI scheme tariff advantages. Go-to-market angle: domestic content compliance for TRAI-mandated 5G RAN deployments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed module integrators possessing qualified vendor status at Dell and HPE but lacking captive wafer capacity. Long-term viability favors entities with backward integration into substrate fabrication or forward integration into CXL controller IP. Signal to watch: hyperscale direct procurement share crossing 50% threshold as disintermediation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| HBM3E Packaging Qualification | Secures allocation from NVIDIA and AMD AI accelerator sockets requiring 12-stack configurations. |
| CXL 3.0 Controller Development | Enables memory pooling architectures for fabric-attached DRAM in financial services. |
| ABF Substrate Capacity Expansion | Reduces dependency on Taiwan and Japan suppliers for high-layer-count modules. |
| Automotive AEC-Q100 Certification | Opens GDDR6 and LPDDR5 sockets in German electric vehicle zonal platforms. |
| India PLI Manufacturing Footprint | Captures domestic content requirements from TRAI 5G RAN deployment mandates. |
Research Approach
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and MIIT energy-efficiency benchmarks preceded structured interviews with packaging engineering directors, data center procurement officers, automotive Tier 1 supplier quality managers, and substrate fabrication planners. Primary fieldwork combined with secondary validation from JEDEC standards documentation, EIA power consumption data, and customs trade records. Bottom-up module shipment estimates triangulated against top-down wafer capacity allocations from South Korean and Taiwanese foundry disclosures.
Variance decomposition across technology node transitions, application mix shifts, and regional procurement patterns shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include memory class, interface generation, certification tier, end-use application, and customer type concentration. CAGRs derived from fitted growth curves applied to wafer-level bit output projections and module average selling price trajectories. Industry-specific inputs encompassed EUV lithography ramp schedules, ABF substrate capacity expansion timelines, and CXL controller adoption curves in enterprise server sockets.
Underlying assumptions cover sustained AI training cluster investment, MIIT PUE enforcement continuity, and ASML equipment delivery schedules, with deviation risk concentrated in export control restrictions and legacy DDR4 inventory digestion rates. Revision becomes warranted when hyperscale direct procurement share or CXL attach rates cross inflection thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Hybrid Memory Cube Market
Memory Chips
DDR SDRAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Digital RF Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
MRAM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Global Standalone Memory Market
Memory Chips
DDR RAM Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Static RAM Market