
 Global Internet of Things Sensors Market | 2026-2036
Global Internet of Things Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Things Sensors Market Outlook
Distributor consolidation across industrial automation channels is narrowing access for mid-tier sensor suppliers. Texas Instruments leverages its analog front-end portfolio to sustain design wins in precision measurement nodes. STMicroelectronics anchors European manufacturing with MEMS fabrication scale. Bosch Sensortec dominates consumer-grade motion sensing through captive wafer capacity and direct OEM relationships.
Internet of Things Sensors are transducer-based devices that convert physical phenomena into digital signals with specified accuracy ranges, typically operating across temperature extremes and electromagnetic interference conditions for real-time telemetry in distributed systems. Pressure sensors and motion sensors command the widest deployment bases, while proximity sensors carry premium positioning in safety-critical industrial automation architectures. Wi-Fi and LoRaWAN connectivity technologies are pulling ahead in smart home and environmental monitoring segments where range and power constraints diverge sharply.
FCC certification requirements in the United States, CE marking under the EU Radio Equipment Directive, and China's MIIT radio transmission approvals collectively shape product development cycles and geographic launch sequencing. ETSI harmonized standards across Europe further compress time-to-market for multi-protocol sensor platforms. Stakeholders must monitor evolving spectrum allocation decisions and cybersecurity labeling mandates to preserve market access and avoid retrofit liabilities.
Market Dynamics
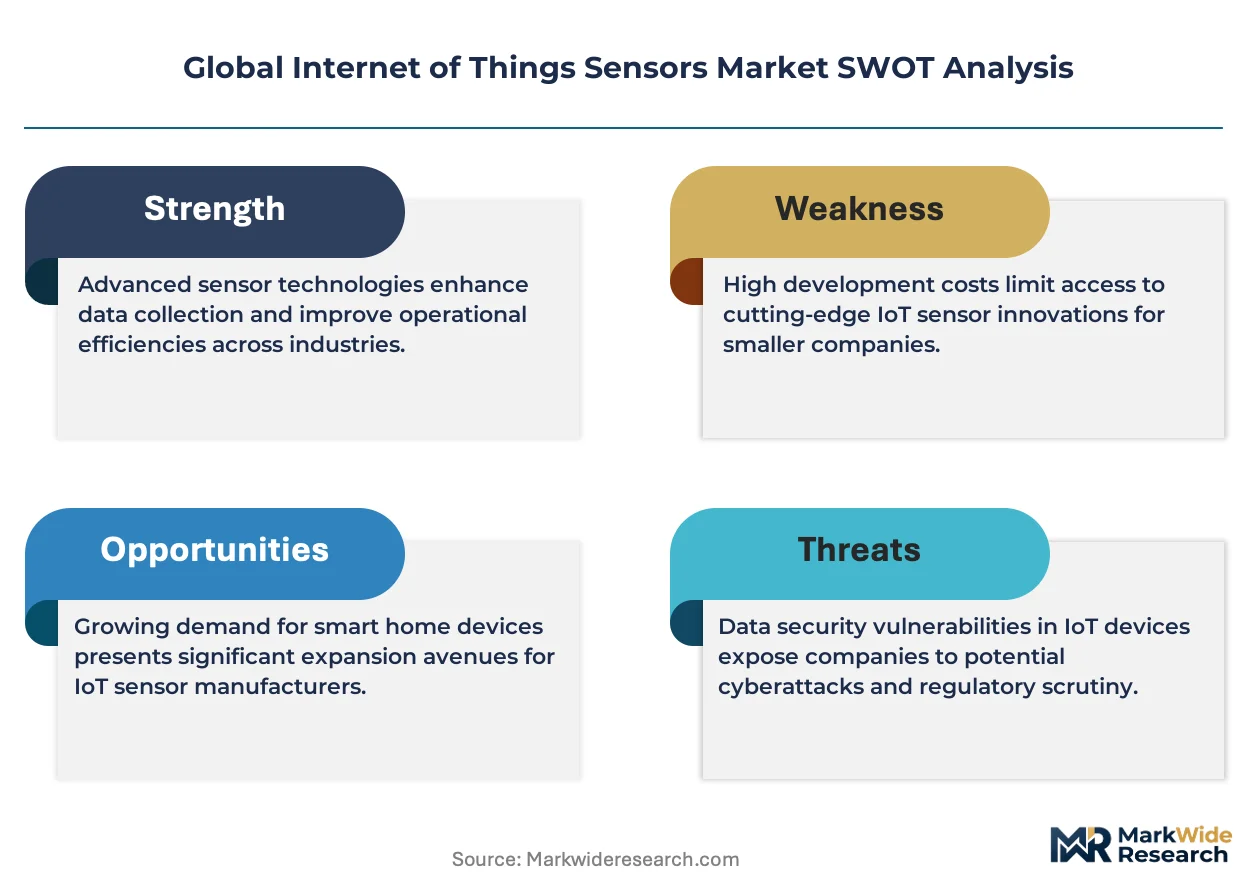
Distributor consolidation across industrial automation channels is compressing margins for mid-tier sensor suppliers while MEMS fabrication scale advantages concentrate among vertically integrated European and Asian manufacturers. FCC certification timelines and EU Radio Equipment Directive compliance costs now determine geographic launch sequencing for multi-protocol platforms.
Growth Catalysts
- GB standards compliance in China:Manufacturing plants under national dual carbon goals are mandating predictive maintenance sensor deployments to optimize energy efficiency and reduce unplanned downtime in heavy industrial facilities.
- Precision agriculture telemetry:Wireless soil moisture and microclimate sensors are expanding acreage coverage as farm operators integrate LoRaWAN connectivity into irrigation automation systems across water-stressed growing regions.
- Remote patient monitoring:HIPAA-aligned telehealth infrastructure is accelerating FDA-cleared biometric sensor adoption in chronic disease management programs requiring continuous physiological data streams.
Market Restraints
- Silicon wafer supply concentration:Captive MEMS foundry capacity at dominant European and Asian suppliers limits second-source options for fabless sensor designers during capacity allocation cycles.
- FCC certification friction:Multi-protocol sensor platforms face extended approval timelines for unlicensed spectrum devices, delaying US market entry and compressing product refresh windows.
- Passive infrared substitution:Low-cost thermal imaging modules are displacing traditional proximity sensors in select indoor occupancy detection applications, pressuring component ASPs.
Strategic Opportunities
- India PLI scheme leverage:Electronics manufacturing incentives under the country's production-linked initiative are attracting sensor packaging and testing investments for export-oriented supply chain reconfiguration.
- EU AI Act compliance hardware:Edge AI sensor modules with embedded inference capabilities are capturing design wins in automated quality inspection systems requiring GDPR-aligned data processing.
- Smart home channel expansion:Direct-to-installer distribution models are bypassing traditional industrial distributor markups for environmental monitoring kits in residential energy management retrofits.
Industry Challenges
- RF engineering talent scarcity:Multi-protocol firmware development for Wi-Fi and LoRaWAN coexistence requires specialized wireless stack expertise that outpaces university pipeline output.
- Legacy system integration friction:Brownfield industrial sites with proprietary SCADA architectures demand costly protocol gateway development for IP-based sensor telemetry deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Things Sensors Market |
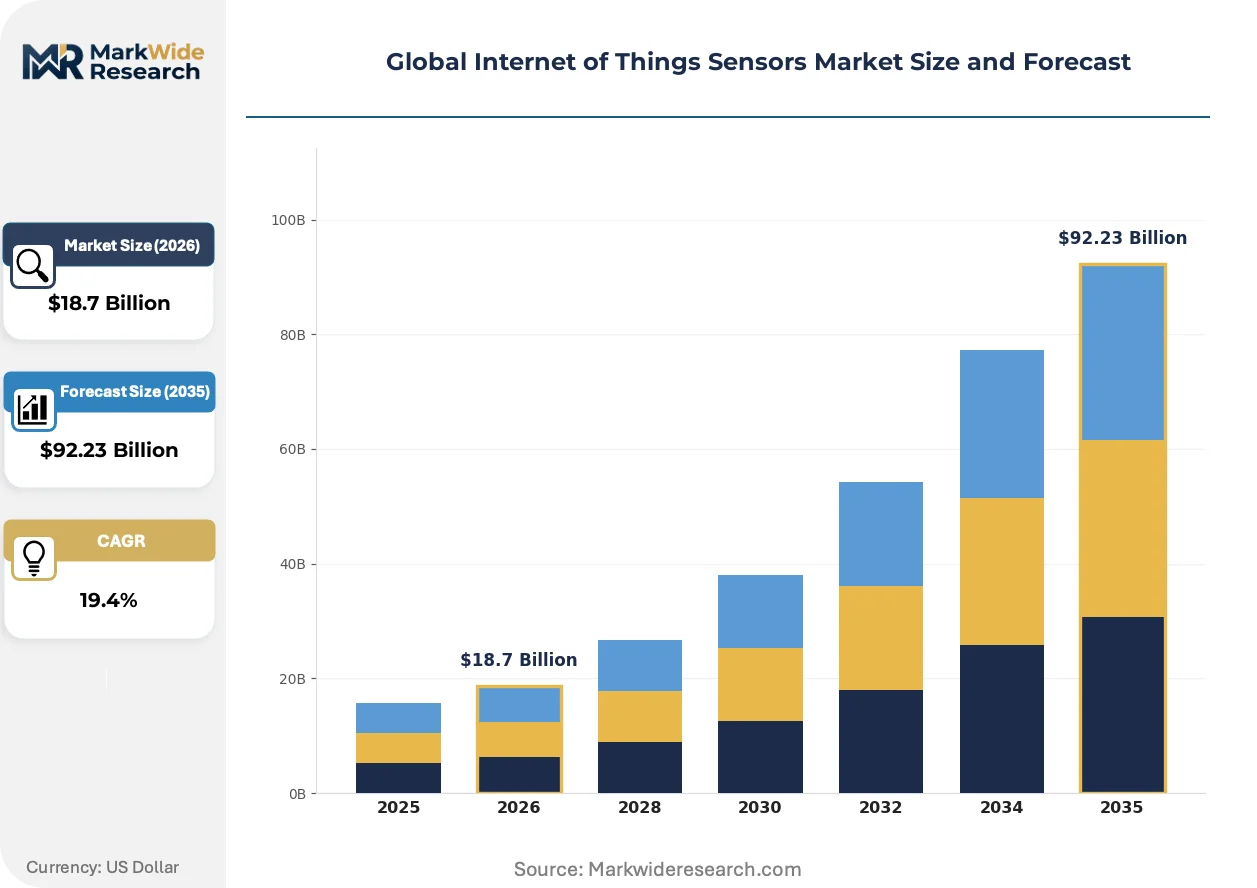
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Motion Sensors Technology: Wi-Fi, Bluetooth, Zigbee, LoRaWAN Application: Smart Home, Industrial Automation, Healthcare Monitoring, Environmental Monitoring End User: Consumer Electronics, Manufacturing, Healthcare, Agriculture |
| Companies Covered | Texas Instruments, TE Connectivity, STMicroelectronics, NXP Semiconductors, Honeywell International, Infineon Technologies, Analog Devices, Bosch Sensortec, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Things Sensors Market Strategic Shifts
Energy harvesting interfaces and ambient-powered sensing nodes are eliminating battery maintenance cycles in distributed telemetry networks. These advances are compressing total cost of ownership models and enabling deployment in previously inaccessible locations.
Photovoltaic-thermal hybrid harvesters integrated with ultra-low-power microcontrollers are extending maintenance-free operation for environmental monitoring nodes in remote agricultural deployments. Precision agriculture operators in Australia and Spain are piloting these systems at scale. The elimination of battery replacement logistics is rendering obsolete traditional wired power infrastructure for distributed sensor grids.
ETSI harmonized standards under the EU Radio Equipment Directive are streamlining multi-country approval pathways for sub-GHz sensor platforms. Industrial automation vendors are consolidating SKUs around unified hardware designs. Germany and France are witnessing accelerated certification cycles for smart building sensor suites that previously required sequential national filings.
Buyer consolidation among agricultural cooperatives is shifting procurement toward multi-year telemetry service contracts with hardware-inclusive pricing. Traditional component distributors are losing volume to systems integrators offering soil-to-cloud monitoring subscriptions. This pattern is most pronounced in Brazil and the US Midwest where large farming operations dominate acreage.
Global Internet of Things Sensors Market Segmentation
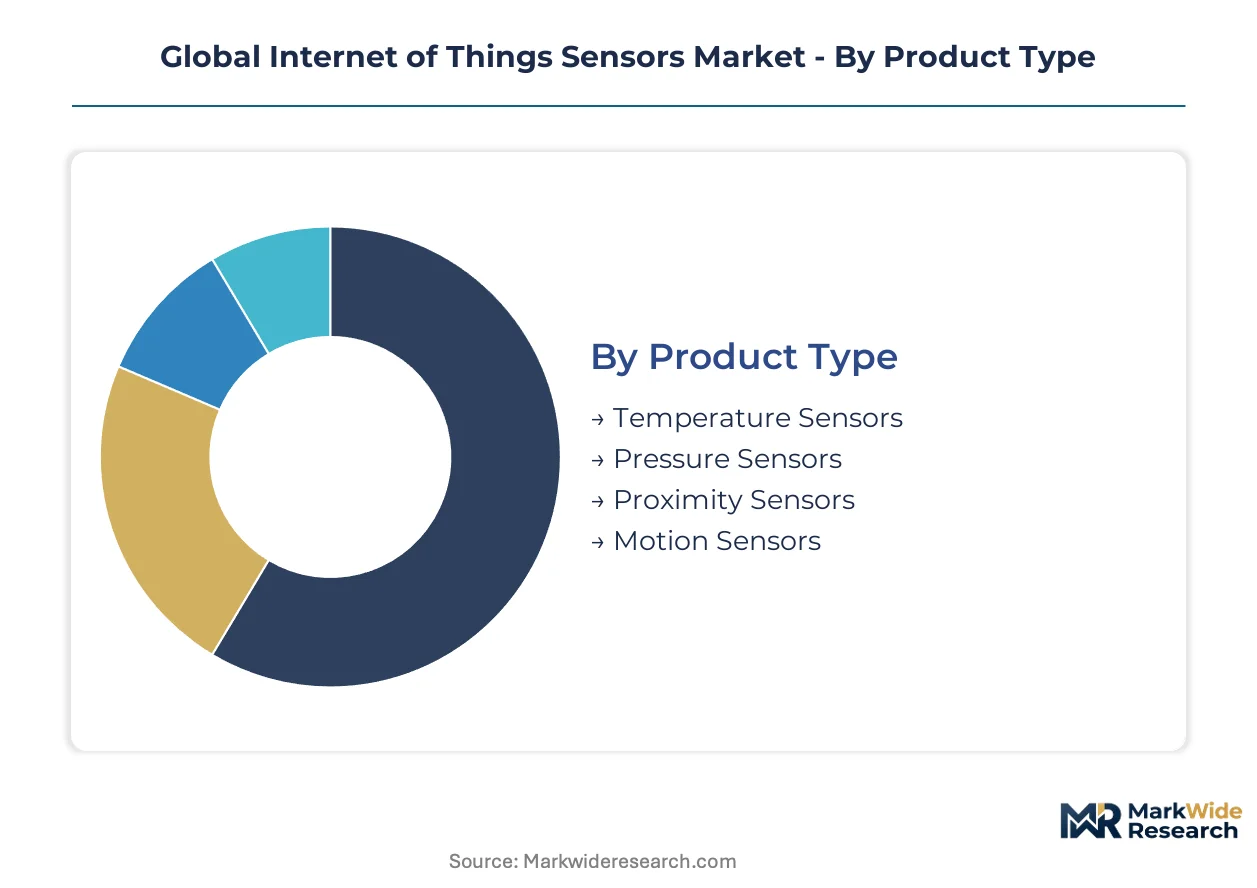
Segmentation in IoT sensors reveals divergent replacement cycles and margin structures across product architectures. Understanding these patterns allows suppliers to align R&D pipelines with revenue velocity and customer lifetime value profiles.
Product Type:
Pressure sensors and motion sensors turn inventory fastest through industrial automation channels, while temperature sensors exhibit longer deployment cycles in environmental infrastructure.
- Pressure Sensors:Piezoresistive and capacitive transducers measure fluid and gas force with ±0.1% accuracy across harsh media conditions. German automotive plants and Chinese steel mills are expanding deployments for hydraulic system monitoring under predictive maintenance mandates.
- Motion Sensors:MEMS-based accelerometers and gyroscopes detect linear and angular displacement with six-axis fusion capabilities. Consumer wearable manufacturers in South Korea and Taiwan are driving volume through biometric tracking integration.
- Temperature Sensors:Thermocouple and RTD variants provide ±0.5°C precision for cold chain logistics and HVAC control networks.
- Proximity Sensors:Inductive and capacitive detection modules enable non-contact object sensing in safety-critical robotic workcells.
Pressure sensors anchor the volume base while motion sensors gain share at the steepest rate.
Technology:
Cost tier stratification separates high-throughput Wi-Fi modules from ultra-low-power LoRaWAN chipsets targeting decade-long battery life.
- Wi-Fi:IEEE 802.11ax-enabled transceivers deliver 100+ Mbps throughput for video-capable smart home devices and industrial gateways. US and Japanese residential automation installers specify these for latency-sensitive security camera networks.
- LoRaWAN:Sub-GHz spread-spectrum modulation achieves 15km rural range at sub-milliwatt standby power. Australian and Spanish agricultural operators are deploying these for soil moisture grids in water-stressed regions.
- Bluetooth:BLE 5.3 stacks enable mesh networking for indoor positioning and asset tracking in healthcare facilities.
- Zigbee:2.4GHz mesh protocols dominate utility smart meter deployments requiring IPv6 addressability.
Wi-Fi commands the highest unit volumes while LoRaWAN expands most quickly in greenfield telemetry networks.
Application:
Customer type differentiation separates consumer-facing smart home installations from capital-intensive industrial automation retrofits.
- Industrial Automation:Hardened sensor nodes with IP67 ratings and SIL 2 safety certification monitor rotating equipment and process variables. German machinery OEMs are embedding these for Ecodesign compliance and energy efficiency verification.
- Healthcare Monitoring:FDA-cleared and CE-marked biometric sensors transmit continuous vital signs through HIPAA-aligned and GDPR-compliant infrastructure. US telehealth providers are integrating these into chronic disease management programs.
- Smart Home:Cost-optimized environmental and occupancy sensors connect through voice assistant ecosystems.
- Environmental Monitoring:Air quality and water purity sensors feed regulatory compliance dashboards for municipal utilities.
Industrial automation generates the largest revenue pool while healthcare monitoring climbs the fastest on regulatory tailwinds.
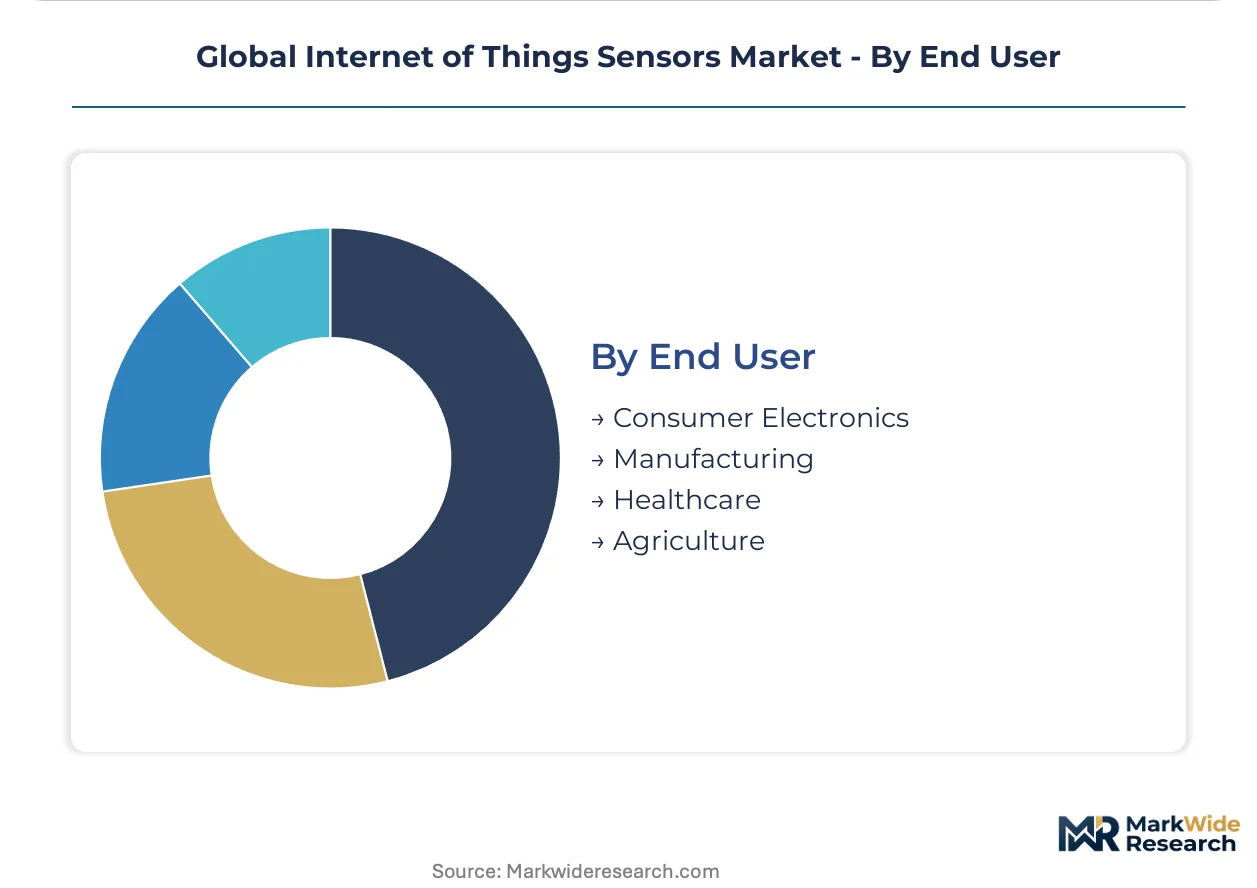
End User:
Supply concentration varies sharply between consolidated consumer electronics OEMs and fragmented agricultural cooperatives.
- Manufacturing:Discrete and process manufacturers deploy multi-sensor arrays for digital twin modeling and OEE optimization. Chinese facilities under GB standards and dual carbon goals are mandating predictive maintenance sensor rollouts.
- Consumer Electronics:Smartphone and wearable OEMs specify compact, low-power motion and environmental sensors with direct fab relationships. South Korean and Taiwanese contract manufacturers control procurement timing.
- Healthcare:Hospital systems and home care providers source FDA-cleared devices through GPO contracts.
- Agriculture:Large farming operations in Brazil and the US Midwest are shifting from component purchases to multi-year telemetry service subscriptions.
Manufacturing anchors procurement volume while agriculture shows the steepest expansion trajectory through service-model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips that of India by a factor reflecting FCC certification premiums and healthcare procurement concentration. Germany commands premium positioning through Ecodesign compliance mandates. China leverages GB standards and dual carbon goals to accelerate domestic sensor deployment at scale.
United States
FDA-cleared biometric sensors for remote patient monitoring dominate healthcare procurement, with telehealth providers integrating continuous physiological data streams. FCC certification timelines for multi-protocol platforms create entry barriers that sustain domestic premium positioning. Silicon Valley clusters anchor edge AI sensor development for automated quality inspection systems.
Germany
Automotive and steel manufacturing plants mandate predictive maintenance sensor deployments under Ecodesign regulations and energy efficiency verification requirements. ETSI harmonized standards streamline multi-country approval pathways for industrial automation vendors. Bavarian machinery OEMs embed hardened sensor nodes with SIL 2 safety certification for rotating equipment monitoring.
China
Heavy industrial facilities under national dual carbon goals are scaling predictive maintenance rollouts to optimize energy efficiency and reduce unplanned downtime. MIIT radio transmission approvals and GB standards compliance shape product development cycles for domestic manufacturers. Yangtze River Delta manufacturing clusters concentrate MEMS fabrication capacity for captive supply to consumer electronics OEMs.
India
Electronics manufacturing incentives under the PLI scheme attract sensor packaging and testing investments for export-oriented supply chain reconfiguration. BIS certification requirements and CEA regulations govern industrial automation sensor deployments in process manufacturing. Maharashtra and Gujarat industrial corridors witness contract manufacturing expansion for agricultural telemetry service providers.
Australia
Water-stressed agricultural regions deploy LoRaWAN-enabled soil moisture and microclimate sensors for irrigation automation systems. The country's national spectrum regulator manages sub-GHz allocation for rural telemetry networks spanning remote acreage. Queensland and New South Wales farming cooperatives pilot photovoltaic-thermal hybrid harvesters for maintenance-free environmental monitoring nodes.
Global Internet of Things Sensors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with MEMS fabrication scale and analog front-end portfolios. Market structure concentrates around vertically integrated European and Asian manufacturers holding captive wafer capacity, while fabless designers face second-source limitations during allocation cycles. Two strategic archetypes dominate: diversified semiconductor conglomerates with broad analog portfolios, and focused MEMS fabricators with direct OEM relationships. Competitive moves center on distributor consolidation across industrial automation channels and direct-to-installer distribution models bypassing traditional markups.
Within the diversified semiconductor tier, Texas Instruments and STMicroelectronics exemplify platform breadth through analog front-end and MEMS fabrication capabilities respectively. Bosch Sensortec GmbH anchors the focused motion-sensing specialist archetype with European manufacturing scale. These three occupy positions reflecting distinct competitive vectors: portfolio breadth against fabrication specialization against captive OEM relationships.
| Leading Market Players |
|---|
| Texas Instruments |
| TE Connectivity |
| STMicroelectronics |
| NXP Semiconductors |
| Honeywell International |
| Infineon Technologies |
| Analog Devices |
| Bosch Sensortec |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion amplifies cost differentials between captive MEMS foundry outputs and fabless alternatives, concentrating pricing power among vertically integrated manufacturers while forcing tiered pricing stratification across standard and configured-to-order sensor platforms.
Pricing Analysis
The customization-premium spread separates standard off-the-shelf motion sensors from configured-to-order industrial nodes with SIL 2 safety certification and IP67 environmental hardening. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with FDA-cleared biometric modules commanding substantial premiums over consumer-grade alternatives. Cost compression in consumer wearables is intensifying because South Korean and Taiwanese OEMs consolidate procurement around direct fab relationships. Agricultural cooperatives exhibit highest price sensitivity through multi-year telemetry service contracts, while German automotive plants demonstrate lowest sensitivity under Ecodesign compliance mandates.
Supply Chain Analysis
Silicon wafer feedstock draws from concentrated MEMS fabrication capacity in Germany, China, and Taiwan, with Bosch Sensortec and STMicroelectronics maintaining captive wafer supply. Raw material dependencies center on 200mm and 300mm silicon substrates, specialized MEMS process chemicals, and analog front-end semiconductor components. Single-source vulnerability pervades fabless designers lacking second-source options during capacity allocation cycles. Distribution runs through consolidating industrial automation channels and emerging direct-to-installer models for smart home environmental monitoring kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor hardware margins are compressing while telemetry-as-a-service contracts expand revenue velocity through recurring data-analytics subscriptions that outpace unit sales growth.
For Market Incumbents: Harden MEMS fabrication scale advantages through backward integration into specialized wafer supply and expand SIL 2 certification portfolios to defend against low-cost thermal imaging substitutes displacing proximity sensors in occupancy detection. Channel control represents the critical lever as distributor consolidation threatens mid-tier supplier access. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian PLI scheme contract manufacturing for agricultural telemetry exporters and EU AI Act-compliant edge AI sensor modules for automated quality inspection. The most penetrable segment spans direct-to-installer smart home environmental monitoring kits bypassing traditional industrial distributor markups. For Investors and Strategic Acquirers: FCC cybersecurity labeling mandates reshape the acquisition landscape by elevating compliance infrastructure value and penalizing retrofit liabilities. Long-term viability centers on platforms with embedded inference capabilities and multi-protocol firmware stacks. The signal to monitor involves spectrum allocation decisions affecting sub-GHz sensor platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Captive wafer supply at Bosch Sensortec and STMicroelectronics anchors European manufacturing scale against Asian competition. |
| Multi-Protocol Certification Investment | ETSI harmonized standards and FCC approval pathways compress time-to-market for industrial automation vendors. |
| Edge AI Module Development | GDPR-aligned data processing capabilities capture design wins in German automated quality inspection systems. |
| Direct-to-Installer Distribution | Bypassing traditional channel markups unlocks margin recovery in residential energy management retrofits. |
| Telemetry Service Contract Pivot | Brazilian and US Midwest agricultural cooperatives shift procurement from components to soil-to-cloud subscriptions. |
Study Parameters
Desk research of ETSI harmonized standards documentation, FCC equipment authorization databases, and EU Ecodesign implementing measures preceded structured interviews with MEMS fabrication engineers, industrial automation procurement directors, agricultural telemetry systems integrators, and healthcare GPO contracts managers. Primary fieldwork across the Yangtze River Delta, Bavarian machinery clusters, and Australian farming cooperatives combined with secondary validation through SEC semiconductor filings, MIIT radio transmission approval records, and customs trade data. Bottom-up sensor unit shipment estimates triangulated against top-down market value reconstructions.
The analytical framework held fixed GB standards compliance trajectories and dual carbon policy intensity across the projection horizon while varying LoRaWAN spectrum allocation decisions and FDA cybersecurity guidance evolution. Segmentation dimensions modeled include product architecture, connectivity protocol, application vertical, and end-user procurement concentration. CAGRs derived from regression analysis against industrial automation capital expenditure cycles and telehealth infrastructure deployment curves. Forecast inputs incorporated water-stressed agricultural acreage expansion rates and Ecodesign mandate enforcement timelines.
Sensitivities concentrate around silicon wafer capacity allocation shocks, FCC certification timeline extensions for multi-protocol platforms, and thermal imaging cost curves accelerating proximity sensor displacement. Cross-checking against IEA industrial energy efficiency investment benchmarks and USDA precision agriculture adoption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
China Sensors Market