
 Memory Chip Market | 2026-2036
Memory Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Chip Market Intelligence
ISO 26262 automotive functional safety qualification is collapsing the supplier base for mission-critical memory. Samsung Electronics leverages captive HBM and advanced DRAM geometries to sustain process leadership. SK hynix anchors the high-bandwidth memory segment through dedicated packaging investments. Micron Technology competes in the U.S. and Japan with differentiated EUV-based node transitions.
A memory chip is a semiconductor device fabricated from silicon wafers using photolithography, deposition, and etching processes to create arrays of transistors and capacitors that store digital bits through electrical charge states. Flash memory cells employ floating-gate or charge-trap architectures to retain data without power, serving as non-volatile storage in smartphones, enterprise SSDs, and automotive systems. DRAM continues to command the largest value pool due to AI server buildouts, while Flash dominates unit volume across consumer and industrial applications. SRAM occupies niche high-speed cache roles where latency tolerance approaches zero.
EPA emissions rules, the EU F-Gas Regulation, and China's MEE standards constrain fluorinated gas use in etching and cleaning processes, raising capital costs for new fabs and favoring incumbents with installed abatement infrastructure. REACH and RoHS compliance in Europe restricts hazardous substance content in packaged modules, filtering sub-scale assemblers from automotive supply chains. Stakeholders must weigh geographic diversification of wafer output against the capital intensity of meeting divergent regional environmental mandates.
Market Dynamics
AI server buildouts by cloud hyperscalers are compressing procurement cycles and concentrating demand for high-bandwidth memory, while tightening environmental regulations across Taiwan, South Korea, and the United States raise capital barriers for new fabrication capacity.
Growth Catalysts
- China's MEE standards:Domestic environmental enforcement is accelerating abatement technology adoption among Chinese fabs, creating captive demand for advanced process equipment and retrofit services.
- Automotive functional safety mandates:ISO 26262 qualification requirements are filtering sub-scale memory suppliers from mission-critical automotive supply chains, concentrating procurement among qualified vendors.
- HBM packaging investments:Dedicated 2.5D and 3D packaging capacity expansion in Taiwan and South Korea is enabling denser AI accelerator configurations that pull through advanced DRAM volumes.
Market Restraints
- Fluorinated gas supply constraints:EPA emissions rules and the EU F-Gas Regulation are restricting etching gas availability, raising input costs for EUV-based node transitions.
- Water-intensive process requirements:Advanced fabrication clusters in Taiwan and Arizona face hydrological limits that constrain greenfield expansion timelines.
- Charge-trap NAND scaling limits:Physical cell dimension constraints below 200-layer architectures are slowing cost-per-bit reduction curves in enterprise storage applications.
Strategic Opportunities
- India's semiconductor PLI scheme:Central government incentives for memory packaging and testing operations are attracting assembly investments that bypass wafer fabrication capital intensity.
- Edge AI inference deployment:Low-power SRAM and specialty DRAM configurations for autonomous systems are opening specification windows outside hyperscaler procurement channels.
- EU Green Deal alignment:REACH and RoHS compliance premiums are creating certification-based price stratification that rewards early abatement infrastructure deployment.
Industry Challenges
- EUV lithography technician scarcity:The specialized skill set for 13.5nm wavelength system maintenance is concentrating talent among incumbent equipment operators in the Netherlands and Taiwan.
- Automotive qualification timelines:AEC-Q100 stress testing and ISO 26262 documentation requirements extend product introduction cycles to 24-36 months, compressing revenue realization windows.
- Legacy DDR4 inventory absorption:Server OEM transition to DDR5 architectures is forcing write-down exposure for distributors holding previous-generation module stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Chip Market |
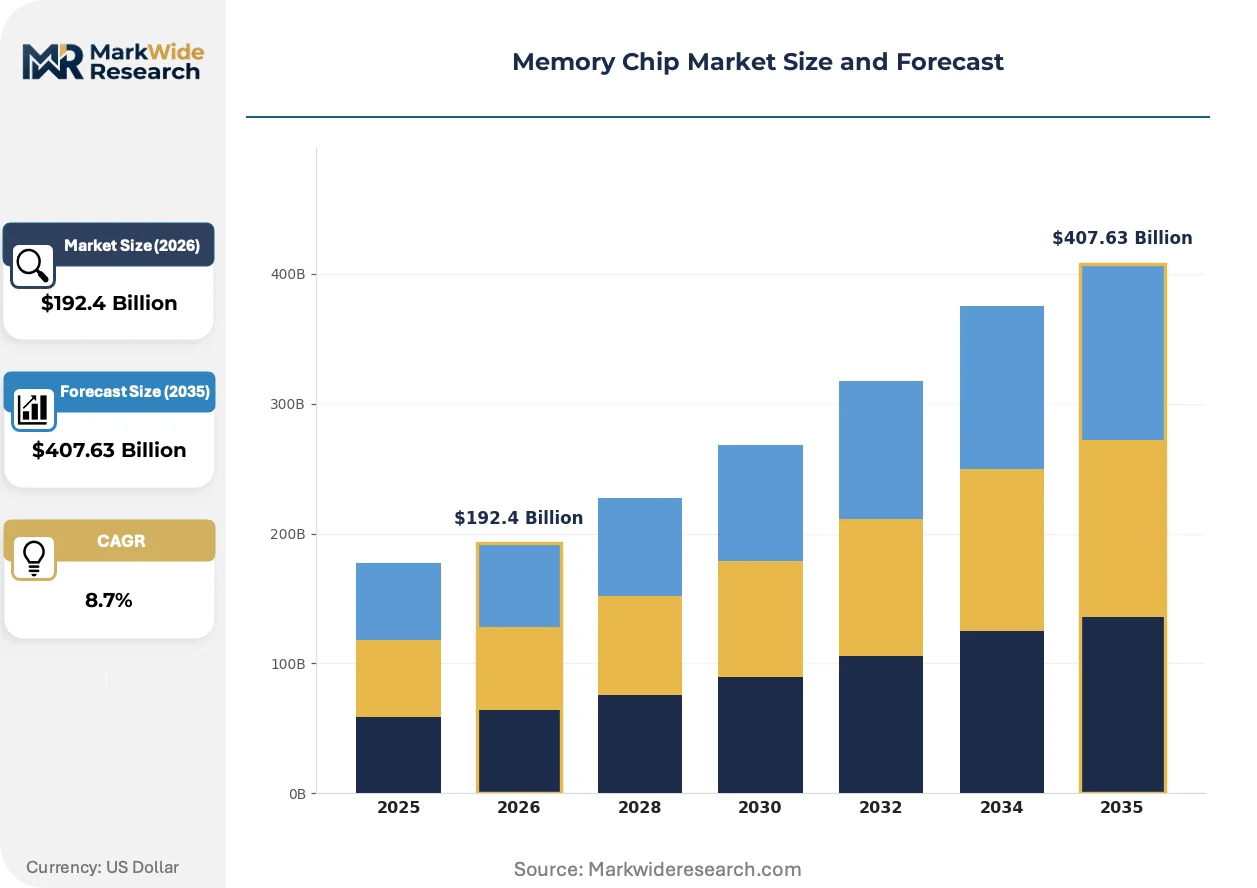
| Market Size in 2026 | $192.4 Billion |
| Market Size in 2035 | $407.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: DRAM, SRAM, Flash, EEPROM Application: Consumer Electronics, Computing, Automotive, Industrial Form Factor: DIMM, SO-DIMM, MCP, UFS End User: OEMs, Data Centers, Retailers, Distributors |
| Companies Covered | TSMC, Kioxia, SK hynix, Infineon Technologies, YMTC, Samsung Electronics, Intel Corporation, CXMT, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Chip Market Strategic Shifts & Innovations
Process geometry compression and packaging innovation are redefining competitive advantage in memory manufacturing, while regulatory emissions accounting and buyer procurement consolidation reshape value capture mechanisms.
Hybrid bonding technology is supplanting traditional microbump interconnects in high-bandwidth memory stacks. Cloud hyperscalers deploying NVIDIA and AMD AI accelerators are specifying hybrid-bonded HBM3E configurations for 2025 server ramps. This transition is compressing the supplier base to those with in-house wafer-to-wafer bonding capability, locking out fabless memory designers from the highest-margin AI attach markets.
The EU F-Gas Regulation is mandating phasedown schedules for hydrofluorocarbon etching gases used in 3D NAND string stacking. Memory manufacturers are responding with abatement system retrofits and process gas recycling investments that add 8-12% to cleanroom capital intensity. South Korean and Japanese fabs with installed fluorinated gas recovery infrastructure are absorbing compliance costs more efficiently than greenfield projects in the United States.
Hyperscale direct procurement is collapsing the traditional distributor channel for enterprise DRAM modules. Meta, Microsoft, and Google specifications now flow directly to Samsung, SK hynix, and Micron design teams, bypassing memory module integrators that previously captured value through configuration services. Taiwan-based ODM server builders report this disintermediation is most advanced in North American cloud infrastructure deployments, where procurement centralization has eliminated regional distributor tiers entirely.
Memory Chip Market Segmentation
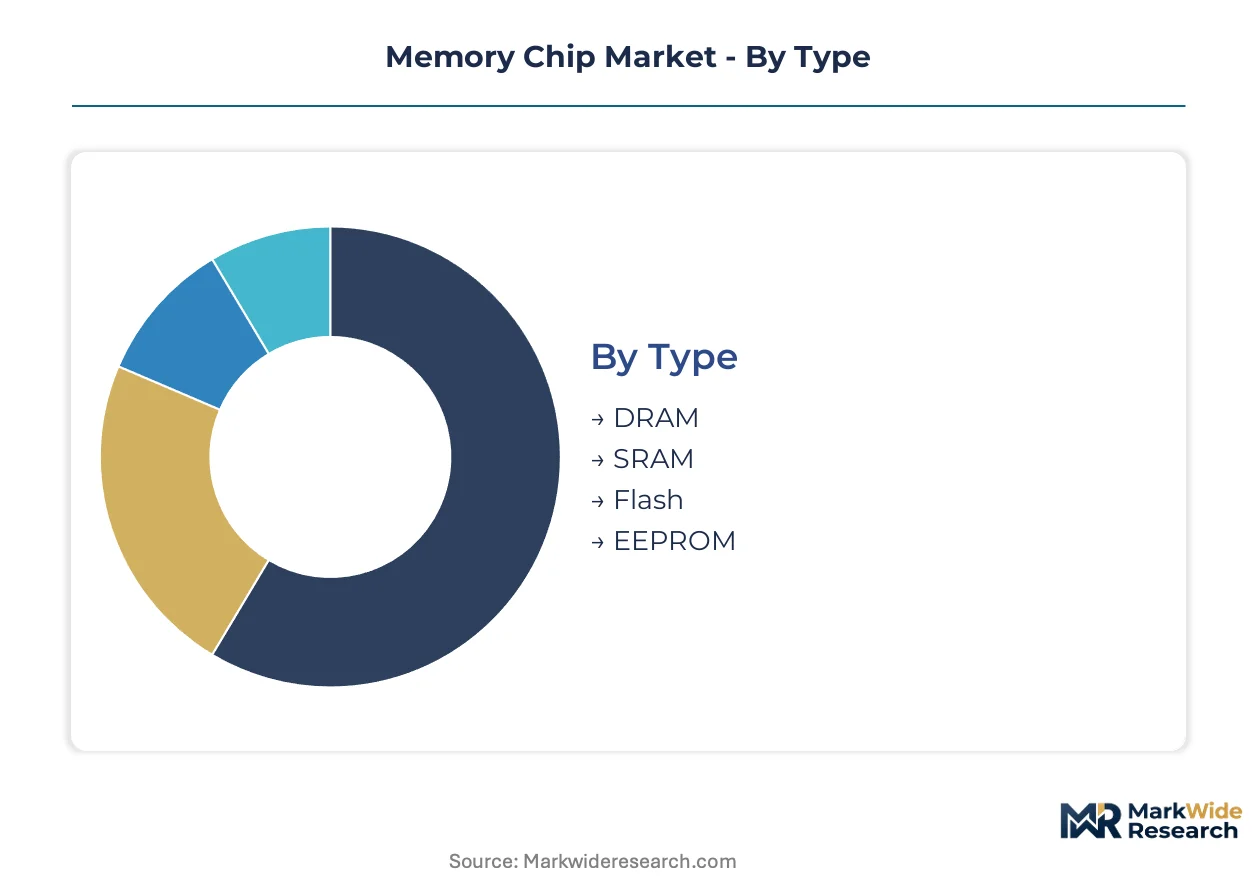
Memory chip segmentation reveals how architectural specialization and procurement channel fragmentation create distinct competitive arenas. Each dimension exposes different margin structures, qualification barriers, and geographic concentration patterns that determine vendor positioning.
Type:
DRAM and Flash dominate export-led volume flows to Taiwan and South Korea fabrication clusters, while SRAM and EEPROM serve more geographically dispersed specialty demand.
- DRAM:Charge-based volatile memory built from one-transistor-one-capacitor cells requiring constant refresh cycles. Cloud hyperscalers in the United States are compressing procurement cycles for high-bandwidth configurations, tightening supply allocation for server-grade modules.
- Flash:Non-volatile storage employing floating-gate or charge-trap architectures that retain data without power. Enterprise SSD deployments in Japan and Germany are absorbing TLC and QLC NAND output as datacenter storage tiers expand.
- SRAM:Six-transistor cell structures delivering sub-nanosecond access latency for cache hierarchies. Automotive ECU suppliers in Germany and Japan specify radiation-hardened variants for autonomous driving compute.
- EEPROM:Electrically erasable programmable memory with byte-level addressability for configuration storage. Industrial equipment OEMs across Italy and France utilize these chips for calibration data retention in harsh environments.
Flash holds the largest share; momentum sits with DRAM as AI server buildouts accelerate.
Application:
Cost tier stratification separates premium automotive qualification paths from high-volume consumer electronics procurement.
- Consumer Electronics:Smartphones, tablets, and wearables specifying LPDDR5X and UFS 4.0 interfaces. South Korean and Chinese handset OEMs dominate procurement, with BOM memory content rising as camera and AI processing demands intensify.
- Computing:Client PCs and enterprise servers driving DDR5 module transitions. Taiwanese and American server ODMs are consolidating direct supplier relationships, bypassing traditional distributor channels for volume procurement.
- Automotive:Mission-critical storage for ADAS and infotainment systems requiring ISO 26262 qualification. German and Japanese Tier-1 suppliers enforce AEC-Q100 compliance that filters sub-scale vendors from design wins.
- Industrial:Programmable logic controllers, robotics, and edge gateways demanding extended temperature ranges. Italian and Swiss automation OEMs specify industrial-grade Flash with decade-long supply guarantees.
Computing commands the largest value pool; automotive climbs fastest as electrification multiplies memory content per vehicle.
Form Factor:
Packaging density and thermal constraints determine which configurations ship to domestic versus export assembly operations.
- DIMM:Dual in-line memory modules with 64-bit data paths for desktop and server motherboards. American hyperscale datacenters specify registered DIMMs with on-die ECC for error correction at scale.
- SO-DIMM:Small-outline variants for space-constrained laptops and embedded systems. Japanese and Taiwanese notebook OEMs drive procurement for thin-and-light form factors.
- MCP:Multi-chip packages stacking DRAM and NAND with wire-bond or hybrid-bond interconnects. Smartphone designers in South Korea and China utilize these for PCB area optimization.
- UFS:Universal Flash Storage with serial interface replacing eMMC in high-end mobile devices. Flagship handset launches from Chinese and Vietnamese assembly lines specify UFS 4.0 for sequential read performance.
DIMM generates the highest revenue concentration; MCP expands most quickly as mobile packaging complexity increases.
End User:
Customer type dictates contract structure, with direct OEM relationships favoring long-term supply agreements versus spot-market distributor exposure.
- OEMs:Original equipment manufacturers integrating memory into finished systems. American and Taiwanese server OEMs negotiate quarterly pricing adjustments tied to DRAM spot indices.
- Data Centers:Hyperscale operators specifying custom module configurations. Meta, Microsoft, and Google procurement teams in the United States engage directly with Samsung, SK hynix, and Micron design engineers.
- Retailers:Consumer-facing channels for upgrade modules and storage devices. German and French electronics retailers stock DDR4 and DDR5 DIMMs for enthusiast PC builders.
- Distributors:Channel intermediaries holding inventory for smaller OEMs and industrial accounts. Arrow and Avnet operations across Europe and North America face margin compression as direct procurement expands.
Data centers capture the fastest volume expansion; distributors face structural displacement as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CHIPS Act disbursements and the EU F-Gas Regulation are redrawing capital flows across fabrication clusters. Taiwan, South Korea, and the United States absorb the majority of greenfield investment, while environmental compliance costs filter sub-scale entrants from advanced node competition.
United States
AI server deployments by Meta, Microsoft, and Google compress procurement cycles for high-bandwidth memory. EPA emissions rules constrain fluorinated gas use in etching processes, raising abatement capital requirements. The Arizona fabrication corridor faces hydrological limits that extend construction timelines for advanced DRAM facilities.
Taiwan
Hybrid bonding capacity expansion serves NVIDIA and AMD accelerator specifications for 2025 server ramps. The island's environmental regulator enforces wastewater discharge standards that add compliance layers to cleanroom operations. Hsinchu Science Park anchors wafer-to-wafer bonding infrastructure that locks in HBM3E supply allocation.
South Korea
Domestic hyperscaler Naver and Kakao Enterprise accelerate AI infrastructure buildouts, pulling through advanced DRAM volumes. K-environment ministry standards mandate fluorinated gas recovery systems that favor incumbents with installed abatement infrastructure. Yongin and Pyeongtaek clusters concentrate dedicated packaging investments for 2.5D and 3D memory stacks.
China
MEE standards accelerate domestic abatement technology adoption among fabs serving state-backed server OEMs. Dual carbon goals tighten manufacturing emissions benchmarks for 3D NAND string stacking operations. Yangtze Memory Technologies anchors charge-trap architecture production in Wuhan and Shanghai clusters despite equipment access constraints.
Japan
Automotive ECU suppliers in Nagoya and Tokyo specify radiation-hardened SRAM for autonomous driving compute. METI subsidies under the Semiconductor Revival Plan support legacy node memory production for industrial equipment. Hiroshima and Mie prefectures concentrate Kioxia and Western Digital joint venture output for enterprise SSD applications.
Memory Chip Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and technology access dimensions. The supplier base concentrates around three integrated fabricators controlling advanced node DRAM and NAND output, with state-affiliated challengers building captive capacity behind trade barriers. Strategic archetypes span captive HBM specialists, diversified memory-logic integrators, and China-focused domestic champions. Competitive moves center on hybrid bonding technology licensing and direct hyperscaler procurement relationships that disintermediate distributor channels.
Among diversified memory-logic integrators, Samsung Electronics and SK hynix occupy positions as process leaders with captive packaging capability. Taiwan-based TSMC represents the foundry archetype that enables fabless memory designers through advanced logic-node integration. American Micron Technology anchors the Western hemisphere supplier tier with EUV-based node transitions in Japan and domestic facilities. These three exemplify how geographic diversification of wafer output intersects with divergent regional environmental mandates.
| Leading Market Players |
|---|
| TSMC |
| Kioxia |
| SK hynix |
| Infineon Technologies |
| YMTC |
| Samsung Electronics |
| Intel Corporation |
| CXMT |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
ISO 26262 automotive functional safety qualification gates both supplier eligibility and price stratification simultaneously, filtering sub-scale vendors from mission-critical procurement while concentrating premium pricing power among qualified incumbents. REACH and RoHS compliance in Europe adds certification-based cost layers that reward early abatement infrastructure deployment with margin capture.
Pricing Analysis
Certification level creates the primary spread between automotive-grade modules and consumer DRAM, with AEC-Q100 compliance commanding substantial premiums over standard commercial specifications. Three-tier pricing structure across automotive-qualified, enterprise-grade, and consumer segments reflects qualification investment recovery timelines. Cost compression in DDR4 legacy inventory is intensifying because server OEMs accelerated DDR5 transitions. Hyperscale data center operators exhibit lowest price sensitivity due to direct procurement relationships, while industrial distributors face highest sensitivity from spot-market exposure.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced DRAM and HBM, while the United States concentrates EUV-based logic integration and packaging. Fluorinated etching gases, silicon wafers, and advanced photoresists constitute critical input dependencies. Single-source vulnerability concentrates in EUV lithography equipment where Dutch and Japanese suppliers control system availability. Distribution runs through direct OEM relationships for hyperscale volumes, with distributor channels surviving only in industrial and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The memory chip market sits in cyclical recovery driven by AI server buildouts compressing procurement cycles and absorbing excess inventory. Capital discipline among incumbent fabricators has tightened supply growth relative to demand expansion.
For Market Incumbents: Secure hybrid bonding capacity allocation through dedicated packaging investments in Taiwan and South Korea, locking HBM3E supply commitments before competitor ramps. Defend against Chinese state-backed challengers by accelerating EUV node transitions in Japan and domestic facilities, leveraging installed abatement infrastructure to absorb fluorinated gas compliance costs more efficiently than greenfield entrants.
For New Entrants and Emerging Players: Lead with India's semiconductor PLI scheme for memory packaging and testing operations, bypassing wafer fabrication capital intensity while capturing assembly value. Target edge AI inference deployment for autonomous systems, where low-power SRAM and specialty DRAM configurations open specification windows outside hyperscaler procurement channels dominated by incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed memory module integrators facing disintermediation from direct hyperscaler procurement. Long-term viability hinges on captive packaging technology or automotive qualification moats rather than commodity DRAM exposure. Watch hybrid bonding yield rates as the inflection indicator separating margin capture from capital destruction.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables HBM3E supply allocation for NVIDIA and AMD accelerator specifications. |
| Automotive Qualification Investment | Secures ISO 26262 compliance for ADAS memory procurement from German Tier-1 suppliers. |
| Fluorinated Gas Abatement Retrofit | Absorbs EU F-Gas Regulation compliance costs more efficiently than greenfield competitors. |
| Direct Hyperscaler Procurement | Bypasses distributor channels to capture value from Meta, Microsoft, and Google specifications. |
| Edge AI Memory Configuration | Opens specification windows for autonomous driving compute outside hyperscaler dominance. |
Research Approach
The analysis maps DRAM, Flash, SRAM, and EEPROM sub-sectors, each validated through semiconductor fabrication executives, memory procurement officers at hyperscale operators, automotive Tier-1 supplier engineers, and equipment vendor technical leads. Primary interviews combined with secondary validation from SEC 10-K filings, customs trade data, hyperscaler capex disclosures, and foundry utilization reports. Bottom-up wafer output estimates triangulate against top-down demand absorption models.
Consistency checks validated volume and value outputs against external benchmarks across the modeling period. Segmentation dimensions modeled include memory architecture type, application tier, form factor density, and end-user procurement channel. CAGRs derived from supply-demand balance equations incorporating fab capacity ramps, yield learning curves, and technology node transition timelines. Forecast inputs include AI server shipment trajectories and automotive electrification content multiplication.
The analysis sits within stated boundaries; outcomes outside sustained AI infrastructure investment or accelerated automotive qualification timelines would require recalibration. Forecasts reflect assumptions regarding fluorinated gas supply availability, EUV equipment delivery schedules, and hydrological constraints in Arizona and Taiwan fabrication corridors. Recalibration cycles align with material shifts in hyperscaler procurement patterns or regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
DDR SDRAM Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Mobile DRAM Market
Memory Chips
Japan DRAM Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Memristor Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
ECC Memory Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Memory IC Market