
 Ignition Interlock Devices Market | 2026-2036
Ignition Interlock Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ignition Interlock Devices Market Analysis
North American manufacturing capacity is reconfiguring around stricter state compliance timelines for ignition interlock programs. Intoxalock leverages its service center density to sustain installation coverage across rural and urban jurisdictions. Drägerwerk AG & Co. KGaA anchors European demand through precision fuel-cell sensor technology and regulatory certification depth. Smartstart Inc. competes on subscription pricing flexibility and real-time monitoring platform integration.
An ignition interlock device is a breathalyzer-linked vehicular control system that prevents engine start when blood alcohol concentration exceeds a pre-set threshold, typically calibrated between 0.02% and 0.04% BAC depending on jurisdictional mandate. Fuel cell technology dominates the sensor architecture due to its specificity for ethanol and operational stability across temperature extremes from -40°C to 85°C. Camera-enabled product types capture the fastest structural expansion as courts and fleet operators demand visual verification of the breath sample provider. Government agencies represent the most concentrated margin pool given their role as program administrators and bulk procurement authorities.
The National Highway Traffic Safety Administration (NHTSA) model specifications and state-level administrative codes shape device certification requirements and installation protocol standards across the United States. Canada's provincial regulators, including Ontario's Ministry of Transportation and British Columbia's Superintendent of Motor Vehicles, enforce comparable interlock mandates with distinct calibration and data reporting intervals. Stakeholders must monitor emerging state legislative sessions for mandatory interlock expansion to first-time offenders, a shift that would restructure addressable volume and service infrastructure requirements.
Market Dynamics
State legislative momentum toward mandatory interlock installation for first-time DUI offenders is compressing procurement timelines and forcing service infrastructure expansion across the United States. This regulatory pressure cascade is the dominant structural force reshaping device deployment volumes and vendor geographic coverage requirements.
Growth Catalysts
- NHTSA Model Specifications:Federal calibration standards harmonize device certification across state lines, reducing manufacturer compliance duplication and accelerating multi-state program entry.
- Commercial Fleet Mandates:FMCSA regulations and carrier insurance requirements are pulling ignition interlock adoption into long-haul trucking and logistics operations as a risk mitigation protocol.
- Fuel-Cell Sensor Maturation:Ethanol specificity and temperature stability improvements are extending device operational reliability into extreme climate zones previously served by less precise semiconductor alternatives.
Market Restraints
- Platinum Catalyst Cost Volatility:Fuel-cell electrodes depend on platinum group metals, exposing manufacturers to commodity price swings that compress hardware margins.
- Service Center Concentration:Installation and calibration capacity clusters in metropolitan corridors, creating coverage gaps in rural jurisdictions that limit program compliance rates.
- Semiconductor Sensor Substitution:Lower-cost metal oxide semiconductor alternatives threaten price-sensitive segments despite inferior ethanol specificity and cross-sensitivity to environmental contaminants.
Strategic Opportunities
- First-Offender Mandate Expansion:Legislative sessions in states currently restricting interlock orders to repeat offenders represent latent volume expansion requiring pre-positioned service infrastructure.
- Camera-Enabled Verification Convergence:Facial recognition integration with breath sample capture addresses court demands for identity confirmation, opening premium-tier product positioning.
- Direct-to-Fleet Subscription Channels:Bypassing traditional court-referral intermediaries through telematics platform partnerships enables recurring revenue capture from commercial vehicle operators.
Industry Challenges
- Certified Technician Pipeline:State-specific installer licensing requirements and calibration protocol training create bottlenecks that constrain service network scaling.
- Legacy Vehicle Electrical Integration:Pre-OBD-II and modified engine control systems demand custom wiring harnesses that complicate installation standardization and extend service times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ignition Interlock Devices Market |
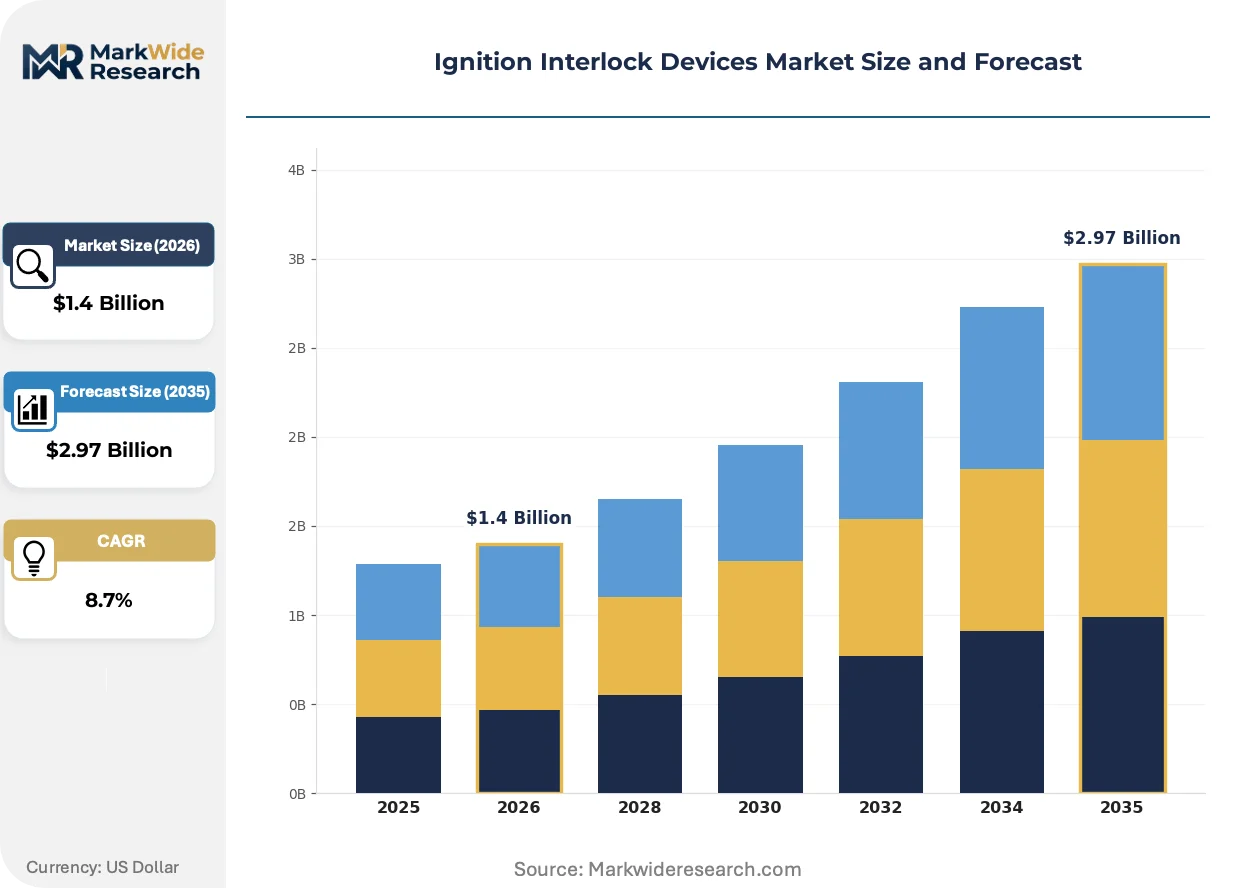
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive, Active, Camera-Enabled, Smartphone-Integrated End User: Individuals, Fleet Operators, Government Agencies, Non-Profit Organizations Technology: Fuel Cell, Semiconductor, Digital Signal Processing, Infrared Installation Type: Professional Installation, DIY, Mobile Services, Integrated Systems |
| Companies Covered | Intoxalock, Smartstart Inc., Lifesafer Inc., Guardian Interlock System Corp., Alcohol Countermeasure Systems (International) Inc., Drägerwerk AG & Co. KGaA, Alco Alert Interlock, Inc., Monitech LLC, Alcohol Detection Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ignition Interlock Devices Market Emerging Trajectories
Device architecture is pivoting from passive breath analysis toward active identity verification and real-time data transmission, transforming the interlock from a mechanical lockout mechanism into a connected compliance monitoring platform.
Camera-enabled interlock systems are rendering obsolete standalone breathalyzer units that lack visual confirmation of the test subject. State courts and fleet safety managers in California, Texas, and Florida are mandating photographic evidence alongside BAC readings. This dual-capture requirement is compressing demand toward integrated hardware platforms and marginalizing basic sensor-only configurations.
The NHTSA model specification updates are tightening data logging intervals and mandating standardized event code reporting across all certified devices. Manufacturers must reconfigure firmware architectures to capture rolling retest timing, engine start attempts, and tamper events with uniform granularity. California's Department of Motor Vehicles and Texas Department of Public Safety are aligning state administrative codes to these federal benchmarks, accelerating compliance-driven product refresh cycles.
Fleet procurement departments are consolidating vendor relationships through multi-year service agreements that bundle installation, calibration, and data analytics into per-vehicle monthly fees. This subscription compression is displacing transactional court-referral revenue models in the commercial segment. Long-haul trucking operators operating across state lines are driving this shift, prioritizing unified reporting dashboards over jurisdiction-specific device configurations.
Ignition Interlock Devices Market Segmentation
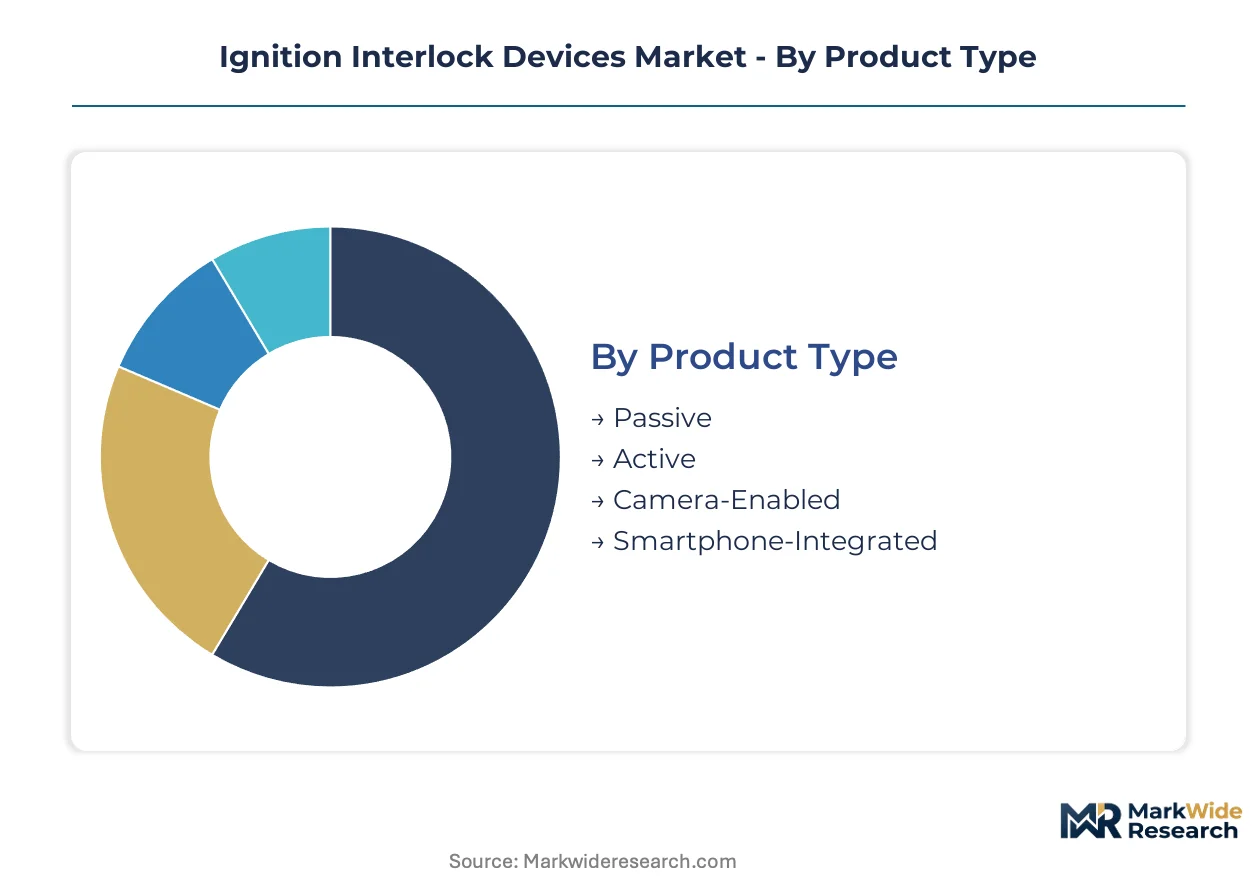
Ignition interlock device procurement patterns diverge sharply across enforcement contexts, with court-mandated installations following compliance-driven specifications while fleet operators prioritize telematics integration. Understanding these segment boundaries clarifies where hardware margins concentrate versus where service revenue dominates.
Product Type:
Cost tier stratification separates basic breathalyzer units from integrated verification platforms with recurring data fees.
- Camera-Enabled:Dual-capture systems embed facial recognition alongside ethanol detection, satisfying NHTSA model specifications for identity verification. California and Texas courts now mandate photographic evidence, pulling procurement toward premium hardware tiers with embedded imaging sensors and encrypted transmission protocols.
- Active:Breath sampling requires intentional user exhalation into a mouthpiece, delivering precise BAC quantification for high-stakes enforcement scenarios. Repeat-offender programs and commercial fleet mandates specify active architecture for its evidentiary reliability in administrative hearings.
- Passive:Ambient air sampling detects alcohol vapor without direct user interaction, suited for fleet safety protocols where driver cooperation cannot be assumed. Lower hardware costs position passive units for large-scale commercial deployment.
- Smartphone-Integrated:Bluetooth tethering to mobile applications enables remote calibration scheduling and real-time compliance alerts. Younger offender demographics and logistics operators with distributed fleets drive adoption of app-connected architectures.
Camera-Enabled holds installed capacity. Smartphone-Integrated is rotating up the share rankings.
End User:
Customer type determines procurement channel structure, with government intermediation creating long sales cycles but volume concentration.
- Government Agencies:State transportation departments and court administrative offices function as bulk procurement authorities, negotiating master service agreements that bundle installation, calibration, and data reporting. NHTSA certification requirements and state administrative codes shape vendor qualification criteria.
- Fleet Operators:Commercial carriers under FMCSA safety mandates deploy interlocks as risk mitigation infrastructure, bypassing court referral channels through direct vendor relationships. Long-haul trucking operations spanning multiple states prioritize unified reporting dashboards over jurisdiction-specific device configurations.
- Individuals:Court-referred DUI offenders constitute the historical demand base, with installation and monthly service fees typically self-funded. State-level first-offender mandate expansions would restructure volume distribution across user categories.
- Non-Profit Organizations:Substance abuse treatment providers and victim advocacy groups administer interlock scholarship programs for indigent offenders, representing a price-sensitive procurement channel with irregular volume.
Government Agencies anchor program architecture. Fleet Operators are climbing the fastest as commercial safety mandates tighten.
Technology:
Sensor maturity creates performance differentiation across temperature extremes and cross-sensitivity profiles.
- Fuel Cell:Electrochemical oxidation of ethanol at platinum-group catalyst electrodes delivers specificity unmatched by semiconductor alternatives, with operational stability from -40°C to 85°C. NHTSA model specifications and state certification protocols explicitly favor fuel-cell architecture for evidentiary-grade installations.
- Semiconductor:Metal oxide sensors measure resistance changes upon ethanol adsorption, offering lower hardware cost at the expense of cross-sensitivity to environmental contaminants. Price-sensitive fleet segments and developing market applications tolerate reduced specificity for capital expenditure reduction.
- Digital Signal Processing:Algorithmic filtering of sensor outputs reduces false-positive rates and enables predictive maintenance alerts. Firmware-upgradable platforms extend device service life across multi-year mandated installation periods.
- Infrared:Spectroscopic ethanol detection at specific absorption wavelengths provides non-contact measurement capability, emerging in research and development pipelines for next-generation passive monitoring systems.
Fuel Cell commands certification compliance. Semiconductor is gaining share fastest in cost-optimized commercial segments.
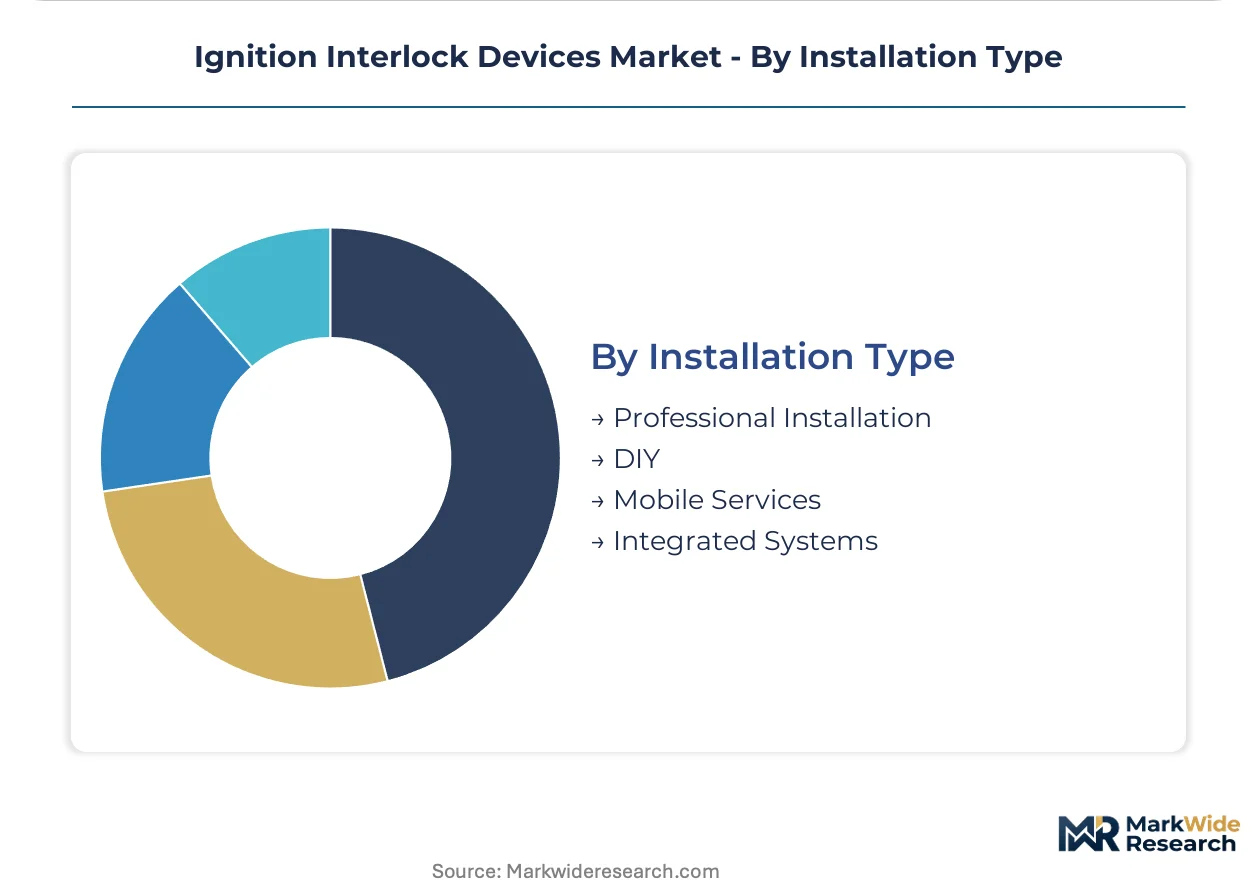
Installation Type:
Service delivery modality shapes geographic coverage economics and customer acquisition cost structures.
- Professional Installation:Certified technicians execute hardwired integration with vehicle electrical systems, mandatory for court-ordered devices under state licensing protocols. Metropolitan service center density determines vendor competitive position in high-volume jurisdictions.
- Mobile Services:Technician dispatch to customer locations addresses rural coverage gaps and fleet operator downtime constraints. Van-based calibration and installation units extend addressable market beyond fixed facility footprints.
- DIY:Plug-and-play devices targeting consumer vehicle segments face regulatory barriers in court-mandated applications but serve voluntary fleet safety programs with simplified deployment requirements.
- Integrated Systems:Factory-installed interlock architecture embedded during vehicle manufacturing remains nascent, with OEM partnerships exploring telematics platform convergence for commercial vehicle pre-installation.
Professional Installation holds certified technician capacity. Mobile Services is rotating up the share rankings as rural program expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System underwrites North American device deployment density, while European rail freight corridors and Asian port automation networks shape logistics safety mandates across distinct regulatory environments.
United States
State court systems and fleet operators drive procurement volume through NHTSA-certified fuel-cell platforms. The NHTSA model specifications harmonize calibration standards across jurisdictions, reducing manufacturer compliance burdens. Texas and California concentrate installation capacity, with metropolitan service centers handling bulk court-referral volumes and long-haul trucking compliance.
Canada
Provincial transportation ministries enforce interlock mandates through distinct calibration intervals and data reporting protocols. Health Canada and provincial regulators like Ontario's Ministry of Transportation certify devices for evidentiary use. Installation networks cluster along the Windsor-Quebec Corridor, serving Ontario's manufacturing belt and British Columbia's Pacific port logistics.
Germany
Commercial fleet safety regulations and KBA vehicle certification standards anchor European demand for precision sensor technology. The EU Green Deal's transport decarbonization targets intersect with logistics safety mandates. Industrial automation clusters in Baden-Württemberg and Bavaria host precision sensor manufacturing for automotive integration.
Australia
State-level road safety authorities administer mandatory interlock programs with TGA-aligned medical device oversight. Victoria and New South Wales transport departments specify fuel-cell architecture for court-ordered installations. Sydney and Melbourne service networks cover southeastern population centers, with mobile calibration units extending into Western Australia's mining logistics corridors.
United Kingdom
DVLA administrative frameworks and court sentencing guidelines structure device deployment for high-risk offenders. DVSA commercial vehicle enforcement pulls interlock adoption into fleet safety protocols. Installation capacity concentrates in Greater London and the Midlands, with Scottish and Welsh program expansions driving service network extension.
Ignition Interlock Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and calibration firmware. Market structure consolidates around vertically integrated service networks that bundle hardware, installation, and data reporting. Three archetypes dominate: court-program contractors with state-level certification depth, fleet-focused telematics integrators, and precision sensor technology suppliers. Competitive moves center on geographic service expansion and camera-enabled product tier launches.
Within the court-program contractor tier, Intoxalock and Smartstart Inc. represent established North American platform operators. Drägerwerk AG & Co. KGaA anchors European positioning through precision instrumentation heritage. These three exemplify how regulatory certification depth and service infrastructure density determine competitive viability across distinct jurisdictional frameworks.
| Leading Market Players |
|---|
| Intoxalock |
| Smartstart Inc. |
| Lifesafer Inc. |
| Guardian Interlock System Corp. |
| Alcohol Countermeasure Systems (International) Inc. |
| Drägerwerk AG & Co. KGaA |
| Alco Alert Interlock, Inc. |
| Monitech LLC |
| Alcohol Detection Systems |
| Others |
Supply Flow & Price Mechanics
Platinum group metal sourcing from South Africa and Russia concentrates upstream cost exposure for fuel-cell electrode manufacturers, pushing margin retention toward vertically integrated device producers with captive calibration service networks and state-level certification depth.
Pricing Analysis
NHTSA model specifications dictate the pricing tier structure across the ignition interlock device market. Three-tier pricing structure across premium, standard, and economy levels separates camera-enabled verification platforms from basic breathalyzer units and passive ambient sensors. Price differentiation hinges on certification grade for evidentiary admissibility and geographic delivery cost for rural service coverage. Cost compression in the semiconductor sensor tier is intensifying because fleet operators tolerate reduced ethanol specificity for capital expenditure reduction. Government agencies demonstrate lowest price sensitivity given their role as program administrators with bulk procurement authority, while non-profit scholarship programs represent the most price-sensitive channel.
Supply Chain Analysis
Platinum catalyst feedstock draws from South Africa, Russia, and Zimbabwe for fuel-cell electrode production. Sensor module manufacturing rests on precision electrochemical component fabrication in Germany and Japan, with final device assembly concentrating in Mexico and the United States to satisfy NHTSA certification proximity requirements. Single-source vulnerability sits with platinum group metal refining capacity concentrated in southern African mining corridors. Distribution runs through court-referral intermediaries for individual offender segments and direct telematics platform partnerships for fleet operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ignition interlock device market functions as a regulatory entrenchment story where state certification depth and service infrastructure density create switching costs that protect incumbent positioning across multi-year program cycles.
For Market Incumbents: Build certification moats through preemptive NHTSA model specification compliance investment ahead of federal updates. Deepen backward integration into fuel-cell sensor module production to offset platinum catalyst cost volatility. Anchor geographic coverage through mobile service fleet expansion into rural jurisdictions where competitor presence remains thin. Defend against semiconductor sensor substitution by emphasizing evidentiary reliability in court-mandated installations.
For New Entrants and Emerging Players: Establish a beachhead in the fleet operator segment where direct vendor relationships bypass entrenched court-referral channels controlled by incumbents. Target long-haul trucking operators with unified telematics dashboard offerings that span multiple state jurisdictions. Penetrate the smartphone-integrated product tier where app-connected architectures attract younger offender demographics and distributed logistics fleets. Pursue OEM partnerships for factory-installed interlock pre-integration in commercial vehicle manufacturing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed court-program contractors holding dense state-level service networks but limited technology differentiation. Long-term viability centers on camera-enabled product tier transition and fleet segment pivot away from transactional court-referral dependency. Acquisition targets should display certified technician pipeline depth and multi-state program administration relationships. Watch for state legislative sessions expanding first-offender mandates as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Camera-Enabled Product Launch | California and Texas courts now mandate photographic evidence alongside BAC readings. |
| Mobile Service Network Expansion | Van-based calibration units extend coverage into rural jurisdictions with compliance gaps. |
| Fleet Telematics Integration | FMCSA safety mandates pull interlock adoption into long-haul trucking risk mitigation protocols. |
| Fuel-Cell Sensor Backward Integration | Captive platinum catalyst sourcing buffers margin compression from commodity price volatility. |
| State Certification Pre-Positioning | NHTSA model specification alignment accelerates multi-state program entry and procurement access. |
Methodological Framework
A spread of perspectives from state program administrators, certified installation technicians, fleet safety managers, and fuel-cell sensor engineers converged on the working assumptions underpinning this analysis. Primary interviews with court administrative officers and commercial carrier compliance directors combined with secondary validation against NHTSA certification databases, state legislative session records, and FMCSA enforcement data. Bottom-up device deployment tracking across state-level programs triangulated with top-down market sizing from vendor service network disclosures.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, end-user procurement channel structure, sensor technology tier, and installation service delivery modality. CAGRs derived from rolling deployment velocity analysis against state mandate expansion scenarios. Forecast inputs incorporated platinum group metal price trajectory assumptions and certified technician pipeline scaling constraints.
Sensitivities concentrate around state legislative outcomes for first-offender mandate expansion and platinum catalyst commodity price volatility. Forecasts reflect documented assumptions regarding NHTSA specification update timing and fleet operator telematics platform adoption curves. Cross-checking against state transportation department procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market