
 Automotive Perimeter Lighting System Market | 2026-2036
Automotive Perimeter Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Perimeter Lighting System Market Intelligence
New production capacity for advanced lighting modules in Mexico and Poland is fragmenting the established Tier-1 supplier landscape. Magna International Inc. leverages its electronics integration capabilities to offer complete systems. HELLA GmbH & Co. KGaA competes on its deep specialization in lighting and sensor fusion. Meanwhile, Stanley Electric Co., Ltd. sustains its market position through strong relationships with Japanese automakers.
Automotive perimeter lighting systems are exterior illumination solutions that project light patterns onto the ground around a vehicle. These systems often utilize LED modules controlled by a central ECU to create a 'light carpet' for welcome animations, safety zones, or brand projection. Within applications, the Electric Vehicles segment shows the highest integration rates for these features as a key differentiator. OLED and Micro-LED technologies are gaining traction over traditional LEDs for their ability to create more dynamic and uniform light surfaces.
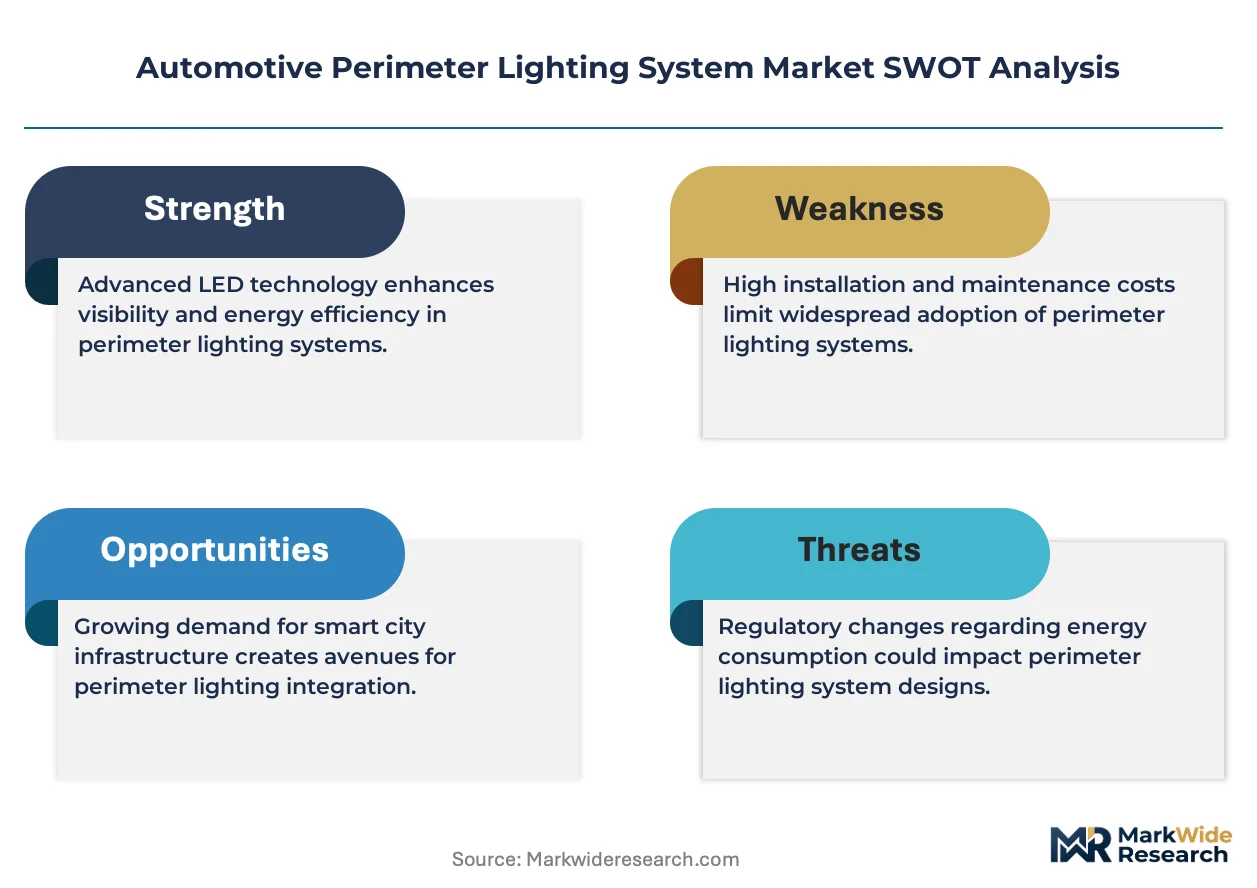
Regulatory frameworks like the EU's General Safety Regulation and China's GB standards influence design by setting minimum visibility requirements. Simultaneously, NHTSA regulations in the U.S. govern the legality of dynamic lighting projections, impacting market entry for new features. The strategic decision for suppliers centers on managing the bill of materials for advanced components while demonstrating clear value to OEMs.
Market Dynamics
The core dynamic shaping the automotive perimeter lighting market is the tension between rapid technological advancement in light projection and the slower, fragmented pace of global regulatory approval. This creates a landscape where engineering capabilities often outstrip what can be legally deployed on public roads.
Growth Catalysts
- ADAS Integration:The fusion of perimeter lighting with Advanced Driver-Assistance Systems (ADAS) sensors creates functional applications, such as highlighting detected pedestrians or indicating the vehicle's intended path, which enhances safety and drives OEM adoption.
- EV Segment Differentiation:Electric vehicle manufacturers utilize advanced perimeter lighting, including welcome carpets and brand projections, as a key visual and technological differentiator to attract consumers in a competitive market segment.
- Regulatory Mandates for Visibility:Frameworks like the EU's General Safety Regulation and China's GB standards are pushing for enhanced vehicle conspicuity, indirectly creating a pull for more advanced and effective exterior lighting systems to meet or exceed these requirements.
Market Restraints
- High Bill of Materials:The cost of advanced components such as Micro-LEDs, laser modules, and dedicated electronic control units (ECUs) significantly increases the overall system price, limiting adoption to premium vehicle trims and luxury segments.
- Regulatory Heterogeneity:Divergent regulations, particularly the stringent rules from the NHTSA in the U.S. governing the brightness and movement of ground projections, create compliance hurdles and slow the rollout of new, dynamic features across different regions.
- System Complexity and Integration:Integrating dynamic lighting systems with a vehicle's existing electrical architecture and software presents significant technical challenges, requiring specialized expertise and extensive validation, which can delay development cycles.
Strategic Opportunities
- Vehicle-to-Pedestrian (V2P) Communication:There is a significant opportunity to develop lighting systems that project standardized, intuitive symbols onto the road to communicate vehicle intent (e.g., yielding, autonomous motion) directly to pedestrians and cyclists.
- Commercial Vehicle Applications:Expansion into light and heavy commercial vehicles offers a new frontier, where projection systems can create safety zones for loading/unloading, display company branding, or guide forklift operations around the truck.
- Aftermarket and Customization:A developing opportunity exists in the automotive aftermarket for modular, programmable lighting kits that allow vehicle owners to customize welcome animations and projection patterns, tapping into the vehicle personalization trend.
Industry Challenges
- Software Integration Expertise Gap:A shortage of engineers skilled in both lighting hardware and the complex software required for dynamic animations and ADAS sensor fusion creates a critical talent bottleneck for suppliers and OEMs.
- Lack of Communication Standards:The absence of a universal standard for light-based vehicle-to-pedestrian communication leads to fragmented, OEM-specific solutions, hindering the development of a commonly understood visual language for road safety.
- Durability and Environmental Testing:Ensuring the long-term reliability of ground projection optics against road salt, water ingress, and abrasion from debris poses a significant engineering and material science challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Perimeter Lighting System Market |
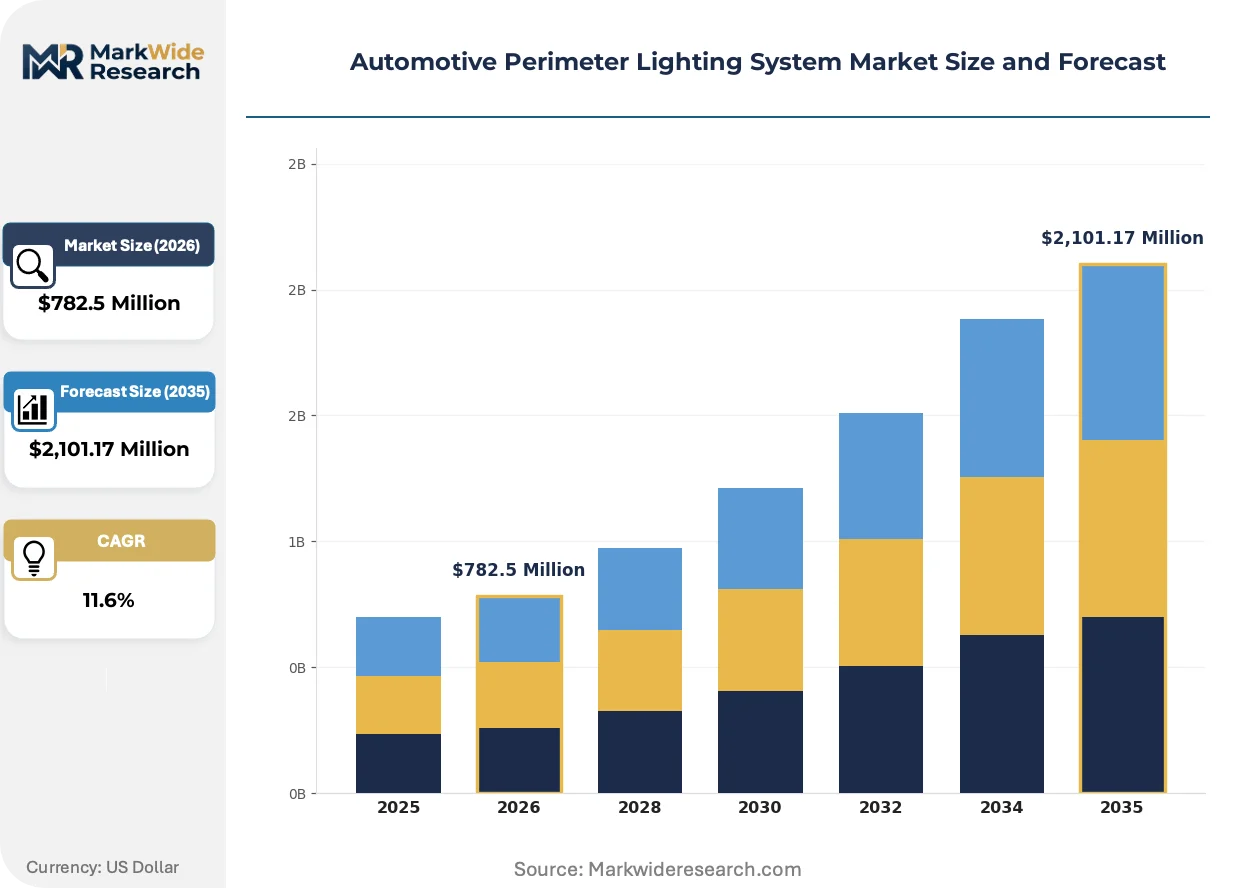
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $2,101.17 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Modules, Ambient Lighting Kits, Sensor-Integrated Lights, Fiber Optic Lighting, Electroluminescent Panels Technology: OLED, Laser Lighting, Micro-LED, Digital Light Processing, Organic Photovoltaics Application: Luxury Vehicles, Commercial Vehicles, Electric Vehicles, Recreational Vehicles, Autonomous Shuttles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Specialty Garages |
| Companies Covered | Magna International Inc., Marelli Holdings Co., Ltd., Gentex Corporation, OSRAM GmbH, Stanley Electric Co., Ltd., HELLA GmbH & Co. KGaA, Samvardhana Motherson Group, Varroc Engineering Limited, KOITO MANUFACTURING CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Perimeter Lighting System Market Strategic Shifts & Innovations
The functional role of exterior lighting is transforming from passive illumination to active communication. This evolution is driven by the convergence of solid-state lighting, embedded software, and vehicle sensor data, turning the vehicle's perimeter into a dynamic information interface.
OLED and Micro-LED technologies provide the ability to create highly uniform and segment-addressable light surfaces. Luxury automakers and electric vehicle startups are the primary adopters, seeking to leverage the technology for signature welcome animations and intricate signaling patterns. This advancement is collapsing the distinction between simple lighting hardware and complex digital displays on the vehicle exterior.
Updated GB standards in China are influencing global design roadmaps for adaptive lighting. These regulations set stringent performance criteria while also creating pathways for intelligent systems that can adjust beam patterns in real-time. Consequently, OEMs targeting the Chinese market are compelled to prioritize the development of matrix and digital light processing systems that meet these specific rules.
Automotive OEMs are altering their sourcing strategies for these complex systems. The procurement model is shifting away from buying discrete components toward sourcing complete, pre-validated perimeter lighting modules from Tier-1 suppliers with deep electronics integration capabilities. This trend is most pronounced in Germany and China, where speed-to-market for new EV models is a primary competitive driver.
Automotive Perimeter Lighting System Market Segmentation
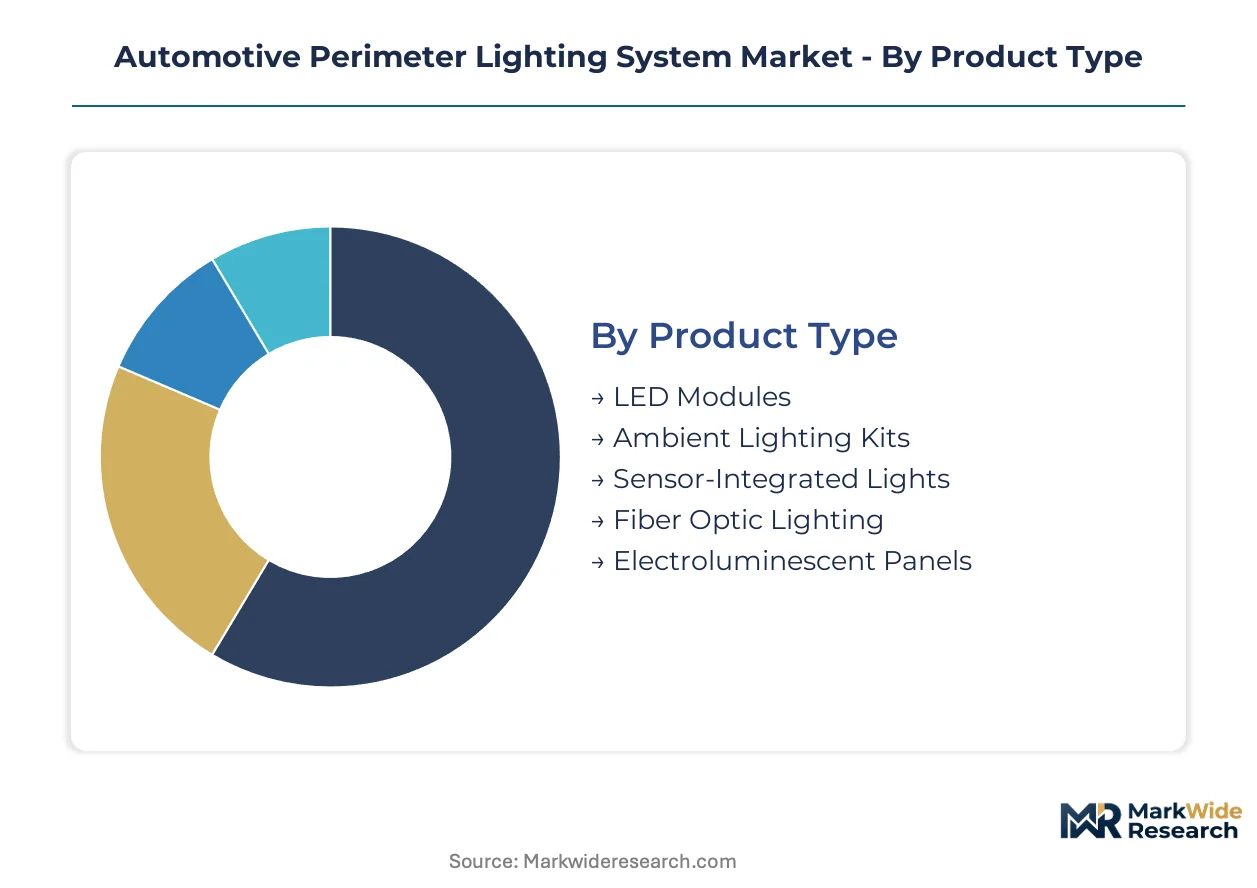
The automotive perimeter lighting system market exhibits distinct segmentation across product type, technology, application, and end-user categories. Understanding these segments is crucial for identifying areas of concentrated demand and technological leadership within the industry.
Product Type:
The product type segment spans from mature, established components to highly advanced, integrated systems. This spectrum reflects the varying levels of sophistication and functionality offered to vehicle manufacturers.
- LED Modules:These are foundational components for modern perimeter lighting systems, providing efficient and durable light sources. Demand for LED modules is concentrating in all vehicle segments, driven by their versatility and decreasing cost per lumen.
- Sensor-Integrated Lights:These systems combine illumination with proximity or environmental sensors, enabling dynamic responses to surroundings. Their demand concentrates within luxury and electric vehicle platforms, where ADAS integration enhances safety and user experience.
- Ambient Lighting Kits:These kits provide customizable interior and exterior accent lighting, primarily for aesthetic enhancement.
- Fiber Optic Lighting: Fiber optic solutions offer flexible light distribution for intricate design elements and uniform illumination.
- Electroluminescent Panels:These panels provide thin, flexible, and uniform light surfaces for specific design applications.
LED Modules retains volume leadership; Sensor-Integrated Lights holds the steepest expansion curve.
Technology:
The technology segment highlights the rapid innovation cycle, with new light sources offering enhanced dynamic capabilities and design freedom. These advancements allow for more complex light patterns and energy efficiency.
- Micro-LED:This technology delivers superior brightness, contrast, and pixel-level control, enabling highly dynamic and detailed light projections. Luxury and Electric Vehicle manufacturers are adopting Micro-LED for signature welcome animations and precise ground illumination.
- Digital Light Processing:DLP technology uses micro-mirror arrays to project high-resolution, adaptive light patterns, allowing for advanced safety warnings and communication. Demand is increasing in regions like China, where updated GB standards encourage intelligent adaptive lighting systems.
- OLED:Organic Light Emitting Diodes provide uniform, thin, and flexible light surfaces, ideal for integrated design elements.
- Laser Lighting:Laser technology offers highly focused and long-range illumination, primarily used for advanced headlight systems and specialized projections.
- Organic Photovoltaics:These emerging technologies focus on energy harvesting and flexible, transparent light sources.
New technologies are displacing traditional lighting solutions across premium vehicle segments.
Application:
The application segment categorizes where perimeter lighting systems are deployed, showing varying rates of adoption and specific feature requirements across vehicle types. Each application has distinct needs for aesthetics, safety, or functionality.
- Electric Vehicles:EVs integrate perimeter lighting extensively for brand identity, charging status indication, and enhanced pedestrian safety features. The competitive EV market segment drives high adoption rates for advanced lighting systems as a key differentiator.
- Luxury Vehicles:High-end models utilize sophisticated perimeter lighting for premium aesthetics, personalized welcome sequences, and exclusive brand projection. These vehicles often serve as early adopters for cutting-edge lighting technologies.
- Commercial Vehicles:This segment includes trucks and vans where perimeter lighting can enhance operational safety and visibility.
- Autonomous Shuttles:Future mobility solutions will rely on perimeter lighting for V2P communication and operational status signaling.
- Recreational Vehicles:RVs use perimeter lighting for campsite illumination, safety, and aesthetic enhancement.
Electric Vehicles and Luxury Vehicles lead the integration of advanced perimeter lighting systems.
End User:
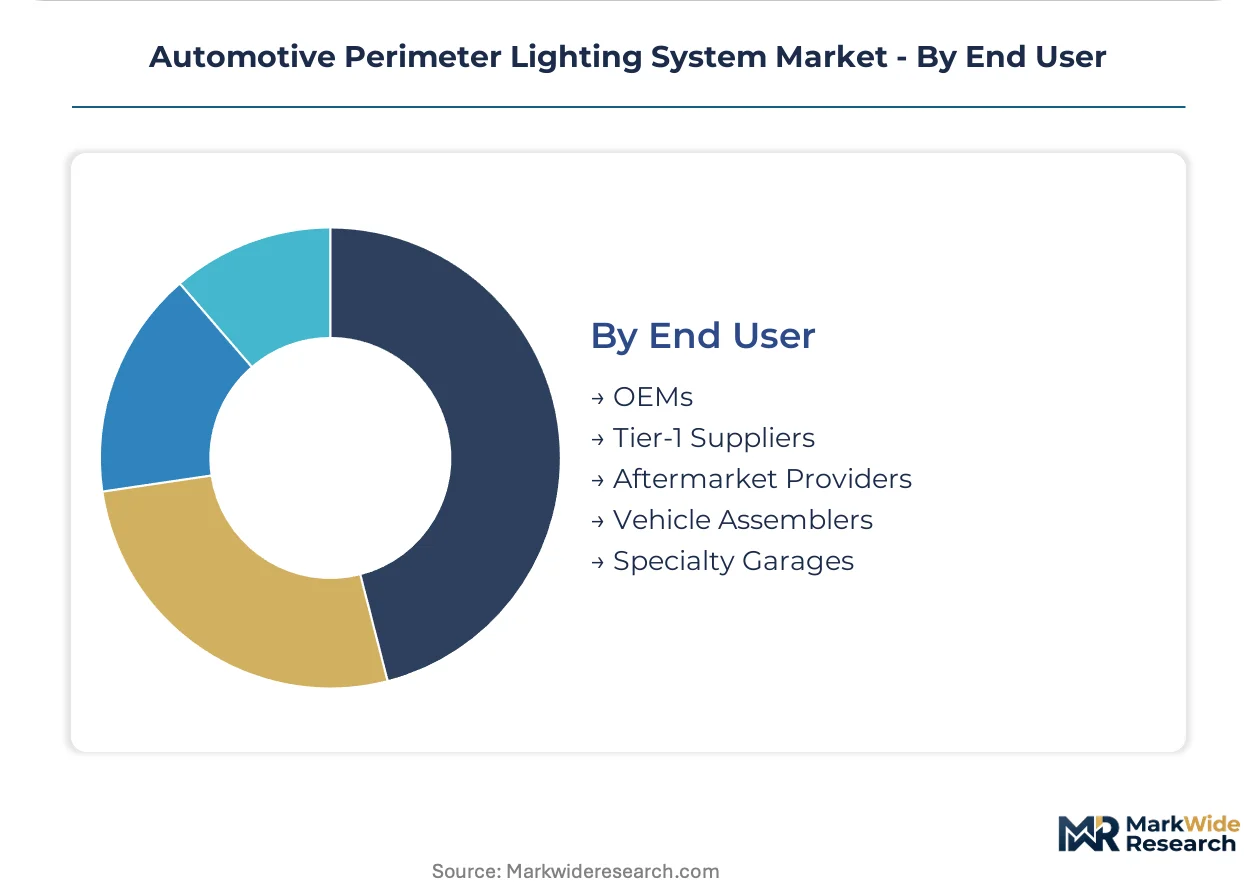
The end-user segment outlines the primary customers for perimeter lighting systems, reflecting the supply chain structure from manufacturing to aftermarket services. This segment reveals how different players engage with the technology.
- OEMs:Original Equipment Manufacturers integrate perimeter lighting systems directly into new vehicle designs during the production phase. OEMs specify advanced features and require robust, validated systems for their vehicle platforms.
- Tier-1 Suppliers:These companies develop and supply complete perimeter lighting modules and systems directly to OEMs, often incorporating electronics and software integration. Tier-1 suppliers are critical for delivering complex, pre-validated solutions to automotive production lines.
- Aftermarket Providers:These entities offer customization and upgrade options for existing vehicles, catering to personalization trends.
- Vehicle Assemblers:Assemblers integrate components from various suppliers into the final vehicle product.
- Specialty Garages:These independent workshops provide installation and maintenance services for lighting systems.
OEMs drive initial demand through new vehicle platforms, while Tier-1 Suppliers enable system integration and innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA regulations in the U.S. govern the legality of dynamic lighting projections, influencing market entry for new features in a key automotive market. Automotive production clusters in China and Germany are driving demand for perimeter lighting systems, particularly from luxury and electric vehicle manufacturers. New production capacities in Mexico and Poland are also reshaping the global supply landscape for advanced lighting modules.
China
Electric vehicle manufacturers extensively integrate perimeter lighting for brand identity and enhanced pedestrian safety features in China. Updated GB standards in China influence global design roadmaps for adaptive lighting systems. Automotive production clusters in Shanghai and Shenzhen are experiencing high demand, driven by domestic EV startups and luxury brands.
Germany
Luxury and electric vehicle manufacturers in Germany are primary adopters of advanced perimeter lighting systems for premium aesthetics. The EU's General Safety Regulation indirectly creates a pull for more advanced exterior lighting systems to meet enhanced conspicuity requirements. Automotive production hubs in Bavaria and Baden-Württemberg are centers for innovation and OEM sourcing of complex lighting modules.
United States
ADAS integration with perimeter lighting creates functional applications, such as highlighting detected pedestrians, enhancing safety for U.S. consumers. NHTSA regulations strictly govern the brightness and movement of ground projections, creating compliance hurdles for dynamic features. Automotive innovation centers in Michigan and California are focusing on developing V2P communication systems for future mobility solutions.
Mexico
New production capacity for advanced lighting modules in Mexico is fragmenting the established Tier-1 supplier landscape, serving North American OEMs. USMCA trade agreements influence the sourcing strategies of automotive manufacturers, encouraging regional supply chain integration. Automotive manufacturing hubs in Puebla and Saltillo are expanding their capabilities for advanced electronics and lighting component assembly.
Poland
Tier-1 suppliers are leveraging new production capacity in Poland to serve European automotive clusters with advanced lighting components. EU directives on vehicle safety and environmental standards are driving the adoption of energy-efficient and dynamic lighting solutions. Automotive component manufacturing zones around Wrocław and Katowice are becoming key nodes for specialized lighting module production.
Automotive Perimeter Lighting System Market Key Industry Players
Integrated system providers and specialized component manufacturers split the market for automotive perimeter lighting systems. The established Tier-1 supplier landscape is experiencing fragmentation due to new production capacity in emerging automotive regions. Electronics integration capabilities and deep specialization in lighting and sensor fusion represent key competitive moves among market participants.
Companies like Magna International Inc. exemplify integrated system provision, leveraging their electronics integration capabilities to offer complete perimeter lighting solutions to OEMs. HELLA GmbH & Co. KGaA represents deep specialization in lighting and sensor fusion, competing on its focused expertise in these critical areas. Stanley Electric Co., Ltd. sustains its market position through strong relationships with Japanese automakers, anchoring its presence in a significant automotive production base.
| Leading Market Players |
|---|
| Magna International Inc. |
| Marelli Holdings Co., Ltd. |
| Gentex Corporation |
| OSRAM GmbH |
| Stanley Electric Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Samvardhana Motherson Group |
| Varroc Engineering Limited |
| KOITO MANUFACTURING CO., LTD. |
| Others |
Cost & Logistics Intelligence
Advanced component manufacturing in Germany and China, alongside specialized Tier-1 suppliers, concentrates pricing power, influencing margin pools for premium vehicle OEMs. This upstream control shapes the cost structure for dynamic lighting systems.
Pricing Analysis
Geographic price spreads for automotive perimeter lighting systems reflect regional demand for advanced features. Pricing stratifies across premium, standard, and economy tiers based on technology sophistication and customization level. Cost compression in advanced component manufacturing is intensifying due to increasing competition among specialized suppliers. Luxury and Electric Vehicle OEMs exhibit the lowest price sensitivity for these differentiating features, while volume segments remain highly cost-conscious.
Supply Chain Analysis
Upstream feedstock for automotive perimeter lighting systems, particularly specialized LED chips and optical components, primarily sources from China and Germany. Manufacturing capacity for complete modules concentrates in Germany, Mexico, and Poland. The supply chain faces single-source vulnerability for highly specialized Micro-LED and DLP projection modules. Distribution runs through direct channels from Tier-1 suppliers to OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive perimeter lighting market faces a critical constraint in specialized engineering talent. A significant gap exists in expertise for integrating complex software with advanced lighting hardware.
For Market Incumbents:
Pre-empt fragmentation of the established Tier-1 supplier landscape by acquiring specialized software integration firms. Invest heavily in R&D for Micro-LED and DLP technologies to maintain a leadership position against emerging tech firms. Deepen electronics integration capabilities to offer OEMs complete, pre-validated modules. Secure key certifications for adaptive lighting systems to navigate diverse regulatory frameworks, particularly in the U.S. and China.
For New Entrants and Emerging Players:
Pursue niche opportunities in commercial vehicle applications where safety zones and operational communication are critical. Target the aftermarket segment with modular, programmable lighting kits that enable vehicle personalization. Develop standardized V2P communication systems for future autonomous shuttles, leveraging a clear safety value proposition. Focus on regions with less stringent dynamic lighting regulations to accelerate market entry.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across advanced lighting module production due to Micro-LED and DLP investments. The market demonstrates long-term viability, driven by EV differentiation and safety mandates. Target specialized software firms with expertise in ADAS integration or component manufacturers holding key optical patents. A signal to watch involves OEM procurement shifts towards complete, pre-validated perimeter lighting modules from Tier-1 suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire ADAS Software Specialists | This enhances electronics integration capabilities for dynamic safety features in premium vehicles. |
| Invest in Micro-LED/DLP R&D | This secures technological leadership for intricate welcome animations and advanced communication patterns. |
| Expand Production in Mexico/Poland | This optimizes regional supply chains for North American and European automotive production clusters. |
| Develop Standardized V2P Communication | This establishes a common visual language for pedestrian safety, driving wider OEM adoption. |
| Pursue Commercial Vehicle Applications | This unlocks new revenue streams by providing safety lighting for loading zones and operational guidance. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 R&D directors, and regulatory affairs specialists. Secondary validation utilized vehicle production databases, regulatory filings from NHTSA and China GB standards, and academic research on advanced lighting technologies. This approach combined bottom-up market sizing with top-down validation.
Demand-supply balance models informed the analytical framework across the projection horizon. Segmentation dimensions included product type, technology, application, end-user, and vehicle class. Compound annual growth rates were derived from historical adoption trends and future technology roadmaps. Key forecast inputs included electric vehicle production forecasts and Advanced Driver-Assistance Systems integration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology entrants or major OEMs would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and material cost trajectories. Cross-checking against vehicle production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market