
 Automotive Occupant Sensing System Market | 2026-2036
Automotive Occupant Sensing System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Occupant Sensing System Market Intelligence
Software-defined safety subscriptions is restructuring how automotive occupant sensing value gets captured, shifting one-time hardware sales toward recurring revenue tied to over-the-air feature activation. DENSO Corporation leverages its semiconductor fabrication depth to anchor sensor production in-house across Asian supply corridors. Joyson Safety Systems Co., Ltd. specializes in integrated seat modules that bundle pressure sensing with heating and ventilation. Autoliv, Inc. dominates frontal crash sensing while extending its portfolio into cabin monitoring through camera-based fusion architectures.
An automotive occupant sensing system comprises sensor arrays, signal processing units, and classification algorithms that detect human presence, position, and physical characteristics within vehicle compartments, typically operating through capacitive field distortion, pressure mapping, or millimeter-wave reflection with response latencies under 50 milliseconds for airbag deployment decisions. The system serves the primary commercial purpose of enabling intelligent restraint deployment and preventing child hot-car fatalities. Pressure sensor technology leads in unit volume due to its cost efficiency for seat-integrated applications, while radar and camera-based fusion represents the fastest-expanding margin pool as OEMs pursue cabin-wide monitoring without privacy-invasive optics. Control units concentrate value capture through embedded AI inference, whereas aftermarket providers face structural barriers from proprietary vehicle bus architectures and calibration requirements.
The National Highway Traffic Safety Administration and Euro NCAP shape demand through divergent testing protocols, with the former emphasizing frontal crash performance and the latter integrating child presence detection into safety ratings that influence OEM platform decisions. China's MIIT mandates GB-standard compliance for new energy vehicle cabin monitoring, creating separate certification pathways for domestic and export-oriented suppliers. ISO 26262 functional safety requirements and the EU AI Act's risk classification for biometric inference systems compound engineering complexity. Stakeholders must monitor how regulatory fragmentation between federal motor vehicle safety standards and regional consumer protection frameworks reshapes product architecture roadmaps and geographic market prioritization.
Market Dynamics
Software-defined safety architectures are restructuring value capture from one-time hardware sales toward recurring revenue streams tied to over-the-air feature activation, forcing tier-1 suppliers to rebuild business models around firmware monetization rather than component shipment volume.
Growth Catalysts
- Euro NCAP 2025 Protocol:Child presence detection mandates are accelerating capacitive and radar-based system integration across European OEM platforms, creating immediate retrofit demand for existing vehicle architectures.
- Pressure Sensor Cost Efficiency:Seat-integrated pressure mapping dominates unit volume for entry and mid-range vehicle segments, enabling mass-market penetration where optical systems remain prohibitively expensive.
- South Korea EV Premium Segment:Domestic OEMs are specifying cabin-wide occupant monitoring as standard equipment in electric SUV platforms, driving specification pull through Hyundai-Kia supply chains.
Market Restraints
- Semiconductor Input Volatility:Millimeter-wave radar chip supply concentrates among TSMC-fabricated RF-CMOS foundry capacity, exposing tier-1 suppliers to foundry allocation constraints and die cost inflation.
- ISO 26262 Certification Burden:ASIL-D functional safety requirements for airbag deployment decisions impose 18-24 month validation timelines that freeze architecture choices and delay platform updates.
- Capacitive Sensing Range Limitations:Field distortion methods fail to detect motionless occupants or discriminate between human and non-human objects at distances exceeding 50 centimeters, creating coverage gaps in full-cabin monitoring.
Strategic Opportunities
- India Passenger Vehicle Underpenetration:Mandatory frontal crash sensing remains absent from A-segment and B-segment domestic platforms, creating first-mover advantage for localized pressure sensor module production.
- Camera-Radar Sensor Fusion:Convergence of millimeter-wave reflectance with low-resolution infrared imaging enables privacy-compliant vital sign monitoring without visible-spectrum optics, opening health-adjacent service revenue streams.
- China MIIT GB-Standard Tailwind:New energy vehicle cabin monitoring mandates for driver attention and occupant detection are creating separate certification pathways that favor domestic suppliers with established MIIT relationships.
Industry Challenges
- Embedded AI Inference Talent Scarcity:Functional safety-qualified machine learning engineers capable of deploying quantized neural networks on automotive-grade MCUs command 40% salary premiums, constraining R&D velocity at mid-tier suppliers.
- Legacy CAN Bus Integration Friction:Proprietary vehicle network architectures from established OEMs resist standardized sensor data formats, forcing module suppliers to maintain customer-specific firmware branches that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Occupant Sensing System Market |
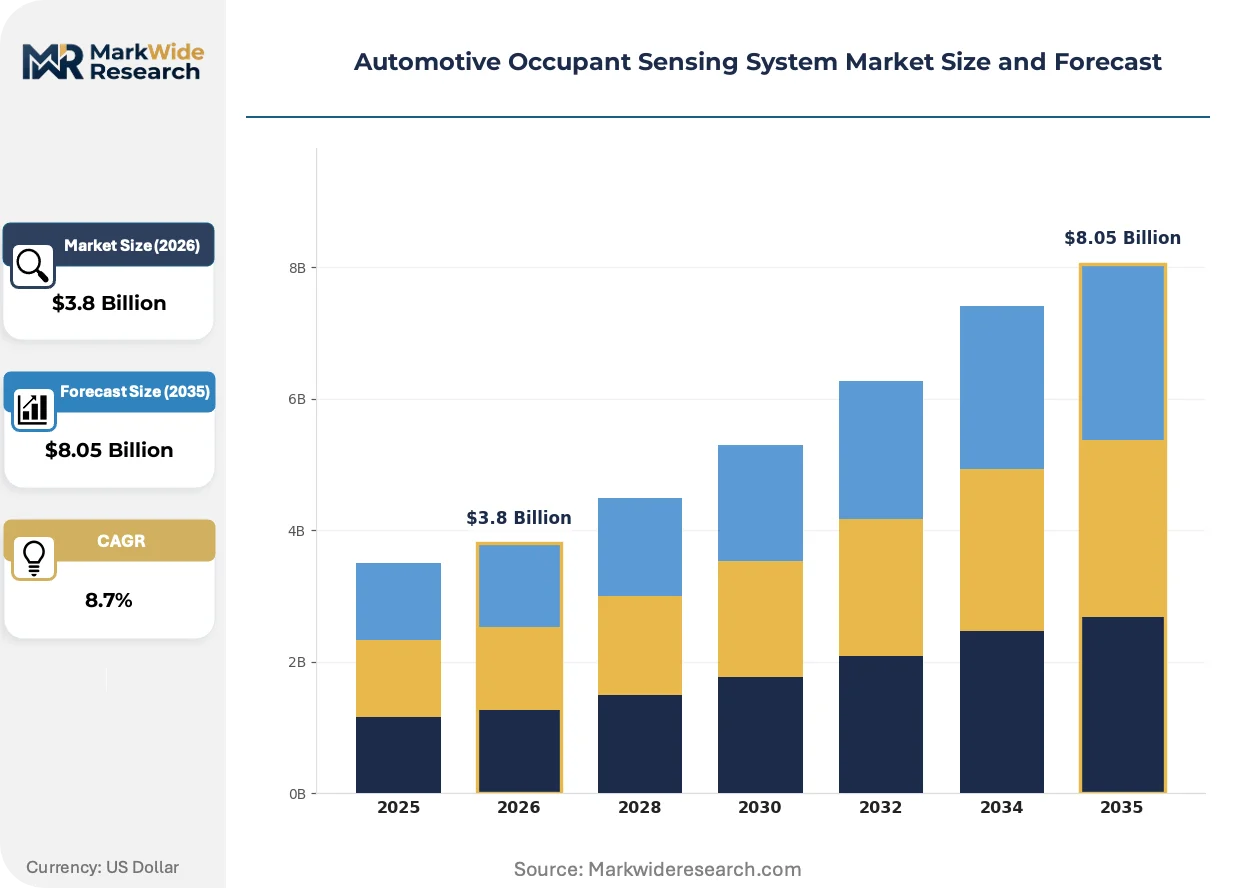
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Infrared, Pressure Sensor, Capacitive, Radar, Camera-Based Application: Child Detection, Seat Belt Reminder, Airbag Deployment, Occupant Classification, Theft Prevention Component: Sensors, Control Units, Actuators, Signal Processors, Power Supply End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | DENSO Corporation, Joyson Safety Systems Co., Ltd., Autoliv, Inc., Aptiv PLC, Lear Corporation, ZF Friedrichshafen AG, Magna International Inc., Hyundai Mobis Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Occupant Sensing System Market Strategic Shifts & Innovations
Millimeter-wave radar is modularizing into discrete functional blocks that separate RF front-end, signal processing, and classification layers, enabling tier-1 suppliers to source subsystems from specialized vendors rather than maintaining captive vertical integration.
Radar-on-chip architectures from NXP and Infineon are modularizing the traditional multi-component radar module into integrated packages that combine antenna arrays, transceivers, and digital signal processing on single substrates. Premium SUV and electric vehicle OEMs in Germany and Japan are adopting these consolidated designs at platform refresh cycles to reduce wiring harness complexity and assembly labor. This modularization is compressing the addressable market for discrete radar component specialists while expanding margin pools for system integrators capable of fusing radar with capacitive and pressure inputs.
The EU AI Act's risk classification framework for biometric inference systems is imposing conformity assessment requirements on camera-based occupant classification algorithms that process physical characteristics. Tier-1 suppliers must now maintain separate algorithm versions for European deployment versus other markets, fragmenting software development roadmaps and extending validation timelines. Child presence detection systems utilizing optical methods face the steepest compliance burden, accelerating OEM migration toward radar-capacitive fusion architectures that avoid biometric data classification entirely.
Fleet operators and mobility-as-a-service providers are unbundling occupant sensing hardware from vehicle purchase decisions, instead procuring sensing capability through telematics platform subscriptions that include over-the-air feature activation. This procurement compression is visible most acutely in United States commercial van and ride-hail vehicle segments, where Alphabet's Waymo and Amazon's Rivian fleets specify sensor-rich configurations with usage-based payment terms rather than upfront capital expenditure.
Automotive Occupant Sensing System Market Segmentation
Technology choices in occupant sensing determine cost position, functional safety rating, and regulatory compliance pathways. Application requirements diverge sharply between crash-responsive restraint systems and always-on cabin monitoring functions. Component architecture and supply chain configuration shape margin capture differently across mass-market and premium vehicle platforms.
Technology:
Volume applications favor mature field-distortion methods, while premium platforms pursue sensor fusion for cabin-wide coverage.
- Pressure Sensor:Seat-integrated force-sensitive resistors detect occupant mass distribution through conductive polymer deformation. Hyundai-Kia and Stellantis specify these modules for B-segment and C-segment platforms across South Korea, Italy, and Poland where unit cost constraints dominate specification decisions.
- Radar:Millimeter-wave systems operating at 60-79 GHz penetrate soft materials to detect motionless occupants and vital signs. German luxury OEMs and Japanese premium manufacturers specify radar-capacitive fusion for electric SUV architectures to satisfy Euro NCAP child presence mandates without optical privacy concerns.
- Ultrasonic:Time-of-flight acoustic ranging supports simple proximity detection in cost-constrained interior zones.
- Infrared:Thermal differential sensing enables low-light occupant localization without visible illumination.
- Capacitive:Electric field distortion methods provide contact-based presence confirmation with minimal calibration drift.
- Camera-Based:Low-resolution infrared imaging supports gesture recognition and driver monitoring where biometric classification is acceptable.
Today's leader: Pressure Sensor. Tomorrow's challenger: Radar.
Application:
Safety-critical functions command ASIL-D certification premiums; convenience features operate at lower functional safety grades.
- Airbag Deployment:Real-time occupant classification determines inflation force and suppression timing with sub-50-millisecond latency requirements. NHTSA FMVSS 208 compliance mandates dual-stage deployment logic for frontal crash protection across United States vehicle fleets.
- Child Detection:Always-on monitoring prevents hot-car fatalities through motion and breathing pattern recognition. Euro NCAP's 2025 protocol integration into safety ratings accelerates OEM adoption of multi-sensor architectures in European platforms.
- Seat Belt Reminder:Seat-integrated pressure sensing triggers audible and haptic warnings when occupied seats lack fastened restraints.
- Occupant Classification:Mass and position estimation enables adaptive restraint configuration for adult, child, and infant occupants.
- Theft Prevention:Interior motion detection triggers alarm systems through ultrasonic or radar-based intrusion sensing.
Airbag Deployment commands current revenue concentration. Child Detection is climbing the fastest as regulatory mandates expand.
Component:
Value capture concentrates in signal processing and embedded inference, not raw sensing elements.
- Sensors:Transducer elements convert physical occupancy parameters into electrical signals through piezoelectric, capacitive, or electromagnetic mechanisms.
- Control Units:ASIL-D qualified microcontrollers execute classification algorithms with hardware-enforced redundancy for airbag deployment decisions.
- Signal Processors:Digital filtering and noise cancellation circuits extract valid occupant signatures from cluttered cabin environments.
- Actuators:Electromechanical interfaces trigger restraint deployment or HVAC adjustments based on classification outputs.
- Power Supply:Automotive-grade voltage regulation ensures continuous operation across engine start-stop cycles and transient load conditions.
Control Units extract premium margins through functional safety qualification. Signal Processors are gaining share fastest as AI inference migrates toward edge architectures.
End User:
Procurement authority determines specification complexity, validation burden, and payment terms.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and General Motors maintain direct relationships with sensor specialists for platform-defining architectures.
- Tier-1 Suppliers:Autoliv, DENSO, and Joyson Safety Systems integrate multi-sensor modules into seat and restraint systems for OEM assembly.
- Vehicle Assemblers:Contract manufacturers in emerging markets source pre-validated occupant sensing kits through tier-1 distribution channels.
- Aftermarket Providers:Independent service networks face calibration and bus architecture barriers that limit addressable scope to simple seat-belt reminder retrofits.
Tier-1 Suppliers dominate current volume. OEMs are consolidating specification authority through software-defined safety platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting production toward jurisdictions where Euro NCAP compliance costs less than the safety rating premiums they unlock. Module suppliers are relocating final assembly to Poland and Mexico while retaining sensor fabrication in Germany and Japan.
United States
NHTSA FMVSS 208 mandates dual-stage airbag deployment logic for frontal crash protection across domestic vehicle fleets. The Inflation Reduction Act's domestic content incentives accelerate reshoring of control unit assembly to Michigan and Tennessee. Detroit-based tier-1 suppliers are expanding pressure sensor module capacity to serve GM and Ford platform refreshes.
Germany
Volkswagen Group and BMW specify radar-capacitive fusion architectures for electric SUV platforms to satisfy Euro NCAP 2025 child presence mandates. KBA type-approval requirements enforce ISO 26262 ASIL-D validation for restraint deployment systems. Bavarian semiconductor fabs anchor millimeter-wave radar chip supply for Continental and ZF Friedrichshafen integration lines.
China
MIIT GB-standard compliance for new energy vehicle cabin monitoring creates separate certification pathways favoring domestic suppliers. BYD and NIO specify occupant classification systems as standard equipment across premium EV segments. Yangtze River Delta sensor module clusters in Shanghai and Suzhou supply both local OEMs and export-oriented joint ventures.
Japan
Toyota Motor Corporation and Honda Motor Co. integrate multi-sensor seat modules through keiretsu supply relationships with DENSO and Aisin. METI carbon neutrality roadmaps accelerate radar-based systems that eliminate power-hungry optical components. Nagoya-area manufacturing corridors concentrate pressure sensor fabrication for hybrid vehicle platforms.
South Korea
Hyundai-Kia mandates cabin-wide occupant monitoring as standard in electric SUV architectures. MFDS automotive safety guidelines align with Euro NCAP protocols, easing export certification for domestic suppliers. Gyeonggi Province assembly plants source integrated seat modules from Hyundai Mobis captive production.
Automotive Occupant Sensing System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with tier-1 integrators commanding premium pricing for ASIL-D qualified systems while commodity module assemblers compete on unit cost for B-segment platforms. The market structures around three strategic archetypes: semiconductor-forward suppliers with captive fabrication, seat-integrated system specialists, and diversified safety conglomerates with airbag heritage. Consolidation pressure is intensifying through strategic partnerships for radar-on-chip sourcing and geographic expansion into underpenetrated Indian and Southeast Asian vehicle assembly corridors.
Among Japanese and German industrial conglomerates, DENSO Corporation and ZF Friedrichshafen AG exemplify the semiconductor-forward archetype with in-house sensor fabrication depth. Autoliv, Inc. occupies a distinct position as a safety-system pure-play with established frontal crash sensing credentials. These three anchors illustrate how competitive positioning diverges between fabrication-integrated and integration-focused business models.
| Leading Market Players |
|---|
| DENSO Corporation |
| Joyson Safety Systems Co., Ltd. |
| Autoliv, Inc. |
| Aptiv PLC |
| Lear Corporation |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Hyundai Mobis Co., Ltd. |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Tier-1 OEM procurement concentration in Germany and Japan anchors contract-based long-term offtake agreements for ASIL-D qualified modules, while spot-market pressure from Chinese EV assemblers is fragmenting pricing power across mid-tier sensor suppliers.
Pricing Analysis
Capacity additions in Poland and Mexico are reshaping price floors for pressure sensor modules serving European and North American assembly plants. Three-tier pricing structure across premium radar-fusion, standard capacitive-pressure integration, and economy ultrasonic-only levels reflects ASIL certification burden and volume scale. Cost compression in entry-level seat-integrated systems is intensifying because Chinese domestic suppliers are bypassing tier-1 integration margins through direct OEM relationships. Fleet operators exhibit highest price sensitivity due to procurement compression toward telematics subscriptions, while German luxury OEMs remain least sensitive given platform-standardization premiums.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates concentrate sensor fabrication in Germany, Japan, and Taiwan where captive semiconductor fabs and automotive-grade foundry partnerships predominate. Raw material dependencies span RF-CMOS silicon wafers, conductive polymer substrates for pressure sensing, and rare-earth elements for radar magnetics. Single-source vulnerability in TSMC-fabricated millimeter-wave radar chips exposes tier-1 suppliers to foundry allocation constraints during automotive semiconductor demand cycles. Distribution runs through tier-1 integrator assembly lines in supplier parks adjacent to OEM vehicle plants, with aftermarket channels structurally limited by proprietary CAN bus architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Euro NCAP child presence mandates and NHTSA frontal crash protocols creates geographic-arbitrage opportunities, as compliance cost differentials favor module production in Poland for European export while Michigan assembly serves domestic content incentives.
For Market Incumbents: To counter radar-on-chip modularization from NXP and Infineon compressing discrete component margins, Autoliv and DENSO should deepen backward integration into captive semiconductor fabrication while expanding certification engineering capacity in Germany to accelerate ASIL-D validation timelines. Control over RF-CMOS foundry allocation represents the critical defensive lever against fabless entrants. For New Entrants and Emerging Players: Begin with India's A-segment and B-segment passenger vehicle platforms where mandatory frontal crash sensing remains absent from domestic specifications, creating first-mover advantage for localized pressure sensor module production. A direct OEM partnership strategy bypassing tier-1 integration channels accelerates market access where established supplier relationships have not yet consolidated. For Investors and Strategic Acquirers: Semiconductor-forward tier-1 suppliers are the most active acquirer in this space, targeting specialized radar signal processing firms and AI inference startups to consolidate sensor fusion capabilities. Long-term viability over the next decade hinges on software-defined safety platform control rather than hardware shipment volume. The inflection signal to monitor is OEM consolidation of specification authority away from tier-1 integrators toward direct sensor specialist relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-on-Chip Integration | NXP and Infineon consolidated designs reduce wiring harness complexity for German electric SUV platforms. |
| Software-Defined Safety Platform | Over-the-air feature activation shifts revenue from hardware sales toward recurring firmware monetization streams. |
| ASIL-D Certification Acceleration | Investment in functional safety engineering capacity compresses 18-24 month validation timelines for airbag deployment systems. |
| Geographic Manufacturing Footprint | Poland and Mexico final assembly locations exploit regulatory arbitrage between Euro NCAP and NHTSA compliance costs. |
| Sensor Fusion Architecture | Radar-capacitive integration enables Euro NCAP child presence detection without EU AI Act biometric classification burden. |
Research Approach
Multiple input streams — structured interviews with tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distributors; secondary validation against vehicle production databases, IHS Markit registration data, and SEC filings from DENSO, Autoliv, and Aptiv; and technical literature from ISO 26262 working groups — were reconciled through bottom-up unit-volume modeling and top-down market sizing triangulation.
Historical shipment patterns across vehicle class, propulsion architecture, content per vehicle, and regional production cluster were cross-referenced against expert panel assessments of Euro NCAP 2025 protocol adoption timelines and MIIT GB-standard implementation trajectories. CAGRs across the analysis window were derived from segmented growth rate differentials weighted by platform refresh cycles and regulatory mandate effective dates, with sensor technology substitution curves and semiconductor supply constraints incorporated as boundary conditions.
Several conditions sit outside the modeled scope, including potential NHTSA rulemaking extending child presence detection to United States fleets, abrupt TSMC foundry allocation disruptions affecting radar chip supply, and OEM vertical integration into captive sensor fabrication. Forecasts reflect assumptions regarding regulatory implementation timelines and semiconductor supply normalization. A model refresh is warranted upon material change in Euro NCAP testing protocol adoption rates or MIIT enforcement intensity for new energy vehicle cabin monitoring mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market