
 Driving Armor Market | 2026-2036
Driving Armor Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Armor Market Foresight
Buyer concentration among government defense and security agencies is realigning competitive priorities across the driving armor landscape. Dainese leverages its motorsport heritage to navigate adjacent tactical mobility segments. DuPont anchors the upstream material layer through Kevlar fiber dominance, while Alpinestars competes on integrated protection systems for high-speed vehicle operations. Honeywell International sustains its position through Spectra polyethylene fiber technology leadership.
Driving armor encompasses protective garments and equipment engineered to mitigate ballistic, fragmentation, and blunt-force trauma for personnel operating within or around motorized vehicles, typically incorporating aramid fibers, ultra-high-molecular-weight polyethylene, or ceramic composite plates rated against specific threat levels. The product type dimension shows bulletproof vests commanding the largest installed base while tactical gear captures expanding share among private security contractors. Ceramic material formulations lead in military threat-level applications, whereas polyethylene plates displace steel across law enforcement channels due to weight advantages.
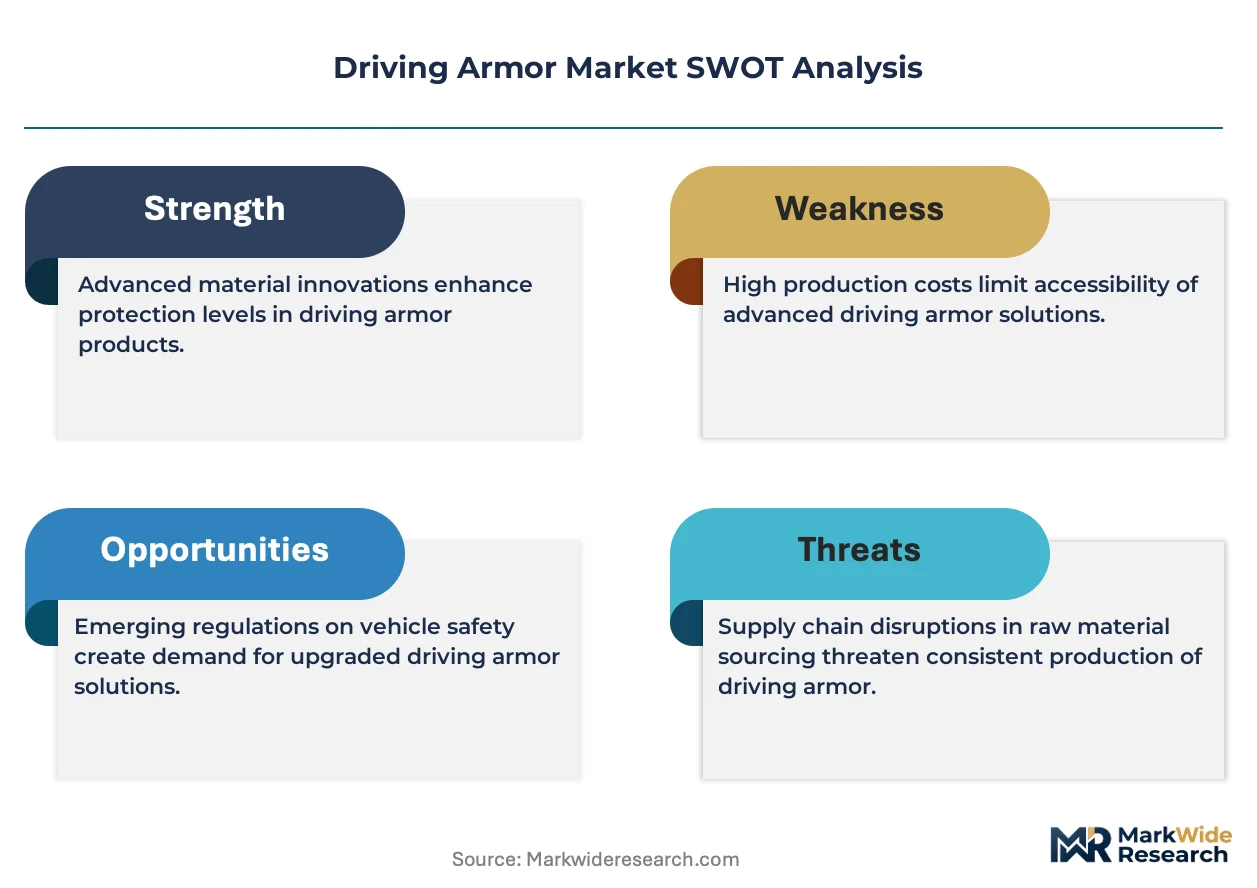
The National Institute of Justice sets ballistic resistance standards in the United States, while NATO STANAG protocols shape cross-border military procurement specifications, and the European Union's CE marking framework governs commercial protective equipment distribution across member states. These regulatory layers create tiered compliance barriers that favor established testing relationships and certified manufacturing footprints. Stakeholders must monitor evolving NIJ .07 standard implementation timelines and dual-use export control classifications that could restrict material flows to allied security forces.
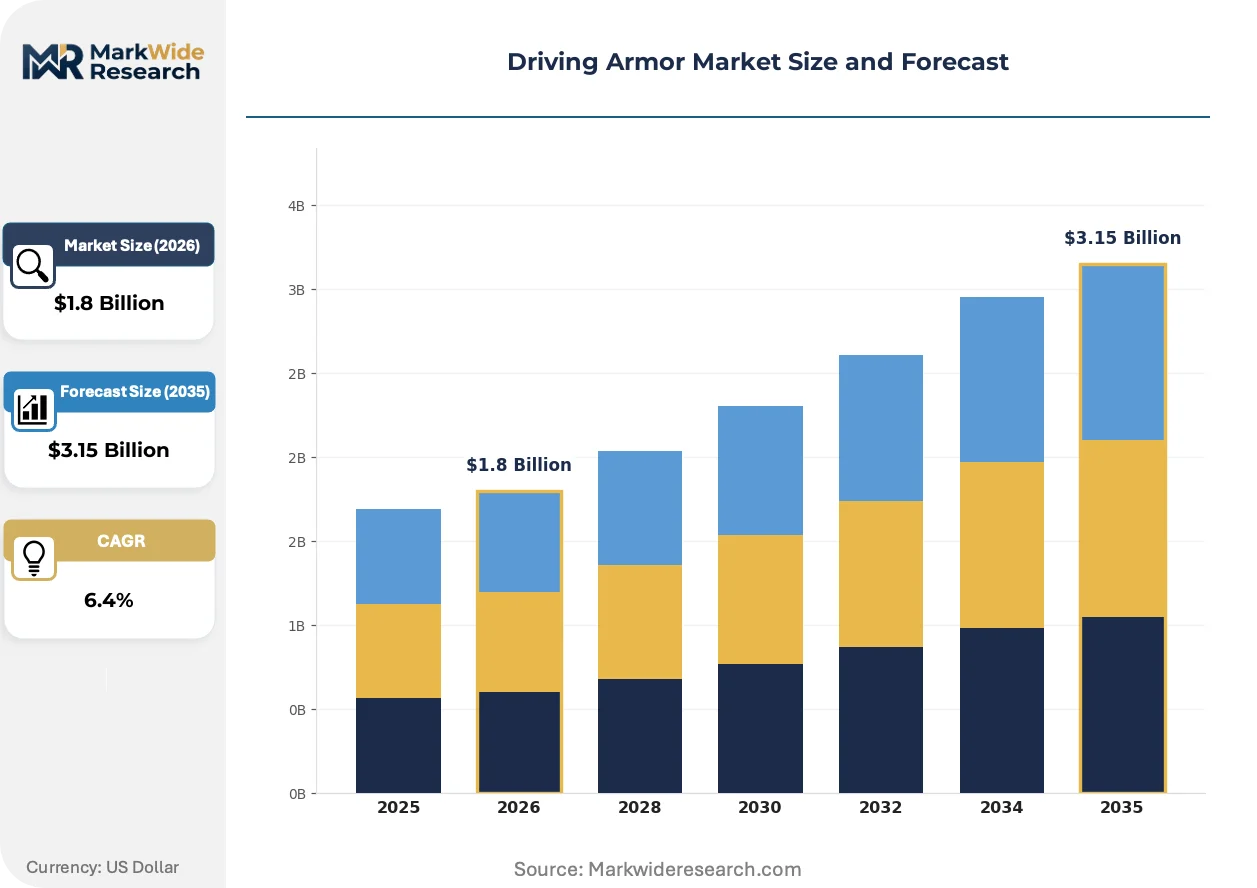
Market Dynamics
The NIJ .07 standard revision is compressing certification timelines and forcing polyethylene plate upgrades across law enforcement procurement channels, creating a structural bottleneck for manufacturers lacking certified testing relationships.
Growth Catalysts
- NATO STANAG procurement alignment:Cross-border military standardization is enabling bulk polyethylene plate orders across allied defense ministries, consolidating supplier qualification pools.
- State-level law enforcement modernization:US municipal agencies are replacing steel plate inventories with ultra-high-molecular-weight polyethylene systems to reduce officer fatigue.
- Ceramic composite threat-level advancement:Military vehicle crews require upgraded ceramic formulations against armor-piercing ammunition, pulling material innovation investment.
Market Restraints
- Aramid fiber supply concentration:Kevlar production capacity concentrates among limited upstream chemical processors, creating input bottlenecks during surge demand periods.
- Dual-use export control friction:US International Traffic in Arms Regulations restrict polyethylene fiber shipments to allied security forces, fragmenting supplier-customer relationships.
- Ballistic testing infrastructure scarcity:NIJ-certified laboratories face 18-month backlogs, delaying product launches and freezing working capital.
Strategic Opportunities
- Private security contractor expansion:Executive protection details and high-value transport operators represent an underpenetrated channel seeking discreet, concealable polyethylene solutions.
- Integrated sensor-embedded armor:Convergence of ballistic plates with biometric monitoring and communications hardware creates premium system opportunities for vehicle crews.
- EU CE marking harmonization:The European Union's personal protective equipment directive streamlines cross-border commercial sales, reducing per-country compliance costs.
Industry Challenges
- Ballistic materials engineering talent scarcity:Specialized polymer chemists and ceramic composite designers command premium compensation, constraining R&D team scaling.
- Legacy steel plate inventory displacement:Law enforcement agencies face budget friction funding polyethylene replacements while depreciating functional steel assets.
- Multi-standard certification complexity:Manufacturers must simultaneously satisfy NIJ, NATO STANAG, and CE marking requirements, multiplying testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Armor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Tactical Gear, Bulletproof Vests, Ballistic Shields Material: Kevlar, Steel, Polyethylene, Ceramic Application: Law Enforcement, Military, Private Security, Civilian Use End User: Government Agencies, Security Forces, Private Individuals, Organizations |
| Companies Covered | Alpinestars, RYNOX Gears, First Mfg, Dainese, Leatt, EVS Sports, Troy Lee Designs, Honeywell International, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Armor Market Shifts & Advancements
Automation of manufacturing processes and regulatory compression of certification cycles are restructuring competitive advantage around speed-to-market rather than raw material access alone.
Ultra-high-molecular-weight polyethylene fiber weaving is automating layup precision for multi-curve plate geometries. US Department of Defense contractors are adopting robotic preforming cells to meet NIJ .07 volume requirements. This automation is compressing defect rates and enabling just-in-time production for urgent procurement awards.
REACH chemical registration protocols in the European Union are tightening aramid fiber processing disclosure requirements. Manufacturers must document solvent recovery rates and worker exposure controls across European supply chains. Military suppliers with established ECHA compliance documentation are capturing preferred supplier status in NATO cross-border tenders.
Consolidated national procurement frameworks are replacing fragmented municipal purchasing across federal defense ministries. Australian Defence Force centralized armor acquisition through a single tendering office, compressing vendor lists from twelve to four qualified suppliers. This concentration is visible across Five Eyes intelligence-sharing partners, where interoperability mandates favor standardized polyethylene plate specifications.
Driving Armor Market Segmentation
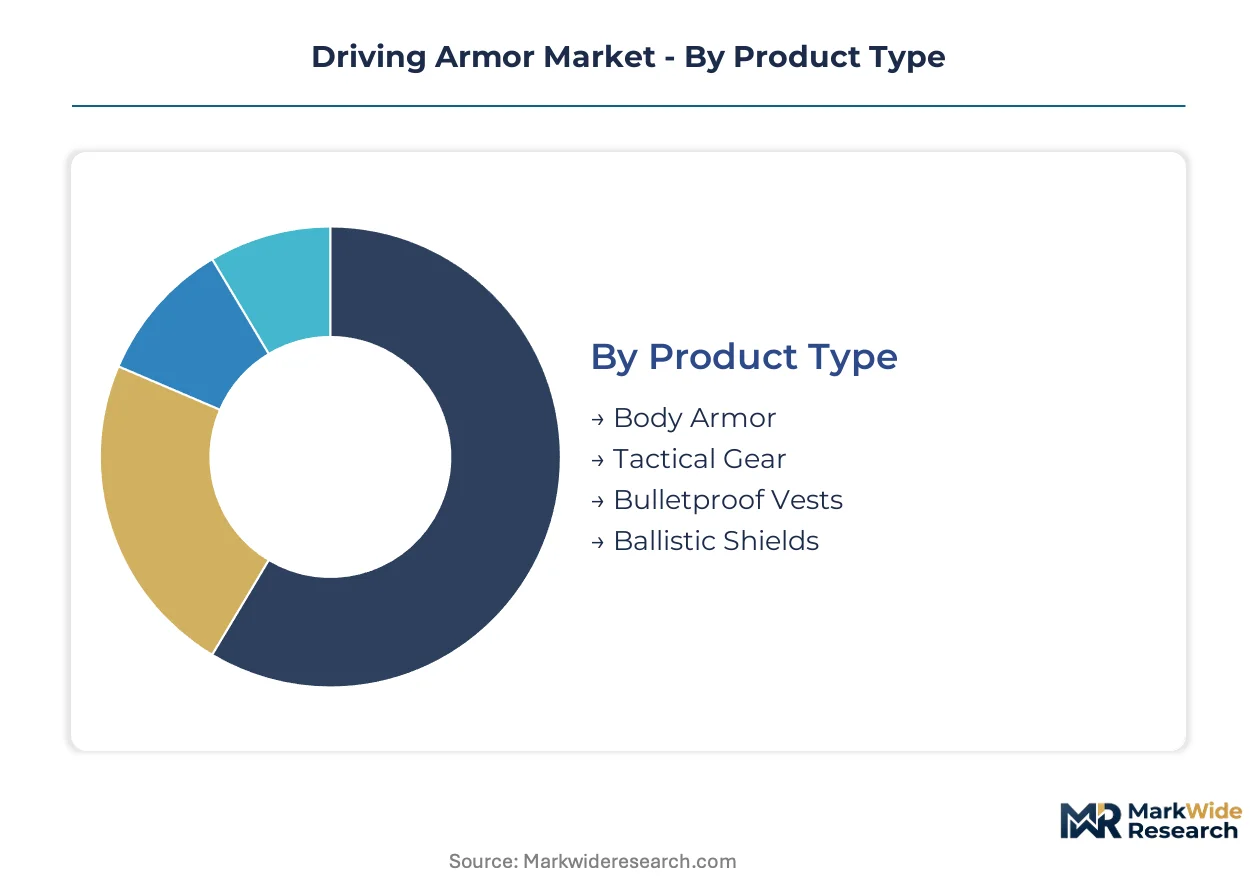
Driving armor procurement channels fragment across threat-level specifications, budget tiers, and regulatory compliance requirements. Each segmentation dimension carries distinct margin profiles and certification barriers that reshape competitive positioning across supplier ecosystems.
Product Type:
Volume concentration sits with legacy protective garments, while premium system integration captures expanding procurement budgets from specialized vehicle crews.
- Bulletproof Vests:Soft armor systems utilizing aramid fiber layers rated against handgun threats dominate municipal law enforcement inventories. US state-level modernization programs are replacing steel plate inserts with polyethylene equivalents to reduce officer fatigue during extended vehicle patrols.
- Tactical Gear:Modular load-bearing equipment integrates ballistic panels with communications and medical pouches for rapid vehicle egress scenarios. Private security contractors in executive protection roles are driving demand for low-visibility configurations that balance concealability with NIJ Level IIIA protection.
- Body Armor:Hard plate systems rated against rifle threats anchor military vehicle crew protection protocols across NATO STANAG-aligned procurement frameworks.
- Ballistic Shields:Portable protection systems for tactical vehicle approaches concentrate demand among specialized response units requiring maneuverable cover solutions.
Mature deployment sits with bulletproof vests across routine patrol functions. Newer deployment is concentrated in tactical gear as private security channels professionalize their protective capabilities.
Material:
Cost-to-weight ratios are restructuring procurement priorities across military and law enforcement channels, with ceramic commanding premium threat-level applications and polyethylene displacing legacy alternatives.
- Polyethylene:Ultra-high-molecular-weight polyethylene fiber plates deliver multi-hit rifle protection at approximately half the weight of steel equivalents. Law enforcement agencies in the United States are accelerating polyethylene adoption to address musculoskeletal injury claims linked to prolonged steel plate wear during vehicle-based operations.
- Ceramic:Alumina and silicon carbide composite formulations achieve armor-piercing threat ratings required for military vehicle crew protection. NATO member state defense ministries are consolidating ceramic plate specifications through STANAG 4569 alignment to enable cross-border interoperability and bulk procurement leverage.
- Kevlar:Aramid fiber soft armor maintains dominance in concealable vest applications where flexibility and extended wear comfort outweigh maximum threat protection requirements.
- Steel:Legacy plate systems persist in budget-constrained municipal agencies facing depreciation friction on functional existing inventories despite polyethylene performance advantages.
Volume leadership belongs to polyethylene as weight-driven replacement cycles accelerate. Ceramic formulations retain the steepest expansion trajectory from armor-piercing threat escalation in contested operational environments.
Application:
End-use concentration patterns reflect divergent procurement authorization levels, with military channels consolidating through national frameworks and private security operating through fragmented purchasing nodes.
- Law Enforcement:Municipal, county, and state agencies operate through decentralized procurement with NIJ certification as the mandatory qualification gate. The NIJ .07 standard revision is compressing supplier pools to manufacturers with established certified laboratory relationships.
- Military:National defense ministries execute consolidated tendering with NATO STANAG interoperability requirements shaping technical specifications. Australian Defence Force centralized armor acquisition demonstrates the vendor consolidation trajectory visible across Five Eyes partners.
- Private Security:Executive protection and high-value transport operators seek discreet polyethylene solutions outside government procurement channels, creating margin opportunities for specialized suppliers.
- Civilian Use:Individual purchasers navigate varying state-level restrictions on body armor possession, with demand concentrating in jurisdictions with permissive regulatory frameworks.
Established procurement volume centers on military applications through national defense budgets. Private security represents the most rapidly diversifying channel as threat perceptions expand across corporate and individual risk management strategies.
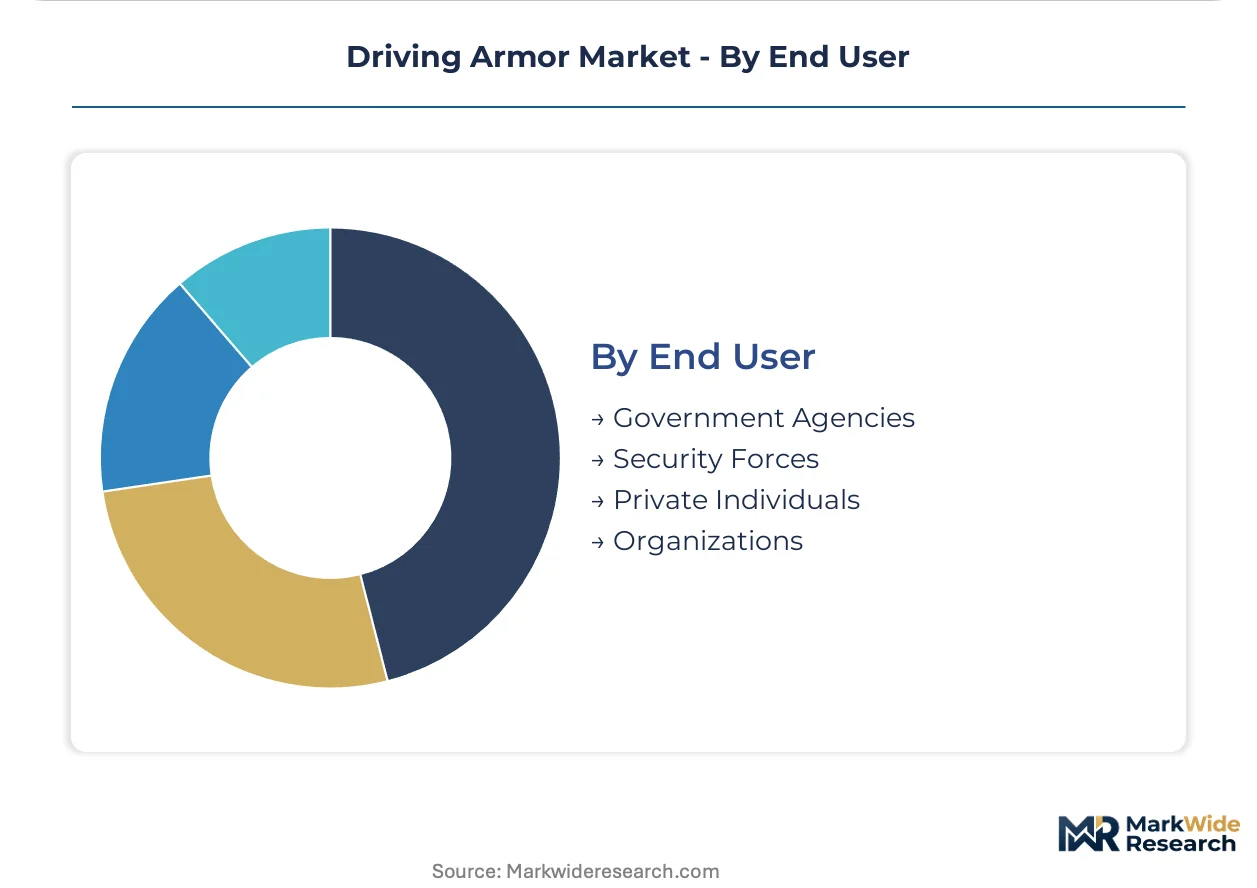
End User:
Customer-type segmentation reveals structural concentration among institutional purchasers with multi-year procurement horizons versus transactional individual acquisition patterns.
- Government Agencies:Federal, state, and municipal entities operate through formalized competitive bidding with NIJ certification and documented testing histories as non-negotiable qualification criteria. Working capital intensity from 18-month NIJ-certified laboratory backlogs favors established suppliers with parallel testing pipelines.
- Security Forces:Allied military and paramilitary organizations navigate dual-use export control friction under US International Traffic in Arms Regulations, fragmenting supplier-customer relationships for polyethylene fiber shipments.
- Organizations:Corporate security departments and non-governmental entities with vehicle-based operations in high-threat environments represent an emerging procurement category with customized threat assessment protocols.
- Private Individuals:Discrete purchasers prioritize concealability and rapid acquisition timelines over maximum protection ratings, with online distribution channels capturing share from traditional retail outlets.
Contracting concentration sits with government agencies through formal procurement frameworks. Organizational end users are gaining share fastest as corporate risk management programs professionalize their protective equipment standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Department of Defense contracting channels and state-level law enforcement modernization budgets in the United States concentrate procurement volume. NATO member states are expanding polyethylene plate orders through aligned military procurement programs.
United States
The National Institute of Justice revises ballistic resistance standards, forcing material upgrades across law enforcement agencies. NIJ-certified laboratories face testing backlogs that compress supplier qualification timelines. Department of Defense contractors in the Mid-Atlantic region adopt robotic preforming cells to meet NIJ .07 volume requirements.
Germany
Bundeswehr modernization programs drive ceramic composite demand for vehicle crew protection systems. REACH chemical registration protocols tighten aramid fiber processing disclosure requirements across European supply chains. Industrial clusters in North Rhine-Westphalia host manufacturers with established ECHA compliance documentation capturing preferred supplier status.
United Kingdom
Five Eyes interoperability mandates favor standardized polyethylene plate specifications for cross-border military coordination. The Ministry of Defence consolidates armor acquisition through centralized tendering frameworks. Defense contractors in the Midlands region scale production to meet NATO STANAG-aligned procurement schedules.
Australia
The Australian Defence Force centralized armor acquisition through a single tendering office, compressing vendor lists from twelve to four qualified suppliers. National procurement frameworks replace fragmented municipal purchasing across federal defense ministries. Manufacturing concentration in Victoria and New South Wales supplies polyethylene plate systems for allied security forces.
France
Direction Générale de l'Armement oversees consolidated military procurement with NATO STANAG technical specifications. CE marking harmonization under the European Union's personal protective equipment directive streamlines cross-border commercial sales. Defense industrial bases in the Île-de-France region integrate ballistic protection with vehicle systems for export markets.
Driving Armor Market Competitive Landscape
United States producers anchor the upstream material tier through fiber technology dominance; European specialists hold integrated protection system capabilities. Supplier pools consolidate around certified testing relationships and documented regulatory compliance histories. Three archetypes define competitive positioning: heritage motorsport brands navigating adjacent tactical mobility, chemical processors controlling aramid and polyethylene fiber supply, and defense contractors integrating sensor-embedded armor systems. Dominant competitive moves include backward integration into fiber production and strategic partnerships with NIJ-certified testing laboratories.
Among material science specialists, DuPont and Honeywell International exemplify upstream control over aramid and ultra-high-molecular-weight polyethylene fiber supply. Dainese occupies a position representing heritage motorsport brands extending into tactical mobility segments. These three anchors illustrate how competitive advantage flows from certified manufacturing footprints and established testing relationships rather than product differentiation alone.
| Leading Market Players |
|---|
| Alpinestars |
| RYNOX Gears |
| First Mfg |
| Dainese |
| Leatt |
| EVS Sports |
| Troy Lee Designs |
| Honeywell International |
| DuPont |
| Others |
Supply & Pricing Matrix
Specialized polymer chemists and ceramic composite designers in the Mid-Atlantic defense manufacturing corridor command premium compensation packages that compress margins at the economy tier while sustaining wide spreads to premium NIJ-certified systems. Labor-cost differentials between certified engineering talent and production-line assembly propagate three-tier pricing stratification across law enforcement procurement channels.
Pricing Analysis
Volume concentrates in municipal law enforcement bulletproof vest replacements while margins concentrate in military ceramic plate systems. Three-tier pricing structure across premium, standard, and economy levels separates NIJ .07-certified polyethylene plates from legacy steel inventory clearances and uncertified imports. Cost compression in the economy tier intensifies because municipal agencies face depreciation friction on functional steel assets. State-level law enforcement agencies exhibit highest price sensitivity due to decentralized budget authorization, while Department of Defense contractors demonstrate lowest sensitivity given threat-level specification mandates.
Supply Chain Analysis
NIJ-certified laboratory relationships function as qualification gates that filter supplier pools before manufacturing scale becomes relevant. Raw material concentration centers on the United States for Spectra polyethylene fiber, Germany for aramid processing chemicals under REACH protocols, and Australia for consolidated defense procurement. Ceramic composite formulations draw from alumina suppliers in Germany and silicon carbide processors in the United States. Single-source vulnerability concentrates in Kevlar fiber production capacity among limited upstream chemical processors. Distribution runs through defense ministry tendering offices in NATO member states and fragmented municipal procurement channels in US law enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ballistic testing infrastructure scarcity props pricing power for incumbent suppliers with established NIJ-certified laboratory relationships, constraining new capacity entry regardless of raw material availability.
For Market Incumbents: Lock in exclusive testing queue arrangements with NIJ-certified laboratories to compress competitor certification timelines. Secure captive supply of ultra-high-molecular-weight polyethylene fiber through backward integration or long-term offtake agreements with Honeywell International or DuPont. Threat from emerging polyethylene weavers in Asia-Pacific regions necessitates rapid certification pipeline investment. Certification capacity represents the priority lever for margin defense. For New Entrants and Emerging Players: The price-point gap between premium NIJ-certified systems and economy-tier steel replacements creates white-space opportunity for mid-tier polyethylene solutions. Private security contractors in executive protection roles represent the most penetrable segment given fragmented purchasing outside government procurement channels. Target organizational end users with customized threat assessment protocols and rapid fulfillment timelines. Go-to-market angle should emphasize discreet, concealable configurations with NIJ Level IIIA protection ratings. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier manufacturers possessing established ECHA compliance documentation and pending NIJ .07 certification given REACH protocol tightening and standard revision catalysts. Long-term viability over a five-to-ten-year window favors suppliers with dual military-commercial certification footprints. Acquisition target archetype: European manufacturers with CE marking infrastructure and nascent NIJ laboratory relationships. Signal to watch is Australian Defence Force vendor list expansion or contraction as proxy for Five Eyes interoperability standard adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ-Certified Laboratory Partnership | Secures 18-month testing queue priority for polyethylene plate certification cycles. |
| Robotic Preforming Cell Deployment | Enables just-in-time production for urgent Department of Defense procurement awards. |
| ECHA Compliance Documentation Investment | Captures preferred supplier status in NATO cross-border tenders under REACH protocols. |
| Private Security Channel Development | Accesses margin-rich executive protection demand outside government contracting channels. |
| Sensor-Embedded Armor Integration | Creates premium system opportunities for vehicle crews requiring biometric monitoring convergence. |
Research Methodology
SEC 10-K filings, NATO procurement databases, and NIJ standard revision documentation formed the secondary backbone. Primary interviews with defense procurement officers, NIJ-certified laboratory directors, polymer chemists at fiber manufacturers, and private security contractors combined with secondary validation. Bottom-up and top-down triangulation cross-checked polyethylene plate shipment volumes against Department of Defense budget authorization data.
Bottom-up modeling segmented the market across product type, material formulation, and application dimensions. The analytical lens weighted military procurement cycles, law enforcement modernization budgets, and private security professionalization trends. CAGRs were derived from regression analysis of historical polyethylene adoption curves and threat-level specification escalations. Industry-specific forecast inputs included NIJ .07 implementation timelines and dual-use export control classification changes.
Underlying measurement precision varies by segment; military applications carry tighter precision than private security given consolidated national procurement data availability. Forecasts reflect assumptions regarding NATO STANAG alignment continuity and REACH chemical registration stability. A model refresh is warranted upon material change in NIJ certification backlog durations or polyethylene fiber export control reclassification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market