
 Terrain Awareness and Warning System Market | 2026-2036
Terrain Awareness and Warning System Market Size, Share, and Industry Trends Forecast 2026-2036
Terrain Awareness and Warning System Market Analytics
Subscription-based terrain database updates and software-defined alerting modules is hardening into a distinct revenue layer alongside hardware sales. Honeywell International Inc. leverages its integrated flight management ecosystem to bundle predictive terrain services with avionics suites. Garmin Ltd. anchors the general aviation segment through portable and panel-mounted TAWS with continuous map refresh cycles. Collins Aerospace competes on military and commercial platforms with federated sensor architectures that reduce cockpit display redundancy.
A Terrain Awareness and Warning System is an integrated avionics safety system that processes GPS position, radar altimeter data, and digital elevation models to generate predictive cautions and warnings when aircraft proximity to terrain violates computed envelopes. The system serves the primary commercial purpose of preventing controlled flight into terrain by providing flight crews with advance alert times exceeding those of basic ground proximity systems. EGPWS technology leads installed bases across commercial aviation due to its enhanced situational awareness with runway and obstacle databases. Civil Aviation application demand outpaces military programs as low-cost carriers in emerging markets expand fleet utilization rates. Hardware components retain the largest value share, though software and sensor systems segments capture expanding margins through retrofit upgrade cycles.
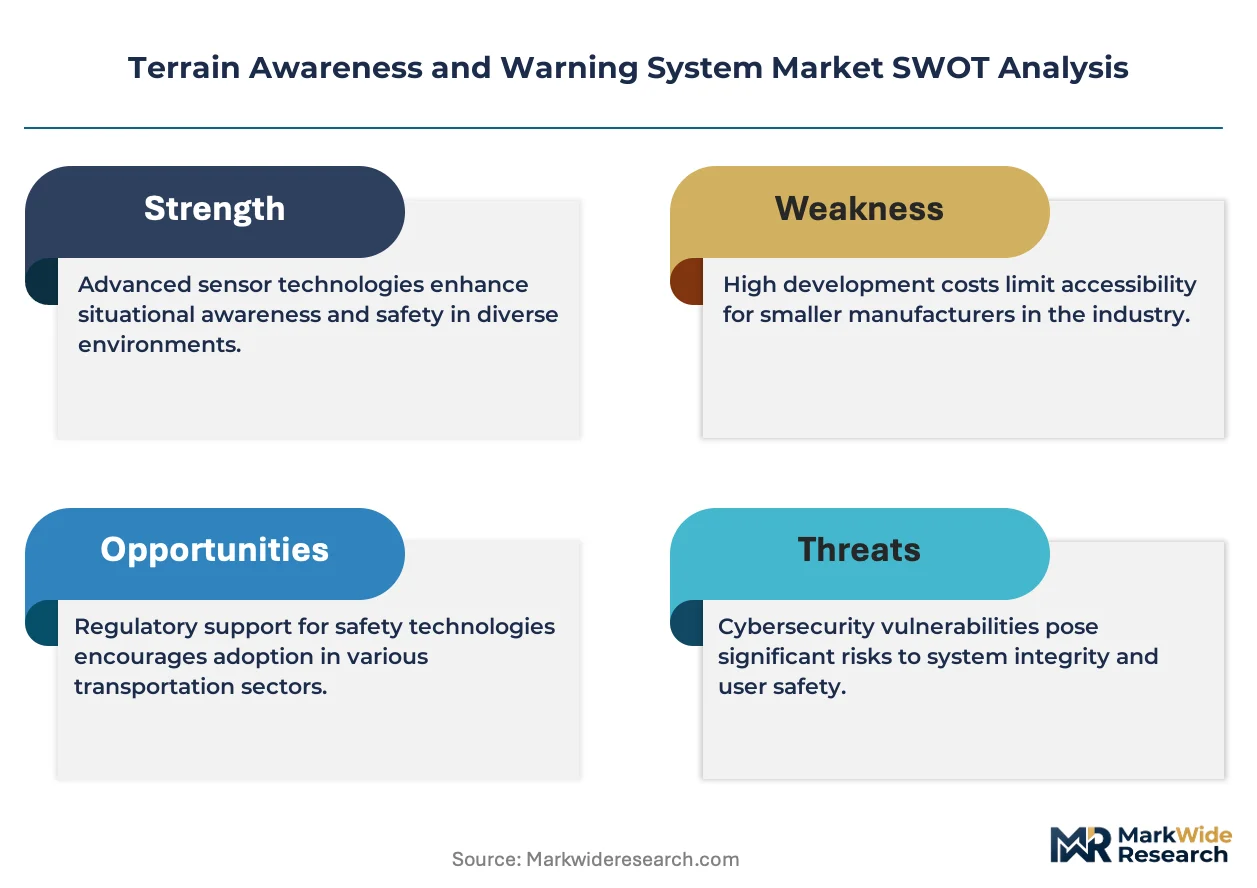
The FAA mandates TAWS equipage under 14 CFR 135.154 for turbine-powered aircraft, while EASA enforces comparable requirements through CS-AWF certification standards, both frameworks directly shaping retrofit demand timelines for regional operators. The EU AI Act and emerging machine-learning validation protocols from EASA will influence next-generation predictive alerting algorithms and system autonomy thresholds. Stakeholders must monitor how regulatory divergence between FAA performance-based standards and EASA prescriptive certification pathways affects product development roadmaps and aftermarket service architectures.
Market Dynamics
FAA and EASA mandates for terrain avoidance capabilities are compressing retrofit timelines for regional turbine fleets, while software-defined alerting architectures are displacing hardware-centric upgrade cycles across commercial aviation.
Growth Catalysts
- 14 CFR 135.154 Mandate:FAA requirements for turbine-powered aircraft equipage are forcing regional operators to accelerate TAWS installation schedules ahead of compliance deadlines.
- Retrofit Cycles:Legacy narrow-body and regional jet fleets in Asia-Pacific are entering concentrated modernization windows that bundle terrain systems with avionics suite overhauls.
- Digital Elevation Models:High-resolution terrain database subscriptions are generating recurring revenue streams that extend system lifecycles beyond initial hardware sales.
Market Restraints
- Sensor Cost Volatility:Radar altimeter component pricing fluctuates with semiconductor foundry capacity constraints concentrated in East Asian supply chains.
- Certification Pathway Divergence:FAA performance-based standards and EASA prescriptive certification frameworks create parallel development tracks that inflate engineering overhead.
- Legacy System Entrenchment:Basic ground proximity warning systems in older freighter fleets delay full TAWS adoption due to airframe modification complexity.
Strategic Opportunities
- Urban Air Mobility:Emerging eVTOL platforms require predictive terrain alerting integrated with autonomous flight management systems for low-altitude corridor operations.
- India Fleet Expansion:Domestic carriers modernizing regional jet fleets present concentrated demand for integrated TAWS solutions with continuous database refresh services.
- EU AI Act Alignment:Machine-learning validation protocols for predictive alerting algorithms create first-mover advantages for suppliers with certified autonomous decision-support modules.
Industry Challenges
- Systems Integration Complexity:Federated sensor architectures must interface with legacy cockpit displays across mixed-generation fleets without redundant hardware installation.
- Validation Engineering Bottleneck:EASA's emerging machine-learning certification standards require specialized flight-test data collection that outpaces current validation workforce capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terrain Awareness and Warning System Market |
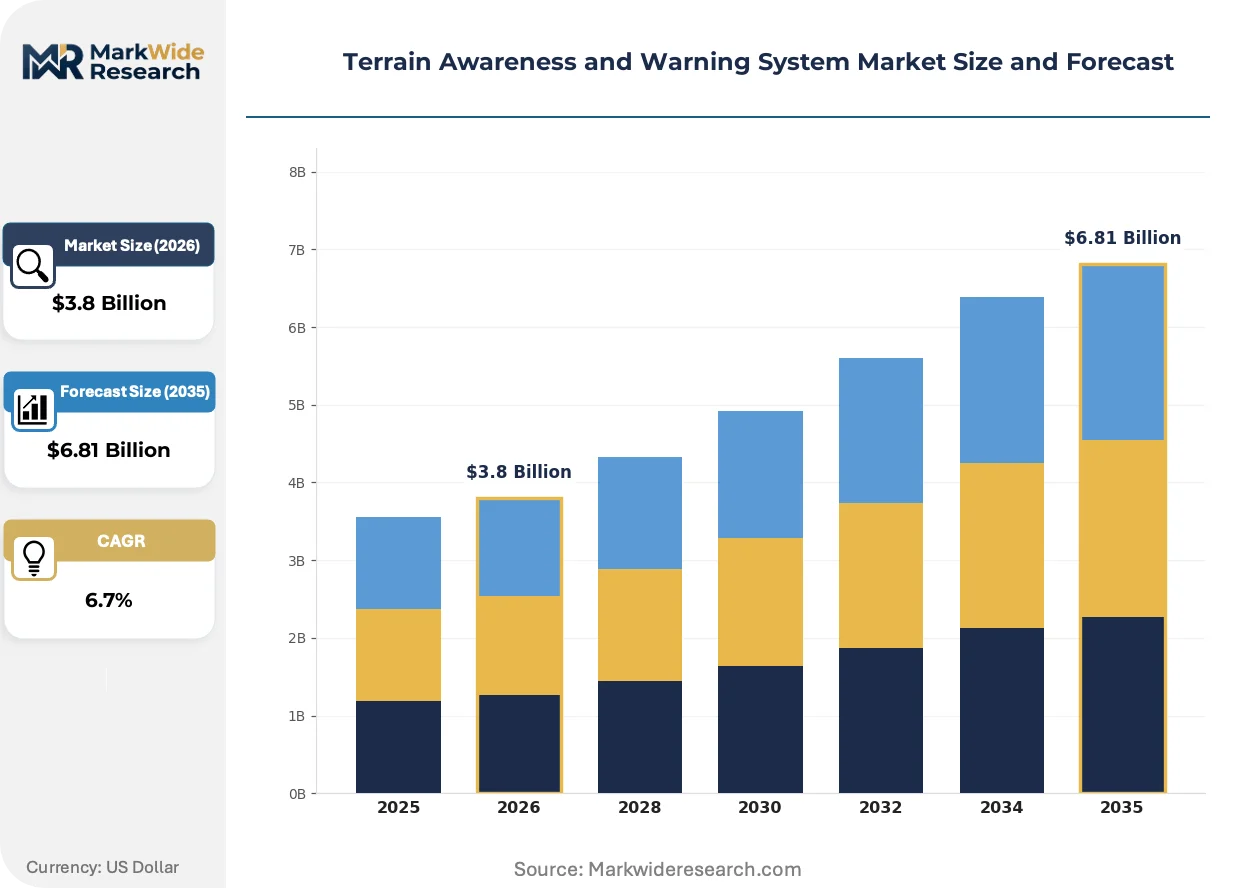
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FMS, GPWS, EGPWS, TAWS Application: Civil Aviation, Military Aviation, General Aviation, Commercial Transportation End User: Airlines, Military Forces, Private Operators, Corporate Fleets Component: Hardware, Software, Sensor Systems, Display Units |
| Companies Covered | Thales Group, Aspen Avionics, Inc., Honeywell International Inc., Genesys Aerosystems, Avidyne Corporation, Garmin Ltd., L3Harris Technologies, Universal Avionics Systems Corporation, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terrain Awareness and Warning System Market Evolving Landscape
Predictive terrain alerting is converging with autonomous flight management systems, while regulatory frameworks are hardening around machine-learning validation protocols that will reshape supplier certification strategies.
Enhanced Ground Proximity Warning System technology is integrating GPS position, radar altimeter inputs, and digital elevation models into unified predictive envelopes. Low-cost carriers in emerging markets are adopting EGPWS as standard equipage during narrow-body fleet inductions. This convergence is integrating terrain awareness into broader flight management ecosystems that bundle navigation, weather, and obstacle alerting into single software-defined platforms.
EASA's machine-learning validation protocols under the EU AI Act are imposing algorithmic transparency requirements on predictive alerting systems. These standards compress development timelines for suppliers seeking certification ahead of 2026 implementation windows. Commercial aviation operators in Europe are prioritizing suppliers with pre-validated autonomous decision-support modules to avoid retrofit penalties.
Subscription-based terrain database refresh cycles are displacing perpetual-license models across general aviation and regional operator segments. Continuous map update services now anchor aftermarket revenue streams that extend customer relationships beyond initial hardware installation. This shift is most visible in China and India, where domestic carriers bundle database subscriptions with fleet-wide avionics modernization contracts.
Terrain Awareness and Warning System Market Segmentation
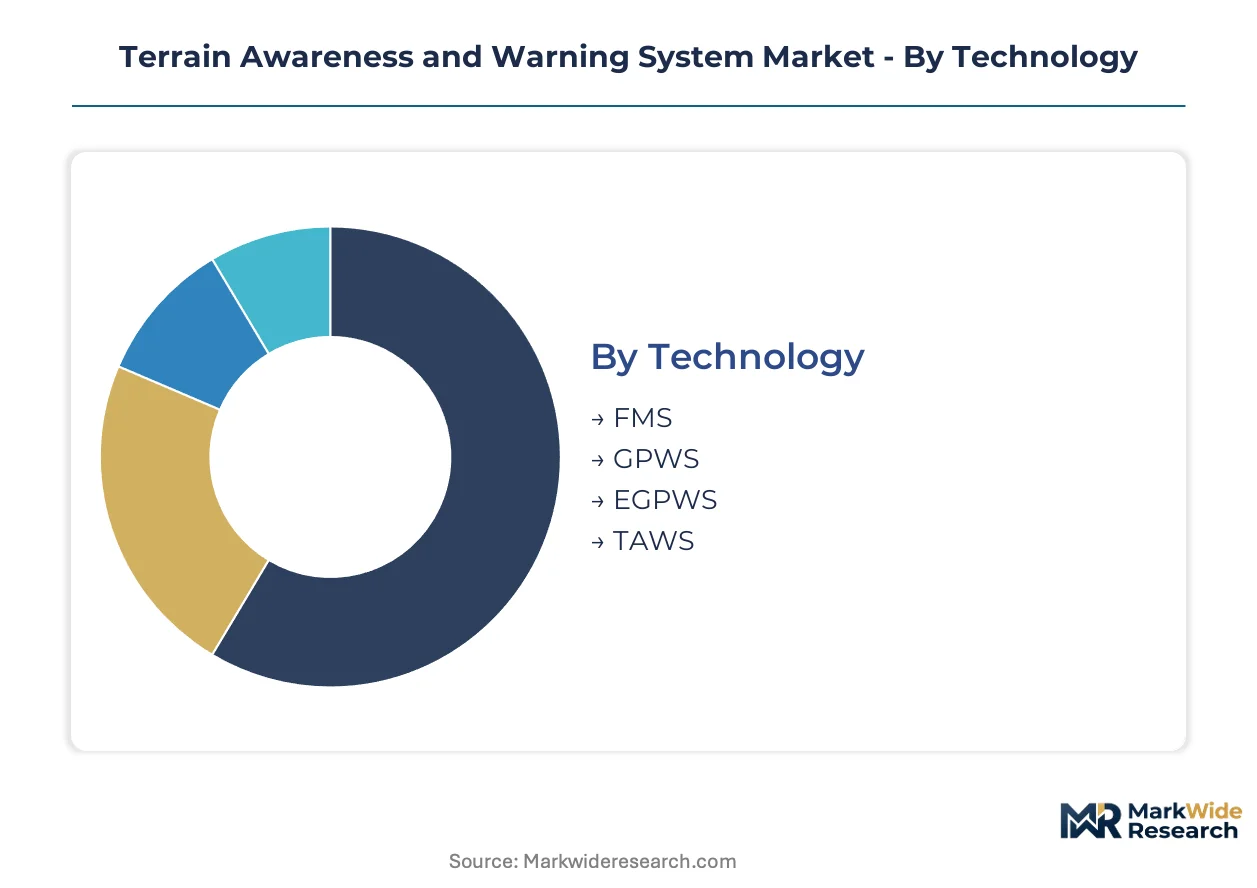
TAWS market segmentation reflects distinct procurement patterns across aviation verticals, with technology tiers commanding different pricing structures and certification timelines. Component-level segmentation tracks hardware-software margin shifts as predictive alerting architectures evolve.
Technology:
Supply concentration in radar altimeter and GPS receiver manufacturing concentrates upgrade decisions among three dominant architectures.
- EGPWS:Enhanced Ground Proximity Warning System integrates GPS position, radar altimeter data, and digital elevation models into unified predictive envelopes. Commercial airlines in China and India specify EGPWS as baseline equipage during narrow-body fleet inductions, driven by EASA and FAA mandates for terrain avoidance capabilities.
- TAWS:Terrain Awareness and Warning System represents the broad regulatory category encompassing forward-looking terrain avoidance with continuous position monitoring. Regional operators in Asia-Pacific accelerate TAWS installation schedules to meet 14 CFR 135.154 compliance deadlines for turbine-powered aircraft.
- FMS:Flight Management System integration embeds terrain alerting within broader navigation and performance optimization suites.
- GPWS:Ground Proximity Warning System provides basic altitude-based warnings without predictive terrain mapping.
EGPWS absorbs the bulk of installed capacity; TAWS is expanding most quickly.
Application:
Cost tier differentiation separates military-grade federated architectures from commercial integrated solutions.
- Civil Aviation:Commercial air transport operators deploy integrated TAWS solutions with continuous database refresh services. Low-cost carriers in emerging markets bundle terrain systems with avionics suite overhauls during narrow-body modernization cycles.
- General Aviation:Private and business aircraft operators adopt portable and panel-mounted systems with subscription-based terrain database updates. Garmin anchors this segment through continuous map refresh cycles that displace perpetual-license models.
- Military Aviation:Defense platforms require federated sensor architectures that reduce cockpit display redundancy while maintaining mission-critical reliability.
- Commercial Transportation:Cargo and logistics fleets face delayed adoption due to legacy system entrenchment in older freighter airframes.
Civil Aviation commands the dominant revenue share; General Aviation climbs the fastest on database subscription attach rates.
End User:
Volume concentration among full-service carriers contrasts with fragmented procurement across private operator segments.
- Airlines:Scheduled commercial carriers drive fleet-wide TAWS deployment with integrated avionics modernization contracts. Domestic carriers in India present concentrated demand for solutions with bundled database refresh services.
- Private Operators:Individual aircraft owners prioritize portable systems with lower certification overhead and flexible installation timelines.
- Military Forces:Defense procurement emphasizes federated architectures with redundant sensor pathways for contested electromagnetic environments.
- Corporate Fleets:Business aviation operators balance regulatory compliance with cabin integration aesthetics and display consolidation.
Airlines account for the majority of unit shipments; Private Operators gain share fastest on portable system adoption.
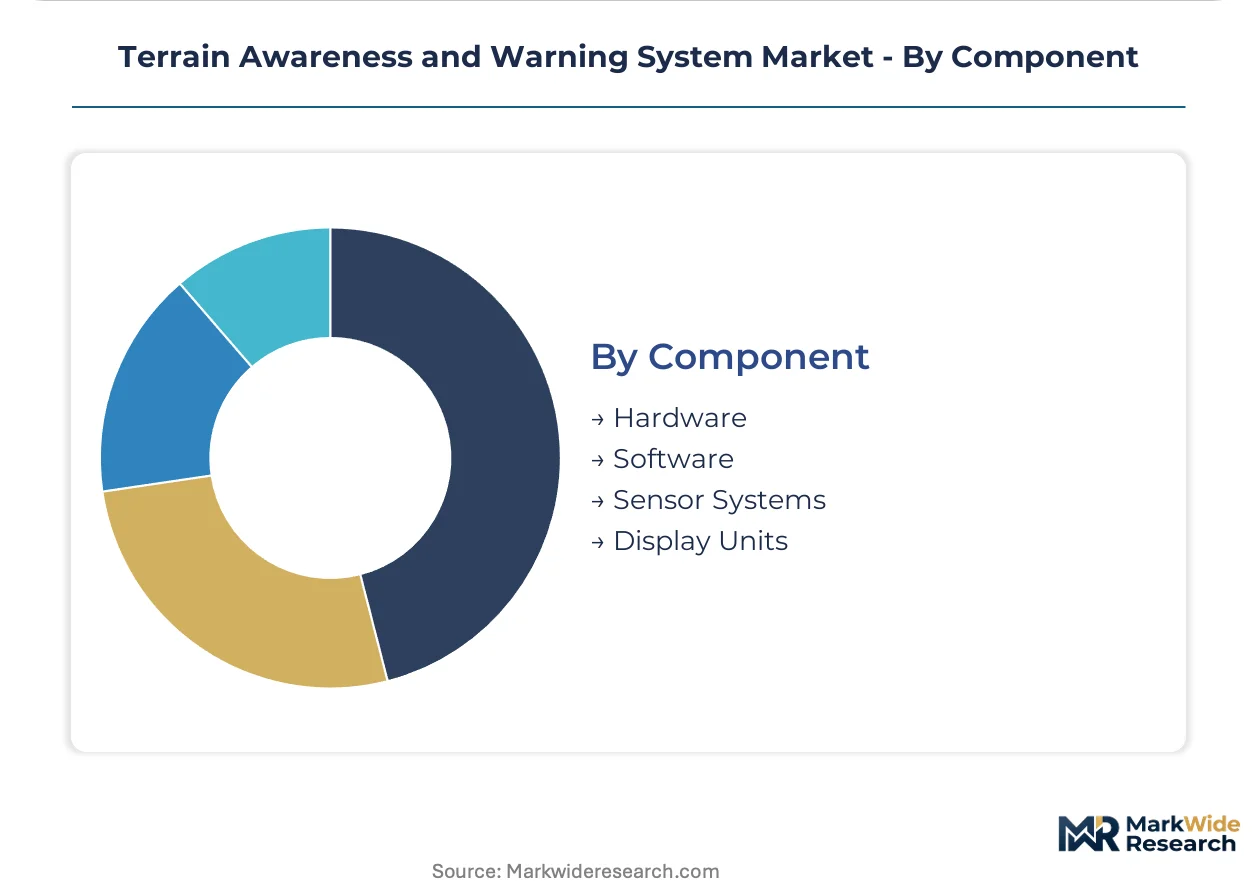
Component:
Margin migration from hardware to software and sensor systems segments reshapes supplier revenue models.
- Hardware:Radar altimeters, GPS receivers, and processing units retain the largest value share despite commoditization pressure. Semiconductor foundry capacity constraints in East Asian supply chains create sensor cost volatility that inflates procurement budgets.
- Software:Predictive alerting algorithms and terrain database subscriptions capture expanding margins through recurring revenue streams. EASA's machine-learning validation protocols under the EU AI Act compress development timelines for certified autonomous decision-support modules.
- Sensor Systems:Federated architectures integrating multiple terrain detection modalities reduce cockpit display redundancy.
- Display Units:Cockpit interface hardware faces displacement as software-defined alerting modules consolidate onto existing multifunction displays.
Hardware retains the dominant installed base; Software shows the steepest expansion trajectory on subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in avionics manufacturing clusters across North America and Europe, while fleet expansion in Asia-Pacific drives consumption growth. Retrofit demand from regional operators and new aircraft deliveries create divergent procurement patterns across geographies.
United States
Domestic carriers accelerate TAWS installation schedules to meet FAA 14 CFR 135.154 compliance deadlines for turbine-powered aircraft. The FAA mandates terrain avoidance capabilities across regional and commercial fleets, compressing retrofit timelines. Wichita, Kansas anchors general aviation avionics production, with panel-mounted system manufacturers serving private operator segments.
China
Commercial airlines expand narrow-body fleet inductions with EGPWS specified as baseline equipage under Civil Aviation Administration of China safety directives. The country's aviation regulator tightens terrain avoidance certification requirements for new aircraft deliveries. Shanghai and Beijing concentrate MRO facilities performing avionics suite overhauls on legacy regional jets.
India
Domestic carriers modernize regional jet fleets, presenting concentrated demand for integrated TAWS solutions with bundled database refresh services. Directorate General of Civil India mandates terrain avoidance capabilities for turbine-powered aircraft entering scheduled service. Mumbai and Delhi-NCR host maintenance hubs executing fleet-wide avionics modernization contracts.
Germany
Lufthansa Group and regional affiliates retrofit legacy fleets to satisfy EASA CS-AWF certification standards for terrain avoidance. EASA enforces prescriptive certification frameworks that shape product development roadmaps for European suppliers. Hamburg and Munich concentrate avionics integration facilities serving Central European operators.
France
Air France-KLM procurement drives demand for federated sensor architectures that reduce cockpit display redundancy across mixed-generation fleets. EASA machine-learning validation protocols under the EU AI Act influence supplier certification strategies for predictive alerting algorithms. Toulouse hosts aerospace clusters where flight management system integration occurs for next-generation platforms.
Terrain Awareness and Warning System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the TAWS value chain. The vendor base clusters around three strategic tiers: diversified aerospace conglomerates with integrated flight management ecosystems, specialized avionics manufacturers focused on portable and panel-mounted systems, and military-grade suppliers with federated sensor architectures. Consolidation pressures intensify as software-defined alerting modules displace hardware-centric upgrade cycles. Strategic moves center on database subscription bundling and certification pre-validation under emerging EASA machine-learning standards.
Within the diversified systems tier, Honeywell International Inc. and Collins Aerospace exemplify integrated platform strategies that embed terrain alerting within broader avionics suites. Garmin Ltd. anchors the specialized avionics segment through continuous map refresh services that displace perpetual-license models. Thales Group occupies a position bridging commercial and defense applications with sensor fusion architectures.
| Leading Market Players |
|---|
| Thales Group |
| Aspen Avionics, Inc. |
| Honeywell International Inc. |
| Genesys Aerosystems |
| Avidyne Corporation |
| Garmin Ltd. |
| L3Harris Technologies |
| Universal Avionics Systems Corporation |
| Collins Aerospace |
| Others |
Value Network & Pricing Analysis
Software-defined alerting architectures are displacing hardware-centric upgrade cycles, simultaneously compressing manufacturing costs for established suppliers while concentrating component sourcing among radar altimeter specialists in East Asian foundries. This dual shift rewards suppliers with captive sensor production while squeezing margins for pure-play software vendors dependent on external semiconductor supply.
Pricing Analysis
Cost-down pressure on integrated avionics suites accelerates because EASA machine-learning validation requirements compress development timelines and inflate engineering overhead. Three-tier pricing structure across certified-autonomous, standard-predictive, and basic-terrain-alerting levels separates military-grade federated architectures from commercial integrated solutions and portable general aviation systems. Price differentiation rests on certification grade and after-sales database subscription bundling, with regional operators in Asia-Pacific exhibiting highest price sensitivity due to fleet modernization budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with radar altimeter semiconductor fabrication concentrated in Taiwan, South Korea, and Japan. TAWS manufacturing draws from GPS receiver modules, high-resolution terrain database servers, and federated sensor processing units. Tariff exposure on semiconductor components threatens margin stability for European and North American system integrators. Distribution runs through OEM avionics suite contracts, aftermarket MRO channels, and direct-to-operator database subscription portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop pricing power for integrated suppliers with backward control over sensor supply, while pure-play software vendors face margin compression from component cost volatility.
For Market Incumbents: Extend database subscription attach rates to lock in recurring revenue streams ahead of EASA AI Act compliance deadlines. Deepen backward integration into radar altimeter design to offset foundry pricing volatility and defend against emerging sensor fusion specialists. For New Entrants and Emerging Players: The price-point gap between certified-autonomous decision-support modules and basic terrain-alerting hardware creates entry space for mid-tier predictive algorithm suppliers. Target general aviation retrofit segments in India and China with portable systems featuring simplified certification pathways and flexible installation timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified aerospace conglomerates seeking sensor fusion capabilities. Long-term viability favors suppliers with pre-validated machine-learning modules under EASA emerging standards. Watch for regulatory divergence between FAA performance-based and EASA prescriptive certification frameworks as inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Certification Pre-Validation | EASA AI Act compliance creates first-mover advantage for autonomous alerting algorithm suppliers. |
| Backward Integration into Sensor Design | Captive radar altimeter production insulates margins from Taiwan foundry capacity constraints. |
| Database Subscription Platform Launch | Continuous terrain map refresh services displace perpetual-license models in general aviation. |
| Urban Air Mobility Partnership | eVTOL platform integration opens low-altitude corridor alerting for autonomous flight management. |
| Asia-Pacific MRO Channel Expansion | Mumbai and Delhi-NCR maintenance hubs execute fleet-wide avionics modernization contracts. |
Research Methodology
Document review covered FAA 14 CFR filings, EASA CS-AWF certification records, and avionics manufacturer technical disclosures, complemented by interviews with flight operations directors at regional carriers, avionics procurement leads at low-cost airlines, MRO facility managers in Shanghai and Mumbai, and terrain database product managers at specialized suppliers. Secondary validation drew from Civil Aviation Administration of China safety directives, Directorate General of Civil India mandate documentation, and semiconductor trade flow data. Bottom-up fleet installation estimates were triangulated against top-down avionics market sizing.
Cross-referencing historical retrofit cycle patterns with panel input from airline fleet planners shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology tier, application vertical, end-user category, and component type alongside regulatory certification pathway. CAGRs were derived from installed base growth rates and replacement cycle timing, incorporating fleet expansion schedules from Indian and Chinese domestic carriers and EASA mandate compliance deadlines as industry-specific inputs.
Inputs from regulatory filing databases and carrier fleet planning disclosures were available through the study window; gaps in proprietary avionics pricing data and unannounced military procurement programs introduce uncertainty bands around segment-level estimates. Forecasts reflect documented assumptions regarding mandate enforcement timelines and semiconductor supply normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market