
 Motorcycle E-Call Market | 2026-2036
Motorcycle E-Call Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle E-Call Market Intelligence
Cellular-to-cloud connectivity architecture is reshaping how motorcycle emergency response systems transmit collision data to dispatch centers. Robert Bosch GmbH leverages its automotive sensor heritage to dominate embedded crash detection modules for European OEMs. Continental anchors its position through integrated telematics stacks that pair GPS positioning with automatic voice relay. Yamaha Motor differentiates via smartphone application ecosystems that bridge legacy motorcycles into connected emergency networks without factory hardware retrofits.
A motorcycle e-call system comprises an inertial measurement unit, cellular modem, GPS receiver, and speaker-microphone assembly housed in a crash-resistant enclosure, designed to autonomously detect impact events and establish two-way voice communication with emergency services. Embedded systems command the highest hardware margins due to factory integration complexity and type-approval requirements, while smartphone applications capture the largest addressable base among existing motorcycle owners seeking low-cost retrofit pathways. Cloud-based solutions represent the fastest-expanding deployment mode as fleet operators demand centralized incident logging and predictive maintenance overlays.
The EU AI Act and ECE R10 electromagnetic compatibility standards shape product certification pathways for manufacturers targeting European type approval. Germany's KBA and France's ANSM enforce homologation protocols that delay market entry for non-compliant hardware suppliers. Stakeholders must monitor whether the European Commission mandates eCall functionality for all new motorcycles above 125cc displacement, a regulatory expansion that would eliminate standalone device viability in the bloc's largest sales corridors.
Market Dynamics
EU regulatory mandates are compressing adoption timelines for automatic crash detection hardware, forcing suppliers to accelerate type-approval processes while fleet operators absorb integration costs ahead of compliance deadlines. This structural pressure is redrawing competitive advantage toward vertically integrated telematics providers with established homologation capabilities.
Growth Catalysts
- ECE R10 electromagnetic compliance:Harmonized certification across EU member states reduces redundant testing burdens for embedded system manufacturers targeting multiple national markets simultaneously.
- Fleet operator liability exposure:Commercial motorcycle couriers and rental platforms in France and Italy are retrofitting e-call modules to mitigate insurance premiums and accident litigation risk.
- Cellular-V2X protocol maturation:5G reduced-latency transmission standards enable real-time crash data relay to emergency dispatch centers, improving response coordination for rural road incidents.
Market Restraints
- IMU sensor supply concentration:MEMS accelerometer fabrication relies on Taiwanese and South Korean foundry capacity, exposing hardware vendors to geopolitical supply disruption.
- Subscription revenue model resistance:Individual motorcycle owners reject recurring cellular data fees for emergency services, limiting aftermarket penetration outside fleet channels.
- Legacy motorcycle electrical architecture:Pre-2015 touring bikes lack CAN bus connectivity, forcing expensive wiring harness modifications for embedded e-call installation.
Strategic Opportunities
- Aftermarket smartphone bridge applications:Low-cost Bluetooth-to-cellular adapters capture existing owners of 125cc+ motorcycles in Spain and Portugal unwilling to replace factory electronics.
- Intelligent Speed Assistance convergence:EU AI Act provisions enable bundled offerings combining automatic emergency calling with real-time speed limit recognition and rider alert systems.
- Cloud-based fleet incident analytics:Motorcycle rental operators in Germany seek centralized crash reconstruction data to negotiate preferential insurance terms and optimize rider training programs.
Industry Challenges
- ECE type-approval timeline compression:Germany's KBA and France's ANSM certification queues extend 14-18 months for new hardware entrants, freezing product launch schedules.
- Embedded-versus-tethered system integration:OEMs struggle to harmonize factory-installed cellular modules with third-party smartphone application ecosystems without redundant subscription conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle E-Call Market |
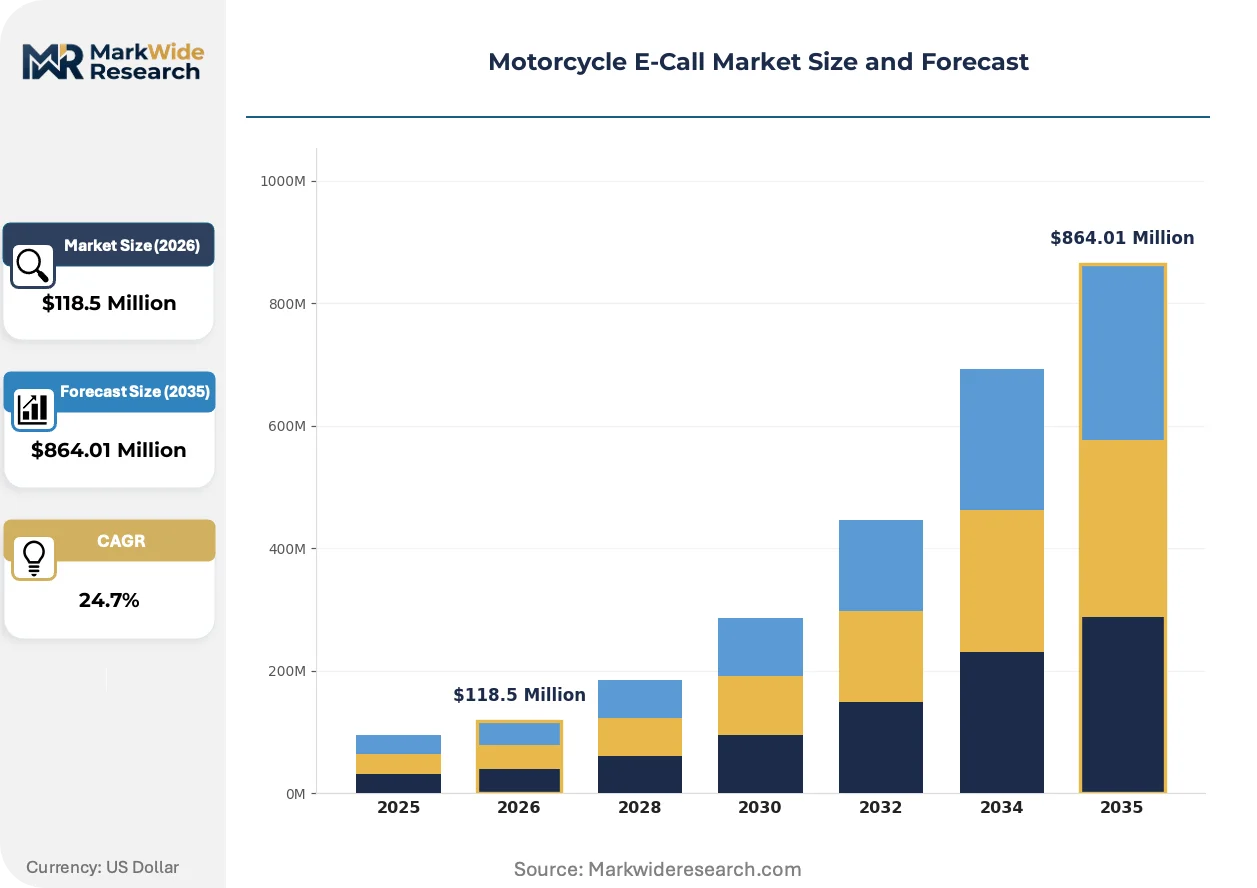
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $864.01 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, GPS, Cellular, Satellite Features: Automatic Crash Detection, Voice Assistance, GPS Tracking, Remote Diagnostics Deployment: Embedded Systems, Smartphone Applications, Standalone Devices, Cloud-Based Solutions End User: Motorcycle Riders, Fleet Operators, Insurance Companies, Emergency Services |
| Companies Covered | Robert Bosch GmbH, Bayerische Motoren Werke AG, Continental, Triumph Motorcycles, Honda Motor, Yamaha Motor, BMW Motorrad, Harman, RealRider, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle E-Call Market Strategic Shifts & Innovations
Sensor fusion architectures are displacing single-point crash detection, combining accelerometer data with gyroscopic trajectory analysis and GPS velocity vectors to reduce false-positive emergency alerts. This convergence is elevating hardware complexity while compressing price tolerance for standalone devices.
Multi-axis inertial measurement is hybridizing with machine-learned impact classification algorithms. Tier-1 suppliers are embedding neural inference engines directly into crash-detection modules. Premium touring motorcycle OEMs in Germany and Italy are specifying these enhanced systems for 2027 model year platforms. The technology is hybridizing hardware margins toward software-defined functionality that enables over-the-air algorithm updates.
France's ANSM and Germany's KBA are tightening electromagnetic compatibility testing protocols under ECE R10 revisions. Non-compliant suppliers face market exclusion from EU type-approval pathways. Embedded system manufacturers with pre-certified telematics stacks are capturing design wins from competitors forced into costly retesting cycles.
Commercial fleet procurement is consolidating around integrated telematics service providers rather than standalone hardware vendors. Motorcycle rental operators in Spain and Italy now specify crash detection as a bundled component within multi-year vehicle management contracts. This bundling is compressing standalone device margins while elevating recurring service revenue visibility for vertically integrated platform vendors.
Motorcycle E-Call Market Segmentation
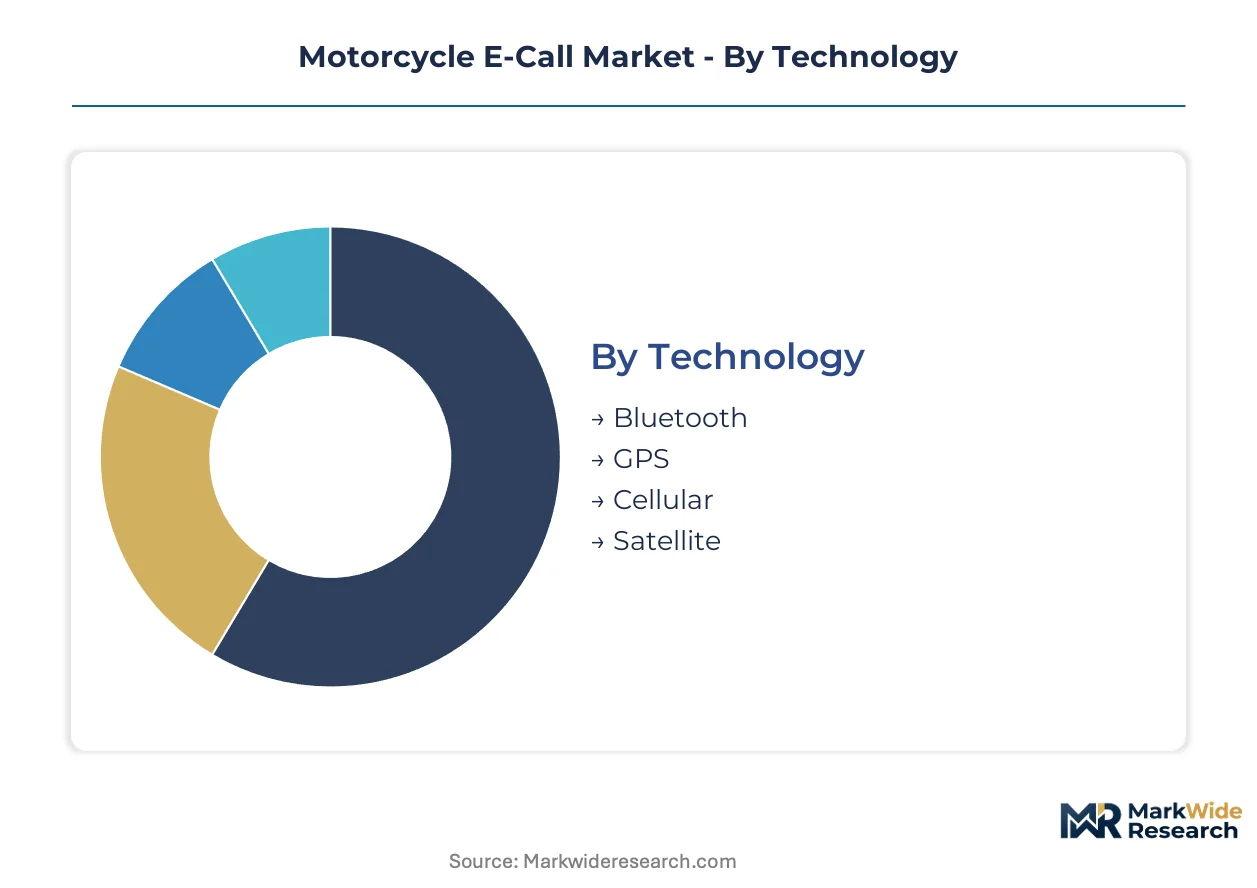
Technology differentiation determines hardware margins and certification complexity across the motorcycle e-call landscape. Deployment mode selection shapes recurring revenue potential and customer acquisition costs for suppliers competing across OEM, aftermarket, and fleet channels.
Technology:
Cost tier stratification separates premium integrated stacks from low-cost single-function modules competing on retrofit accessibility.
- Cellular:Embedded LTE-M and 5G modems enable direct emergency service routing without smartphone tethering. Fleet operators in Germany specify cellular-native architectures to eliminate rider phone dependency during incident response.
- GPS:Multi-constellation receivers combining GPS, GLONASS, and Galileo signals deliver sub-5-meter positioning accuracy for rural crash locations. France's ANSM mandates dual-frequency GPS for type approval of premium touring motorcycle systems.
- Bluetooth:Low-energy protocols bridge legacy motorcycles to smartphone application ecosystems. Spain's aftermarket retrofit channels concentrate demand for Bluetooth-to-cellular adapters among 125cc-400cc touring bike owners.
- Satellite:Iridium and emerging LEO constellations extend coverage beyond cellular dead zones in Alpine and Mediterranean coastal corridors. Limited adoption reflects hardware cost premiums and subscription resistance among individual riders.
Cellular holds installed capacity. GPS is rotating up the share rankings.
Features:
Application criticality varies by liability exposure and regulatory mandate intensity across rider categories.
- Automatic Crash Detection:Multi-axis IMU sensor fusion algorithms classify impact severity and trigger autonomous emergency calls. EU AI Act provisions are mandating this functionality for new motorcycle type approvals above 125cc displacement.
- Voice Assistance:Two-way speaker-microphone assemblies enable emergency dispatcher communication when riders are incapacitated. Italy's commercial courier fleets specify voice relay redundancy to mitigate litigation exposure from delayed response.
- GPS Tracking:Real-time location streaming supports theft recovery and route reconstruction for insurance claims. Portuguese rental operators bundle tracking with crash detection in multi-year fleet management contracts.
- Remote Diagnostics:CAN bus integration enables predictive maintenance alerts and over-the-air firmware updates. Embedded system manufacturers leverage diagnostics capability to justify hardware margin premiums against standalone competitors.
Automatic Crash Detection commands the dominant share position. Remote Diagnostics is climbing the fastest.
Deployment:
Customer type concentration shapes margin structure, with fleet operators accepting subscription models that individual owners reject.
- Embedded Systems:Factory-integrated cellular-GPS modules with ECE R10 type approval command premium hardware margins. OEM specification in Germany and Italy requires 14-18 month homologation timelines that freeze out non-compliant suppliers.
- Cloud-Based Solutions:Centralized incident logging and predictive analytics overlays attract fleet operators seeking insurance premium negotiations. This deployment mode is expanding most quickly as rental platforms consolidate around vertically integrated telematics providers.
- Smartphone Applications:Low-cost Bluetooth bridges capture existing motorcycle owners unwilling to modify factory electronics. France and Spain show highest penetration among 2010-2019 touring motorcycle demographics.
- Standalone Devices:Self-contained cellular-GPS units with internal batteries serve riders of pre-2015 motorcycles lacking CAN bus connectivity. Market share compression reflects OEM integration mandates and subscription revenue model resistance.
Embedded Systems retains volume leadership. Cloud-Based Solutions is ascending the share hierarchy.
End User:
Volume concentration and price tolerance diverge sharply between individual consumers and institutional procurement channels.
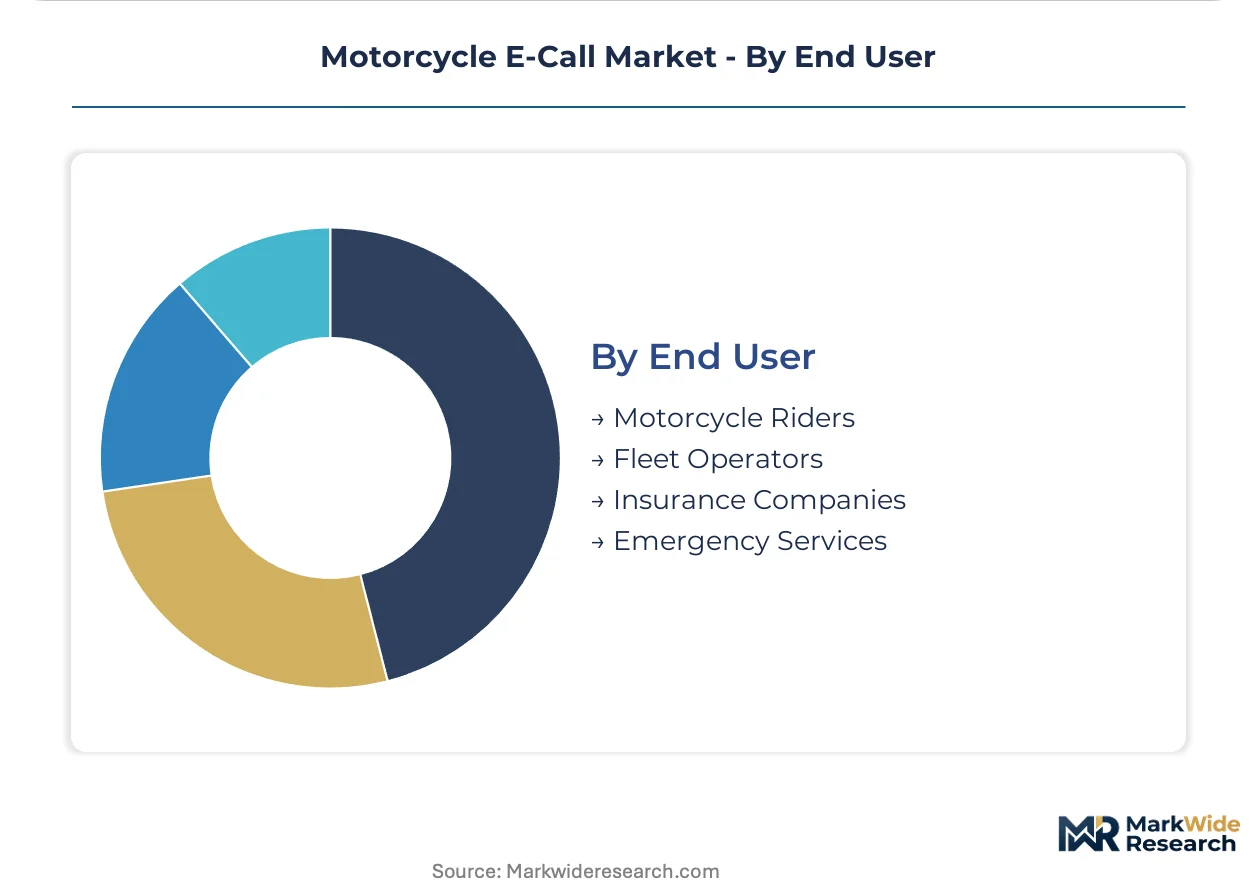
- Fleet Operators:Commercial motorcycle rental and courier platforms in Germany, France, and Italy specify crash detection as bundled telematics components. Multi-year contracts with centralized incident analytics justify hardware subsidies through recurring service revenue.
- Motorcycle Riders:Individual owners prioritize upfront cost minimization and resist cellular subscription fees. Aftermarket smartphone bridge applications capture this segment in Spain and Portugal where regulatory mandates remain advisory.
- Insurance Companies:Risk-based pricing incentives drive specification of certified crash detection systems for premium discounts. Italian insurers lead in mandating e-call hardware for high-displacement touring bike coverage.
- Emergency Services:Public dispatch centers in Germany and France define data format standards for automated collision alerts. Procurement influence is indirect through regulatory pressure on OEM compliance rather than direct hardware acquisition.
Fleet Operators dominate contract value. Insurance Companies is rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and premium touring motorcycle OEMs concentrate demand across Germany, France, Italy, Spain, and the United Kingdom. Regulatory mandates from the EU AI Act and ECE R10 standards compress adoption timelines unevenly across these markets.
Germany
Commercial motorcycle rental platforms and courier fleets drive embedded system procurement. Germany's KBA enforces 14-18 month homologation timelines that freeze out non-compliant hardware suppliers. Bavaria's automotive supplier corridor around Munich anchors development of factory-integrated cellular-GPS modules for 2027 model year platforms.
France
Insurance companies mandate certified crash detection systems for premium touring bike coverage discounts. France's ANSM tightens electromagnetic compatibility testing protocols under ECE R10 revisions. The Île-de-France region hosts fleet operator headquarters specifying bundled telematics contracts with centralized incident analytics.
Italy
Commercial courier fleets specify voice relay redundancy to mitigate litigation exposure from delayed emergency response. Italy's Ministry of Infrastructure aligns national type-approval procedures with EU AI Act provisions for 125cc+ displacement mandates. Lombardy's motorcycle manufacturing cluster around Milan integrates automatic crash detection into premium touring platforms.
Spain
Aftermarket retrofit channels concentrate demand for Bluetooth-to-cellular adapters among 125cc-400cc touring bike owners. Spain's Directorate-General for Traffic promotes advisory e-call installation programs ahead of potential mandate expansion. Catalonia's rental operator networks consolidate procurement around vertically integrated telematics service providers.
United Kingdom
Post-Brexit regulatory divergence creates uncertainty for EU type-approved hardware suppliers seeking market access. The UK's Vehicle Certification Agency maintains parallel electromagnetic compatibility standards without automatic EU recognition. Southeast England's fleet management software vendors develop cloud-based incident logging overlays for motorcycle rental platforms.
Motorcycle E-Call Market Key Industry Players
Channel-controlling players compete with product-specialist players across embedded, aftermarket, and fleet service channels. The vendor base stratifies between automotive-tier suppliers with homologation capabilities and smartphone application developers targeting retrofit accessibility. Two strategic archetypes dominate: vertically integrated telematics providers capturing fleet contracts, and sensor-heritage automotive suppliers commanding OEM specification. Competitive moves concentrate on accelerated ECE type-approval processes and bundled service contract consolidation.
Within the automotive-tier supplier archetype, Robert Bosch GmbH and Continental occupy positions leveraging factory integration relationships with European OEMs. Among motorcycle OEMs with captive telematics development, Yamaha Motor exemplifies the smartphone application ecosystem approach bridging legacy motorcycles into connected emergency networks. Harman represents the audio-electronics heritage players extending into speaker-microphone assemblies for two-way voice relay functionality.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Bayerische Motoren Werke AG |
| Continental |
| Triumph Motorcycles |
| Honda Motor |
| Yamaha Motor |
| BMW Motorrad |
| Harman |
| RealRider |
| Others |
Cost & Logistics Intelligence
Taiwanese MEMS foundry capacity for inertial measurement units anchors upstream supply concentration, directing hardware margin pools toward vertically integrated telematics providers with captive sensor sourcing and ECE R10 pre-certification. Fleet operators absorb embedded system premiums through multi-year service contracts while individual riders in Southern Europe resist subscription fees, fragmenting pricing power across buyer archetypes.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate embedded module procurement, with hardware margins stratifying across ECE R10 certification grade, factory integration complexity, and after-sales diagnostic bundling. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified cellular-GPS stacks from Bluetooth bridge adapters and standalone battery units. Cost compression in the standalone tier is intensifying because subscription resistance forces vendors toward razor-thin hardware margins. Fleet operators demonstrate least price sensitivity due to liability-driven procurement mandates, while individual retrofit buyers in Spain and Portugal exhibit highest elasticity.
Supply Chain Analysis
Export controls on advanced MEMS fabrication equipment limit capacity expansion outside Taiwan, South Korea, and select Japanese facilities, constraining supply elasticity for multi-axis accelerometers. Hardware vendors draw from concentrated semiconductor lithography, cellular modem chipsets, and GPS receiver modules. Single-source vulnerability persists for EUV-grade MEMS etching capacity. Distribution runs through Tier 1 automotive suppliers with established KBA and ANSM homologation relationships, freezing out non-certified competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motorcycle e-call penetration sits at early-cycle expansion, with EU AI Act mandates for 125cc+ displacement creating forced-adoption tailwinds across European corridors.
For Market Incumbents: Entrench position through accelerated ECE R10 certification pipelines and captive IMU sourcing from Taiwanese foundry partners. Smartphone application ecosystems threaten embedded system margins by capturing retrofit demand; backward integration into sensor fusion algorithm development preserves differentiation against software-only entrants. For New Entrants and Emerging Players: Establish a beachhead in Spain's aftermarket Bluetooth-to-cellular adapter segment, where advisory regulatory posture and 125cc-400cc touring bike density create white-space opportunity. Cloud-based fleet incident analytics for German rental operators offers second penetration vector through subscription-based recurring revenue models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telematics service providers consolidating fleet management contracts across Mediterranean rental networks. Long-term viability hinges on regulatory mandate expansion beyond current 125cc thresholds; monitor European Commission directive timing as primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R10 Pre-Certification Investment | Accelerates KBA and ANSM approval timelines, freezing out competitors in embedded system procurement. |
| Smartphone Application Ecosystem Development | Captures legacy motorcycle owners in Spain and Portugal unwilling to modify factory electronics. |
| Cloud-Based Fleet Analytics Platform | Enables German rental operators to negotiate insurance premium discounts through centralized incident logging. |
| MEMS Foundry Partnership Consolidation | Secures Taiwanese accelerometer capacity against supply disruption from geopolitical friction. |
| Intelligent Speed Assistance Bundling | Aligns with EU AI Act provisions combining automatic emergency calling with real-time rider alerts. |
Research Approach
A standing panel of OEM platform engineers, fleet procurement directors, insurance risk assessors, and emergency dispatch system architects provided ongoing calibration across primary interview rounds. Secondary validation drew from KBA type-approval filings, ANSM electromagnetic compatibility protocols, EU AI Act regulatory texts, and cellular-V2X standardization committee records. Bottom-up hardware shipment estimates and top-down fleet contract value analysis were triangulated to anchor volume and value outputs.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling across technology tier, deployment mode, end-user category, and regional regulatory cluster. CAGRs were derived from adoption curve analysis against mandate implementation timelines. Forecast inputs incorporated fleet operator contract renewal rates and individual rider subscription attrition patterns.
Stress conditions across MEMS supply disruption severity, EU mandate scope expansion, and cellular data tariff inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation pacing and fleet procurement consolidation velocity. Material shifts in European Commission mandate timing or Taiwanese foundry export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market