
 High-Tech Logistics Market | 2026-2036
High-Tech Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
High-Tech Logistics Market Foresight
REACH compliance for battery transport and hazardous materials handling is realigning the cost-of-entry calculus for European logistics operators. Symbotic sustains technology leadership through dense robotic orchestration in grocery and retail fulfillment centers. Gatik navigates fixed-route autonomous delivery between distribution hubs and retail endpoints in North America. Delhivery dominates express parcel networks across South Asia through algorithmic route optimization and hyperlocal warehousing density.
High-tech logistics encompasses the integration of autonomous systems, sensor networks, and intelligent software platforms to manage material flow with precision below 99.5% error thresholds and sub-hour fulfillment windows. Its primary purpose centers on collapsing latency between production nodes and consumption endpoints while minimizing labor dependency in sorting, transport, and inventory verification. The robotics segment within technology anchors capital deployment, as articulated arm and AMR installations absorb warehouse labor compression mandates. Last mile delivery solutions extract premium pricing from healthcare and e-commerce end users where temperature integrity and delivery windows carry contractual penalties. Inventory management services within service type exhibit margin compression from SaaS commoditization, pushing vendors toward outcome-based contracts tied to stockout reduction.
FDA validation requirements for pharmaceutical cold chain traceability shape sensor and RFID specification standards across North American healthcare logistics networks. EMA's Annex 1 revisions on sterile product distribution force European operators into redundant temperature monitoring infrastructure with blockchain-anchored documentation. China's SAMR algorithmic accountability rules for autonomous vehicle decision logs create compliance friction for robotics platforms deployed in Sino-foreign joint ventures. Stakeholders must weigh regulatory divergence against platform standardization bets, as fragmentation between FDA, EMA, and NMPA data architectures threatens interoperability economics for multi-continental operators.
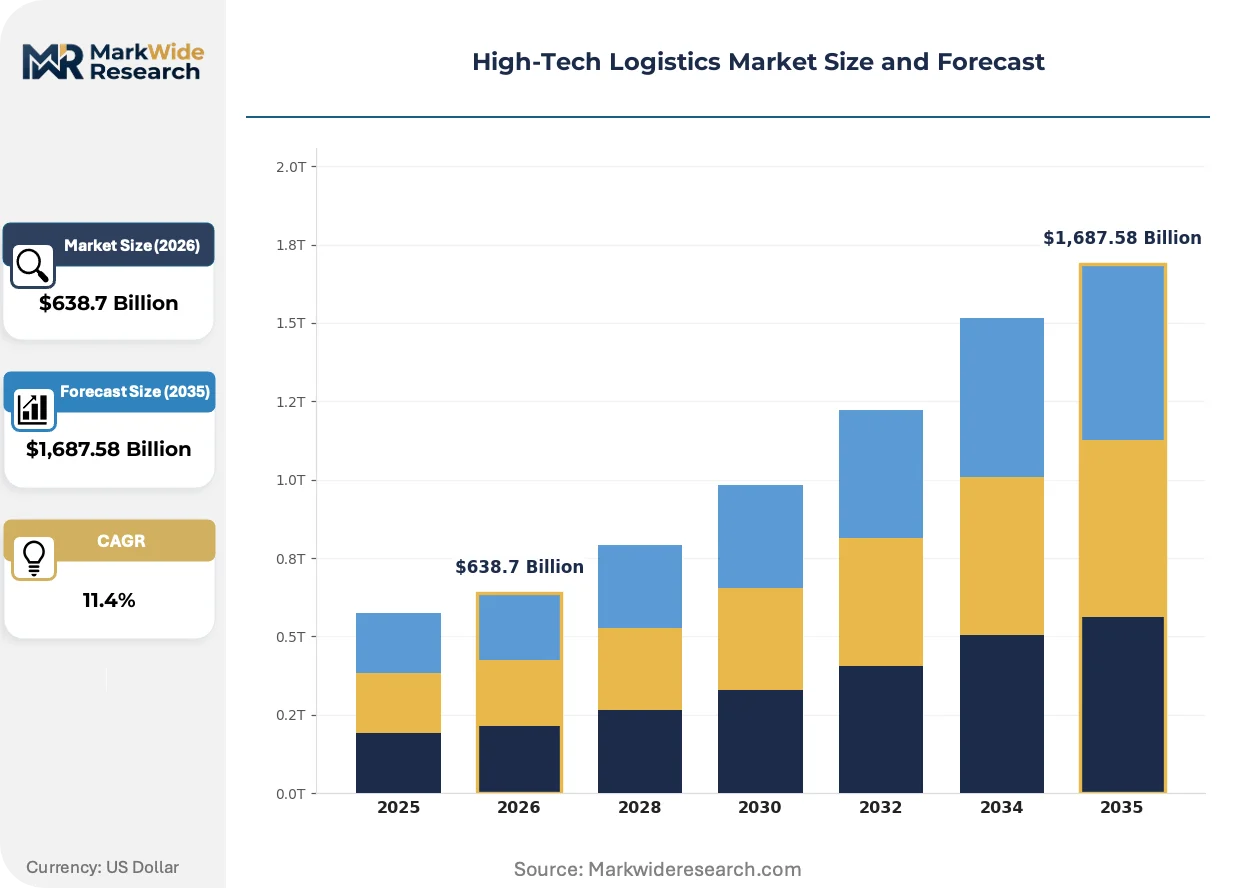
Market Dynamics
Semiconductor manufacturers in Taiwan and South Korea are compressing fulfillment windows below four hours, forcing logistics operators to deploy autonomous mobile robots and real-time inventory verification systems at capital intensity levels previously reserved for aerospace supply chains.
Growth Catalysts
- EU AI Act compliance mandates:European operators are retrofitting warehouse robotics with explainable decision-logging architectures to satisfy algorithmic accountability requirements, accelerating platform standardization across the region.
- Automotive OEM demand:German manufacturers are integrating robotics-driven fulfillment with just-in-sequence production lines, creating pull-through demand for sub-hour inventory turnover capabilities.
- LiDAR sensor cost curves:Deflation in solid-state perception hardware is enabling autonomous freight corridor pilots between Shanghai and Suzhou industrial zones without human safety drivers.
Market Restraints
- Lithium-ion battery cell supply:Cathode material concentration in Indonesian nickel processing and Chinese graphite refining creates input cost volatility for electric autonomous vehicle fleets.
- Technical limitation:Edge-case perception failure rates in snow and fog conditions above 5% prevent regulatory clearance for full autonomy in Nordic last-mile corridors.
- Regulatory friction:China's SAMR algorithmic accountability rules for autonomous vehicle decision logs create compliance friction for Sino-foreign joint venture robotics platforms.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO's tightening temperature excursion documentation requirements for biologics distribution create first-mover advantage for RFID-anchored traceability providers.
- Technology convergence:Digital twin warehouse simulation is fusing with reinforcement learning route optimization, enabling predictive disruption management before physical inventory movement.
- Brazilian agrochemical distribution:ANVISA's pending serialization mandate for crop protection products opens white space for integrated packaging-to-dock logistics platforms.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of articulated arm robotics requires hybrid mechanical-electrical-software skill sets that vocational training pipelines in Germany and Japan have not scaled to match deployment velocity.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical logistics operators face eighteen-month certification cycles for electronic signature and audit trail systems, delaying warehouse management system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Tech Logistics Market |
| Market Size in 2026 | $638.7 Billion |
| Market Size in 2035 | $1,687.58 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automation, Robotics, RFID, IoT Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding End User: E-commerce, Manufacturing, Retail, Healthcare Solution: Supply Chain Management, Last Mile Delivery, Tracking Systems, Fleet Management |
| Companies Covered | Locus Robotics, GeeK+, FourKites, Waabi, Starship Technologies, Symbotic, Delhivery, Gatik, Nuro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Tech Logistics Market Shifts & Advancements
Robotic orchestration platforms are collapsing the latency between inbound freight receipt and outbound order consolidation, compressing traditional warehouse labor models while elevating sensor fusion and edge computing infrastructure to core competitive differentiators.
Autonomous mobile robots equipped with simultaneous localization and mapping capabilities are integrating dense storage retrieval with dynamic slotting optimization. Third-party logistics providers in the Netherlands and Singapore are deploying these systems at scale, enabling facility throughput gains without proportional warehouse footprint expansion. The technology is integrating predictive maintenance algorithms that preempt actuator failures before picking accuracy degrades below contractual thresholds.
EMA's Annex 1 revisions on sterile product distribution are mandating redundant temperature monitoring infrastructure with blockchain-anchored documentation. European operators serving biologics manufacturers are retrofitting cold chain lanes with distributed ledger verification nodes. The regulation is compressing vendor qualification timelines and disqualifying logistics providers lacking real-time data immutability capabilities.
Healthcare procurement teams are unbundling transportation from inventory management, awarding separate contracts to specialized cold chain carriers and SaaS-native visibility platforms. This disintermediation is displacing integrated 3PL relationships in North American pharmaceutical distribution. The shift is most visible in oncology biologics, where hospital systems now directly contract with temperature-controlled parcel specialists while maintaining independent warehouse management software licenses.
High-Tech Logistics Market Segmentation
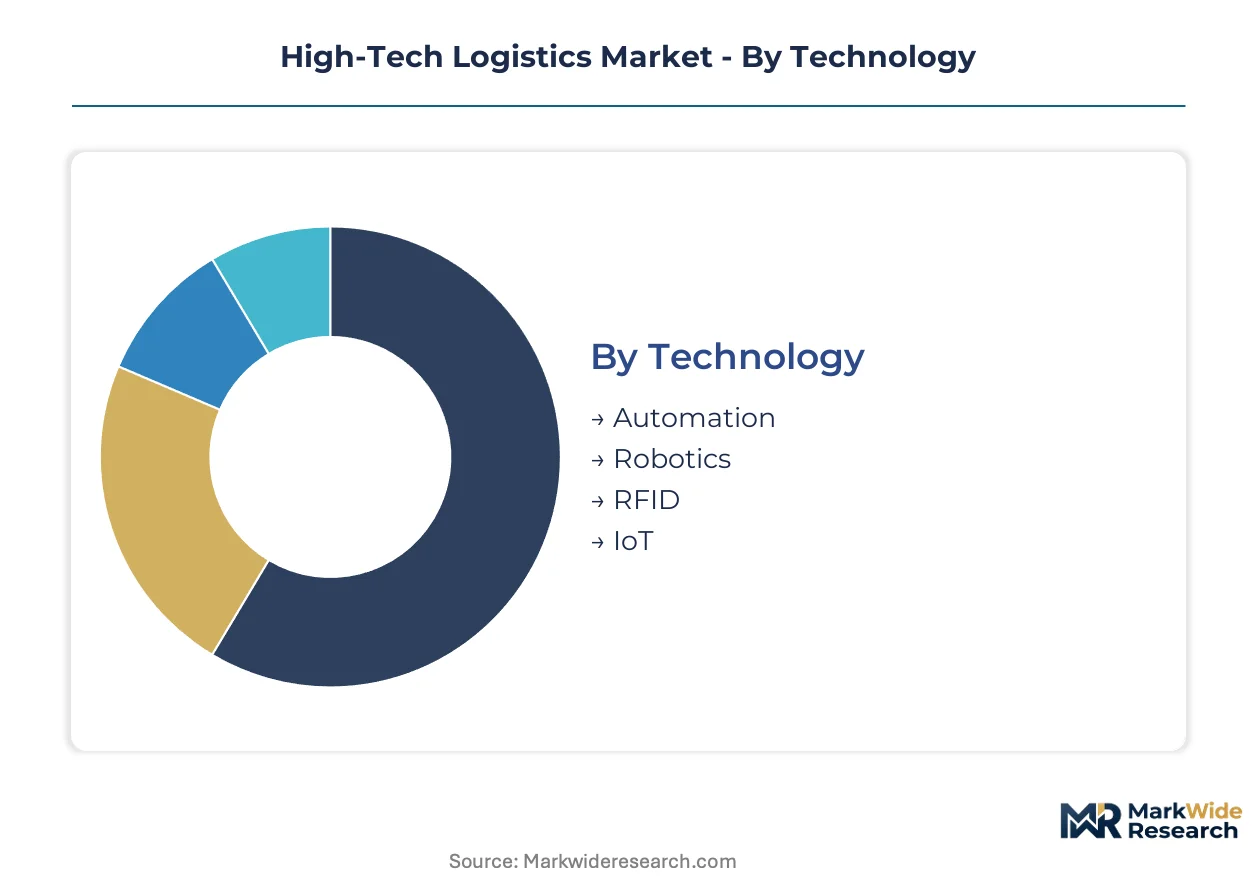
High-tech logistics segmentation reveals distinct compliance architectures across technology and service categories. FDA 21 CFR Part 11 validation requirements for pharmaceutical cold chains sit alongside EU AI Act algorithmic accountability mandates for warehouse robotics, fragmenting vendor qualification pathways.
Technology:
FDA validation requirements for pharmaceutical traceability systems and EU AI Act explainability mandates create divergent certification burdens across technology segments, with healthcare-facing deployments requiring dual-track compliance investments.
- Robotics:Articulated arm and AMR installations integrate simultaneous localization and mapping with predictive maintenance algorithms. Semiconductor manufacturers in Taiwan and South Korea deploy these systems for sub-four-hour fulfillment windows, absorbing capital intensity levels previously reserved for aerospace supply chains.
- Automation:Dense robotic orchestration platforms compress latency between inbound freight receipt and outbound order consolidation. German automotive OEMs integrate these systems with just-in-sequence production lines, creating pull-through demand for sub-hour inventory turnover capabilities.
- RFID:EMA Annex 1 sterile product distribution mandates drive blockchain-anchored temperature monitoring infrastructure.
- IoT:Sensor fusion networks enable edge computing infrastructure for real-time inventory verification.
Robotics sits at the top of the volume ranking, with automation climbing the fastest.
Service Type:
Margin structures diverge sharply across service categories, with outcome-based contracts displacing traditional SaaS pricing in inventory management while transportation commands premium pricing from temperature-controlled healthcare segments.
- Transportation:Autonomous freight corridors and fixed-route delivery systems integrate LiDAR perception hardware with regulatory-compliant decision logging. North American healthcare procurement teams unbundle transportation from inventory management, awarding separate contracts to specialized cold chain carriers.
- Warehousing:Dense storage retrieval systems with dynamic slotting optimization enable facility throughput gains without proportional footprint expansion. Third-party logistics providers in the Netherlands and Singapore deploy these at scale.
- Inventory Management:SaaS commoditization pressures margins, pushing vendors toward outcome-based contracts tied to stockout reduction.
- Freight Forwarding:Algorithmic route optimization absorbs hyperlocal warehousing density requirements across South Asian express parcel networks.
Transportation captures the highest margin tier, with warehousing gaining share fastest.
End User:
End-user concentration determines sensor specification standards, with FDA-validated pharmaceutical cold chains requiring redundant temperature monitoring that e-commerce fulfillment centers can bypass.
- Healthcare:Oncology biologics distribution demands FDA-validated electronic signature systems and blockchain-anchored documentation. Hospital systems now directly contract with temperature-controlled parcel specialists while maintaining independent warehouse management software licenses.
- E-commerce:Sub-hour fulfillment windows drive robotics-driven fulfillment center deployment with real-time inventory verification systems.
- Manufacturing:Just-in-sequence production lines integrate with automated warehousing for semiconductor and automotive component flow.
- Retail:Grocery fulfillment centers deploy dense robotic orchestration for temperature-sensitive inventory handling.
Healthcare commands premium pricing tiers, with e-commerce expanding most quickly.
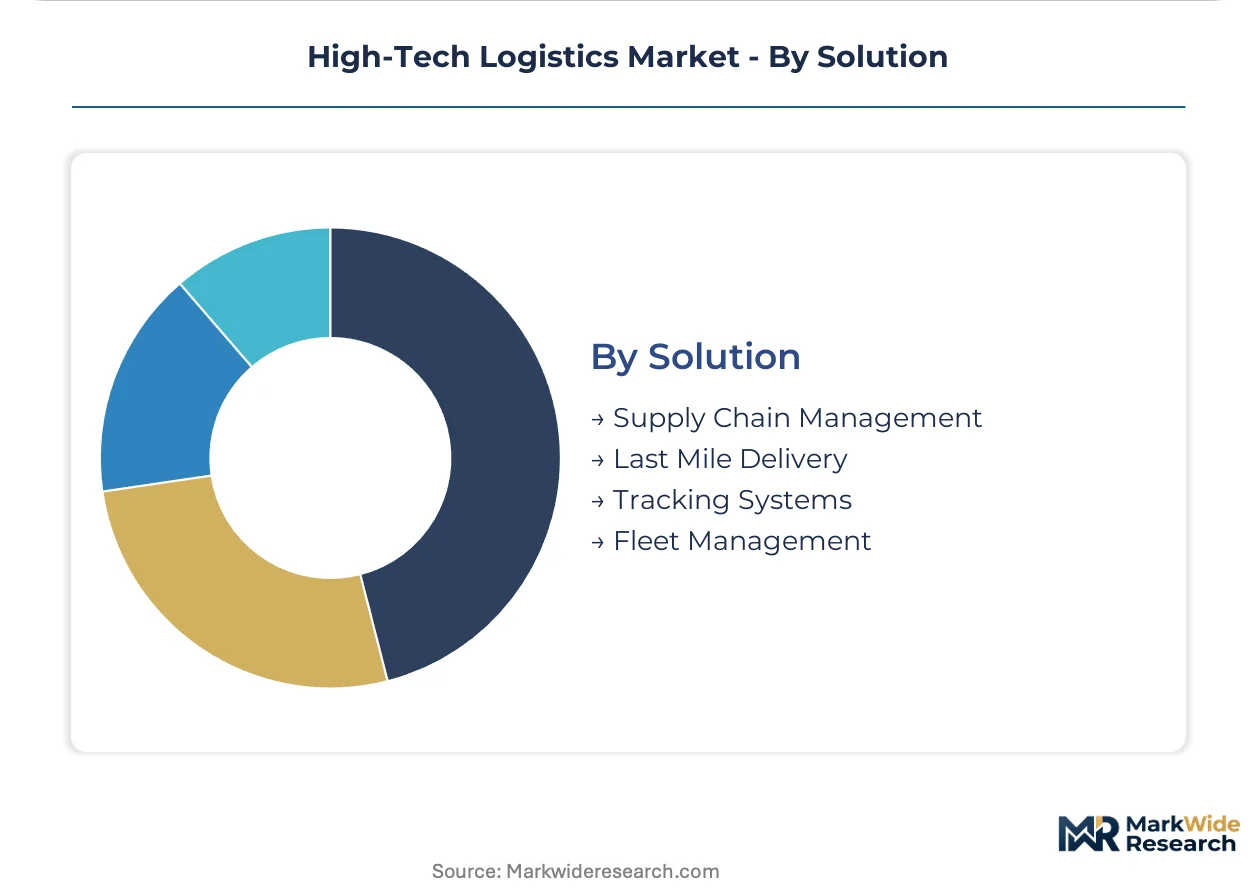
Solution:
Solution architectures fragment between predictive disruption management platforms and compliance-heavy tracking systems, with pharmaceutical traceability requirements forcing specialization that generalist supply chain management vendors cannot match.
- Last Mile Delivery:Autonomous mobile robots navigate fixed routes between distribution hubs and retail endpoints. Edge-case perception failure rates in snow and fog conditions above 5% prevent regulatory clearance for full autonomy in Nordic corridors.
- Supply Chain Management:Digital twin warehouse simulation fuses with reinforcement learning route optimization, enabling predictive disruption management before physical inventory movement.
- Tracking Systems:RFID-anchored traceability platforms capture CDSCO tightening requirements for Indian pharmaceutical cold chain temperature excursion documentation.
- Fleet Management:Electric autonomous vehicle fleets face lithium-ion battery cell supply volatility from Indonesian nickel processing and Chinese graphite refining concentration.
Supply chain management anchors enterprise spending, with last mile delivery showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mechatronics technicians and Taiwanese semiconductor engineers anchor the geography's talent density, concentrating automation expertise in industrial corridors where sub-hour fulfillment windows demand precision below 99.5% error thresholds.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg integrate robotics-driven fulfillment with just-in-sequence production lines, pulling through demand for real-time inventory turnover. KBA vehicle autonomy regulations and EU AI Act algorithmic accountability mandates force warehouse robotics retrofits with explainable decision-logging architectures. The Stuttgart industrial corridor hosts dense robotic orchestration deployments serving automotive component flow.
United States
FDA-validated pharmaceutical cold chains in the Northeast and California command premium pricing from healthcare procurement teams unbundling transportation from inventory management. FDA 21 CFR Part 11 validation timelines stretch eighteen months for electronic signature and audit trail systems, delaying warehouse upgrades. The Boston-Cambridge biotech cluster drives blockchain-anchored temperature monitoring infrastructure for oncology biologics distribution.
China
Semiconductor manufacturers in the Yangtze River Delta compress fulfillment windows below four hours, deploying autonomous mobile robots at capital intensity levels previously reserved for aerospace. SAMR algorithmic accountability rules for autonomous vehicle decision logs create compliance friction for Sino-foreign joint venture robotics platforms. The Shanghai-Suzhou industrial zone pilots autonomous freight corridors using deflated solid-state LiDAR perception hardware.
South Korea
Memory chip and display panel producers in Gyeonggi Province demand sub-four-hour fulfillment cycles, forcing logistics operators into real-time inventory verification systems. GB standards alignment for cross-border autonomous vehicle deployment intersects with domestic smart logistics infrastructure investments. The Suwon-Pyeongtaek semiconductor belt concentrates AMR installations with predictive maintenance algorithms.
India
Express parcel networks across South Asia absorb hyperlocal warehousing density requirements through algorithmic route optimization. CDSCO tightening temperature excursion documentation requirements for biologics distribution creates first-mover advantage for RFID-anchored traceability providers. The Mumbai-Pune pharmaceutical corridor and Bangalore e-commerce fulfillment hubs drive cold chain infrastructure expansion.
High-Tech Logistics Market Competitive Landscape
The competitive structure tilts toward robotics-native platform providers with dense orchestration capabilities. Consolidation pressures favor vendors bundling warehouse automation with last-mile autonomous delivery, while SaaS-commoditized inventory management segments fragment into outcome-based pricing models. Three archetypes dominate: semiconductor supply chain specialists, pharmaceutical cold chain validators, and grocery-retail fulfillment orchestrators. M&A activity concentrates on sensor fusion and edge computing acquisitions; strategic partnerships bridge LiDAR cost deflation with regulatory-compliant decision logging.
Among North American autonomous freight developers, Waabi and Gatik occupy positions at the fixed-route validation frontier, while Symbotic anchors the dense robotic orchestration tier for grocery and retail fulfillment centers. These three exemplify divergent platform bets—perception-heavy long-haul autonomy, constrained-geometry hub-to-retail delivery, and warehouse-native robotic density—each representing distinct capital intensity and regulatory clearance pathways.
| Leading Market Players |
|---|
| Locus Robotics |
| GeeK+ |
| FourKites |
| Waabi |
| Starship Technologies |
| Symbotic |
| Delhivery |
| Gatik |
| Nuro |
| Others |
Supply & Pricing Matrix
Captive integration into semiconductor-grade fulfillment infrastructure anchors both supply security and pricing power for operators serving Taiwan and South Korean chip manufacturers. This vertical control over AMR deployment and real-time inventory systems insulates premium-tier vendors from SaaS commoditization pressures while forcing mid-market competitors into outcome-based contract structures.
Pricing Analysis
Bundled robotics-orchestration contracts command premium positioning against unbundled transportation-only services across healthcare and e-commerce segments. Pricing stratifies across FDA-validated pharmaceutical tiers, EU AI Act-compliant automation tiers, and standard fulfillment tiers, with certification level and geographic delivery cost as primary differentiation drivers. Cost compression in inventory management SaaS is intensifying because of platform commoditization, squeezing margins for pure-software vendors while robotics-native providers maintain pricing resilience. Healthcare procurement teams exhibit lowest price sensitivity due to contractual penalty structures for temperature excursions, whereas retail fulfillment centers face acute pressure to reduce per-unit handling costs.
Supply Chain Analysis
Freight cost volatility from lithium-ion battery cell logistics concentrates supply risk for electric autonomous vehicle fleets dependent on Indonesian nickel processing and Chinese graphite refining. Hardware sourcing draws from Taiwan for semiconductor components, Germany for precision mechatronics, and China for sensor assembly, with cathode material concentration creating single-source vulnerability for battery-dependent robotics platforms. Distribution runs through third-party logistics providers in the Netherlands and Singapore for dense storage retrieval systems, while direct OEM relationships dominate automotive and pharmaceutical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where semiconductor manufacturers and pharmaceutical cold chain operators are shifting procurement specifications toward sub-99.5% error thresholds and blockchain-anchored traceability, disqualifying generalist vendors.
For Market Incumbents: Anticipate margin compression from LiDAR cost deflation by deepening captive production of sensor fusion hardware and securing exclusive mechatronics technician pipelines in Germany and Japan. Defend against disintermediation threats from healthcare procurement teams unbundling transportation and inventory management by embedding outcome-based guarantees into warehouse robotics contracts. For New Entrants and Emerging Players: CDSCO tightening temperature excursion documentation requirements in India opens a window for RFID-anchored traceability providers to capture first-mover position in the Mumbai-Pune pharmaceutical corridor. Target Brazilian agrochemical distribution ahead of ANVISA's pending serialization mandate, deploying integrated packaging-to-dock logistics platforms through joint venture structures with established cold chain operators. For Investors and Strategic Acquirers: Roll-up economics work for robotics-native platform providers with dense orchestration capabilities because SaaS-commoditized inventory management segments are fragmenting into outcome-based pricing models that favor scaled automation vendors. Monitor FDA 21 CFR Part 11 validation timeline extensions as the inflection signal for warehouse management system upgrade cycles and associated robotics retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Hardware Integration | Captive LiDAR production insulates margins from solid-state perception cost deflation curves. |
| EU AI Act Compliance Certification | Explainable decision-logging architectures unlock European automotive OEM contract eligibility. |
| Pharmaceutical Cold Chain Validation | FDA 21 CFR Part 11 certification enables oncology biologics distribution premium pricing. |
| Mechatronics Technician Pipeline Development | Hybrid skill training programs in Stuttgart and Suwon reduce maintenance cost inflation. |
| Blockchain-Anchored Traceability Deployment | EMA Annex 1 compliance qualifies vendors for European sterile product distribution networks. |
Research Methodology
Direct dialogue with warehouse operations directors, robotics platform engineers, pharmaceutical supply chain managers, and cold chain logistics procurement leads grounded qualitative insights in operator-level constraints and investment timelines. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 1 revision texts, EU AI Act implementation specifications, and SAMR autonomous vehicle accountability rules. Bottom-up installation data for AMR and articulated arm deployments triangulated against top-down capital expenditure disclosures from semiconductor and automotive OEMs.
Bottom-up segment modeling tracked robotics, automation, RFID, and IoT technology categories against transportation, warehousing, inventory management, and freight forwarding service types across healthcare, e-commerce, manufacturing, and retail end users. Top-down macro validation incorporated EU AI Act compliance cost estimates, LiDAR sensor price curves, and lithium-ion battery supply concentration indices. CAGRs were derived from regression analysis of historical fulfillment window compression rates and capital intensity benchmarks from aerospace supply chain parallels.
Revisions become necessary when regulatory divergence between FDA, EMA, and NMPA data architectures accelerates, when edge-case perception failure rates in adverse weather conditions delay autonomous vehicle clearance timelines, or when Indonesian nickel export restrictions disrupt battery cell supply chains. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market