
 Driver Alert System Market | 2026-2036
Driver Alert System Market Size, Share, and Industry Trends Forecast 2026-2036
Driver Alert System Market Analytics
Level 2+ autonomy-grade driver monitoring is redrawing competitive boundaries in the alert system sector. Robert Bosch GmbH leverages its integrated sensor portfolio to dominate OEM supply contracts for camera-based occupant monitoring. Continental AG anchors European production through its specialized focus on infrared eye-tracking modules for commercial vehicle cabins. Mobileye differentiates by embedding alert algorithms directly within its autonomous driving compute platforms, blurring the line between standalone safety and full self-driving stacks.
A driver alert system comprises sensor arrays, signal processors, and human-machine interface outputs designed to detect operator impairment through ocular behavior analysis, steering pattern deviation, or lane departure frequency, with typical camera systems operating at frame rates exceeding frames per second for real-time drowsiness classification. Camera-based technology leads unit shipments due to cost scalability and Euro NCAP integration mandates, while LiDAR-based architectures represent the fastest-growing segment as automakers pursue multimodal redundancy for Level 3 deployments. Integrated systems command the deepest margin pools by bundling alert functions within broader ADAS controller units, whereas standalone alert modules face commoditization pressure from tier-one suppliers.
NHTSA's pending rulemaking on advanced impaired-driving prevention technology and the EU's General Safety Regulation mandating driver drowsiness and attention warning systems reshape product roadmaps and certification requirements for any supplier accessing transatlantic vehicle platforms. Euro NCAP's 2023 protocol updates rewarding direct driver monitoring over indirect steering-based detection accelerate camera-with-IR adoption timelines across European OEM portfolios. Stakeholders must weigh the capital intensity of multimodal sensor fusion against the risk of regulatory fragmentation as China MIIT advances its own GB standards for intelligent driving safety systems.
Market Dynamics
Euro NCAP's 2023 protocol updates mandating direct driver monitoring over indirect steering-based detection are compressing adoption timelines and forcing tier-one suppliers to reconfigure sensor fusion architectures around infrared-capable camera modules.
Growth Catalysts
- EU General Safety Regulation:Mandates driver drowsiness and attention warning systems across all new vehicle types, creating a compliance-driven demand floor for OEM integration.
- Commercial fleet liability reduction:North American trucking operators deploy camera-based drowsiness detection to lower insurance premiums and exposure from fatigue-related incidents.
- Infrared eye-tracking modules:Advancements in low-light ocular behavior analysis enable real-time impairment classification without cabin illumination interference.
Market Restraints
- Semiconductor supply concentration:Image sensor and processor shortages in East Asian foundries create lead time volatility for camera module production.
- Multimodal fusion cost structure:LiDAR-based redundancy architectures for Level 3 deployments carry sensor hardware costs that constrain mass-market penetration.
- Regulatory fragmentation risk:Divergent certification requirements between NHTSA pending rulemaking and China MIIT GB standards force parallel development tracks.
Strategic Opportunities
- Aftermarket retrofit channels:Commercial vehicle fleets in Brazil and India present underpenetrated demand for standalone alert systems outside OEM integration cycles.
- Autonomous driving compute convergence:Embedding drowsiness algorithms within centralized ADAS controllers reduces hardware duplication and captures margin from sensor consolidation.
- Outcome-based fleet safety contracts:Telematics providers bundle driver monitoring with usage-based insurance, creating recurring revenue streams beyond equipment sales.
Industry Challenges
- Embedded vision engineering scarcity:Shortage of specialists in real-time image processing and neural network optimization for edge deployment constrains R&D velocity.
- Functional safety certification timelines:ISO 26262 ASIL-B compliance for camera-based monitoring systems extends product validation cycles by months.
- Legacy vehicle integration complexity:Retrofitting CAN bus architectures in older commercial fleets requires custom gateway development for alert system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver Alert System Market |
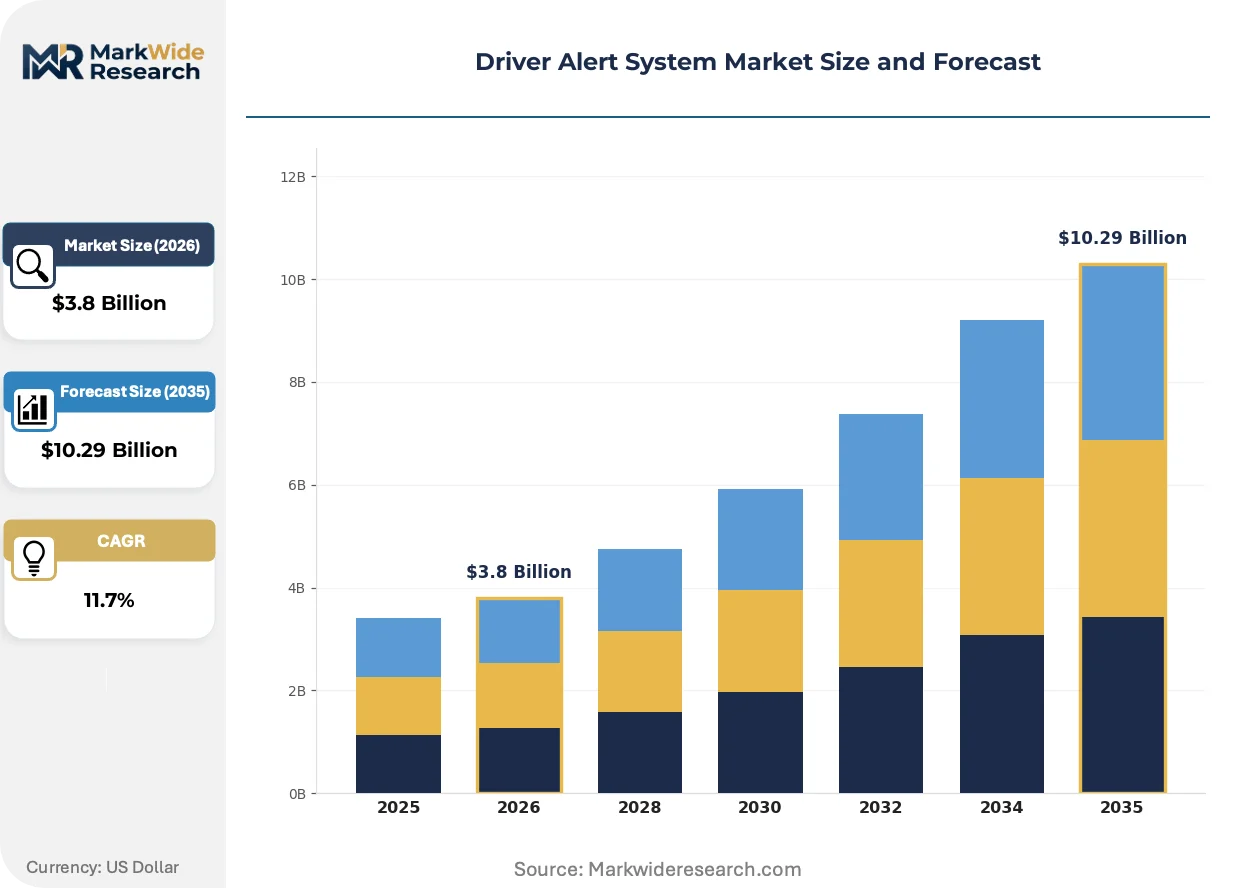
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Radar-Based, LiDAR-Based, Sensor-Based Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Emergency Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Manufacturers Integration Level: Standalone Systems, Integrated Systems, Advanced Driver Assistance Systems, Hybrid Solutions |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Aptiv PLC, Valeo SA, Magna International Inc., Mobileye, ZF Friedrichshafen AG, Seeing Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver Alert System Market Evolving Landscape
Sensor fusion architectures are fragmenting into competing technical philosophies, with suppliers betting on divergent combinations of camera, radar, and biometric inputs to satisfy evolving safety mandates while managing bill-of-materials compression.
Edge-based neural inference is decomposing traditional signal processing hierarchies in driver monitoring systems. Tier-one suppliers deploy on-chip machine learning accelerators to execute drowsiness classification without cloud dependency. This shift compresses latency budgets and reduces data transmission costs, enabling OEMs to meet Euro NCAP real-time response requirements without redundant compute layers.
NHTSA's pending advanced impaired-driving prevention technology rulemaking is accelerating pre-competitive collaboration between domestic automakers and sensor suppliers. The proposed mandate for passive alcohol detection integration is forcing redesigns of cabin monitoring architectures to accommodate additional biometric channels. Commercial vehicle segments face the steepest compliance curves due to higher exposure thresholds in federal safety scoring.
Fleet procurement patterns favor integrated safety platform subscriptions over discrete hardware purchases. Large trucking operators negotiate enterprise-wide driver monitoring through telematics providers, displacing standalone alert module vendors from direct relationships. This channel consolidation is most pronounced in Germany and the United States, where fleet management software penetration exceeds other developed markets.
Driver Alert System Market Segmentation
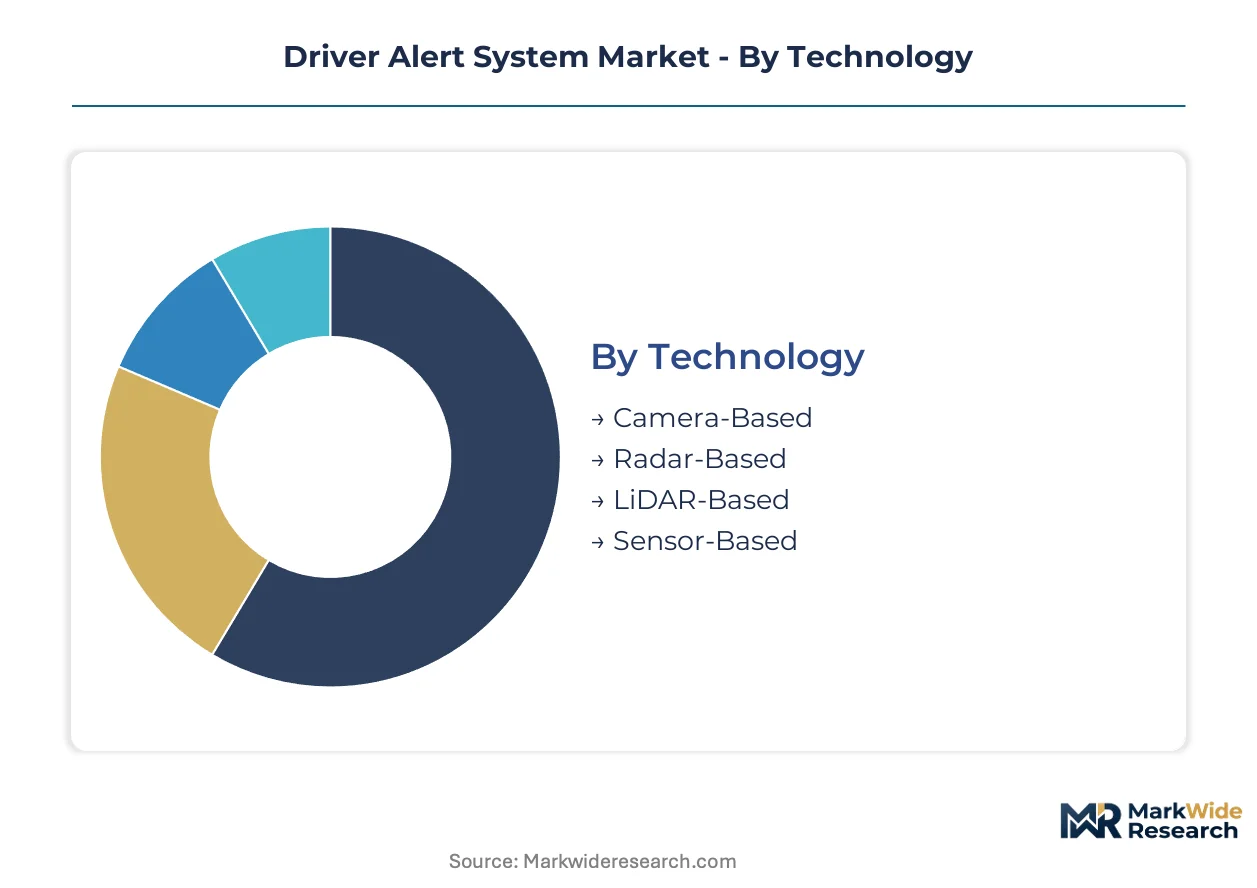
Technology choices in driver alert systems determine regulatory compliance pathways and hardware cost structures. Application segments diverge sharply between consumer-grade convenience features and commercial fleet liability management requirements.
Technology:
Margin pools concentrate in multimodal sensor fusion where infrared-capable camera modules command premium positioning against single-sensor alternatives.
- Camera-Based:Infrared eye-tracking modules process ocular behavior at frame rates exceeding real-time classification thresholds. Euro NCAP direct monitoring mandates in Germany and France drive factory integration into premium vehicle platforms, displacing steering-based indirect detection.
- LiDAR-Based:Multimodal redundancy architectures combine depth sensing with visual inputs for Level 3 autonomy-grade impairment classification. Automakers in Japan and South Korea pursue this sensor stack despite hardware cost constraints on mass-market penetration.
- Radar-Based:Cabin occupancy detection through micro-Doppler signatures enables presence verification without optical privacy concerns.
- Sensor-Based:Steering angle and lane departure frequency analysis provides legacy fallback for indirect drowsiness estimation.
The dominant share belongs to Camera-Based systems, while LiDAR-Based architectures are expanding most quickly through autonomous driving platform convergence.
Application:
Volume distribution tracks vehicle production scale, with commercial segments offering superior lifetime value through recurring fleet safety subscriptions.
- Commercial Vehicles:North American trucking operators deploy camera-based drowsiness detection to satisfy insurance underwriting requirements and reduce fatigue-related liability exposure. Fleet management software providers bundle monitoring with usage-based coverage, creating recurring revenue beyond hardware deployment.
- Passenger Vehicles:Euro NCAP safety rating protocols mandate direct driver monitoring across all new vehicle types sold in European Union member states. OEMs integrate infrared-capable modules at factory level to secure five-star certification thresholds.
- Emergency Vehicles:First responder fleets require impairment detection compatible with high-stress operational cadences and irregular shift patterns.
- Motorcycles:Helmet-integrated or handlebar-mounted alert modules address rider fatigue in long-distance touring and delivery applications.
Commercial Vehicles capture the deepest margin pools through enterprise procurement, while Passenger Vehicles deliver unit volume scale across OEM integration cycles.
End User:
Channel structure determines pricing power, with direct fleet relationships displacing discrete module vendors through platform subscription models.
- Fleet Operators:Large trucking enterprises negotiate enterprise-wide driver monitoring through telematics providers in the United States and Germany. Outcome-based safety contracts tie equipment deployment to insurance premium reductions and incident rate improvements.
- OEMs:Factory integration demands ISO 26262 ASIL-B compliance and extended validation cycles for camera-based monitoring systems. Tier-one suppliers compete for platform supply contracts through integrated sensor portfolio breadth.
- Aftermarket Providers:Retrofit channels serve commercial vehicle fleets in Brazil and India outside OEM production cycles.
- Vehicle Manufacturers:Assembly line integration of alert functions within broader ADAS controller units reduces hardware duplication.
Fleet Operators are gaining procurement influence fastest, while OEMs retain volume concentration through factory integration mandates.
Integration Level:
System architecture choices separate premium bundled offerings from commoditized standalone modules facing tier-one supplier compression.
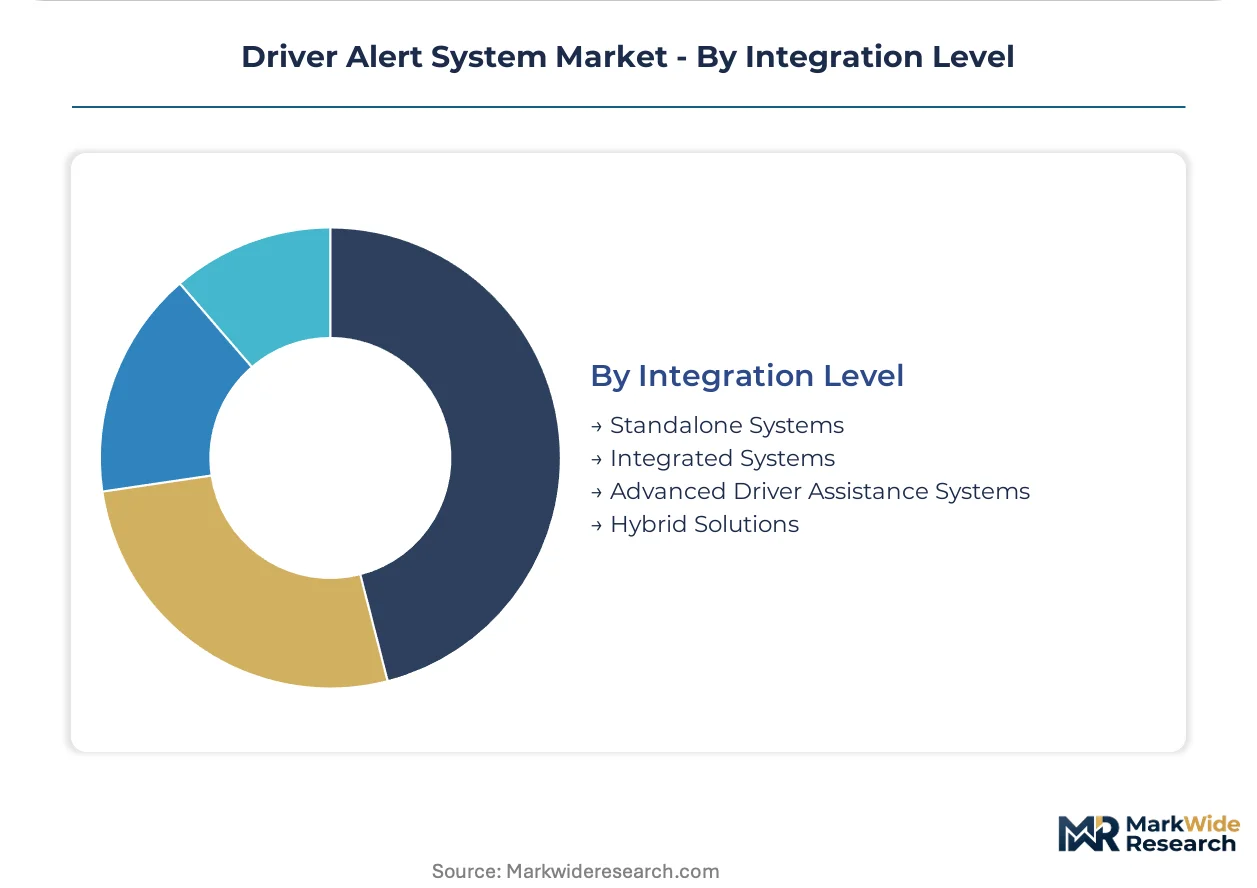
- Integrated Systems:Bundling alert functions within centralized ADAS controllers captures margin from sensor consolidation and reduces hardware duplication. Edge-based neural inference on machine learning accelerators executes drowsiness classification without cloud dependency.
- Advanced Driver Assistance Systems:Convergence with autonomous driving compute platforms embeds impairment algorithms within full self-driving stacks. Mobileye and similar suppliers blur boundaries between standalone safety and Level 2+ autonomy features.
- Standalone Systems:Discrete alert modules face pricing pressure as tier-one suppliers push integrated alternatives.
- Hybrid Solutions:Combinations of embedded and cloud-connected processing balance latency requirements with over-the-air update capabilities.
Integrated Systems hold the dominant revenue position, while Advanced Driver Assistance Systems are climbing the fastest through autonomy platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in driver alert systems favor manufacturing clusters with integrated automotive supply chains. Germany and Japan maintain net export positions in camera-based monitoring modules, while the United States and China absorb substantial import volumes to satisfy fleet retrofit demand and OEM integration mandates.
United States
NHTSA's pending advanced impaired-driving prevention technology rulemaking accelerates domestic fleet procurement of drowsiness detection systems. Commercial trucking operators across Texas and the Midwest deploy camera-based monitoring to satisfy insurance underwriting requirements. Detroit's automotive supplier corridor anchors North American production of integrated ADAS controllers bundling alert functions.
Germany
Euro NCAP's direct driver monitoring mandates compress adoption timelines for infrared-capable camera modules. The EU General Safety Regulation creates compliance-driven demand across all new vehicle categories. Stuttgart and Munich host dense supplier ecosystems where Bosch, Continental, and ZF compete for OEM platform contracts tied to premium vehicle production.
China
MIIT's advancing GB standards for intelligent driving safety systems establish parallel certification requirements distinct from Euro NCAP protocols. Domestic automakers in Shanghai and Shenzhen pursue multimodal sensor fusion architectures for Level 3 autonomy deployments. Local module suppliers capture share in camera-based systems serving mass-market passenger vehicle segments.
Japan
METI's vehicle safety technology roadmaps emphasize impairment detection compatible with aging driver demographics. Automakers in Toyota City and Yokohama integrate alert algorithms within centralized autonomous driving compute platforms. Domestic suppliers specialize in compact infrared eye-tracking modules optimized for right-hand-drive cabin architectures.
South Korea
Korea's national automotive safety agency aligns testing protocols with Euro NCAP benchmarks to preserve export market access. Hyundai and Kia production bases near Seoul and Busan source camera modules from domestic tier-one suppliers. Local component makers expand capacity for edge-based neural inference accelerators executing real-time drowsiness classification.
Driver Alert System Market Competitive Landscape
Listed leaders compete with private specialists across sensor fusion architectures and OEM integration depth. Tier-one automotive suppliers dominate factory-fit contracts through integrated ADAS controller portfolios, while standalone alert module vendors face margin compression from bundled alternatives. Two strategic archetypes define competitive positioning: diversified conglomerates leveraging sensor portfolio breadth, and focused specialists concentrating on infrared eye-tracking or edge-based neural inference. Capacity expansion in East Asian foundries and strategic partnerships around autonomous driving compute convergence represent the dominant competitive moves reshaping supply relationships.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG occupy positions defined by integrated manufacturing depth across multiple sensor categories. Bosch's Stuttgart-based operations exemplify the supplier archetype competing through factory-level OEM integration contracts. Continental AG represents European production anchoring for infrared-capable camera modules. Mobileye sits within the autonomy-platform convergence archetype, embedding alert functions within centralized compute stacks rather than standalone hardware modules.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Aptiv PLC |
| Valeo SA |
| Magna International Inc. |
| Mobileye |
| ZF Friedrichshafen AG |
| Seeing Machines |
| Others |
Value Network & Pricing Analysis
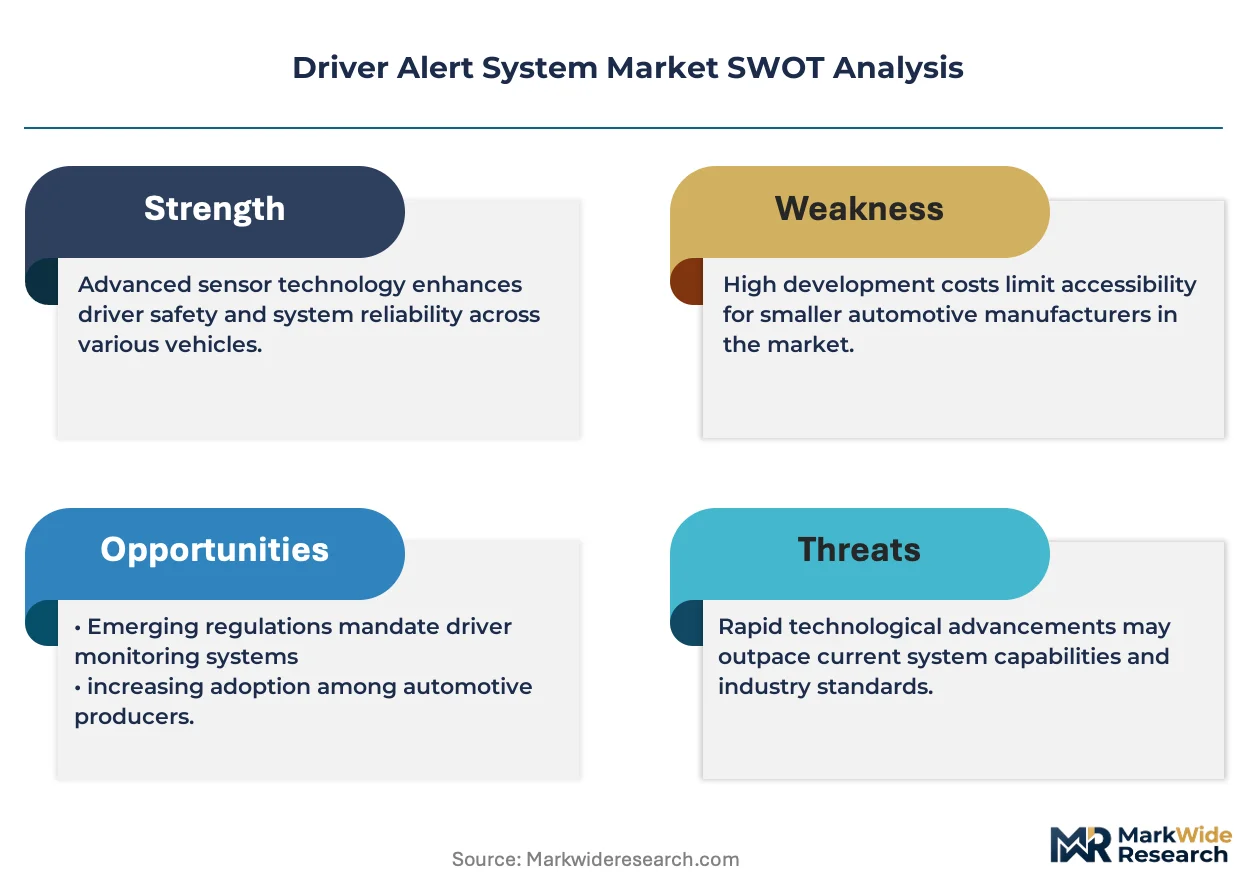
Twenty-four-week lead times for infrared-capable image sensors from East Asian foundries concentrate pricing power among tier-one suppliers with pre-allocated wafer capacity, while fleet buyers face take-it-or-leave-it terms on integrated ADAS controller bundles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 26262 ASIL-B certification grade and volume procurement scale. Cost compression in standalone alert modules is intensifying because tier-one suppliers bundle alert functions within broader ADAS controllers. Fleet operators demonstrate highest price sensitivity due to enterprise-wide procurement leverage, while premium passenger vehicle OEMs absorb certification premiums without volume negotiation.
Supply Chain Analysis
Strategic stockpiling of image sensors and neural inference accelerators dominates inventory strategy over just-in-time approaches, given foundry allocation volatility. Manufacturing concentrates in Germany, Japan, and South Korea for camera modules and edge-compute components. Supply chains draw from specialized CMOS image sensors, infrared emitters, and machine learning accelerators. Single-source vulnerability in advanced node semiconductor fabrication creates structural risk. Distribution runs through tier-one automotive supplier networks into OEM assembly lines and telematics provider channels for fleet retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory divergence between Euro NCAP direct monitoring mandates and NHTSA pending impaired-driving rulemaking creates parallel certification niches for specialized suppliers.
For Market Incumbents: Shield factory-fit contracts by deepening captive supply of infrared eye-tracking modules and accelerating ISO 26262 ASIL-D certification investment ahead of regulatory escalation. Threat substitution from autonomy-platform convergence by Mobileye-style embedded alert algorithms demands sensor portfolio breadth as defense. Capacity addition in South Korean foundries secures wafer allocation against semiconductor supply concentration risk. For New Entrants and Emerging Players: Aftermarket retrofit service gaps in Brazilian and Indian commercial fleets present white-space entry points where OEM integration cycles exclude legacy vehicle operators. Telematics platform partnerships offer the most penetrable channel structure. Target outcome-based fleet safety contracts bundling hardware deployment with usage-based insurance integration as the specific go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because Euro NCAP and NHTSA mandates create irreversible demand floors regardless of autonomous driving timeline slippage. Acquisition target archetype: edge-based neural inference specialists with automotive functional safety certification. Signal to watch is NHTSA final rule publication triggering fleet procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Infrared Camera Module Capacity Expansion | Secures wafer allocation from East Asian foundries for Euro NCAP compliance timelines. |
| Edge-Based Neural Inference Acquisition | Captures machine learning accelerator talent scarce in automotive embedded vision engineering. |
| Telematics Platform Partnership | Displaces standalone alert vendors through bundled fleet safety subscription models. |
| ISO 26262 ASIL-B Certification Investment | Unlocks OEM factory integration contracts requiring extended validation cycle completion. |
| Aftermarket Retrofit Channel Development | Addresses underpenetrated demand in Brazil and India outside OEM production cycles. |
Research Methodology
Desk research of automotive production databases, regulatory filing repositories, and tier-one supplier technical disclosures preceded structured interviews with OEM platform engineers, fleet procurement directors, tier-one ADAS controller product managers, and telematics provider safety solution leads. Primary fieldwork combined with secondary validation from Euro NCAP protocol documentation, NHTSA rulemaking dockets, and MIIT GB standard drafts. Bottom-up unit shipment modeling triangulated against top-down OEM integration pipeline analysis across the projection horizon.
Variance decomposition across technology segments, application categories, and regional regulatory clusters shaped the analytical framework. Segmentation dimensions modeled include camera versus LiDAR versus radar technology stacks, commercial versus passenger vehicle applications, integrated versus standalone system architectures, and OEM versus fleet versus aftermarket channel structures. CAGRs derived from regression against vehicle production forecasts and regulatory mandate phase-in schedules. Industry-specific inputs encompass Euro NCAP safety rating protocol weightings and fleet insurance underwriting requirement evolution.
Forecasts assume regulatory continuity in EU General Safety Regulation implementation, NHTSA advanced impaired-driving prevention technology rulemaking, and China MIIT GB standards advancement; material policy shifts would require re-modeling. Revision becomes warranted when semiconductor supply concentration or regulatory fragmentation risk crosses threshold levels affecting tier-one supplier capacity allocation or parallel certification cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market