
 ICE Start and Stop System Market | 2026-2036
ICE Start and Stop System Market Size, Share, and Industry Trends Forecast 2026-2036
ICE Start and Stop System Market Foresight
Aftermarket service revenue is reconfiguring margin pools away from pure component sales toward predictive maintenance and software calibration contracts. Valeo SA leverages its European manufacturing footprint to anchor battery-based system supply for passenger vehicle programs. Robert Bosch GmbH dominates sensor integration and microcontroller architectures across multiple OEM platforms. Denso Corporation specializes in thermal-optimized battery management systems for hybrid start-stop configurations.
An ICE start and stop system automatically shuts down and restarts the internal combustion engine to eliminate idle fuel consumption, typically integrating a reinforced starter motor, enhanced battery, and engine control unit with sub-200 millisecond restart latency. The electromechanical product type leads unit volume while battery-based systems retain the largest installed base across legacy platforms. Passenger vehicle applications generate the dominant revenue share, though commercial vehicle demand is expanding fastest as fleet operators target idle-reduction compliance. OEM end users control procurement specifications, while aftermarket providers capture recurring revenue from battery replacement cycles and control module reprogramming.
The EPA enforces Corporate Average Fuel Economy standards that effectively mandate start-stop adoption across US light-duty fleets. EMA's Euro 7 emission limits and China's MIIT fuel consumption regulations create parallel compliance obligations across the three largest production geographies. ISO 26262 functional safety standards govern software control and sensor validation protocols, shaping supplier qualification requirements. Stakeholders must monitor how battery chemistry advances and 48-volt electrical architecture penetration alter system design priorities and supplier value capture.
Market Dynamics
The transition from 12-volt to 48-volt electrical architectures is compressing supplier margins and forcing battery-based system redesigns across passenger vehicle platforms. OEM procurement teams now specify electromechanical solutions that eliminate belt-driven starter generators entirely.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US light-duty fleet mandates effectively require start-stop adoption, creating baseline demand across domestic OEM programs.
- China MIIT fuel consumption regulations:Domestic automakers accelerate electromechanical system integration to meet corporate average targets ahead of 2025 compliance deadlines.
- Enhanced flooded battery chemistry:Absorbent Glass Mat technology extends cycle life for start-stop duty profiles, reducing warranty exposure for fleet operators.
Market Restraints
- Lithium-ion raw material volatility:Battery-grade lithium carbonate price swings destabilize cost models for 48-volt system suppliers.
- European supplier concentration:German and French component manufacturers control reinforced starter motor production, creating single-source vulnerability for Asian OEMs.
- Technical limitation in restart latency:Sub-200 millisecond restart targets strain solenoid durability, forcing premature field replacements in high-cycle applications.
Strategic Opportunities
- India passenger vehicle electrification timeline:PLI scheme incentives for hybrid technology create entry points for start-stop system localization.
- Predictive maintenance software contracts:Battery health monitoring algorithms enable recurring revenue streams beyond hardware sales.
- EMA Euro 7 emission limits:Stricter idle emissions thresholds mandate expanded start-stop deployment in commercial vehicle segments previously exempted.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-D validation for engine control unit software extends development timelines by 12-18 months.
- Legacy 12-volt platform integration:Electromechanical system retrofits require wiring harness redesigns that disrupt vehicle program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICE Start and Stop System Market |
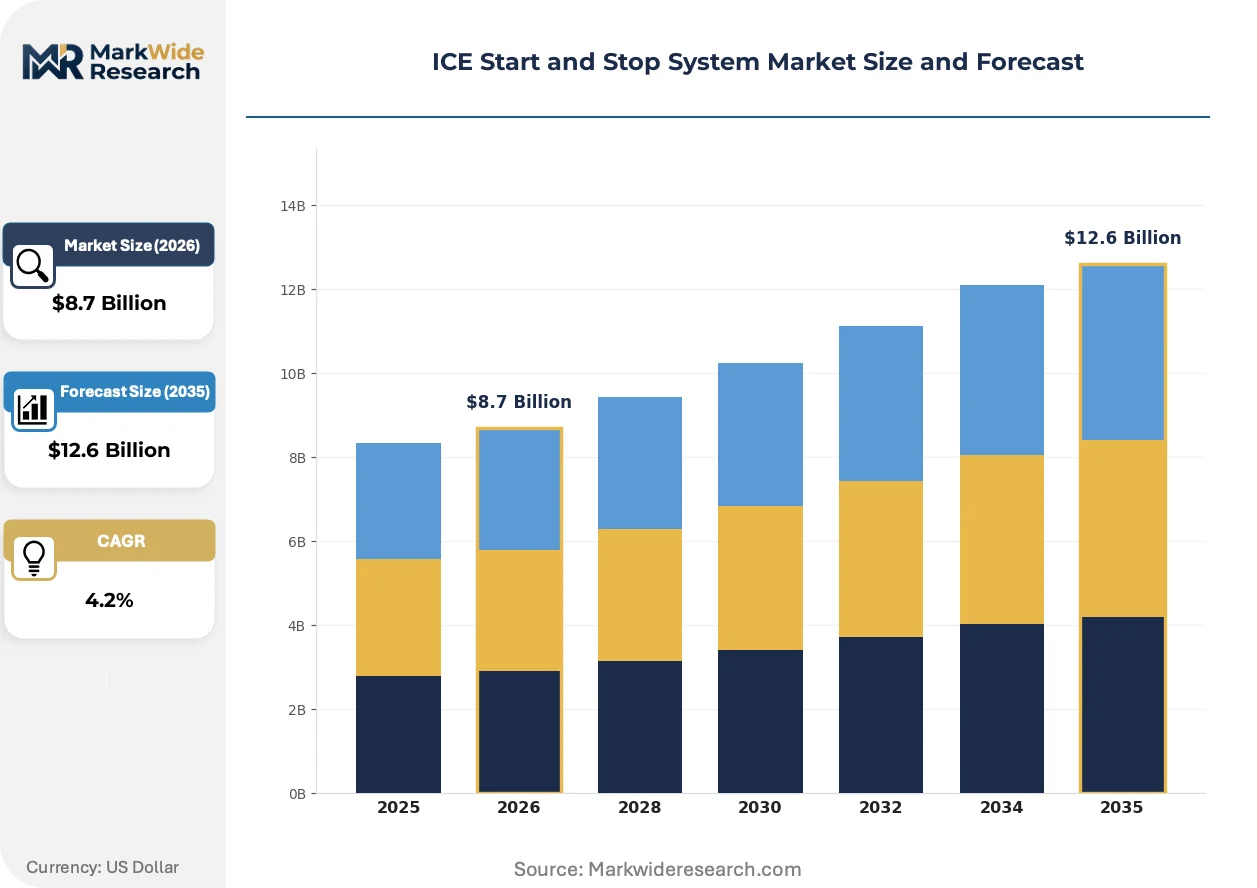
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Based, Fuel-Based, Hybrid, Electromechanical End User: OEMs, Automotive Manufacturers, Tier-1 Suppliers, Aftermarket Providers Technology: Microcontroller, Sensors, Software Control, Battery Management Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Light Trucks |
| Companies Covered | Valeo SA, Hitachi Astemo, Ltd., Robert Bosch GmbH, Delphi Technologies, Johnson Controls International plc, Continental AG, BorgWarner Inc., Schaeffler Technologies AG & Co. KG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICE Start and Stop System Market Shifts & Advancements
Electrification of auxiliary systems is eliminating mechanical loads and rewriting component specifications across powertrain engineering teams. Three developments are compressing incumbent technology positions.
Integrated starter-generator modules combining motor and inverter functions are rendering obsolete separate belt-driven alternator configurations. European luxury OEMs specify these units for mild-hybrid platforms launching through 2027. The consolidation eliminates standalone component suppliers from Tier 2 procurement lists.
Europe's F-Gas Regulation restricts refrigerants with high global warming potential, accelerating thermal management system redesigns that integrate start-stop battery cooling loops. HVAC suppliers now specify shared coolant circuits that reduce component count. Passenger vehicle programs in Germany and France face 2025 implementation deadlines.
Fleet operators now unbundle battery replacement cycles from vehicle purchase contracts, negotiating standalone service agreements with predictive analytics clauses. Commercial vehicle leasing companies in the United States specify guaranteed uptime terms that shift failure risk to system suppliers. This procurement model compresses component pricing while expanding software calibration revenue pools.
ICE Start and Stop System Market Segmentation
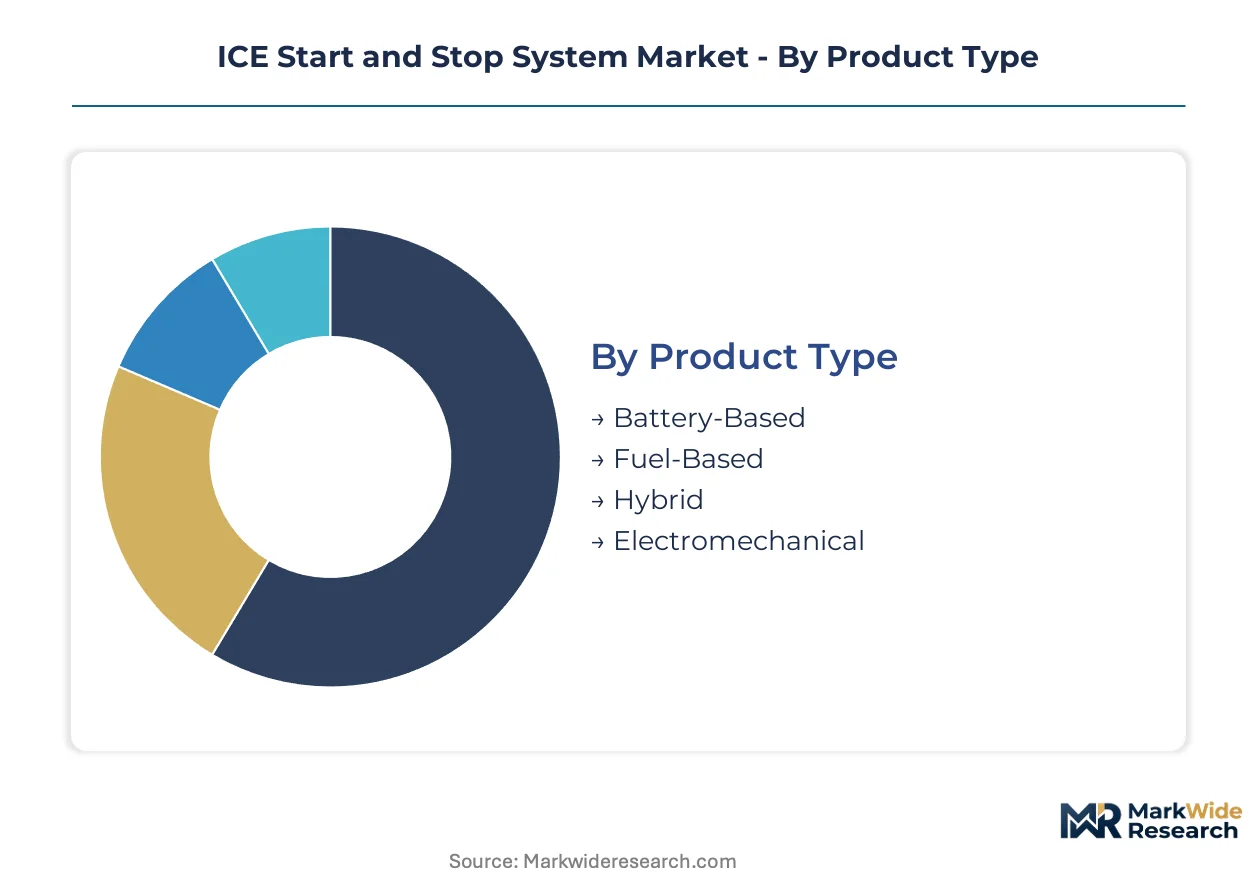
Segmentation in the ICE start and stop system market reveals divergent replacement cycles across product architectures. Battery-based systems require 3-5 year refresh intervals while electromechanical modules extend to 7-10 year lifespans, reshaping supplier revenue recognition patterns and inventory planning horizons.
Product Type:
Battery-based systems turn over fastest due to cyclic degradation, while electromechanical solutions anchor the longest replacement windows in fleet operator portfolios.
- Electromechanical:Integrated motor-generator modules eliminate belt-driven architectures entirely, consolidating inverter and starter functions into single housings. European luxury OEMs in Germany specify these units for mild-hybrid platforms, driven by EMA Euro 7 idle emission thresholds that mandate sub-200 millisecond restart performance.
- Battery-Based:Absorbent Glass Mat chemistry dominates legacy 12-volt installations, with enhanced flooded designs extending cycle life under start-stop duty profiles. Fleet operators in the United States negotiate predictive maintenance contracts that unbundle replacement cycles from vehicle purchase agreements, shifting failure risk to suppliers.
- Hybrid:Combines battery backup with electromechanical actuation for dual-redundancy in commercial vehicle applications.
- Fuel-Based:Compressed natural gas variants serve niche municipal bus fleets with specialized infrastructure requirements.
Electromechanical systems anchor the volume base while battery-based configurations gain share at the steepest rate as 48-volt architectures penetrate mid-market passenger vehicles.
End User:
Procurement authority concentrates with vehicle assemblers who dictate system specifications, while aftermarket channels capture recurring revenue from replacement cycles.
- OEMs:Direct integration into vehicle platform engineering determines wiring harness architectures, control module placement, and thermal management routing. Passenger vehicle OEMs in China specify electromechanical solutions ahead of MIIT fuel consumption compliance deadlines.
- Automotive Manufacturers:Control final assembly integration and warranty terms that cascade to Tier-1 suppliers.
- Tier-1 Suppliers:Bosch and Denso dominate microcontroller and battery management system supply, respectively.
- Aftermarket Providers:Battery replacement cycles and control module reprogramming generate recurring revenue streams independent of new vehicle production volumes.
OEMs command specification authority while aftermarket providers expand fastest as fleet operators unbundle service agreements from capital purchases.
Technology:
Software control layers now capture margin share previously concentrated in hardware components, with functional safety certification extending development timelines.
- Software Control:Engine control unit algorithms manage restart sequencing, battery state estimation, and thermal derating protocols. ISO 26262 ASIL-D validation requirements extend development programs by 12-18 months, concentrating supplier qualification among firms with dedicated functional safety engineering teams.
- Microcontroller:32-bit architectures with hardware security modules prevent unauthorized calibration access.
- Sensors:Crankshaft position and battery current sensing enable closed-loop restart timing.
- Battery Management:Cell balancing and state-of-charge estimation extend cycle life in high-duty applications.
Software control anchors the volume base while battery management systems expand most quickly as lithium-ion chemistries penetrate 48-volt architectures.
Application:
Passenger vehicles generate the dominant revenue share while commercial vehicle demand climbs fastest as idle-reduction compliance expands beyond light-duty fleets.
- Passenger Vehicles:Start-stop penetration approaches saturation in European and Chinese markets where regulatory thresholds are most stringent. Electromechanical systems specified for premium platforms command higher unit economics than battery-based alternatives in compact segments.
- Commercial Vehicles:Fleet operators in the United States negotiate guaranteed uptime terms that shift battery replacement risk to system suppliers. EPA idle emission enforcement for medium-duty trucks expands addressable market beyond historical light-duty concentration.
- Light Trucks:Pickup platforms in North America adopt reinforced starter motors for high-displacement engines.
- Motorcycles:Two-wheeler applications in India emerge under PLI scheme hybrid technology incentives.
Passenger vehicles anchor the volume base while commercial vehicles gain share at the steepest rate as EMA Euro 7 expands start-stop mandates to previously exempted segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys electromechanical systems at the highest penetration rates for premium passenger vehicles, while China and the United States concentrate battery-based architectures in mass-market fleets due to divergent electrification timelines and cost structures.
Germany
Luxury OEMs in Stuttgart and Munich specify integrated starter-generator modules for mild-hybrid platforms launching through 2027. The F-Gas Regulation accelerates thermal management redesigns that share coolant circuits between HVAC and battery cooling loops. Supplier engineering centers in Baden-Württemberg concentrate ASIL-D functional safety certification resources.
China
Domestic automakers in Shanghai and Beijing accelerate electromechanical integration ahead of MIIT fuel consumption compliance deadlines. The dual carbon goals framework tightens corporate average targets for domestic OEM fleets. Manufacturing clusters in the Yangtze River Delta absorb reinforced starter motor capacity expansions from European Tier-1 suppliers.
United States
Fleet operators negotiate predictive maintenance contracts that unbundle battery replacement cycles from vehicle capital purchases. EPA Corporate Average Fuel Economy standards mandate start-stop adoption across light-duty truck platforms. Detroit-based OEM procurement teams specify electromechanical solutions for next-generation pickup architectures.
India
Two-wheeler applications emerge under PLI scheme hybrid technology incentives targeting passenger vehicle electrification timelines. BIS certification requirements shape battery management system qualification protocols for domestic suppliers. Manufacturing investments in Maharashtra and Gujarat localize AGM battery production for start-stop duty profiles.
Japan
Microcontroller architectures from domestic suppliers anchor engine control unit specifications for Asian OEM platforms. METI energy efficiency guidelines reinforce idle-reduction mandates in commercial vehicle segments. Engineering centers in Aichi Prefecture concentrate sensor integration and crankshaft position sensing technologies.
ICE Start and Stop System Market Competitive Landscape
Capability concentration sits with European and Japanese Tier-1 suppliers holding functional safety certification and thermal management integration expertise; scale advantage sits with diversified conglomerates serving multiple OEM platforms across geographies. The vendor base separates into three strategic archetypes: integrated motor-generator specialists, battery management system providers, and sensor-microcontroller integrators. Dominant competitive moves include backward integration into battery cell supply and geographic expansion through joint ventures with domestic OEMs in China and India.
Within the integrated systems tier, Valeo SA and Robert Bosch GmbH exemplify European capability concentration in electromechanical architectures. Denso Corporation anchors Japanese specialization in thermal-optimized battery management for hybrid configurations. These three occupy positions that straddle hardware supply and software calibration revenue pools as fleet operators shift procurement toward outcome-based service agreements.
| Leading Market Players |
|---|
| Valeo SA |
| Hitachi Astemo, Ltd. |
| Robert Bosch GmbH |
| Delphi Technologies |
| Johnson Controls International plc |
| Continental AG |
| BorgWarner Inc. |
| Schaeffler Technologies AG & Co. KG |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and French reinforced starter motor suppliers compresses pricing power for Asian OEMs while simultaneously forcing dual-sourcing investments that widen cost spreads between integrated electromechanical platforms and legacy battery-based architectures.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier-1 suppliers and passenger vehicle OEMs, with spot purchasing confined to aftermarket battery replacement cycles. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 ASIL-D certification grade and volume scale commitments. Cost compression in battery-based tiers is intensifying because lithium-ion raw material volatility destabilizes supplier cost models. Fleet operators exhibit the highest price sensitivity due to unbundled service agreements, while luxury OEMs in Germany demonstrate the least sensitivity when specifying integrated starter-generator modules.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for microcontroller and sensor suppliers serving dual-hemisphere OEM platforms. Manufacturing concentrates in Germany, China, and Japan for electromechanical system assembly, with Mexico emerging as a nearshoring alternative for US-bound production. The supply chain draws from lithium carbonate deposits, copper winding stock, and rare-earth magnet materials. Distribution runs through OEM direct procurement channels for original equipment, with aftermarket providers capturing recurring revenue via independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full battery electric vehicle penetration represents the substitution threat that start-stop system incumbents must navigate as 48-volt architectures become a transitional technology rather than an endpoint.
For Market Incumbents: Build certification moats around ISO 26262 ASIL-D validation capabilities that extend development timelines beyond what emerging competitors can sustain. Backward integration into Absorbent Glass Mat battery cell production secures supply continuity against raw material volatility. Capacity addition in the Yangtze River Delta manufacturing cluster captures China domestic OEM demand ahead of MIIT compliance deadlines. For New Entrants and Emerging Players: India's two-wheeler electrification timeline under PLI scheme incentives offers the most penetrable entry point for localized start-stop system production. Commercial vehicle fleet operators in the United States present white-space opportunity through predictive maintenance software contracts that shift procurement toward outcome-based service agreements. Partner with established Tier-1 distributors to bypass OEM direct qualification barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors functional safety-certified suppliers with thermal management integration expertise. Acquirers should target microcontroller and battery management system specialists with existing OEM platform relationships. Watch 48-volt architecture penetration rates in mid-market passenger vehicles as the inflection signal for electromechanical system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive AGM production reduces exposure to lithium carbonate price swings destabilizing 48-volt system economics. |
| Joint Venture with Domestic OEM in China | Localized manufacturing in Yangtze River Delta clusters absorbs capacity expansions from European Tier-1 suppliers. |
| Predictive Maintenance Software Development | Battery health monitoring algorithms enable recurring revenue streams beyond hardware sales to fleet operators. |
| ASIL-D Functional Safety Certification Investment | Extended validation timelines concentrate supplier qualification among firms with dedicated engineering teams. |
| Platform Standardization Across OEM Programs | Shared wiring harness architectures reduce redesign costs for electromechanical retrofits in legacy 12-volt platforms. |
Research Methodology
Desk research of regulatory filings from EPA, EMA, and MIIT preceded structured interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operator maintenance directors. Secondary validation drew from vehicle production databases, customs trade records, SEC 10-K disclosures, and ISO certification registries. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory mandate timelines.
Assumptions held fixed include EPA Corporate Average Fuel Economy enforcement intensity, EMA Euro 7 implementation scope, and China MIIT compliance deadline adherence. Variables modeled across the analysis window encompassed 48-volt architecture penetration rates, electromechanical versus battery-based system mix, and commercial vehicle fleet electrification timelines. CAGRs derived from segment-level unit projections multiplied by average selling price trajectories, with battery chemistry cost curves and functional safety certification timelines as key forecast inputs.
Practitioners should monitor lithium carbonate price volatility, Euro 7 commercial vehicle exemption revisions, and India PLI scheme hybrid technology qualification changes for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Avalanche Airbags Market