
 Adaptive Headlights Market | 2026-2036
Adaptive Headlights Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Headlights Market Analysis
The capital-intensity gap between tier-one lighting suppliers and mid-tier competitors is collapsing as matrix LED module costs fall and software-defined beam control becomes standard. Koito Manufacturing Co., Ltd. leverages its vertical integration across LED chip sourcing and optical design to sustain margin leadership in factory-installed systems. Robert Bosch GmbH competes through embedded sensor fusion, anchoring its adaptive high beam offerings to ADAS architectures in European and Asian premium vehicles.
Adaptive headlights are electronically controlled forward lighting systems that pivot beams in response to steering angle, vehicle speed, and oncoming traffic detected via camera or radar inputs, with matrix LED arrays containing hundreds of individually addressable diodes that extinguish precise zones to prevent glare. Their primary commercial purpose is to maximize road illumination without dazzling other drivers, reducing nighttime accident rates while supporting automated driving perception requirements. Matrix LED technology leads installed value across premium platforms, while adaptive high beam functionality represents the fastest-growing technology segment as regulators in multiple jurisdictions relax historical anti-glare prohibitions. Factory-installed integration captures the dominant margin pool, whereas aftermarket retrofit channels remain structurally constrained by calibration complexity and warranty limitations.
Euro NCAP assessment protocols, EU General Safety Regulation mandates, and NHTSA pending rulemakings on adaptive driving beam approval are collectively reshaping product certification requirements and market access timelines. ECE R48 and R123 standards govern beam pattern compliance in Europe, while the US DOT maintains more restrictive Federal Motor Vehicle Safety Standard No. 108 provisions that limit full matrix functionality. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to engineer region-specific optical modules or pursue unified global platforms.
Market Dynamics
Matrix LED module costs are collapsing under scale manufacturing while software-defined beam control migrates from premium flagships to mid-range vehicle platforms, compressing the historical technology tiering that separated luxury from volume segments.
Growth Catalysts
- Euro NCAP Safety Protocols:European assessment schemes now weight adaptive lighting performance in overall vehicle ratings, pressuring OEMs across Germany, France, and Italy to factory-install matrix systems as standard equipment rather than optional upgrades.
- China NEV Platform Integration:Domestic electric vehicle architectures in China incorporate intelligent headlight modules as standard perception hardware, creating captive demand for adaptive beam systems that interface with automated driving sensor stacks.
- ADAS Convergence:Camera and radar fusion requirements for Level 2+ automation are pulling adaptive headlight controllers into centralized compute domains, expanding addressable content per vehicle.
Market Restraints
- US DOT Regulatory Friction:Federal Motor Vehicle Safety Standard No. 108 maintains prohibitions on full matrix functionality that extinguishes selective zones, forcing optical module redesigns and limiting feature parity with European-specification vehicles.
- LED Chip Supply Concentration:Epitaxial wafer production for high-performance automotive LEDs clusters in East Asian foundries, exposing tier-one suppliers to geographic concentration risk and input cost volatility.
- Calibration Complexity:Factory-installed systems require precise alignment with vehicle ride height sensors and steering angle encoders, creating technical barriers that structurally constrain aftermarket retrofit penetration.
Strategic Opportunities
- India Premium Passenger Segment:Underpenetrated relative to per-capita income growth, India's luxury vehicle market presents white space for adaptive high beam introduction as Mercedes-Benz, BMW, and Audi expand local assembly operations.
- EU General Safety Regulation Mandates:Binding requirements for advanced driver assistance systems create regulatory pull for intelligent lighting as a compliance pathway, accelerating replacement cycles in the European fleet.
- Software-Defined Lighting Convergence:Over-the-air update capability enables post-sale feature activation and beam pattern optimization, transforming headlights from fixed hardware to recurring revenue platforms.
Industry Challenges
- Optical Engineering Talent Scarcity:The intersection of precision lens design, thermal management, and embedded software control requires specialized skill sets that compete with broader automotive electronics and consumer display sectors.
- Homologation Timeline Compression:Divergent approval pathways between ECE R48/R123 in Europe, NHTSA pending rulemakings in the United States, and GB standards in China force parallel certification tracks that extend program development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Headlights Market |
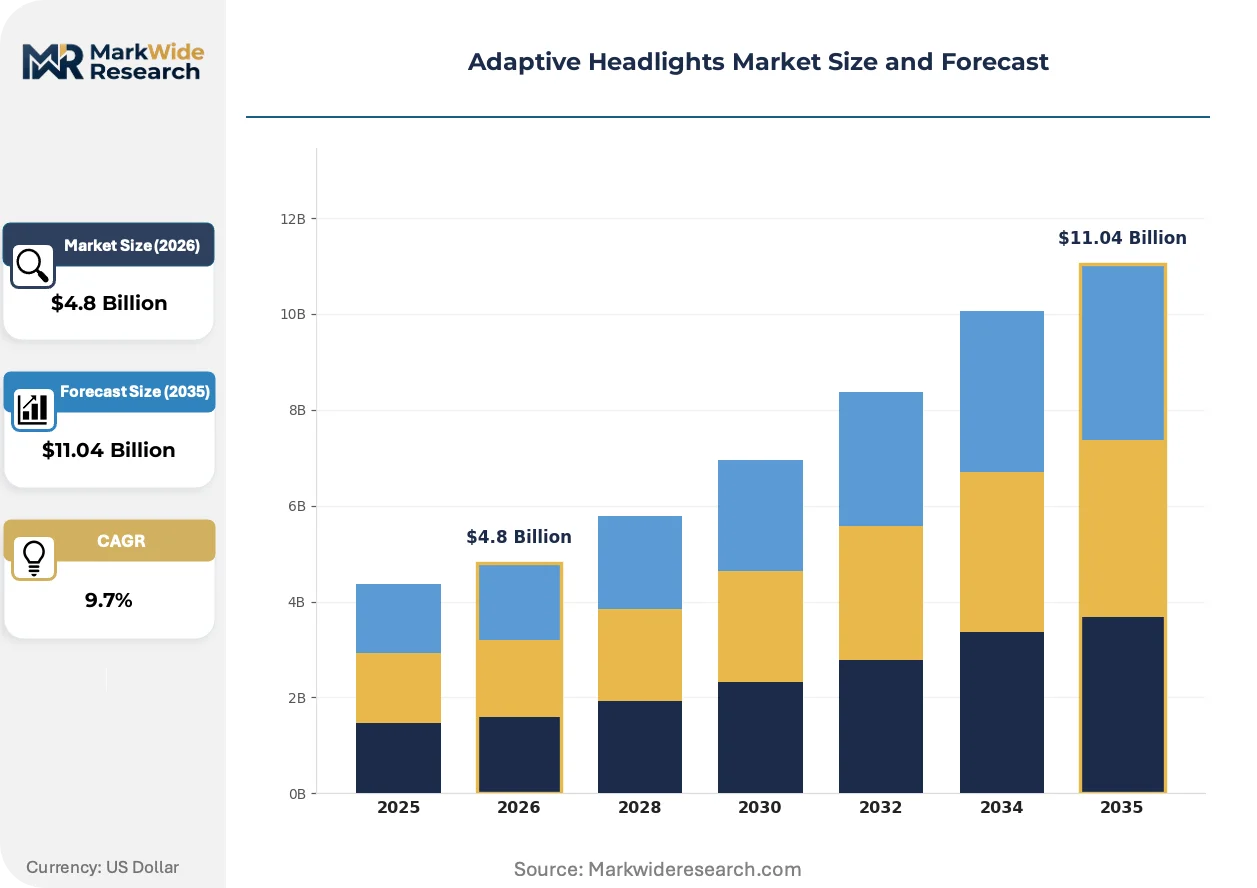
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Laser, HID, Halogen Technology: Dynamic Bending, Static Bending, Continuous Lighting, Adaptive High Beam End User: OEMs, Aftermarket, Vehicle Manufacturers, Fleet Operators Installation: Factory Installed, Retrofit, Integrated Systems, Standalone Units |
| Companies Covered | Koito Manufacturing Co., Ltd., Osram Licht AG, BMW AG, Hyundai Mobis Co., Ltd., Robert Bosch GmbH, Continental AG, HELLA GmbH & Co. KGaA, ZKW Group GmbH, Valeo S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Headlights Market Emerging Trajectories
Digital light processing and solid-state scanning technologies are displacing mechanical actuation in next-generation headlight architectures, enabling pixel-level beam control without moving parts while reducing package size and power consumption.
Micro-LED arrays with thousands of individually addressable emitters are fragmenting the incumbent matrix LED segment by offering finer resolution glare-free zones and enabling projection-based communication functions. German premium OEMs are piloting these systems on flagship electric sedans, with tier-one suppliers scaling wafer-level packaging to meet automotive reliability standards. The technology is fragmenting supplier margins by shifting value capture from optical hardware to semiconductor content and embedded software licensing.
NHTSA's pending rulemaking on adaptive driving beam approval is forcing US market participants to engineer dual-mode optical modules that satisfy both restrictive domestic standards and full-function international specifications. The regulatory uncertainty is compressing product planning horizons and accelerating engineering resource allocation toward compliance documentation. Domestic manufacturers are responding by lobbying for harmonization while maintaining parallel development tracks to avoid market exclusion.
Fleet procurement for rental and mobility services is compressing replacement cycles for headlight systems as operators prioritize nighttime safety ratings and insurance cost reduction. These buyers are unbundling lighting content from traditional trim packages and specifying adaptive high beam as fleet-standard equipment across vehicle classes. The shift is most visible in corporate fleet channels across Germany and the United Kingdom where total cost of ownership models now weight accident avoidance technology more heavily than interior amenities.
Adaptive Headlights Market Segmentation
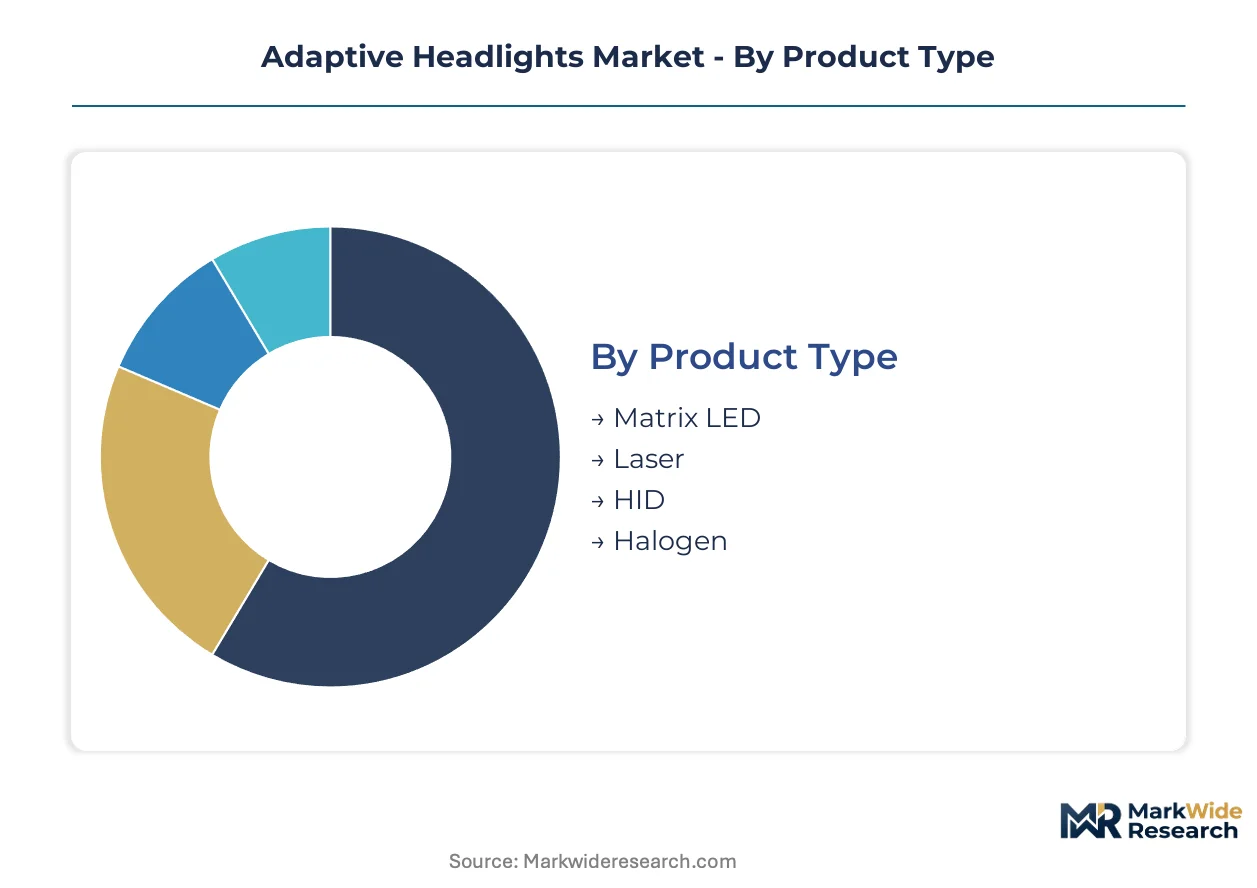
Segmentation in adaptive headlights reveals how value migrates between hardware tiers and software control layers. Manufacturers calibrate portfolio depth against factory integration requirements and aftermarket serviceability constraints.
Product Type:
Margin pools concentrate in semiconductor-intensive modules where LED chip sourcing and optical design create defendable positions.
- Matrix LED:Hundreds of individually addressable diodes enable pixel-level beam extinguishing for glare-free operation. Demand clusters in German and Chinese premium passenger vehicles where Euro NCAP safety ratings and domestic NEV platform mandates require factory-installed intelligent lighting.
- Laser:Diode-pumped phosphor systems deliver extended throw distances with reduced package size. BMW and Audi flagship architectures in Germany specify laser modules for highway beam projection, though thermal management complexity limits volume expansion.
- HID:Xenon arc discharge technology persists in mid-range vehicle refreshes where OEMs delay LED migration. Cost-conscious platforms in India and Southeast Asia sustain residual demand.
- Halogen:Tungsten-halogen incandescence dominates entry-level fleet procurement and emerging market aftermarket replacement. Margins compress under regulatory pressure for efficiency compliance.
Matrix LED holds installed capacity. Laser is rotating up the share rankings.
Technology:
Application intensity varies by automation level, with Level 2+ architectures demanding sensor-fused beam control.
- Adaptive High Beam:Camera-driven selective zone extinguishing prevents oncoming glare while maximizing road illumination. NHTSA pending rulemakings in the United States and ECE R123 compliance in Europe are accelerating OEM adoption across Mercedes-Benz, BMW, and Volvo platforms.
- Dynamic Bending:Steerable modules pivot beams in real-time response to steering angle and vehicle speed. China NEV manufacturers integrate these systems as standard perception hardware for automated driving stacks.
- Static Bending:Pre-set beam angles activate at low speeds for cornering illumination. Cost-optimized implementations in compact passenger vehicles limit addressable content per vehicle.
- Continuous Lighting:Uninterrupted beam patterns without discrete switching zones. Regulatory friction in the United States under FMVSS No. 108 constrains full-function deployment.
Adaptive High Beam captures the steepest expansion trajectory. Dynamic Bending is rotating up the share rankings.
End User:
Customer type determines procurement cadence and specification authority over lighting content.
- OEMs:Brand-owning manufacturers specify headlight systems at platform conception. Volkswagen Group, Stellantis, and Hyundai-Kia anchor volume demand through centralized lighting commodity boards.
- Vehicle Manufacturers:Contract assemblers and joint venture partners execute build-to-print programs. Chinese NEV specialists including NIO and XPeng source adaptive modules for proprietary electrical architectures.
- Fleet Operators:Rental and mobility services unbundle lighting from trim packages. Corporate fleet channels across Germany and the United Kingdom specify adaptive high beam as standard equipment for insurance cost reduction.
- Aftermarket:Retrofit channels face structural constraints from calibration complexity and warranty limitations. Regulatory homologation requirements limit addressable market scope.
OEMs hold installed capacity. Fleet Operators is rotating up the share rankings.
Installation:
Integration depth shapes margin durability and replacement cycle frequency.
- Factory Installed:Precision-aligned systems calibrated to ride height sensors and steering encoders at vehicle assembly. Captures dominant margin pool through warranty-backed lifecycle revenue.
- Integrated Systems:Headlight modules fused with ADAS sensor stacks and centralized compute domains. Expanding content per vehicle as Level 2+ automation proliferates in European and Asian premium segments.
- Standalone Units:Self-contained adaptive modules for platform flexibility. Mid-range vehicle programs in China and India specify these for production optionality.
- Retrofit:Post-sale installation constrained by alignment precision requirements and regulatory certification barriers. Technical complexity limits penetration to specialist workshops.
Factory Installed holds installed capacity. Integrated Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where OEMs command premium factory-installed specifications, while Chinese NEV platforms compress module costs through scale manufacturing. This asymmetry shapes divergent margin structures across major demand centers.
United States
NHTSA's pending adaptive driving beam rulemaking creates regulatory uncertainty for full matrix functionality. FMVSS No. 108 maintains prohibitions on selective zone extinguishing that force optical module redesigns. Detroit-based OEMs engineer dual-mode systems to preserve European specification parity.
Germany
Euro NCAP safety protocols weight adaptive lighting performance in vehicle ratings, pressuring Mercedes-Benz and BMW to standardize matrix LED. ECE R48 and R123 standards govern beam pattern compliance. Stuttgart and Munich anchor concentrated tier-one supplier engineering centers.
China
Domestic NEV architectures from NIO and XPeng integrate intelligent headlight modules as standard perception hardware. GB standards and MIIT regulations shape certification requirements. Yangtze River Delta manufacturing clusters scale LED module production for captive platform demand.
Japan
METI industrial policy supports automotive electronics integration, with Toyota and Honda specifying adaptive high beam for domestic premium platforms. JIS standards align with ECE frameworks for export compatibility. Nagoya-area suppliers concentrate optical design expertise.
India
Mercedes-Benz, BMW, and Audi expand local assembly operations for premium passenger vehicles. BIS certification requirements and DGFT import regulations structure component sourcing. Maharashtra and Gujarat host emerging lighting module integration facilities.
Adaptive Headlights Market Vendor Landscape
Concentration sits with vertically integrated lighting specialists and diversified automotive electronics conglomerates. Tier-one suppliers with captive LED chip sourcing and optical design capabilities command durable margin positions. Two strategic archetypes dominate: Japanese and German specialists with backward integration into semiconductor content, and diversified European and Korean conglomerates leveraging ADAS architecture convergence. Competitive moves center on sensor fusion partnerships and software-defined beam control licensing.
Among Japanese specialists, Koito Manufacturing Co., Ltd. exemplifies the vertically integrated archetype through its control of LED sourcing and optical engineering. Robert Bosch GmbH represents the diversified conglomerate model, anchoring its position through embedded controller integration with European OEM platforms. Valeo S.A. and HELLA GmbH & Co. KGaA occupy positions within the European tier-one supplier tier, competing through homologation expertise and factory-installed calibration capabilities.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Osram Licht AG |
| BMW AG |
| Hyundai Mobis Co., Ltd. |
| Robert Bosch GmbH |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| ZKW Group GmbH |
| Valeo S.A. |
| Others |
Supply Flow & Price Mechanics
ECE R48 and R123 certification requirements gate both supplier qualification and price differentiation simultaneously, forcing optical module manufacturers to absorb homologation costs that stratify factory-installed pricing across European and export-market specifications. This regulatory architecture concentrates margin capture with tier-one suppliers possessing captive testing infrastructure while compressing aftermarket retrofit economics.
Pricing Analysis
Configured-to-order pricing for matrix LED modules commands substantial premiums over standard adaptive high beam configurations due to pixel-density specifications and software licensing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from OEM lighting commodity boards. Cost compression in mid-range LED chip sourcing is intensifying because Yangtze River Delta manufacturing clusters have achieved scale efficiencies. Fleet operators exhibit highest price sensitivity, prioritizing total cost of ownership metrics over feature depth, whereas German premium OEMs demonstrate lowest sensitivity given Euro NCAP safety rating imperatives.
Supply Chain Analysis
Inventory lead times for epitaxial wafers and optical-grade polymers have extended as automotive LED demand converges with consumer display and general lighting applications. Manufacturing concentrates in China, Germany, and Japan, with East Asian foundries dominating high-performance LED chip fabrication. Supply chains draw from gallium nitride substrates, precision-molded polycarbonate lenses, and embedded controller silicon. Single-source vulnerability concentrates in epitaxial wafer production where three facilities supply the majority of automotive-grade output. Distribution runs through OEM tier-one supplier networks with limited aftermarket channel penetration due to calibration complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adaptive headlights market is entering a cyclical recovery phase as automotive production normalizes and NEV platform launches accelerate intelligent lighting integration. OEM capital expenditure cycles and regulatory mandate timelines in Europe and China provide the cyclical impetus.
For Market Incumbents: Compound defensive positioning through backward integration into LED chip sourcing and optical design capabilities to preserve margin leadership against emerging semiconductor specialists. Prioritize certification investment in dual-mode optical modules that satisfy both restrictive US DOT standards and full-function international specifications, defending against regulatory fragmentation risk. For New Entrants and Emerging Players: Software-defined lighting services represent a service-layer gap where incumbents under-serve, particularly in post-sale feature activation and over-the-air beam pattern optimization. Target aftermarket calibration tooling and diagnostic equipment for specialist workshops as the most penetrable segment, leveraging technical complexity barriers that constrain incumbent focus. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-tier matrix LED manufacturing as wafer-level packaging achieves automotive reliability standards, enabling asset-light market entry. Long-term viability favors acquisition targets possessing software control layer IP and OEM platform integration relationships rather than pure optical hardware capabilities. Watch NHTSA adaptive driving beam rulemaking finalization as the critical inflection signal for US market feature parity and margin normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces optical module variants for Volkswagen Group and Stellantis, compressing program development cycles. |
| Software-Defined Vehicle Investment | Enables over-the-air beam pattern updates, transforming headlights into recurring revenue platforms for tier-one suppliers. |
| Geographic Manufacturing Footprint | Yangtze River Delta localization captures Chinese NEV platform demand while mitigating tariff exposure. |
| Sensor Fusion Partnership | Integrates adaptive headlight controllers with Level 2+ ADAS architectures at Robert Bosch GmbH and Continental AG. |
| Regulatory Harmonization Lobbying | Accelerates US DOT approval pathways for full matrix functionality, unlocking feature parity with European specifications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ECE regulatory filings, vehicle production databases, and tier-one supplier technical disclosures. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution specialists, and optical design engineering directors. Secondary validation drew from IHS Markit registration data, NHTSA rulemaking dockets, MIIT certification records, and SEC filings from publicly traded lighting suppliers. Bottom-up volume modeling triangulates against top-down market sizing from automotive electronics expenditure tracking.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis of historical installation rates projected across the analysis window, incorporating technology substitution curves for matrix LED penetration. Forecast inputs include Euro NCAP safety protocol weightings, NEV platform launch schedules, and regulatory approval timeline assumptions for adaptive driving beam functionality.
Forecasts assume regulatory continuity in ECE R48/R123 regimes and pending NHTSA rulemakings; material policy shifts would require re-modeling of technology adoption curves and geographic demand allocation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market