
 Automotive Keyless Entry Access Systems Market | 2026-2036
Automotive Keyless Entry Access Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Keyless Entry Access Systems Market Analysis
Automotive dealership networks is tilting toward direct-to-consumer digital key provisioning as OEMs bypass traditional parts distribution. Continental AG leverages its integrated software-hardware stack to dominate factory-installed systems in German premium brands. Valeo SA competes through specialized NFC and UWB module production for Asian EV platforms. Robert Bosch GmbH anchors aftermarket channels with retrofit biometric kits targeting fleet conversion demand.
Automotive keyless entry access systems encompass electronic locking and authorization mechanisms that replace mechanical key insertion, typically operating via radio frequency transceivers in the 315-433 MHz bands or ultra-wideband pulses for centimeter-level proximity detection. These systems execute passive entry functions through encrypted rolling-code handshakes between vehicle body control modules and authorized portable devices. Bluetooth-enabled mobile applications now represent the fastest-expanding product type as smartphone ecosystem integration eliminates dedicated hardware costs for vehicle owners. Smart keys retain the largest installed base among product categories but face margin compression from commoditized radio-frequency fob production. Factory-installed systems capture the dominant value pool since OEMs bundle keyless entry within centralized electronic architecture specifications that aftermarket providers cannot replicate at equivalent integration depth.
The United Nations Economic Commission for Europe WP.29 regulations govern cybersecurity management systems for connected vehicle access, compelling suppliers to certify threat-resistant authentication protocols. China's Ministry of Industry and Information Technology enforces GB/T standards for radio transmission in automotive remote-control equipment, shaping frequency allocation and interference mitigation requirements. The U.S. Federal Communications Commission maintains Part 15 rules governing unlicensed RF device emissions that constrain transmitter power thresholds in keyless entry hardware. Stakeholders must monitor evolving harmonization between regional cybersecurity mandates and hardware certification timelines to avoid fragmented compliance architectures.
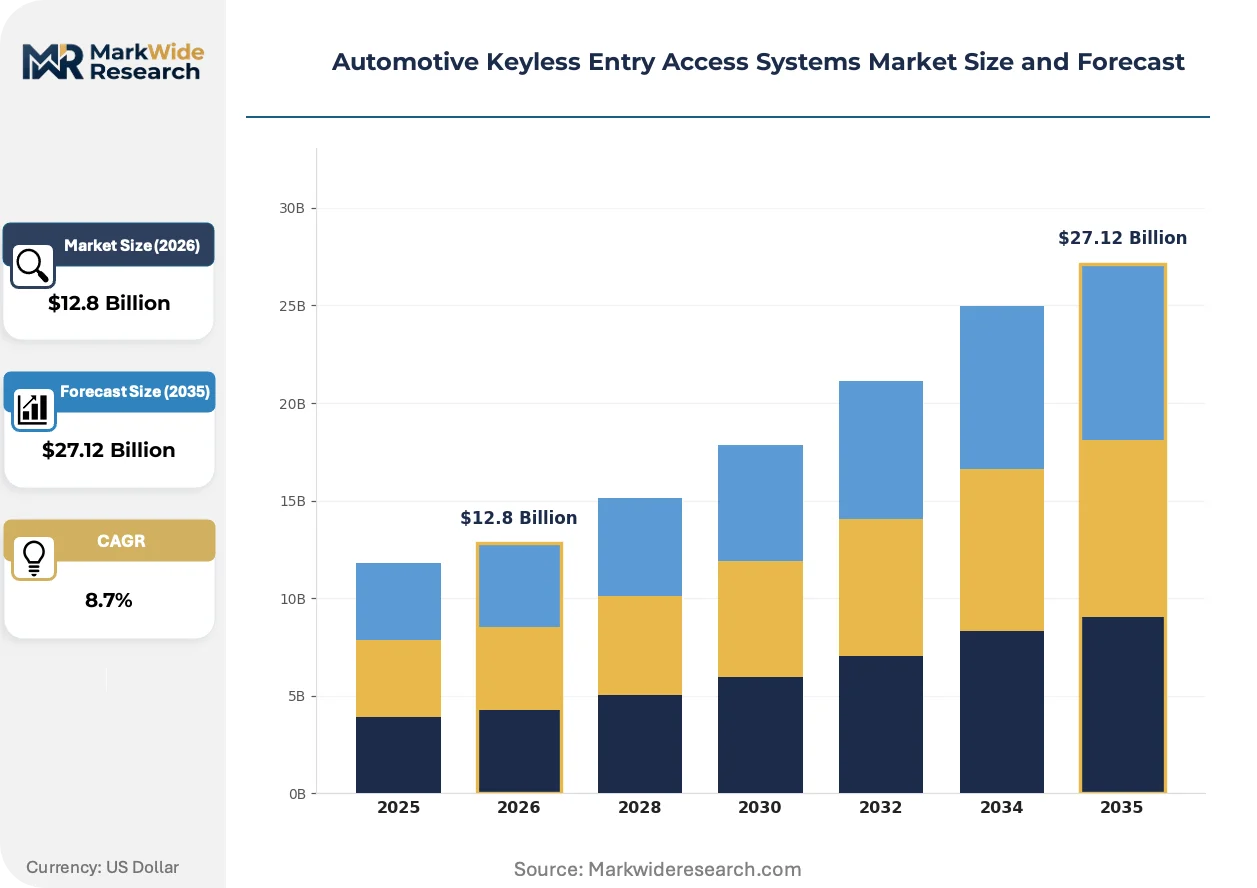
Market Dynamics
Ultra-wideband proximity detection is compressing the installed base of traditional radio-frequency fobs as OEMs mandate centimeter-level spatial accuracy for passive entry authentication.
Growth Catalysts
- EU Cyber Resilience Act:Mandates threat-resistant authentication protocols for connected vehicle access, compelling suppliers to upgrade encryption architectures.
- Biometric integration:Fingerprint and facial recognition modules are becoming standard equipment in Chinese electric vehicle platforms.
- Smartphone ecosystem convergence:Bluetooth-enabled digital keys eliminate dedicated hardware costs for vehicle owners across premium passenger segments.
Market Restraints
- Semiconductor supply concentration:UWB transceiver fabrication depends on concentrated foundry capacity in Taiwan, exposing procurement to geographic disruption.
- FCC Part 15 power thresholds:Unlicensed RF emission limits constrain transmitter range and signal penetration in metallic vehicle architectures.
- Mechanical key retention mandates:Emergency access regulations in multiple jurisdictions require redundant physical backup systems, adding bill-of-materials complexity.
Strategic Opportunities
- Fleet retrofit channels:Aftermarket biometric kits address commercial vehicle operators seeking centralized access management without full platform replacement.
- India PLI scheme for automotive electronics:Production-linked incentives attract module assembly investment for export-oriented supply diversification.
- NFC-UWB convergence:Hybrid authentication protocols combine near-field credential exchange with ultra-wideband spatial verification for layered security.
Industry Challenges
- ISO/SAE 21434 certification timelines:Cybersecurity management system audits for vehicle access systems extend development cycles by 12-18 months.
- Legacy controller area network integration:Modern encrypted handshakes must interoperate with decade-old body control module firmware in platform refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Keyless Entry Access Systems Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Bluetooth, NFC, Infrared Product Type: Smart Keys, Key Fobs, Mobile Applications, Biometric Systems End User: OEMs, Aftermarket Providers, Vehicle Owners, Fleet Operators Installation Type: Factory Installed, Aftermarket Installed, Retrofit Solutions, DIY Kits |
| Companies Covered | Continental AG, Denso Corporation, Valeo SA, HELLA GmbH & Co. KGaA, Tokai Rika Co. Ltd., Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, Alps Alpine Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Keyless Entry Access Systems Market Emerging Trajectories
Authentication architecture is migrating from dedicated hardware toward software-defined credentialing embedded in consumer electronics ecosystems.
Ultra-wideband pulse-position modulation enables centimeter-level distance bounding between vehicle and authorized device. German premium brands are adopting this technology for hands-free entry in their flagship electric platforms. Traditional proximity-based RF fobs are rendering obsolete as UWB delivers spoof-resistant spatial verification.
China's MIIT GB/T radio transmission standards are tightening electromagnetic compatibility requirements for automotive remote-control equipment. Module suppliers must redesign antenna architectures to meet revised interference mitigation thresholds. Domestic electric vehicle manufacturers are accelerating compliance certification ahead of implementation deadlines.
Fleet operators are unbundling access management from vehicle procurement through subscription-based digital key provisioning. Direct-to-consumer software licensing replaces traditional parts distribution for commercial vehicle pools. This pattern concentrates most visibly in North American logistics and rental segments seeking centralized credential administration.
Automotive Keyless Entry Access Systems Market Segmentation
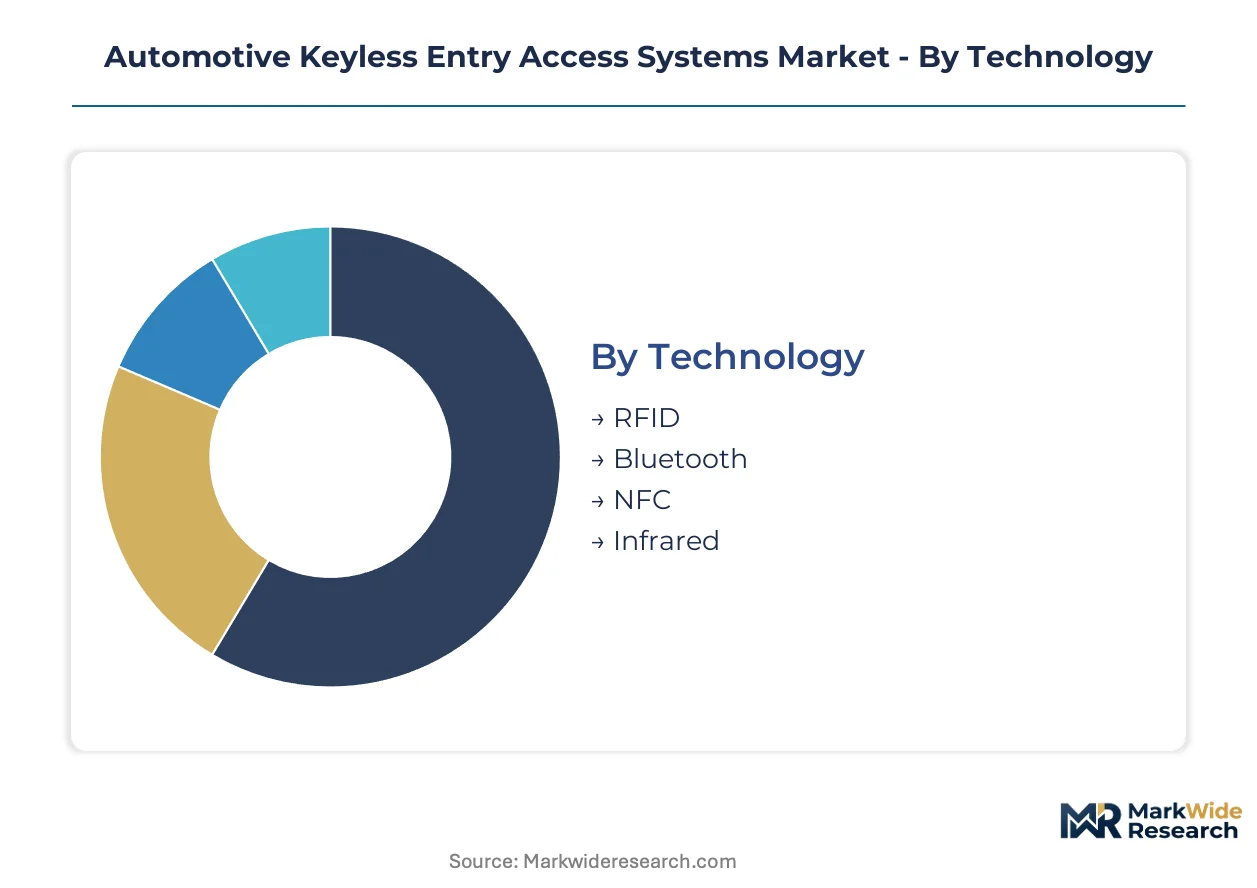
Technology differentiation determines cost structures and security architectures across automotive keyless entry systems. Each segmentation dimension reveals distinct procurement patterns, integration complexity, and margin profiles that shape supplier positioning.
Technology:
Cost tier stratification separates legacy radio-frequency implementations from emerging ultra-wideband and biometric protocols demanding higher semiconductor content.
- RFID:Passive transponder systems operating at 125 kHz for immobilizer functions and 433 MHz for remote entry. Demand concentrates in mass-market vehicle platforms across Brazil and India where cost minimization overrides precision ranging requirements.
- Bluetooth:Low-energy protocols enabling smartphone-to-vehicle credential exchange without dedicated hardware. Chinese electric vehicle manufacturers are standardizing this technology to eliminate physical key production costs entirely.
- NFC:Near-field communication for tap-to-unlock authentication at 13.56 MHz. German premium brands deploy this for backup entry when primary systems fail.
- Infrared:Line-of-sight transmission for legacy remote locking in older vehicle architectures. Fleet operators in North American commercial segments maintain residual demand for replacement units.
RFID commands the established base. The steepest expansion runs through Bluetooth.
Product Type:
Application context distinguishes consumer-facing hardware from embedded software credentials that eliminate physical distribution.
- Smart Keys:Integrated transponder fobs combining passive entry, remote start, and mechanical backup. Japanese and South Korean OEMs retain this as standard equipment across mid-tier and premium nameplates despite margin erosion.
- Key Fobs:Dedicated radio-frequency transmitters without integrated mechanical blades. Aftermarket channels in Mexico and Poland supply these for vehicle models where OEM replacement costs exceed consumer willingness-to-pay.
- Mobile Applications:Software-defined keys distributed through smartphone ecosystems. European rental fleet operators are adopting these for centralized credential revocation and transfer between drivers.
- Biometric Systems:Fingerprint and facial recognition modules integrated into door handles and steering columns. Chinese domestic EV brands deploy these as standard features to differentiate against foreign competitors.
Smart Keys retain volume leadership. Mobile Applications are climbing the fastest.
End User:
Customer type dictates procurement scale, integration depth, and service lifecycle expectations across the value chain.
- OEMs:Original equipment manufacturers specifying keyless entry within centralized electronic architectures. German and Japanese vehicle assemblers bundle these systems into platform-wide body control module contracts.
- Aftermarket Providers:Independent distributors and installers serving vehicle owners outside warranty coverage. Brazilian and Indonesian channels specialize in RFID and infrared retrofit kits for aging vehicle populations.
- Vehicle Owners:Individual consumers purchasing replacement or upgrade systems. North American direct-to-consumer digital key subscriptions are displacing traditional parts purchases.
- Fleet Operators:Commercial vehicle pools requiring centralized access management. Logistics companies across the United States and Germany deploy biometric retrofit kits for driver accountability without full platform replacement.
OEMs capture the dominant value pool. Fleet Operators present the steepest expansion trajectory.
Installation Type:
Volume concentration separates factory-integrated production from post-sale channels with distinct margin and technical support requirements.
- Factory Installed:Systems specified during vehicle design and integrated into body control modules. Premium German and South Korean brands mandate this for warranty alignment and cybersecurity certification.
- Aftermarket Installed:Professional installation of third-party systems at dedicated service centers. Polish and Czech specialists serve Central European vehicle owners seeking UWB upgrades incompatible with factory wiring.
- Retrofit Solutions:Biometric and NFC modules adapted to legacy vehicle platforms. Indian commercial fleet operators adopt these for theft reduction without capital-intensive fleet renewal.
- DIY Kits:Consumer-installable RFID and infrared systems with plug-and-play harnesses. Mexican and Brazilian retail channels distribute these for price-sensitive vehicle owners.
Factory Installed systems anchor production volumes. Retrofit Solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT anchors the dominant geography through GB/T radio transmission standards that reshape electromagnetic compatibility requirements for automotive remote-control equipment. The European Union's Cyber Resilience Act and the United States FCC Part 15 rules create a three-pillar regulatory framework spanning the largest vehicle markets. National implementation timelines vary, fragmenting certification requirements for module suppliers.
China
Domestic electric vehicle manufacturers integrate biometric access as standard equipment to differentiate against foreign competitors. MIIT enforces GB/T standards for radio transmission that tighten interference mitigation thresholds for automotive remote-control equipment. Shenzhen and Shanghai clusters concentrate module assembly investment as production-linked incentives attract export-oriented supply diversification.
Germany
Premium brands mandate factory-installed systems within centralized electronic architecture specifications for warranty alignment and cybersecurity certification. The KBA implements UNECE WP.29 cybersecurity management system audits that extend development cycles for threat-resistant authentication protocols. Stuttgart and Munich anchor integrated software-hardware stack production for flagship electric platforms.
United States
Fleet operators adopt subscription-based digital key provisioning to unbundle access management from vehicle procurement in logistics and rental segments. The FCC maintains Part 15 rules governing unlicensed RF device emissions that constrain transmitter power thresholds in keyless entry hardware. Michigan and California concentrate aftermarket biometric retrofit kit distribution for commercial vehicle pools.
Japan
Mid-tier and premium nameplates retain smart keys as standard equipment despite margin erosion from commoditized radio-frequency fob production. METI oversees harmonization between domestic cybersecurity mandates and international hardware certification timelines. Nagoya and Tokyo clusters specialize in integrated transponder fobs combining passive entry with mechanical backup functions.
India
Commercial fleet operators adopt retrofit biometric and NFC modules for theft reduction without capital-intensive fleet renewal. The PLI scheme for automotive electronics attracts module assembly investment for export-oriented supply diversification. Maharashtra and Gujarat concentrate aftermarket RFID and infrared retrofit kit distribution for aging vehicle populations.
Automotive Keyless Entry Access Systems Market Vendor Landscape
Integrated system architects and specialized module fabricators split the market between factory-installed dominance and aftermarket flexibility. Tier-1 automotive suppliers capture the dominant value pool through OEM body control module contracts, while component specialists compete on NFC and UWB module production for platform-specific integration. Three archetypes define competitive positioning: full-stack integrators, radio-frequency specialists, and biometric retrofit providers. Capacity expansion in Asian EV supply chains and strategic partnerships for smartphone ecosystem convergence represent the dominant competitive moves reshaping supplier relationships.
Within the full-stack integrator tier, Continental AG and Robert Bosch GmbH exemplify divergent strategic positioning. Continental anchors factory-installed systems through software-hardware integration for German premium brands, while Bosch occupies a position across aftermarket channels with retrofit biometric kits targeting fleet conversion demand. Valeo SA represents the specialized module archetype, sitting within NFC and UWB production for Asian electric vehicle platforms. These three entities collectively illustrate how geographic origin and corporate structure map onto divergent value capture strategies in a market tilting toward direct-to-consumer digital key provisioning.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Tokai Rika Co. Ltd. |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Alps Alpine Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Taiwan foundry concentration for UWB transceiver fabrication determines both pricing tier spreads and supply chain shape, compressing margins for Bluetooth-enabled modules while inflating premiums for biometric-integrated factory systems. OEMs absorb this risk through long-term offtake contracts, whereas aftermarket providers face spot-market volatility in radio-frequency fob components.
Pricing Analysis
Configured-to-order pricing for biometric-integrated factory systems commands substantial premiums over standard Bluetooth-enabled digital keys. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated UWB architectures from aftermarket RFID retrofits and DIY infrared kits. Cost compression in commoditized radio-frequency fob production is intensifying because Chinese module suppliers are scaling Bluetooth Low-Energy chipsets for domestic EV platforms. Fleet operators exhibit the highest price sensitivity, while German premium brands demonstrate minimal elasticity for cybersecurity-certified factory installations.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment to Chinese fabs constrain UWB transceiver availability and fragment procurement strategies. Taiwan, South Korea, and Japan anchor wafer fabrication for proximity-sensing chipsets, while China dominates final module assembly for domestic consumption. Silicon germanium substrates, ceramic antenna substrates, and encryption coprocessors constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan foundry capacity for automotive-grade UWB die production. Distribution runs through Tier 1 supplier networks into OEM body control module contracts, bypassing traditional parts wholesalers for digital key provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act mandates threat-resistant authentication protocols, creating a regulatory inflection that accelerates supplier consolidation around certified encryption architectures. This disruption rewards early movers who pre-empt compliance bottlenecks.
For Market Incumbents: Pre-empt margin erosion in commoditized radio-frequency fob production by accelerating backward integration into UWB transceiver design. Secure ISO/SAE 21434 certification ahead of competitor timelines to capture OEM platform mandates. Contain emerging entrant pressure from Chinese module specialists through exclusive body control module contracts with German and South Korean vehicle assemblers. For New Entrants and Emerging Players: Build out fleet retrofit biometric kits targeting North American logistics operators seeking driver accountability without full platform replacement. Penetrate Indian commercial vehicle pools through PLI scheme-aligned module assembly for export-oriented supply diversification. Pursue direct-to-consumer software licensing partnerships with smartphone ecosystem providers to bypass traditional automotive parts distribution. For Investors and Strategic Acquirers: The EU Cyber Resilience Act reshapes the acquisition landscape by elevating cybersecurity-certified suppliers above commodity module fabricators. Long-term viability centers on entities controlling integrated software-hardware stacks with factory-installed OEM relationships. Target acquisition archetypes include NFC-UWB convergence specialists and biometric retrofit platform developers. Monitor MIIT GB/T certification timelines as the signal indicating which Chinese module suppliers will secure export market access.| Strategic Initiative | Industry Significance |
|---|---|
| UWB-Biometric Convergence Development | Combines centimeter-level spatial verification with fingerprint authentication for layered security architectures. |
| Direct-to-Consumer Digital Key Provisioning | Eliminates traditional parts distribution margins through smartphone ecosystem subscription licensing. |
| ISO/SAE 21434 Certification Acceleration | Extends development cycles but locks in OEM platform specifications for threat-resistant authentication. |
| India PLI Scheme Module Assembly Investment | Attracts export-oriented supply diversification away from Taiwan concentration risk. |
| Fleet Retrofit Biometric Kit Distribution | Addresses commercial vehicle operator demand for centralized access management without capital-intensive renewal. |
Methodological Framework
Desk research of regulatory filings, vehicle production databases, and semiconductor trade data preceded structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers. Primary fieldwork captured procurement patterns, certification timelines, and technology migration intentions. Secondary validation drew from UNECE WP.29 documentation, MIIT GB/T standards publications, and FCC Part 15 rulemakings. Bottom-up segment sizing triangulated against top-down market value estimates across technology, product type, and installation type dimensions.
Assumptions held fixed include current regulatory implementation timelines, existing semiconductor fabrication capacity allocation, and observed OEM platform refresh cycles. Variable conditions encompassed smartphone ecosystem convergence velocity, fleet operator subscription adoption curves, and biometric module cost reduction trajectories. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market value expansion. Industry-specific inputs included IHS Markit vehicle registration data and semiconductor bill-of-materials estimates for UWB-enabled architectures.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese module specialists or accelerated UWB standardization by smartphone ecosystem providers would shift outcomes. Material shifts in Taiwan foundry availability, EU Cyber Resilience Act enforcement intensity, or India PLI scheme allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
ICE Start and Stop System Market