
 Russia 3PL Market | 2026-2036
Russia 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Russia 3PL Market Analytics
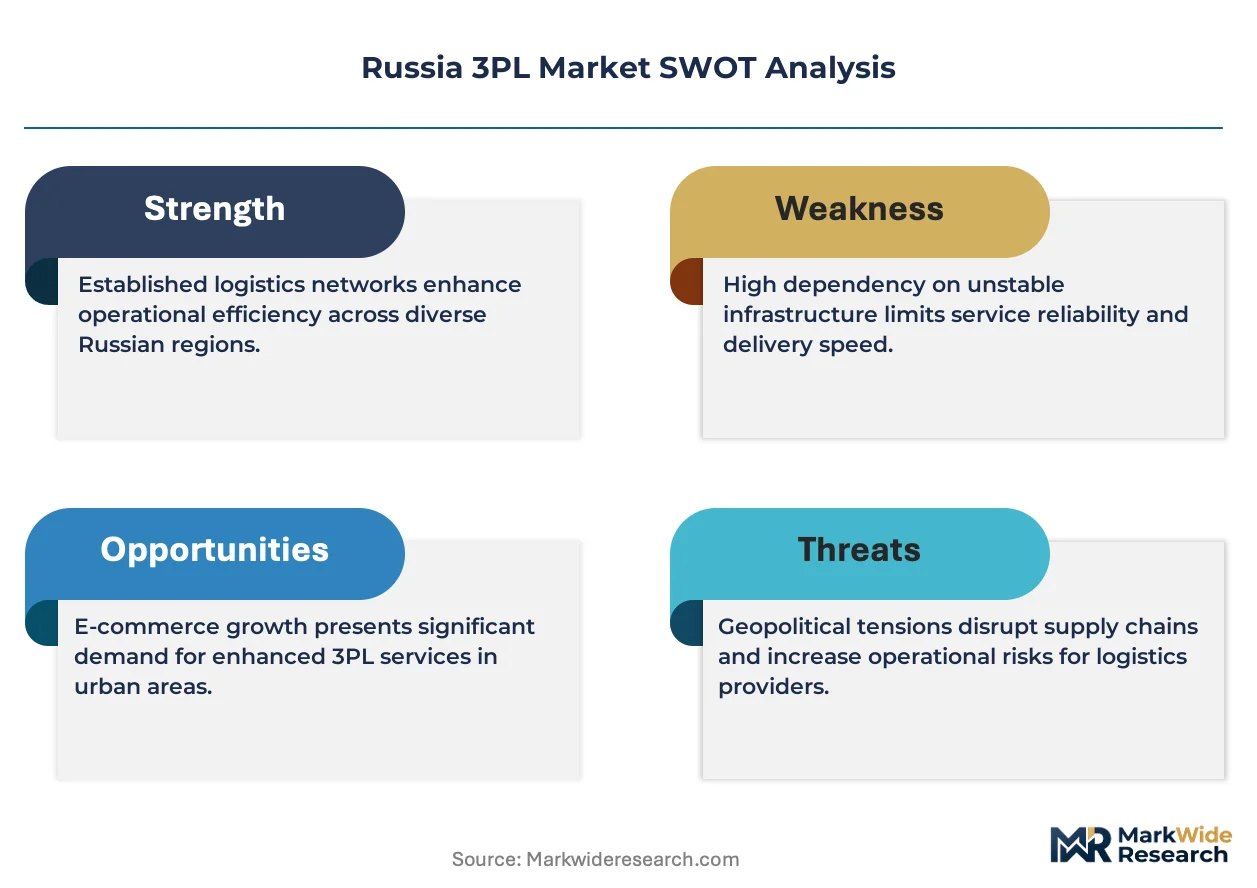
Modular service bundling is decoupling as Russian shippers unbundle freight forwarding from warehousing to optimize cost visibility. RZD Logistics leverages its rail network dominance to anchor intermodal corridors across the Trans-Siberian route. DHL Supply Chain competes through technology-intensive warehouse management deployments in the Moscow region. Eurosib sustains its position via specialized temperature-controlled distribution for pharmaceutical and food verticals.
Third-party logistics (3PL) encompasses outsourced supply chain functions including transportation, warehousing, inventory management, and value-added services performed by external providers rather than in-house fleet or facility ownership. Russia's 3PL sector operates across extreme distances averaging 900 kilometers between major industrial centers, requiring multi-modal coordination spanning rail, road, and inland waterway corridors. Transportation services dominate current revenue composition, while warehouse management systems integration represents the fastest-expanding technology segment as clients demand real-time inventory visibility. The automotive vertical generates concentrated margin pools through just-in-sequence delivery requirements, though e-commerce end users are displacing traditional wholesale channels as the primary growth vector.
Russia's Federal Customs Service and EAEU technical regulations govern cross-border documentation and transit procedures, directly shaping 3PL provider certification requirements and route economics. The Ministry of Transport's infrastructure investment framework influences rail and highway capacity allocation, while GOST standards mandate specific cargo-handling protocols for hazardous and food-grade materials. Stakeholders must monitor regulatory alignment between Russian domestic rules and EAEU harmonization timelines to anticipate compliance cost shifts and corridor access conditions.
Market Dynamics
Modular unbundling of freight forwarding from warehousing services is restructuring contract structures across Russia's 3PL sector, as shippers demand granular cost visibility across the 900-kilometer average spans between industrial centers.
Growth Catalysts
- EAEU Technical Regulations:Harmonized customs documentation standards reduce cross-border transit friction for Kazakhstan and Belarus corridors, accelerating intermodal volume flows.
- E-commerce Fulfillment:Consumer goods retailers are consolidating parcel volumes through Moscow-region distribution centers, pulling automated sortation and last-mile specialization.
- Trans-Siberian Rail Modernization:RZD infrastructure upgrades compress transit times between European Russia and Pacific ports, anchoring new intermodal service tiers.
Market Restraints
- Diesel Price Volatility:Road haulage margins compress when fuel costs spike, disproportionately affecting long-haul trucking across the Central Federal District.
- Warehousing Land Scarcity:Moscow industrial corridor vacancy rates below structural equilibrium limit expansion options for temperature-controlled facilities.
- GOST Certification Complexity:Hazardous materials handling protocols create multi-month approval timelines that freeze corridor access for new entrants.
Strategic Opportunities
- Volga Federal District Underpenetration:Nizhny Novgorod and Kazan manufacturing clusters lack integrated 3PL coverage, opening greenfield warehouse development.
- Pharmaceutical Cold Chain:Eurosib's temperature-controlled specialization model is replicable for biologics distribution as domestic production scales.
- Digital Twin Integration:Convergence of warehouse management systems with rail tracking platforms enables real-time inventory positioning across multi-modal networks.
Industry Challenges
- WMS Integration Complexity:Legacy ERP systems at Soviet-era manufacturers resist API connectivity, forcing expensive middleware deployments.
- Specialized Driver Shortage:Hazardous materials and refrigerated transport certifications face attrition gaps that constrain fleet expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia 3PL Market |
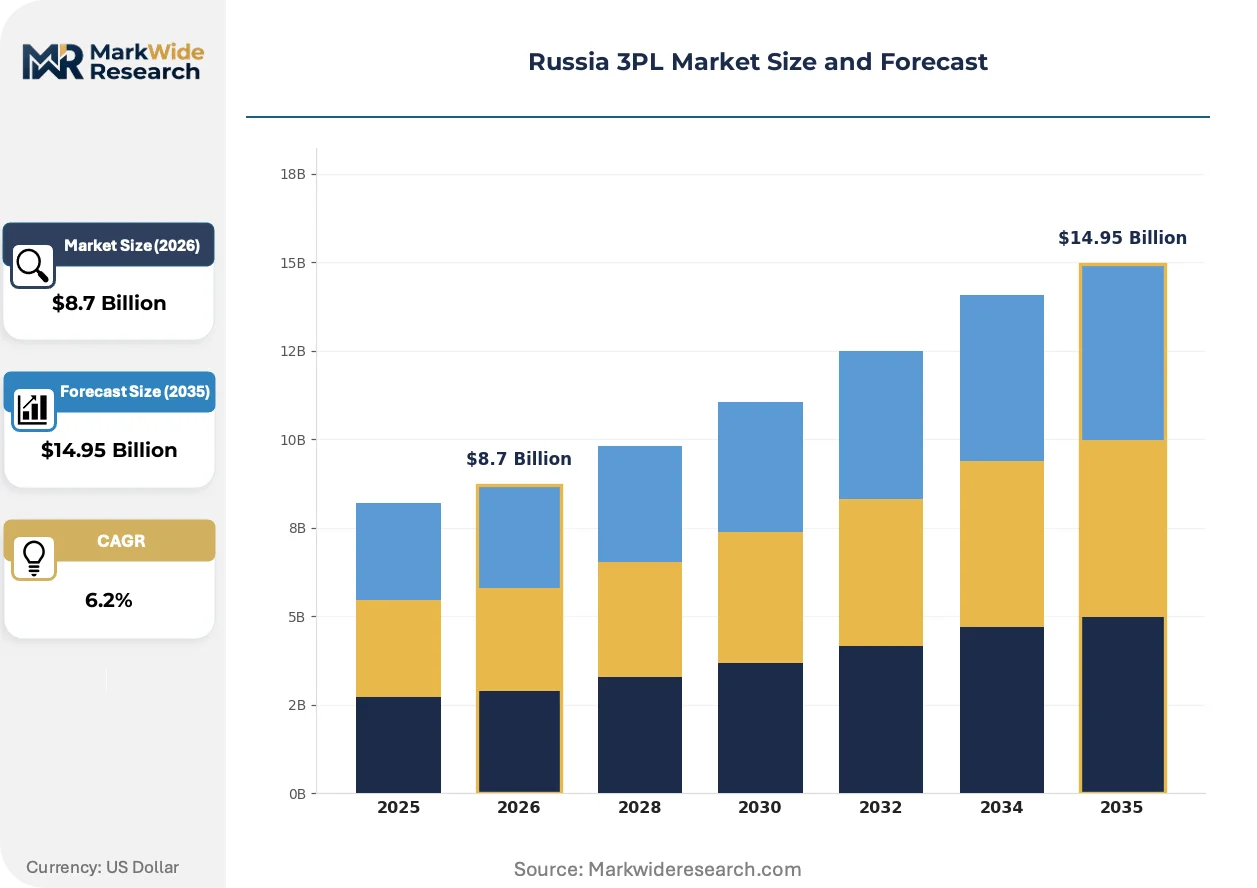
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Industry Vertical: Retail, Automotive, Electronics, Consumer Goods Technology: Warehouse Management Systems, Transportation Management, Internet of Things, Automation End User: Manufacturers, Wholesalers, E-Commerce, Logistics Providers |
| Companies Covered | Eurosib, UPS, DHL Supply Chain, FM Logistics, DP World, Kuehne Nagel, DB Schenker, Nienshants, RZD Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia 3PL Market Evolving Landscape
Real-time visibility platforms and automated materials handling are compressing inventory cycles across Russia's extended geography, while regulatory harmonization with EAEU partners rewrites cross-border service specifications.
Blockchain-enabled cargo documentation is decentralizing customs clearance authority away from centralized broker networks. Automotive and electronics manufacturers in the Moscow region are piloting distributed ledger systems for EAEU transit declarations. This architecture reduces single-point documentation failures and accelerates corridor release times.
Russia's Federal Customs Service alignment with EAEU digital transit frameworks mandates electronic advance cargo declarations for all cross-border movements. Industrial shippers must reconfigure documentation workflows to pre-clear goods before physical border crossing. The automotive vertical faces the steepest compliance cost adjustment due to just-in-sequence delivery tolerances.
Shippers are unbundling long-term warehousing contracts into short-term, volume-flexible agreements indexed to seasonal demand swings. E-commerce fulfillment centers in the Central Federal District are displacing traditional wholesale distribution as the dominant contract type. This pattern concentrates most acutely among consumer goods retailers serving Moscow's same-day delivery expectations.
Russia 3PL Market Segmentation
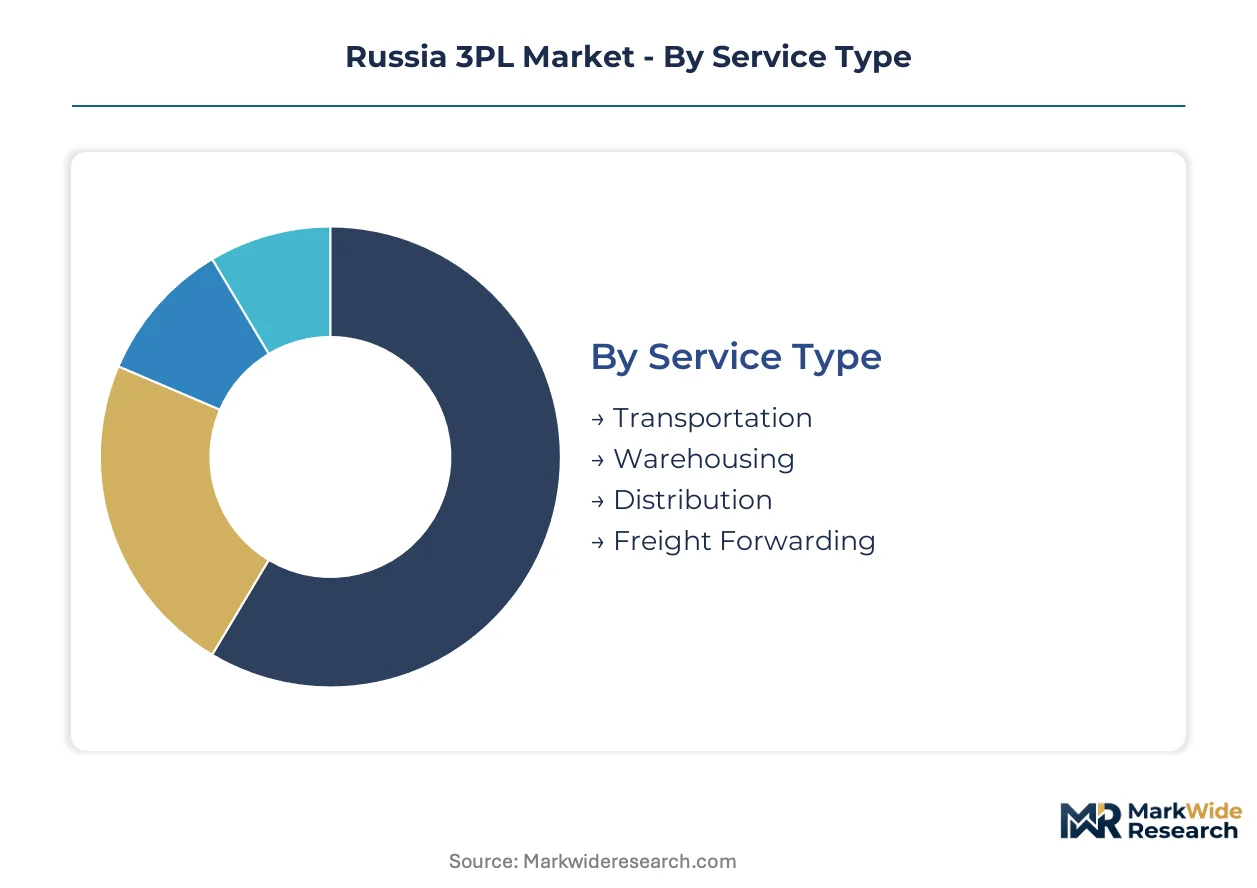
Service unbundling across Russia's 3PL sector demands granular segmentation to map where standalone contracts dominate versus bundled solutions. Each dimension reveals distinct margin structures and technology integration patterns across the 900-kilometer industrial spans.
Service Type:
Standalone transportation contracts anchor the baseline tier, while warehousing and freight forwarding increasingly embed within integrated multi-year agreements.
- Transportation:Rail, road, and inland waterway coordination across extreme distances generates the largest revenue pool. RZD Logistics leverages Trans-Siberian corridor dominance to capture intermodal volumes between European Russia and Pacific ports, with diesel price volatility compressing road haulage margins during cost spikes.
- Warehousing:Temperature-controlled facilities and automated sortation centers concentrate around Moscow's industrial corridor. Land scarcity below structural equilibrium limits expansion options, forcing developers toward Nizhny Novgorod and Kazan greenfield sites.
- Distribution:Last-mile specialization pulls investment toward same-day delivery networks serving Moscow's e-commerce fulfillment expectations. Modular contract structures now index fees to seasonal volume swings rather than fixed annual commitments.
- Freight Forwarding:Customs brokerage and documentation services face unbundling pressure as shippers seek granular cost visibility. EAEU harmonization mandates electronic advance cargo declarations, reshaping workflow configurations.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing.
Industry Vertical:
Cost tier stratification separates high-complexity automotive just-in-sequence requirements from standardized consumer goods handling.
- Retail:Omnichannel fulfillment demands are collapsing wholesale distribution timelines. Moscow-region distribution centers now integrate automated sortation with real-time inventory positioning across multi-modal networks.
- Automotive:Just-in-sequence delivery tolerances create the steepest compliance cost adjustment under EAEU digital transit frameworks. Manufacturers pilot blockchain-enabled cargo documentation to accelerate corridor release times.
- Electronics:Distributed ledger systems for EAEU transit declarations reduce single-point documentation failures. High-value cargo security requirements drive premium service tier adoption.
- Consumer Goods:E-commerce end users displace traditional wholesale channels as the primary growth vector. Parcel volume consolidation through Central Federal District hubs pulls specialized last-mile investment.
Margin concentration sits with Automotive; share gains are climbing the fastest in Consumer Goods.
Technology:
Application maturity separates legacy ERP-resistant deployments from API-native cloud architectures.
- Warehouse Management Systems:Real-time inventory visibility represents the fastest-expanding technology segment. Soviet-era manufacturers resist API connectivity, forcing expensive middleware deployments at legacy production sites.
- Transportation Management:Rail tracking platform convergence with warehouse systems enables multi-modal inventory positioning. RZD infrastructure upgrades compress transit data latency across Trans-Siberian routes.
- Internet of Things:Sensor networks monitor temperature integrity across pharmaceutical cold chains. Eurosib's specialized distribution model scales toward biologics as domestic production expands.
- Automation:Automated materials handling compresses inventory cycles across extended geography. Moscow-region e-commerce fulfillment centers drive sortation robotics deployment.
Adoption depth is greatest in Warehouse Management Systems; steepest expansion trajectory belongs to Automation.
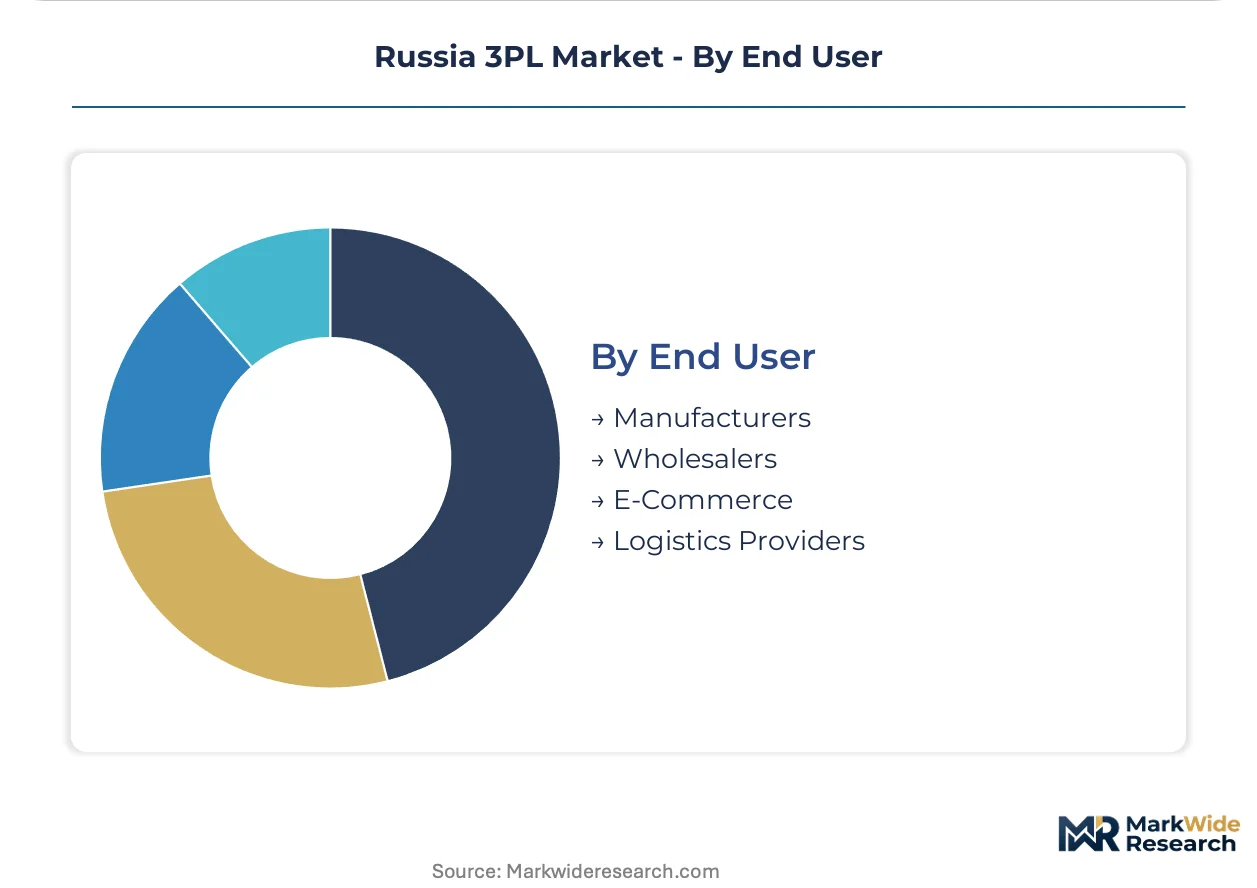
End User:
Customer type determines contract duration flexibility, with manufacturers favoring multi-year agreements against e-commerce short-term indexing.
- Manufacturers:Soviet-era industrial bases in the Volga Federal District require legacy system integration. GOST certification complexity for hazardous materials handling creates multi-month approval timelines.
- Wholesalers:Traditional distribution channels face displacement from direct-to-consumer fulfillment models. Volume concentration shifts toward parcel aggregation for final-mile handoff.
- E-Commerce:Same-day delivery expectations in Moscow force warehouse positioning within 50-kilometer radii. Seasonal demand volatility drives short-term, volume-flexible contract structures.
- Logistics Providers:Sub-contracting relationships layer specialized capabilities across temperature-controlled and hazardous materials corridors. Driver certification attrition gaps constrain fleet expansion.
Contract value pools deepest with Manufacturers; the fastest-growing demand profile belongs to E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's industrial production concentrates east of the Urals while consumption gravity pulls west toward European Russia, creating asymmetric freight flows that 3PL providers must arbitrage through backhaul optimization and intermodal coordination.
Central Federal District
Moscow's industrial corridor generates the densest 3PL demand through e-commerce fulfillment and automotive just-in-sequence delivery. The Ministry of Transport's infrastructure investment framework prioritizes rail and highway capacity allocation through this corridor. Warehouse vacancy rates below structural equilibrium force developers toward satellite zones in the Moscow Oblast periphery.
Volga Federal District
Nizhny Novgorod and Kazan manufacturing clusters lack integrated 3PL coverage despite expanding automotive and electronics production bases. GOST certification complexity for hazardous materials handling creates multi-month approval timelines that freeze corridor access. Greenfield warehouse development opportunities concentrate around Togliatti's vehicle assembly ecosystem and Kazan's special economic zones.
Siberian Federal District
Krasnoyarsk and Novosibirsk serve as transshipment nodes for Trans-Siberian rail corridors linking Pacific ports to European Russia. RZD infrastructure upgrades compress transit times between these nodes, anchoring new intermodal service tiers. Temperature-controlled distribution for food and pharmaceutical verticals remains underdeveloped relative to freight volume potential.
Northwestern Federal District
St. Petersburg's port complex handles Baltic Sea container traffic requiring customs brokerage and documentation services under EAEU harmonized standards. The Federal Customs Service mandates electronic advance cargo declarations, reshaping workflow configurations for cross-border movements. Pharmaceutical cold chain infrastructure scales toward biologics distribution as domestic production expands.
Far Eastern Federal District
Vladivostok and Nakhodka anchor Pacific Rim trade corridors with China and Korea, with free port status accelerating customs clearance velocity. EAEU technical regulations govern cross-border documentation for these transit routes. Specialized container yards and bonded warehousing capacity lag behind container throughput growth.
Russia 3PL Market Competitive Landscape
The competitive structure tilts toward rail-anchored national champions with corridor-specific dominance rather than diversified global integrators. RZD Logistics leverages Trans-Siberian network control to capture intermodal volumes, while international operators compete through technology-intensive warehouse management deployments. Three archetypes define positioning: state-affiliated rail operators, European-based contract logistics specialists, and temperature-controlled vertical specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with providers seeking to lock in scarce Moscow-region warehousing land and EAEU customs brokerage licenses.
Within the state-affiliated tier, RZD Logistics exemplifies rail-network leverage as a competitive moat. European contract logistics specialists include DHL Supply Chain and DB Schenker, which occupy positions emphasizing technology deployment over asset ownership. Temperature-controlled vertical specialization finds representation in Eurosib, which anchors pharmaceutical and food distribution corridors.
| Leading Market Players |
|---|
| Eurosib |
| UPS |
| DHL Supply Chain |
| FM Logistics |
| DP World |
| Kuehne Nagel |
| DB Schenker |
| Nienshants |
| RZD Logistics |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EAEU-compliant digital transit corridors and legacy paper-based brokerage creates a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture pharmaceutical and automotive just-in-sequence clients paying for pre-cleared documentation workflows, while commodity freight faces spot-market volatility as diesel costs spike across the 900-kilometer Central Federal District spans.
Pricing Analysis
Margin tightening in road haulage reflects diesel price volatility that compresses operator economics during cost spikes. Contract-based long-term offtake dominates rail intermodal volumes anchored by RZD Logistics, with volume scale and EAEU certification tier as primary price differentiation drivers. E-commerce fulfillment centers show highest price sensitivity as seasonal demand swings force short-term, volume-flexible agreements. Automotive manufacturers demonstrate least sensitivity, absorbing premium pricing for just-in-sequence delivery tolerances.
Supply Chain Analysis
Freight cost concentration across the Trans-Siberian corridor anchors supply chain economics, with rail-originated flows from China and Korea feeding European Russia consumption centers. Container equipment and diesel fuel represent critical input dependencies, while bonded warehousing capacity lags throughput growth at Vladivostok and Nakhodka ports. Single-source vulnerability sits with RZD's network control over east-west corridors. Distribution runs through Moscow-region consolidation hubs for final-mile handoff to e-commerce and automotive clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's 3PL sector is transitioning from legacy ERP-dependent warehouse management toward API-native cloud architectures and blockchain-enabled cargo documentation. This technology displacement creates asymmetric opportunity windows across incumbent defense, entrant positioning, and investor re-rating.
For Market Incumbents: Cement corridor control through RZD Logistics rail-network leverage and Moscow-region warehousing land lock-up before satellite zone saturation. Defend against DHL Supply Chain technology-intensive deployments by accelerating WMS integration with rail tracking platforms. Prioritize EAEU customs brokerage license accumulation as regulatory harmonization raises compliance barriers. For New Entrants and Emerging Players: Begin with Volga Federal District greenfield development around Nizhny Novgorod and Kazan manufacturing clusters where integrated 3PL coverage remains sparse. Target pharmaceutical cold chain specialization replicating Eurosib's temperature-controlled model as domestic biologics production scales. Pursue sub-contracting relationships with established rail operators to bypass GOST certification complexity. For Investors and Strategic Acquirers: Re-rating potential sits with temperature-controlled vertical specialists given pharmaceutical distribution expansion and food safety regulation tightening. Long-term viability favors providers with EAEU electronic declaration capabilities and scarce Moscow industrial corridor land positions. Watch RZD infrastructure upgrade completion as intermodal service tier inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Management System Integration | API-native cloud architectures displace Soviet-era ERP resistance across Volga Federal District manufacturing bases. |
| Intermodal Service Tier Launch | Trans-Siberian rail modernization compresses transit data latency between Pacific ports and European Russia. |
| Temperature-Controlled Facility Expansion | Pharmaceutical cold chain infrastructure scales toward biologics distribution under EAEU technical regulations. |
| Digital Twin Platform Convergence | Real-time inventory positioning merges warehouse systems with RZD rail tracking across multi-modal networks. |
| EAEU Customs Brokerage License Acquisition | Electronic advance cargo declaration mandates reshape workflow configurations for cross-border corridor access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with logistics operations directors, freight procurement managers at automotive OEMs, warehouse facility developers, EAEU customs brokerage specialists, and RZD corridor planners combined with bottom-up and top-down triangulation. Secondary validation drew from Federal Customs Service transit statistics, Ministry of Transport infrastructure investment disclosures, and EAEU technical regulation harmonization timelines.
Service type, industry vertical, technology application, and end-user contract structure were modeled at segment-level granularity across the projection horizon. CAGRs derived from volume-flow analysis across transportation, warehousing, and freight forwarding revenue pools. Forecast inputs incorporated diesel price volatility scenarios, Moscow industrial corridor vacancy rate trajectories, and EAEU digital transit framework implementation pace.
Underlying measurement precision varies by segment; transportation volume flows carry tighter precision than emerging technology adoption curves. Forecasts reflect assumptions about regulatory harmonization timelines and infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
GCC Air Freight Transport Market