
 Global Automotive Hill Descent Control Market | 2026-2036
Global Automotive Hill Descent Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Hill Descent Control Market Intelligence
The standard fitment of hill descent control systems in mainstream SUVs and crossovers is broadening the technology's addressable market beyond its niche in dedicated off-road vehicles. Bosch leverages its extensive portfolio in braking and stability control to offer integrated solutions. Continental specializes in sensor fusion technologies that enhance system accuracy. ZF Friedrichshafen competes through its advanced chassis and driveline systems for both passenger and commercial vehicles.
Automotive hill descent control is a driver-assistance feature maintaining a preset speed on steep declines without driver brake input. It functions by modulating the anti-lock braking system (ABS) to control each wheel's rotation. The SUV and pickup truck segments dominate the vehicle category, though adoption in crossovers is accelerating. Sensor fusion represents the fastest-growing technology, offering superior performance over standalone radar or camera-based systems.
The system's proliferation is linked to regulations requiring Electronic Stability Control (ESC), enforced by the NHTSA in the United States and under UN ECE standards. China's GB standards for new vehicles also influence braking system capabilities, creating a favorable technical foundation. OEMs and Tier-1 suppliers must now decide how to position this feature, either as standard equipment or within premium off-road packages.
Market Dynamics
The central force shaping the automotive hill descent control market is its software-driven integration into broader Advanced Driver-Assistance Systems. This shift transforms HDC from a standalone mechanical safety feature into an intelligent, connected function that leverages shared sensor data, enhancing performance and enabling new capabilities across vehicle platforms.
Growth Catalysts
- Regulatory Foundation:Mandates for Electronic Stability Control (ESC) under frameworks like the UN ECE regulations and NHTSA standards in the United States create a necessary technical platform, making the addition of software-based HDC a low-cost upgrade for OEMs.
- Consumer Demand in Key Markets:Strong consumer preference in the United States and Germany for SUVs and pickup trucks with high-capability features, including off-road and towing prowess, directly stimulates the inclusion of HDC as a standard or optional feature.
- Segment Expansion:The technology's proliferation beyond traditional 4x4s into the fast-growing crossover and light commercial vehicle (LCV) segments significantly broadens the total addressable market and creates new volume opportunities for suppliers.
Market Restraints
- Cost Sensitivity:In highly price-competitive economy and mid-range vehicle segments, the marginal cost of adding and validating the HDC feature, even if software-based, acts as a barrier to its standard fitment, positioning it as a premium add-on.
- Performance Limitations:The system's reliance on the vehicle's standard anti-lock braking system can lead to brake fade or overheating during prolonged use on extremely steep or long descents, a technical limitation that restricts its utility in severe-duty applications.
- EV Regenerative Braking:The powerful regenerative braking capabilities inherent in battery electric vehicles (BEVs) can provide a similar function of controlled, low-speed descents, potentially reducing the perceived need for a separate, dedicated HDC system.
Strategic Opportunities
- Emerging Market Penetration:Growing automotive markets in Latin America and Southeast Asia, characterized by rising SUV and pickup truck sales and often varied topography, present significant white-space opportunities for HDC system deployment.
- Integration with V2X:The convergence of HDC with Vehicle-to-Everything (V2X) communication can enable vehicles to receive real-time topographical data, allowing the system to pre-emptively adjust speed for upcoming steep gradients before sensors detect them.
- Specialized Vehicle Applications:There is an untapped opportunity to develop and market specialized HDC systems tailored for the unique operational demands of agricultural, mining, and construction vehicles that frequently operate on unpaved and challenging inclines.
Industry Challenges
- Software Integration Complexity:Ensuring flawless and secure software interoperability between the HDC module, the ABS controller, and the vehicle's central ADAS domain controller presents a significant validation and cybersecurity challenge for Tier-1 suppliers and OEMs.
- Driver Education Gap:A primary operational challenge for automakers is effectively communicating the system's intended use, functionality, and limitations to consumers to prevent misuse or an over-reliance that could lead to unsafe driving situations.
- Calibration Across Platforms:The need to precisely calibrate HDC software for a vast array of vehicle weights, powertrain types, and tire specifications is a time-consuming and costly engineering challenge, particularly for diverse LCV fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Hill Descent Control Market |
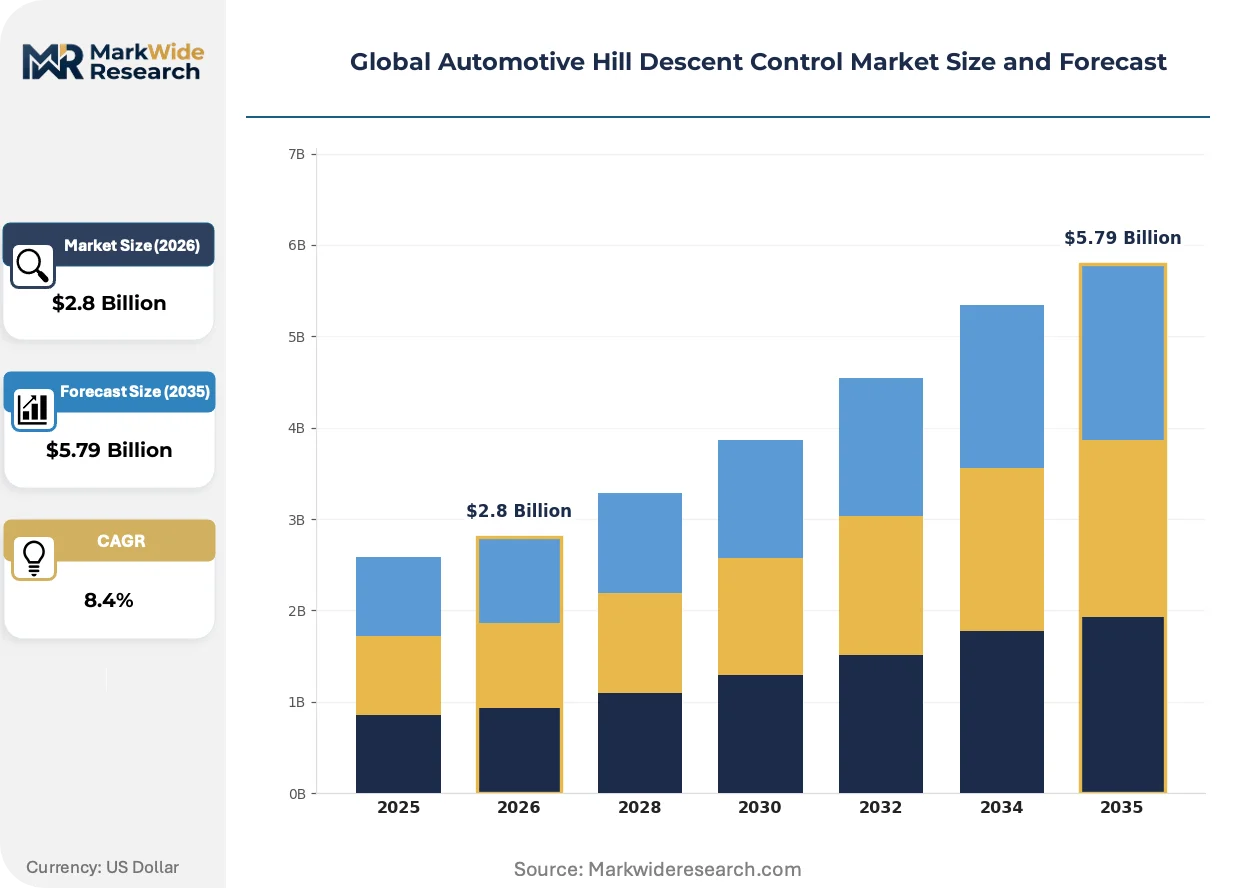
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active, Passive, Electronic, Hydraulic, Integrated Vehicle Category: SUV, Pickup Truck, Crossover, Off-Road Vehicle, LCV Technology: Radar-Based, Ultrasonic, Camera-Based, Sensor Fusion, Inertial Measurement Unit End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Knorr-Bremse, Hitachi Astemo, Bosch, Transtron, Murata, Continental, Hyundai Mobis, WABCO, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Hill Descent Control Market Strategic Shifts & Innovations
The market's evolution is defined by the transition of hill descent control from a hardware-centric function to a software-defined feature within a connected vehicle architecture. This progression is enabling more sophisticated control logic, enhanced safety through sensor fusion, and new methods of feature delivery by automakers.
Sensor fusion technology combines inputs from radar, cameras, and inertial measurement units to create a more detailed model of the vehicle's environment and state. Premium vehicle manufacturers are adopting this approach to deliver smoother and more precise speed modulation on declines. This superior control capability is expanding into the light commercial vehicle segment, where maintaining stability with variable loads is a critical safety requirement.
New automotive cybersecurity mandates, such as UN ECE Regulation 155, are directly impacting system design. This regulation requires OEMs to implement and verify secure software architectures, protecting the communication links between the HDC, braking systems, and other ECUs from external threats. The highly connected passenger SUV segment is most affected, necessitating substantial R&D investment in secure-by-design principles and over-the-air update capabilities.
A significant behavioral shift involves OEMs unbundling HDC from dedicated, expensive off-road packages. Instead, the feature is increasingly positioned as a standard component in higher trim levels of mainstream SUVs and crossovers, appealing to a broader customer base. This strategy is particularly visible in the United States, where consumers value safety and capability features even if they are primarily used in on-road conditions.
Global Automotive Hill Descent Control Market Segmentation
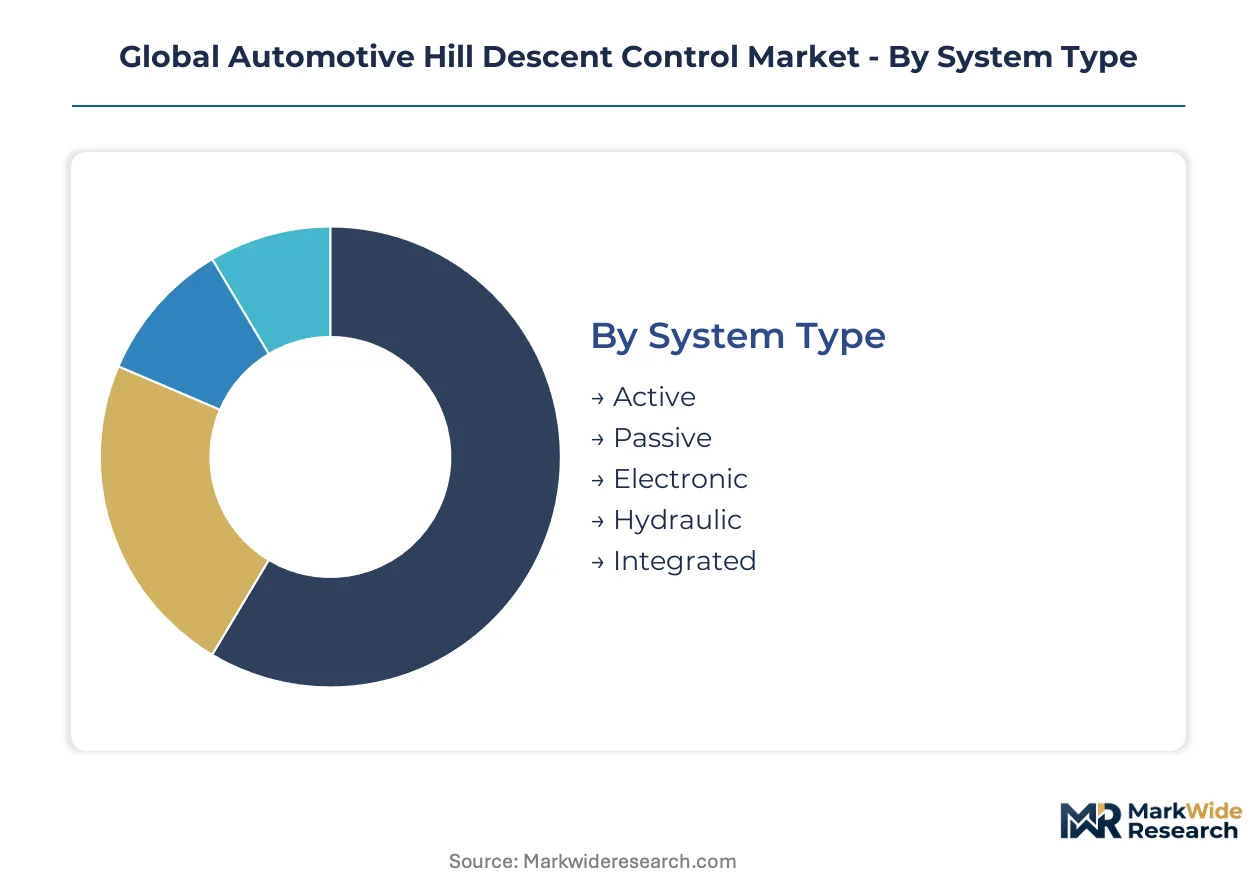
The global automotive hill descent control market exhibits distinct segmentation based on the technical characteristics of the systems, the vehicle types integrating them, the underlying sensor technologies, and the primary end-user groups. Understanding these divisions is crucial for manufacturers and suppliers to align product development and market strategies effectively.
System Type:
The functional architecture of hill descent control systems varies significantly across vehicle platforms and performance requirements.
- Electronic:This system type uses software to modulate the anti-lock braking system, offering precise speed control on steep grades. Demand concentrates in mainstream SUVs in the United States, driven by consumer safety preferences for advanced driver-assistance features.
- Integrated:Hill descent control functions are combined within broader Advanced Driver-Assistance Systems platforms, leveraging shared sensor data for enhanced performance. This approach gains traction in premium crossovers, enhancing overall vehicle intelligence and connectivity.
- Active:Active systems require driver engagement to initiate the descent control function, providing on-demand assistance for challenging terrain.
- Passive:Passive systems operate continuously when specific conditions are met, such as a steep incline and low speed, simplifying driver interaction.
- Hydraulic:These systems rely on hydraulic pressure adjustments within the vehicle's braking system, often found in older or more specialized off-road vehicle applications.
Mature deployment sits with Hydraulic systems. Newer deployment is concentrated in Integrated systems.
Vehicle Category:
The adoption of hill descent control systems spans diverse vehicle types, reflecting varied operational needs and consumer expectations.
- SUV:These vehicles frequently traverse varied terrains, making hill descent control a desirable feature for enhanced stability and driver confidence. Demand concentrates in Germany, where high-capability vehicles are preferred for leisure and utility.
- Pickup Truck:Often used for towing and heavy-duty applications, pickup trucks benefit from stable descent control, particularly when carrying significant loads. The United States drives this segment, valuing both utility and safety features in these vehicles.
- Crossover:This segment experiences accelerating adoption of hill descent control, expanding the technology's addressable market beyond traditional off-roaders.
- Off-Road Vehicle:Dedicated off-road vehicles represent the traditional niche for robust hill descent control solutions, designed for extreme inclines and challenging environments.
- LCV:Light commercial vehicles increasingly integrate hill descent control to manage variable loads and maintain stability on challenging inclines, improving operational safety.
Crossover vehicles represent the fastest-growing trajectory for HDC adoption.
Technology:
The underlying sensor technologies determine the precision and responsiveness of hill descent control systems.
- Sensor Fusion:This technology combines data from multiple sensors, such as radar, cameras, and IMUs, for superior environmental awareness and system accuracy. Premium vehicle manufacturers in Europe leverage sensor fusion for smoother and more precise descent control.
- Inertial Measurement Unit:IMUs provide precise data on vehicle pitch, roll, and yaw, which is critical for maintaining stability and control on steep and uneven grades. Specialized off-road applications in Australia prioritize IMU integration for rugged operating conditions.
- Radar-Based:Utilizes radar sensors to detect obstacles and terrain changes ahead of the vehicle, informing speed modulation decisions.
- Ultrasonic:Employs ultrasonic waves for very close-range obstacle detection, primarily useful at extremely low speeds during descent.
- Camera-Based:Relies on visual input from vehicle cameras to identify road conditions, gradients, and potential hazards, supporting system decisions.
Technological expansion is concentrated in Sensor Fusion, enhancing system accuracy and reliability.
End User:
The various participants in the automotive value chain play distinct roles in the development, integration, and distribution of hill descent control solutions.
- OEMs:Original Equipment Manufacturers integrate hill descent control systems directly into new vehicle designs as either standard equipment or optional features. Automakers in the United States increasingly position HDC in higher trim levels of mainstream SUVs.
- Tier-1 Suppliers:These companies develop and supply complete hill descent control modules and specialized components to OEMs. Bosch, for example, leverages its extensive braking expertise to offer integrated solutions to global vehicle manufacturers.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, incorporating pre-supplied hill descent control systems from Tier-1 suppliers.
- Aftermarket Providers:Offer hill descent control systems or upgrade kits for existing vehicles, catering to specialized modification needs and niche markets.
The segment with the steepest expansion trajectory is Tier-1 Suppliers, driven by increasing OEM demand for integrated ADAS solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers balance localized production with meeting diverse consumer preferences across continents. The adoption trajectory for hill descent control systems varies significantly by region, influenced by regulatory frameworks, vehicle market composition, and consumer demand for advanced driver-assistance features.
United States
Consumer preference for high-capability SUVs and pickup trucks drives demand for hill descent control as a standard or optional feature. NHTSA standards for Electronic Stability Control create a foundational technical platform for the system's integration. Automotive manufacturing hubs in Michigan, particularly around Detroit, concentrate development and integration efforts for these advanced features.
Germany
Strong consumer demand for premium vehicles, including SUVs and crossovers, stimulates the inclusion of sophisticated hill descent control systems. UN ECE regulations, which govern vehicle safety and ADAS integration, influence system design and deployment across the European market. Major automotive centers like Stuttgart and Munich are focal points for research and development in integrated chassis control systems.
China
The implementation of GB standards for new vehicles, particularly regarding braking system capabilities, creates a favorable technical environment for hill descent control adoption. The rapid expansion of the light commercial vehicle (LCV) segment in China also provides new volume opportunities for system suppliers. Automotive production bases in Shanghai and Guangzhou are actively integrating these features into diverse vehicle platforms.
Brazil
Rising sales of SUVs and pickup trucks, coupled with varied topography, present significant white-space opportunities for hill descent control system deployment. General vehicle safety standards and evolving consumer expectations for advanced features influence local OEM offerings. The automotive industry in São Paulo state, including cities like São Bernardo do Campo, drives the integration of such driver-assistance technologies.
Australia
Specialized off-road vehicle applications and rugged operating conditions prioritize robust hill descent control solutions, often integrating Inertial Measurement Units. Australian Design Rules (ADRs) dictate vehicle safety and performance requirements, impacting system specifications for local market vehicles. Automotive engineering firms in Melbourne and Adelaide focus on tailoring these systems for extreme terrain capabilities.
Global Automotive Hill Descent Control Market Key Industry Players
Top-tier vendors anchor the integrated ADAS segment, while specialized component suppliers focus on niche applications. The market exhibits a tiered structure, with established automotive technology providers competing alongside emerging sensor fusion specialists. Dominant competitive moves include strategic partnerships for ADAS integration and significant R&D investment in secure software architectures.
Within the established Tier-1 supplier landscape, German-based Bosch GmbH leverages its extensive portfolio in braking and stability control to offer integrated solutions to global vehicle manufacturers. Continental AG, another German-based technology company, exemplifies specialization in sensor fusion technologies that enhance system accuracy. ZF Friedrichshafen AG, also from Germany, occupies a strong position through its advanced chassis and driveline systems for both passenger and commercial vehicles.
| Leading Market Players |
|---|
| Knorr-Bremse |
| Hitachi Astemo |
| Bosch |
| Transtron |
| Murata |
| Continental |
| Hyundai Mobis |
| WABCO |
| ZF Friedrichshafen |
| Others |
Cost & Logistics Intelligence
Demand for software-defined features in premium vehicle segments drives supplier investment in integrated solutions, influencing component pricing and supply chain specialization. This shift prioritizes advanced functionality over raw material cost in many procurement decisions.
Pricing Analysis
Premium pricing for short lead times and highly customized hill descent control modules reflects the rapid integration demands of OEMs. The dominant pricing structure is contract-based long-term off-take agreements with Tier-1 suppliers. Price differentiation stems from the level of ADAS integration and the certification level for specific vehicle safety standards. Pricing softness reflects the increasing commoditization of basic electronic HDC systems in high-volume segments. Economy and mid-range vehicle segments exhibit the highest price sensitivity, whereas premium SUV manufacturers prioritize performance.
Supply Chain Analysis
UN ECE regulations for vehicle safety are reshaping sourcing strategies, emphasizing compliance and integration capabilities. Geographic supply concentration centers on Germany, China, and the United States for advanced automotive electronics. Raw material dependencies include specialized semiconductors for control units, high-performance sensors, and braking system components. Single-source vulnerability for specific ADAS microcontrollers presents a structural supply chain risk. Distribution runs through Tier-1 suppliers delivering integrated modules directly to OEM assembly lines globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive hill descent control market is navigating a technology-transition phase, with software-defined systems replacing legacy hydraulic functions. This evolution redefines value propositions and competitive dynamics for market participants.
For Market Incumbents: Acquire specialized software development firms to accelerate ADAS integration capabilities. Incumbents must counter the threat of agile software startups and evolving cybersecurity mandates like UN ECE Regulation 155. Invest heavily in secure-by-design principles for control units and leverage existing braking system expertise to offer comprehensive, integrated solutions. Expand capacity in key manufacturing hubs to meet rising global demand for integrated ADAS platforms.
For New Entrants and Emerging Players: UN ECE regulations in Europe open a window for specialized software developers focusing on ADAS integration. Target the fast-growing crossover and light commercial vehicle (LCV) segments, which offer significant white-space opportunities for advanced HDC features. A go-to-market angle emphasizing rapid customization and robust cybersecurity features for specific vehicle platforms can differentiate new players effectively. Focus on regions with evolving safety standards and high SUV/pickup truck sales.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with proven software integration capabilities and strong OEM relationships. Long-term viability hinges on the ability to deliver scalable, secure, and highly integrated ADAS solutions over the next five to ten years. Identify acquisition targets with expertise in sensor fusion or vehicle-to-everything (V2X) communication protocols. The signal to watch is the increasing standardization of ADAS architectures across vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enhances system flexibility and enables over-the-air updates for hill descent control features. |
| Sensor Fusion Technology Partnership | Improves system accuracy and reliability through combined data inputs for advanced control. |
| Cybersecurity Protocol Development | Secures communication links between HDC and other vehicle ECUs against external threats. |
| Light Commercial Vehicle Platform Expansion | Broadens the addressable market for HDC systems in a high-growth segment. |
| Global Regulatory Compliance Focus | Ensures market access and competitive advantage in regions with evolving safety mandates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary research involved interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations specialists. This approach combined qualitative insights with quantitative data, ensuring a robust analytical foundation through bottom-up and top-down triangulation.
Modeling at the vehicle category, system type, technology, and end-user levels provided granular market insights. The forecast framework integrated historical market trends and projected new vehicle production volumes across the analysis window. Compound annual growth rates were derived from a comprehensive assessment of technological adoption rates and regulatory impacts. ADAS penetration rates and consumer preference shifts served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for EV regenerative braking integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and vehicle market growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market