
 Vehicle Occupancy Detection System Market | 2026-2036
Vehicle Occupancy Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Occupancy Detection System Market Intelligence
Asset-light leasing models for sensor hardware and software subscriptions is tilting competitive dynamics toward platform providers with recurring revenue streams. Denso Corporation leverages its captive semiconductor supply to control cost structures across ultrasonic and infrared product lines. Continental AG anchors European OEM relationships through integrated cabin-monitoring architectures that bundle occupancy detection with advanced driver-assistance systems. Bosch competes on manufacturing scale, sustaining dual production footprints that serve both automotive manufacturers and aftermarket fleet channels.
A vehicle occupancy detection system comprises sensor arrays, processing units, and decision algorithms that classify seat-occupancy status, passenger count, or object presence within a vehicle cabin, typically operating at detection accuracies exceeding 95% under variable lighting and temperature conditions. Camera systems integrated with computer vision algorithms capture the fastest expansion trajectory as automakers phase out single-sensor configurations in favor of multimodal fusion architectures. Pressure sensors retain cost advantages in economy vehicle segments where OEMs prioritize hardware minimization, while machine learning deployments concentrate margin pools among tier-one suppliers offering trained inference models rather than raw components.
The National Highway Traffic Safety Administration in the United States and the European Union's General Safety Regulation collectively mandate occupant-classification capabilities for advanced restraint deployment, directly expanding addressable sensor volumes. Japan's Ministry of Economy, Trade and Industry coordinates domestic standards alignment with United Nations Economic Commission for Europe frameworks, reducing certification friction for suppliers serving multiple export markets. Stakeholders must monitor divergence between region-specific data-privacy requirements and real-time passenger-monitoring functionalities as regulatory frameworks for biometric capture crystallize.
Market Dynamics
The vehicle occupancy detection system market is being fundamentally restructured by the transition from discrete sensor modules to multimodal fusion architectures that combine camera, radar, and capacitive sensing into unified cabin-monitoring platforms.
Growth Catalysts
- EU General Safety Regulation:Mandates for occupant classification and child-presence detection are compelling European OEMs to install multi-sensor arrays across passenger vehicle lines.
- Machine-learning inference at the edge:Onboard neural processing units enable real-time passenger classification without cloud dependency, reducing latency for safety-critical restraint deployment decisions.
- Fleet digitization:Commercial vehicle operators in Germany and Japan are retrofitting occupancy data into route optimization and dynamic tolling systems.
Market Restraints
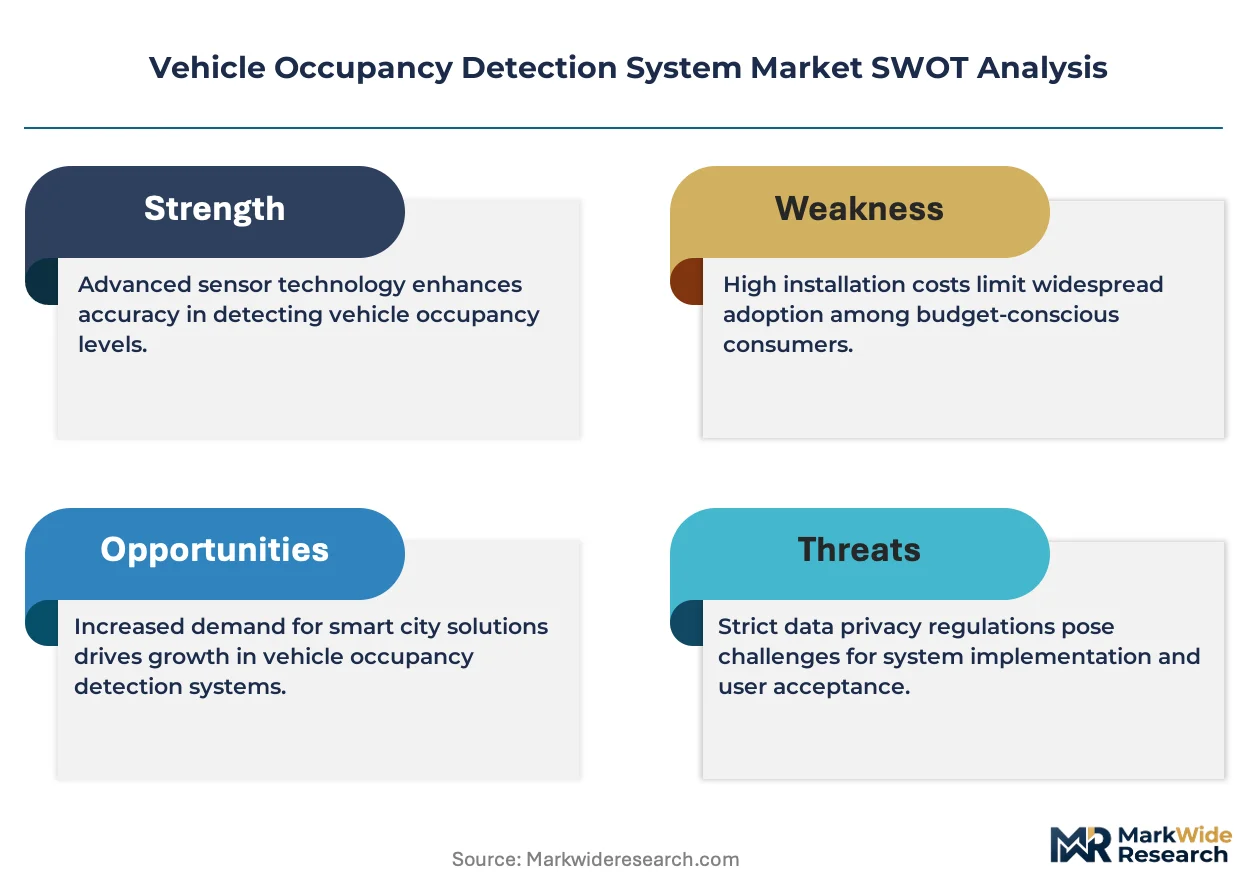
- Semiconductor supply concentration:Image signal processors and edge AI accelerators depend on concentrated foundry capacity in Taiwan, creating vulnerability to geopolitical disruption.
- GDPR biometric friction:Real-time facial recognition for occupant identification triggers data-privacy compliance costs and consent-management complexity in European deployments.
- Ultrasonic sensor commoditization:Mature piezoelectric technologies face margin compression from Chinese component suppliers, eroding tier-one pricing power in economy segments.
Strategic Opportunities
- India's automotive safety mandate expansion:Proposed Bharat New Vehicle Safety Assessment Program updates will likely incorporate occupant-sensing requirements for frontal crash protection.
- Subscription-based sensor-as-a-service:Leasing models for hardware and algorithm updates allow suppliers to capture recurring revenue from fleet operators managing large vehicle pools.
- LiDAR-camera fusion:Integration of solid-state LiDAR with computer vision enables three-dimensional cabin mapping for object detection in low-visibility conditions.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-B compliance for occupancy classification systems demands specialized hardware and software engineering talent that remains scarce.
- Legacy vehicle integration:Retrofitting multimodal architectures into existing electrical architectures requires protocol translation and power budget reallocation that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Occupancy Detection System Market |
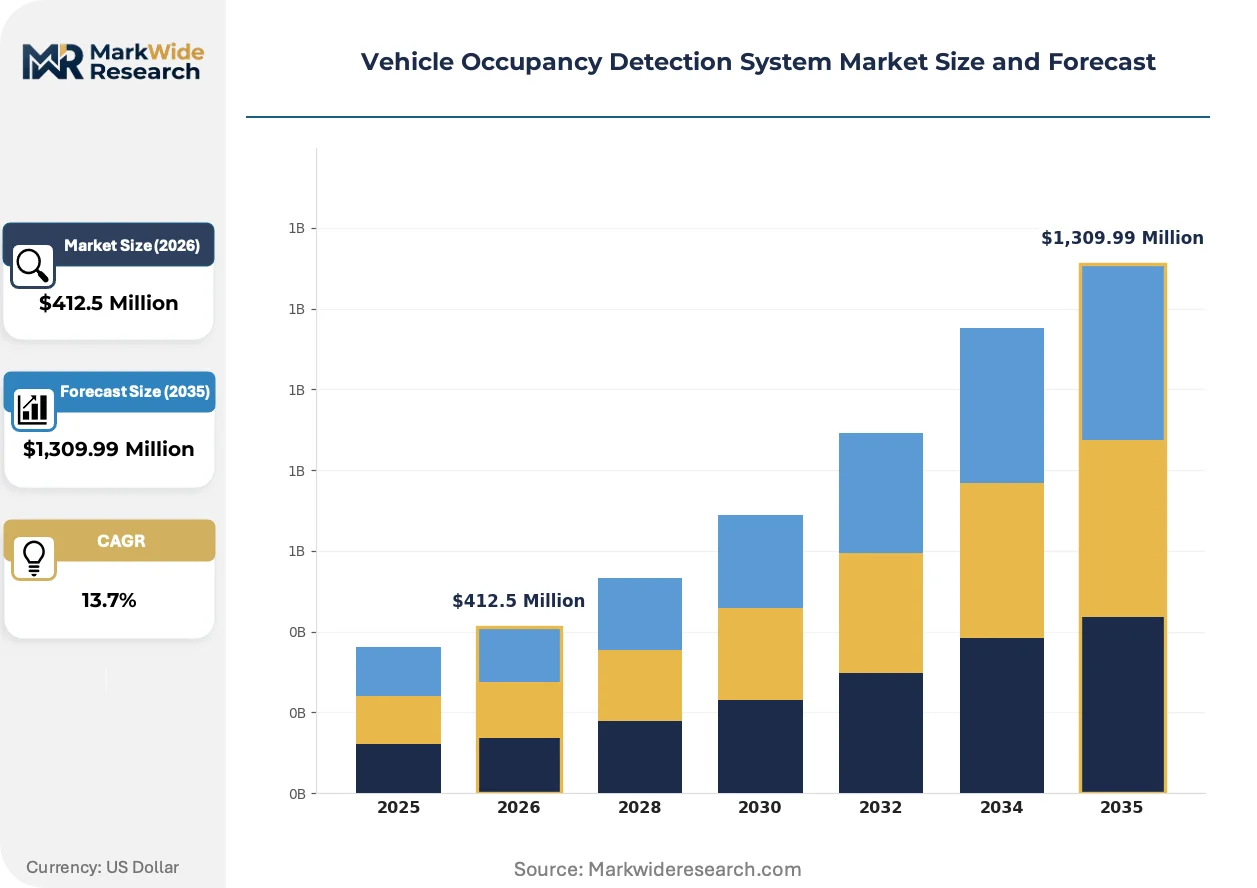
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Infrared Sensors, Pressure Sensors, Camera Systems Technology: Machine Learning, Computer Vision, RFID, Bluetooth Application: Smart Parking, Fleet Management, Public Transport, Ridesharing End User: Transport Authorities, Automotive Manufacturers, Fleet Operators, Service Providers |
| Companies Covered | Denso Corporation, Aptiv, Continental AG, Conduent Inc., ZF, Bosch, Autoliv, Indra Sistemas, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Occupancy Detection System Market Strategic Shifts & Innovations
Multimodal sensor fusion is compressing the competitive landscape by rewarding suppliers with integrated software-hardware capabilities while marginalizing component-only vendors.
Time-of-flight cameras paired with near-infrared illuminators are collapsing the cost-performance gap between premium and mid-tier occupancy detection systems. German and Japanese OEMs are adopting these configurations for 2026 model year vehicles. The technology is collapsing tier boundaries by delivering 3D depth mapping at price points previously associated with basic 2D imaging.
The EU AI Act's risk classification for biometric identification systems is imposing documentation and conformity assessment burdens on cabin-monitoring suppliers. Manufacturers must now maintain technical files demonstrating algorithmic transparency and bias mitigation. European tier-one suppliers are responding by segregating inference models into safety-critical and convenience-only functional blocks.
Fleet procurement teams are consolidating vendor relationships around platform providers offering unified hardware, software, and data analytics. Long-term service agreements with guaranteed algorithm update frequencies are displacing traditional component purchasing. This concentration is most pronounced in North American commercial vehicle segments where telematics integration drives sourcing decisions.
Vehicle Occupancy Detection System Market Segmentation
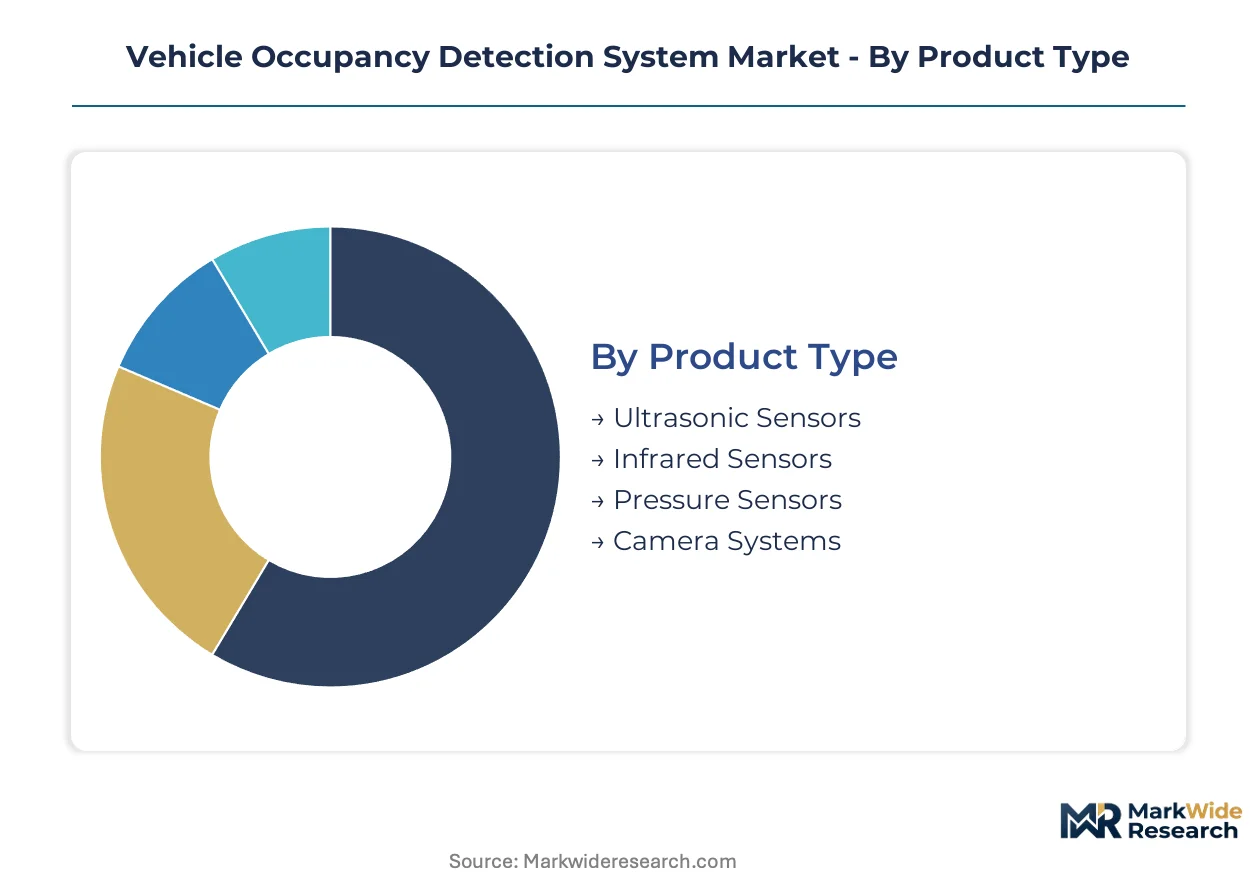
Segmentation in vehicle occupancy detection reveals how sensor modalities, processing architectures, and deployment contexts fragment addressable value pools. Technology choices cascade into divergent margin structures and certification requirements across passenger and commercial vehicle applications.
Product Type:
Mature piezoelectric technologies coexist with emerging multimodal fusion platforms, creating tiered performance-cost trade-offs across vehicle classes.
- Ultrasonic Sensors:Piezoelectric transducers emit high-frequency acoustic pulses to detect seat occupancy through reflected signal analysis. Automotive manufacturers in Germany specify these for economy vehicle lines where hardware minimization overrides classification precision.
- Camera Systems:CMOS image sensors paired with near-infrared illuminators capture 2D and 3D cabin data for computer vision processing. Fleet operators in North America concentrate procurement on these configurations for integrated telematics and driver monitoring compliance.
- Infrared Sensors:Thermopile arrays measure passenger presence through thermal radiation detection without visible light dependency.
- Pressure Sensors:Capacitive and resistive load cells embedded in seat structures detect occupancy through weight distribution changes.
Ultrasonic sensors retain volume leadership in economy vehicle production; camera systems hold the steepest expansion curve as multimodal architectures displace single-sensor configurations.
Technology:
Processing methodologies separate edge-based inference from legacy signal processing, concentrating value capture among suppliers with trained algorithm portfolios.
- Machine Learning:Neural network models trained on occupant classification datasets enable real-time inference without cloud connectivity. Edge AI deployments in Japan prioritize these systems for latency-critical restraint deployment decisions.
- Computer Vision:Convolutional and transformer-based architectures process image streams for passenger count, position, and biometric identification. European OEMs face GDPR compliance costs when deploying facial recognition capabilities for occupant authentication.
- RFID:Radio-frequency identification tags and readers enable automated passenger counting in controlled-access transit environments.
- Bluetooth:Low-energy beacon detection supports occupancy verification through paired mobile device proximity sensing.
Machine learning commands premium pricing in safety-critical applications; computer vision expands most quickly across convenience and fleet management use cases.
Application:
Deployment contexts range from static infrastructure integration to dynamic vehicle-based monitoring, each imposing distinct latency and accuracy specifications.
- Fleet Management:Commercial vehicle operators integrate occupancy data with route optimization, dynamic tolling, and utilization analytics. German logistics companies retrofit these systems to comply with driver hour regulations and passenger transport licensing.
- Ridesharing:Mobility platforms deploy cabin monitoring to verify passenger count, detect unauthorized occupancy, and support incident investigation. Service providers in North America bundle these capabilities with telematics for insurance premium reduction.
- Smart Parking:Infrastructure-mounted sensors track vehicle occupancy status in managed parking facilities.
- Public Transport:Transit authorities deploy automated passenger counting for load balancing, fare compliance, and service planning.
Fleet management captures the largest current revenue pool; ridesharing applications are gaining share fastest as mobility platforms consolidate vendor relationships around integrated hardware-software platforms.
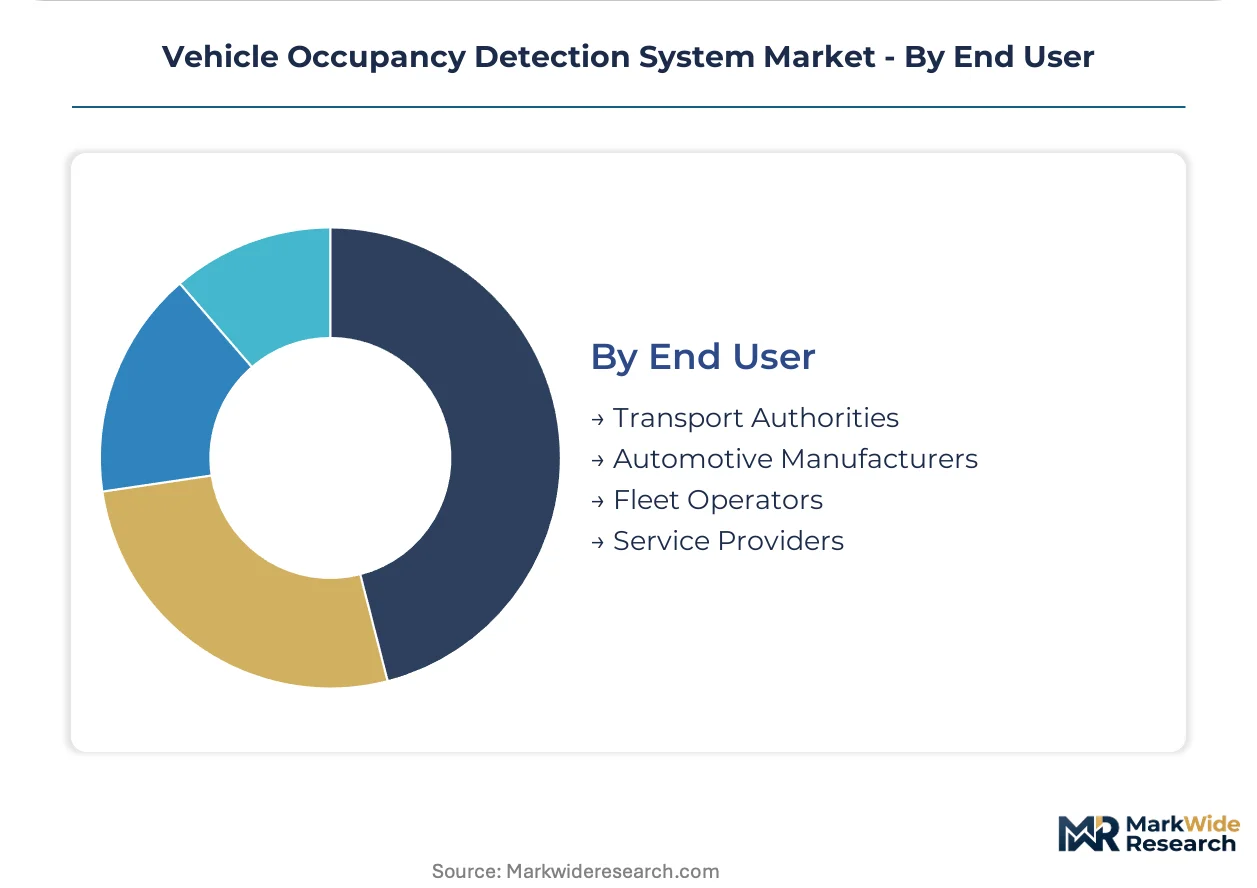
End User:
Procurement authority concentrates among entities with direct regulatory exposure or operational scale sufficient to justify platform-level investments.
- Automotive Manufacturers:OEMs specify occupancy detection systems for new vehicle platforms under NHTSA and EU General Safety Regulation mandates. Japanese manufacturers coordinate with METI to align domestic certification with United Nations Economic Commission for Europe frameworks.
- Fleet Operators:Commercial vehicle managers procure retrofit solutions and long-term service agreements with guaranteed algorithm update frequencies. North American trucking and transit fleets drive demand for subscription-based sensor-as-a-service models.
- Transport Authorities:Government agencies specify occupancy monitoring for public transit infrastructure and regulatory compliance verification.
- Service Providers:Mobility platforms, insurers, and telematics integrators bundle occupancy data into broader vehicle analytics offerings.
Automotive manufacturers dominate absolute volume; fleet operators represent the fastest-climbing segment as asset-light leasing models displace component purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing in Germany and Japan generates surplus capacity for occupancy detection components, while the United States and China absorb significant import volumes to serve domestic fleet digitization and automotive safety mandates.
Germany
Automotive OEMs in Stuttgart and Munich drive procurement of multimodal cabin-monitoring architectures. KBA enforcement of EU General Safety Regulation occupant-classification mandates accelerates sensor array installations across passenger vehicle platforms. Suppliers cluster around Baden-Württemberg's automotive corridor, integrating pressure and camera systems for premium vehicle lines.
United States
Fleet operators in Texas and California retrofit commercial vehicles with subscription-based occupancy analytics for route optimization. NHTSA mandates for advanced restraint deployment expand addressable volumes for edge AI inference systems. Detroit's automotive engineering base anchors development partnerships between tier-one suppliers and domestic OEMs.
Japan
Domestic manufacturers coordinate with METI to align certification standards with United Nations Economic Commission for Europe frameworks. Toyota City and Nagoya host concentrated R&D activity in time-of-flight camera integration for 2026 model year deployments. Pressure sensor production maintains cost advantages for economy vehicle segments across Aichi Prefecture.
China
Domestic OEMs in Shanghai and Shenzhen accelerate adoption of computer vision systems for ridesharing fleet compliance. MIIT guidelines on intelligent vehicle cabin monitoring create regulatory clarity for biometric data processing. Yangtze River Delta manufacturing clusters scale production of ultrasonic modules for export to Southeast Asian automotive assembly plants.
South Korea
Hyundai Motor Group suppliers in Ulsan and Gwangju deploy solid-state LiDAR fusion systems for three-dimensional cabin mapping. MFDS alignment with international functional safety standards reduces certification friction for export-bound occupancy detection platforms. Seoul Capital Area software houses concentrate machine-learning model training for real-time passenger classification.
Vehicle Occupancy Detection System Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform providers capable of delivering unified hardware-software-data architectures rather than discrete component vendors. Tier-one automotive suppliers compete through captive semiconductor supply chains and long-term OEM service agreements. Three strategic archetypes dominate: full-stack cabin-monitoring integrators, sensor-specialist component manufacturers, and fleet-focused platform-as-a-service operators. M&A activity concentrates on machine-learning algorithm portfolios, while geographic expansion targets Indian and Southeast Asian automotive safety mandate implementation.
Among established tier-one automotive suppliers, Denso Corporation, Continental AG, and Bosch exemplify the integrated platform archetype. Denso leverages Japanese semiconductor supply relationships across ultrasonic and infrared product lines. Continental AG anchors European OEM partnerships through bundled cabin-monitoring and advanced driver-assistance architectures. Bosch sustains dual production footprints serving both automotive manufacturers and aftermarket fleet channels through manufacturing scale advantages.
| Leading Market Players |
|---|
| Denso Corporation |
| Aptiv |
| Continental AG |
| Conduent Inc. |
| ZF |
| Bosch |
| Autoliv |
| Indra Sistemas |
| Valeo |
| Others |
Cost & Logistics Intelligence
Undercapacity in Taiwan's foundry capacity for image signal processors is compressing lead times for tier-one automotive suppliers while elevating pricing power among semiconductor fabricators serving the vehicle occupancy detection system value chain.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the vehicle occupancy detection system market. Premium multimodal fusion platforms command valuation premiums tied to ISO 26262 ASIL-B certification and bundled software update commitments. Cost compression in ultrasonic sensor modules is intensifying because Chinese component suppliers are flooding economy segments with commoditized piezoelectric transducers. Fleet operators exhibit the highest price sensitivity due to volume procurement leverage, while luxury automotive manufacturers remain least sensitive when integrated cabin-monitoring architectures are bundled with advanced driver-assistance systems.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment are restricting flows of extreme ultraviolet lithography systems to certain fabrication facilities, concentrating edge AI accelerator production in Taiwan and South Korea. The vehicle occupancy detection system supply chain draws from Japanese CMOS image sensor design houses, German automotive-grade pressure sensor manufacturers, and Taiwanese neural processing unit foundries. Single-source vulnerability in advanced packaging capacity creates structural risk for suppliers dependent on concentrated backend processing. Distribution runs through tier-one automotive supplier networks that maintain direct OEM relationships and aftermarket fleet service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation around platform-as-a-service procurement models is shifting buyer power toward entities with sufficient vehicle scale to demand long-term algorithm update guarantees and unified hardware-software-data architectures.
For Market Incumbents: Entrench defensive positions by securing captive semiconductor supply agreements with Taiwanese foundries to isolate against geopolitical disruption, and accelerate ISO 26262 ASIL-B certification investments to create regulatory moats against emerging sensor-fusion competitors. Machine-learning algorithm portfolios represent the critical lever for sustaining margin pools as raw component sales commoditize. For New Entrants and Emerging Players: India's proposed Bharat New Vehicle Safety Assessment Program updates present the most penetrable geographic expansion opportunity, given limited incumbent presence in occupant-sensing retrofit solutions for domestic automotive assembly. Target ridesharing fleet operators with subscription-based sensor-as-a-service offerings that bundle hardware leasing with real-time occupancy analytics, bypassing capital-intensive OEM qualification cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multimodal fusion platform development, favoring acquisition targets with trained inference model libraries over hardware-only component manufacturers. Algorithm-centric tier-one suppliers with established European OEM relationships offer the strongest long-term viability profile. Monitor divergence between EU AI Act biometric compliance costs and real-time passenger monitoring functionality as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Algorithm Acquisition | Trained inference models concentrate margin pools away from commoditized sensor hardware. |
| Semiconductor Supply Agreement | Captive foundry capacity insulates tier-one suppliers from Taiwan geopolitical risk exposure. |
| Functional Safety Certification Investment | ISO 26262 ASIL-B compliance creates regulatory barriers against unqualified competitors. |
| Sensor-as-a-Service Platform Launch | Recurring revenue models capture fleet operator procurement consolidation. |
| LiDAR-Camera Fusion Development | Three-dimensional cabin mapping enables premium positioning in low-visibility applications. |
Research Approach
A spread of perspectives from OEM platform engineers, tier-one supplier procurement directors, fleet operations managers, and automotive semiconductor specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and United Nations Economic Commission for Europe regulatory documentation. Bottom-up sensor volume estimates triangulated against top-down market value reconstructions.
Demand-supply balance modeling across the projection horizon integrated segmentation dimensions spanning sensor modality, processing architecture, vehicle class, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology-specific adoption trajectories. Forecast inputs incorporated NHTSA mandate implementation timelines, EU General Safety Regulation enforcement schedules, and fleet digitization spending patterns.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor foundries or platform consolidation by hyperscaler entrants would shift outcomes. Material shifts in Taiwan semiconductor access restrictions or EU AI Act biometric enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Airbags Market