
 Occupant Classification System Market | 2026-2036
Occupant Classification System Market Size, Share, and Industry Trends Forecast 2026-2036
Occupant Classification System Market Analysis
The gap between premium and commodity occupant classification tiers is broadening. Bosch leverages in-house MEMS fabrication to sustain margin on force-sensitive resistor arrays. Denso anchors its position through thermal-compensated capacitive mats calibrated for Asian vehicle platforms. ZF Friedrichshafen competes by integrating pressure-sensor foams with seat-structure modules.
Occupant classification systems detect passenger presence, weight, and position through resistive, capacitive, or piezoelectric sensor matrices embedded in seat cushions, with signal conditioning electronics transmitting data to airbag control modules for deployment decisions. Sensor-based systems dominate current revenue as automakers prioritize hardware redundancy for FMVSS 208 compliance. Software solutions represent the fastest-expanding margin pool as edge-computing architectures enable real-time classification without dedicated control units.
NHTSA, Euro NCAP, and Japan's MLIT enforce divergent test protocols that fragment certification requirements across export markets. The EU's General Safety Regulation mandates advanced occupant status monitoring for new vehicle types, pressuring suppliers to support multi-standard firmware. Stakeholders must track how software-defined vehicle architectures redistribute classification logic from discrete modules to domain controllers.
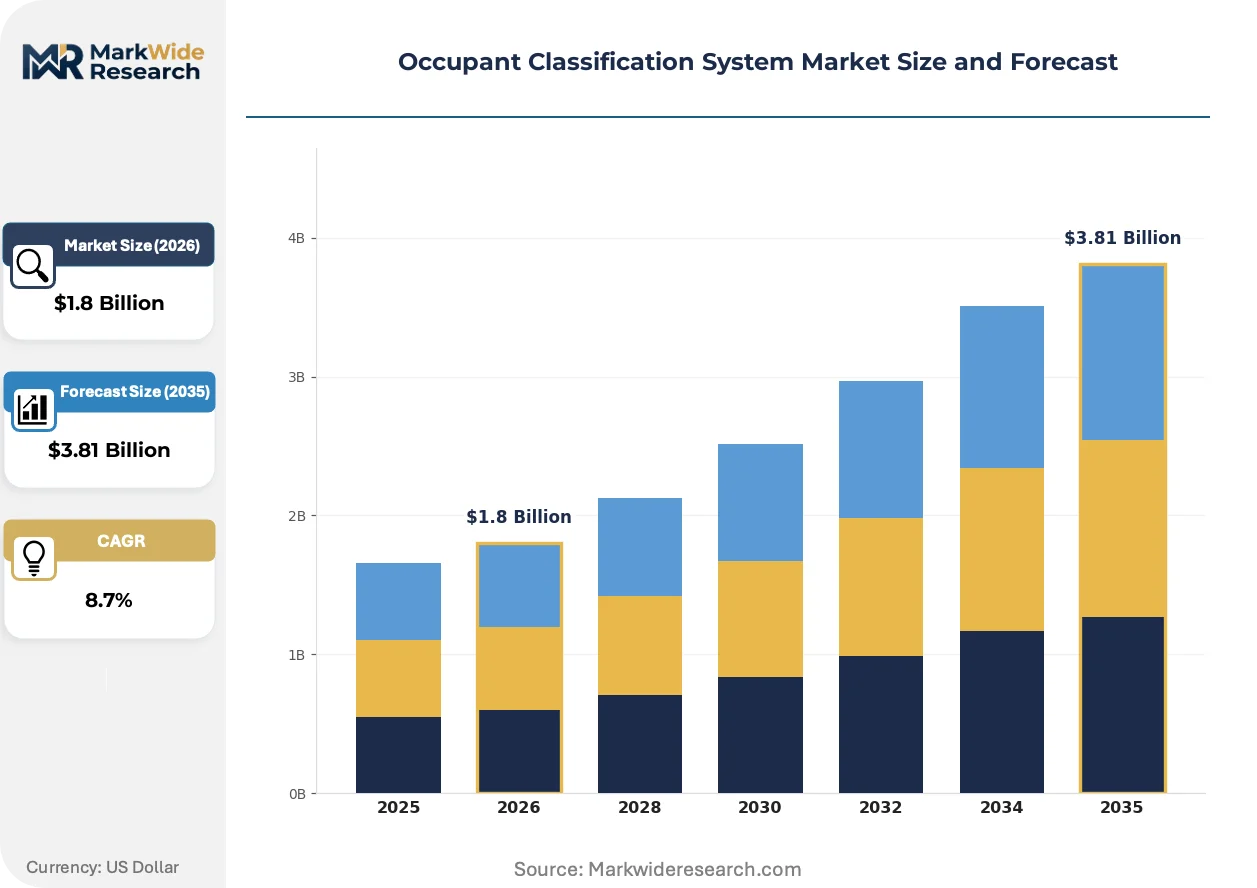
Market Dynamics
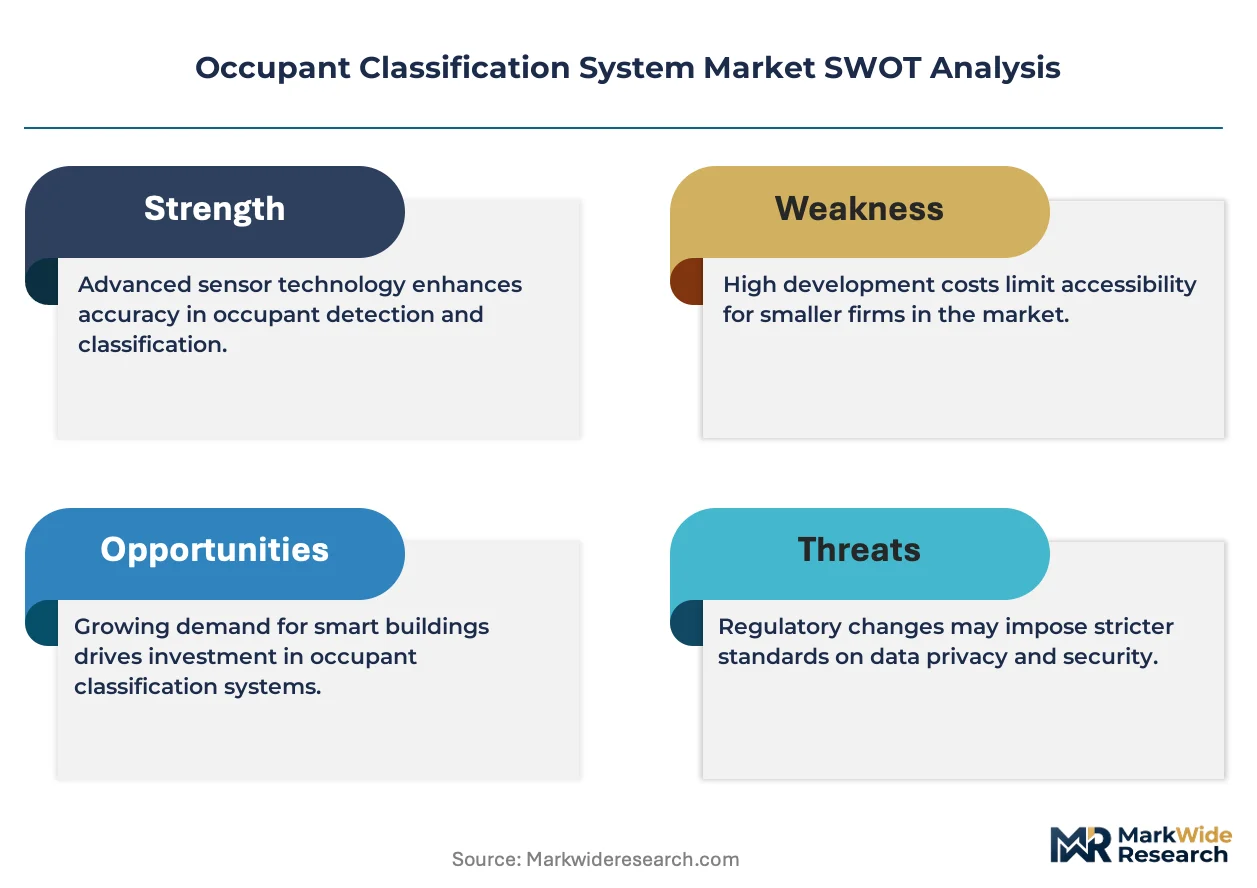
Software-defined vehicle architectures are redistributing occupant classification logic from discrete modules to domain controllers, forcing suppliers to restructure hardware-software value capture.
Growth Catalysts
- NHTSA FMVSS 208:Mandates for advanced airbag suppression systems drive sensor hardware upgrades across US vehicle platforms.
- Capacitive sensing:Thermal-compensated mats calibrated for Asian vehicle platforms enable precise weight-position detection without mechanical fatigue.
- German manufacturing clusters:Concentration of sensor fabrication near Stuttgart and Munich accelerates OEM prototype-to-production cycles.
Market Restraints
- MEMS wafer supply:Concentration of force-sensitive resistor fabrication in Taiwan creates single-source vulnerability for Bosch-tier suppliers.
- Euro NCAP protocol divergence:Test methodology variations between European and Japanese certification bodies inflate firmware validation costs.
- Silicone foam input volatility:Pressure-sensor substrate materials face petrochemical price swings that compress module margins.
Strategic Opportunities
- Edge-computing architectures:Real-time classification without dedicated control units opens margin pools in software licensing.
- EU General Safety Regulation:Advanced occupant status monitoring mandates create firmware upgrade revenue streams for existing installed base.
- India vehicle safety norms:Underpenetrated passenger-car segment offers first-mover advantage for capacitive-mat suppliers.
Industry Challenges
- Multi-standard firmware engineering:NHTSA, Euro NCAP, and Japan MLIT test protocol fragmentation strains development bandwidth.
- Legacy airbag module integration:Domain controller migration requires backward compatibility with 1990s-era CAN bus architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Occupant Classification System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-based Systems, Camera-based Systems, Software Solutions, Hybrid Systems Application: Smart Buildings, HVAC Control, Security Systems, Energy Management End User: Residential, Commercial, Industrial, Academic Institutions Technology: RFID, Infrared, Machine Learning, Computer Vision |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, ZF Friedrichshafen AG, Continental AG, IEE Smart Sensing Solutions, Aptiv, AISIN Corporation, Autoliv Inc., HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Occupant Classification System Market Emerging Trajectories
Signal processing at the sensor edge is compressing the traditional control-unit hierarchy, enabling new entrants to bypass incumbent module suppliers.
Machine-learning inference engines embedded directly in seat-cushion sensor arrays are automating occupant classification without upstream controller arbitration. Automotive OEMs in Germany and Japan are adopting these architectures for 2026 platform refreshes. This compression of the signal chain is automating tier-one supplier displacement in low-complexity vehicle segments.
Euro NCAP's 2026 roadmap mandates child-presence detection as a scoring criterion, forcing capacitive-mat suppliers to add ultrasonic or radar fusion layers. The EU General Safety Regulation accelerates this timeline for new vehicle types. Suppliers serving European OEMs must now maintain dual-certification tracks for basic and advanced occupant monitoring tiers.
Fleet operators now specify outcome-based sensor performance contracts rather than hardware unit purchases, shifting warranty risk to subsystem suppliers. Rental and ride-hail channels in the United States are driving this model fastest. Tier-one suppliers face working-capital pressure as payment terms extend to match vehicle-mileage verification cycles.
Occupant Classification System Market Segmentation
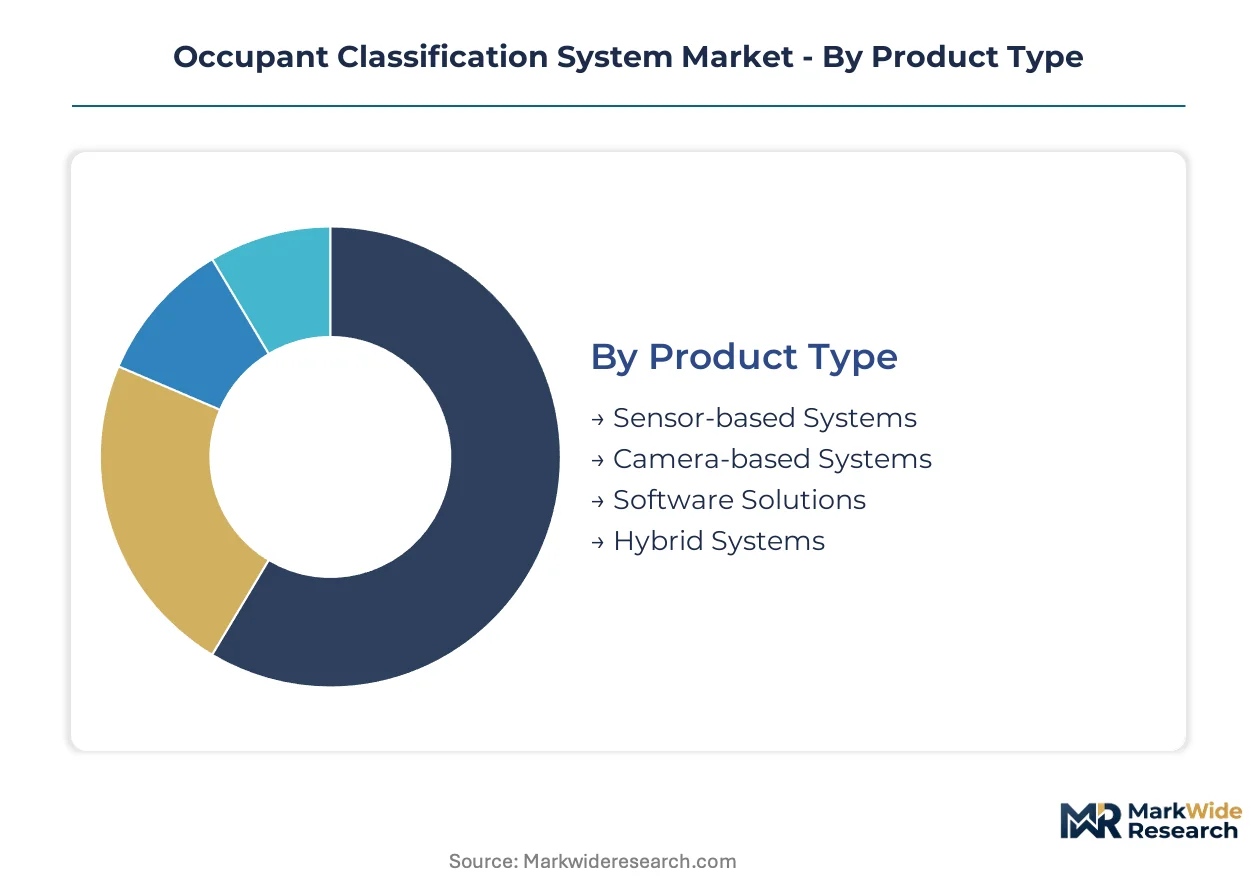
Occupant classification systems fragment across hardware-software boundaries and deployment contexts. Each segment carries distinct margin profiles and regulatory certification requirements that reshape supplier positioning.
Product Type:
Volume concentration favors established hardware platforms while premium capture shifts toward software-defined architectures.
- Sensor-based Systems:Resistive, capacitive, and piezoelectric matrices embedded in seat cushions transmit passenger presence and weight data to airbag control modules. Demand concentrates in Germany, Japan, and the United States where NHTSA FMVSS 208 and Euro NCAP protocols mandate hardware redundancy for crashworthiness compliance.
- Software Solutions:Edge-computing firmware enables real-time classification without dedicated control units, redistributing logic to domain controllers. This segment is climbing the fastest as automotive OEMs adopt software-defined vehicle architectures for platform refreshes.
- Camera-based Systems:Optical sensors mounted in cabin headliners capture occupant position and posture through infrared or visible-spectrum imaging.
- Hybrid Systems:Multi-modal fusion of pressure-sensor arrays with computer-vision layers for redundant classification pathways.
Mature deployment sits with sensor-based systems. Newer deployment is concentrated in software solutions.
Application:
End-use concentration tracks building automation maturity and energy-code stringency across major economies.
- Smart Buildings:Integrated occupancy detection drives HVAC zoning, lighting control, and access management through centralized building management systems. Demand clusters in commercial retrofits where energy-efficiency mandates from the EU Green Deal and similar frameworks accelerate sensor deployment.
- HVAC Control:Real-time occupancy data enables demand-responsive climate conditioning, reducing energy consumption in variable-occupancy spaces. This application is gaining share fastest as facility operators face carbon-reduction targets and utility cost pressures.
- Security Systems:Presence verification for intrusion detection and emergency response coordination in commercial and institutional facilities.
- Energy Management:Granular occupancy analytics for load balancing and peak-demand reduction in grid-interactive buildings.
Established penetration sits with security systems. Accelerating deployment is concentrated in HVAC control.
End User:
Customer-type segmentation reveals divergent procurement patterns between capital-project channels and retrofit upgrade cycles.
- Commercial:Office complexes, retail centers, and hospitality venues deploy large-scale occupancy networks for operational efficiency and tenant experience differentiation. Procurement runs through facilities management contractors and building automation integrators with multi-year service agreements.
- Residential:Single-family and multi-family dwellings adopt occupant sensing through smart home ecosystems and energy-utility rebate programs. This segment is expanding most quickly as connected-home platforms integrate presence detection for security, climate, and lighting automation.
- Industrial:Manufacturing facilities and warehouses utilize occupant classification for safety-zone monitoring and ergonomic workstation optimization.
- Academic Institutions:Campuses deploy room-level occupancy tracking for space-utilization analytics and emergency mass-notification systems.
Deep installed base sits with commercial. Emerging volume is concentrated in residential.
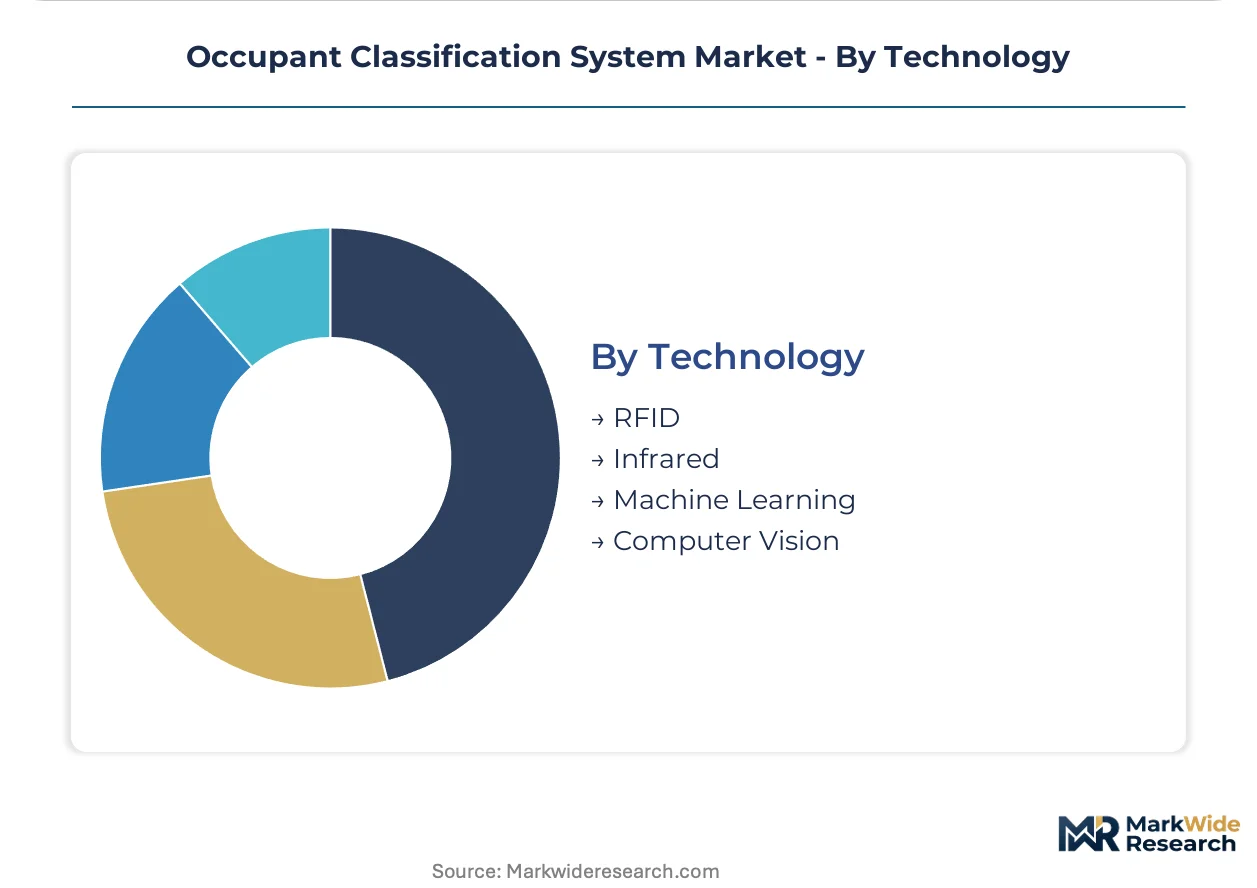
Technology:
Technology choice reflects trade-offs between deployment cost, classification accuracy, and privacy compliance requirements.
- Computer Vision:Camera-based systems with embedded inference engines process visual data for occupant count, position, and activity recognition. Demand concentrates in security-sensitive applications where GDPR and similar privacy frameworks drive edge-processing architectures that minimize data transmission.
- Machine Learning:Pattern-recognition algorithms trained on occupancy datasets enable predictive classification and anomaly detection. This technology is showing the steepest expansion trajectory as cloud-training and edge-inference pipelines mature for building-automation deployments.
- Infrared:Passive and active thermal sensing for presence detection without visible-light illumination, preserving privacy in sensitive environments.
- RFID:Badge-based and passive-tag systems for credential-verified access control and coarse-grained location tracking.
Legacy dominance sits with RFID. Technology transition is concentrated in machine learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the global occupant classification supply chain through its concentration of automotive sensor fabrication and Tier-1 module assembly. Manufacturing clusters in southern Germany, central Japan, and the US Midwest synchronize prototype-to-production cycles for NHTSA and Euro NCAP compliance.
United States
NHTSA FMVSS 208 mandates drive sensor hardware upgrades across Detroit Three platforms. The regulation requires advanced airbag suppression systems with redundant weight detection. Michigan's automotive corridor hosts validation labs and module integration facilities serving North American OEM assembly plants.
Germany
Euro NCAP's 2026 child-presence detection scoring criterion accelerates capacitive-mat fusion with ultrasonic layers. The EU General Safety Regulation tightens compliance timelines for new vehicle types. Baden-Württemberg's sensor fabrication ecosystem near Stuttgart supplies force-sensitive resistor arrays to European premium OEMs.
Japan
MLIT test protocols for occupant status monitoring diverge from European and US certification standards. METI guidance on software-defined vehicle architectures redistributes classification logic to domain controllers. Nagoya's automotive supplier cluster develops thermal-compensated capacitive mats calibrated for domestic vehicle platforms.
China
GB standards for passenger safety systems incorporate NCAP-equivalent crashworthiness requirements. MIIT regulations on intelligent connected vehicles create firmware upgrade pathways for existing installed bases. Yangtze River Delta manufacturing zones assemble pressure-sensor modules for domestic OEMs and export markets.
India
Bureau of Indian Safety norms for passenger cars mandate occupant detection systems in new vehicle categories. PLI scheme incentives for automotive electronics attract capacitive-mat suppliers to establish local production. Tamil Nadu's vehicle assembly corridor offers first-mover positioning for sensor subsystem vendors.
Occupant Classification System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and software-integration capabilities. The market structures into three tiers: integrated automotive electronics conglomerates with captive MEMS fabrication, specialized sensor subsystem suppliers with OEM-validated module designs, and emerging software-centric entrants leveraging edge-computing architectures. Consolidation pressure intensifies as domain controller migration eliminates discrete control-unit suppliers. Strategic moves concentrate on backward integration into sensor wafer supply and multi-standard firmware engineering partnerships.
Within the integrated conglomerate tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes combining in-house MEMS fabrication with validated OEM supply relationships. ZF Friedrichshafen AG occupies a position bridging hardware-software value capture through seat-structure module integration. These three anchors represent divergent responses to software-defined vehicle redistribution of classification logic.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| IEE Smart Sensing Solutions |
| Aptiv |
| AISIN Corporation |
| Autoliv Inc. |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Fleet outcome-based procurement contracts for ride-hail and rental channels in the United States force suppliers to absorb warranty risk across extended mileage verification cycles, compressing working capital and pushing tier-one module vendors toward captive MEMS fabrication or Asian foundry partnerships to recover margin.
Pricing Analysis
Outcome-based performance guarantees now anchor pricing structures as fleet operators shift from hardware unit purchases to sensor-subsystem contracts tied to verified vehicle-mileage thresholds. Three-tier pricing stratification separates FMVSS 208-certified premium arrays from Euro NCAP-basic mid-tier mats and economy-grade resistive sensors for emerging-market platforms. Pricing pressure intensifies in the commodity tier as Chinese module assemblers leverage Yangtze River Delta manufacturing scale. Automotive OEMs exhibit lowest price sensitivity for child-presence detection fusion systems mandated by EU General Safety Regulation timelines.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds and China's MIIT localization mandates for intelligent connected vehicles are reshaping sourcing patterns away from Taiwan-centric MEMS wafer supply. Force-sensitive resistor fabrication draws from Taiwan, South Korea, and Germany while silicone foam substrates and capacitive-mat polymers feed from Japan and the United States. Single-source vulnerability concentrates in Taiwan's 200mm MEMS foundry capacity. Distribution runs through validated Tier-1 module suppliers to OEM seat-structure integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS wafer foundry capacity constraints prop pricing power for suppliers with captive fabrication or qualified second-source relationships, creating a supply-constrained market structure through the projection horizon.
For Market Incumbents: Anticipate displacement risk from edge-computing sensor architectures that bypass discrete control-unit suppliers by embedding machine-learning inference directly in seat-cushion arrays. Secure position through backward integration into force-sensitive resistor wafer supply and multi-standard firmware engineering partnerships spanning NHTSA, Euro NCAP, and Japan MLIT protocols. Prioritize thermal-compensated capacitive-mat R&D for Asian platform calibration requirements. For New Entrants and Emerging Players: The premium-to-economy price gap in occupant classification modules offers entry traction for software-centric vendors with edge-computing firmware architectures. Target India's underpenetrated passenger-car segment where Bureau of Indian Safety norms create first-mover positioning for capacitive-mat suppliers establishing Tamil Nadu production. Pursue direct OEM engagement through domain-controller integration partnerships rather than legacy module-supplier channel structures. For Investors and Strategic Acquirers: The window for entry favors specialized sensor subsystem suppliers with OEM-validated module designs and multi-standard certification track records. Long-term viability hinges on software-defined vehicle architecture compatibility and domain-controller migration readiness. Monitor Euro NCAP child-presence detection scoring implementation as inflection indicator for fusion-system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Backward Integration | Captive wafer supply insulates Bosch-tier suppliers from Taiwan single-source vulnerability. |
| Multi-Standard Firmware Platform | Unified NHTSA-Euro NCAP-MLIT compliance reduces validation cost for export-market OEMs. |
| Edge-Computing Sensor Architecture | Embedded inference engines enable real-time classification without dedicated control units. |
| India PLI Manufacturing Footprint | Tamil Nadu assembly localizes capacitive-mat production for domestic OEM and export demand. |
| Domain Controller Integration Partnership | Software-defined vehicle redistribution creates Tier-1 displacement opportunity for firmware specialists. |
Methodological Framework
Multi-period observation of NHTSA regulatory filing timelines, Euro NCAP protocol revisions, and OEM platform refresh cycles anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement officers, OEM platform engineers, automotive sensor R&D directors, and fleet operator specification managers. Secondary validation drew from NHTSA FMVSS 208 docket records, Euro NCAP technical bulletins, Japan MLIT test procedure updates, and vehicle production databases. Bottom-up segment sizing triangulated against top-down automotive electronics spending estimates.
Segment-weighting across sensor-based systems, software solutions, camera-based systems, and hybrid architectures informed the analytical framework over the projection horizon, with vehicle class, propulsion architecture, content per vehicle, and regional production cluster as modeled dimensions. CAGRs derived from fitted growth curves applied to validated baseline estimates. Forecast inputs incorporated software-defined vehicle adoption trajectories and child-presence detection mandate timelines.
Underlying measurement precision varies by segment; software solutions carry tighter precision than emerging hybrid-system categories given deployment immaturity. Forecasts reflect documented assumptions regarding regulatory implementation schedules and OEM platform transition timing. Sensor wafer supply disruptions or protocol divergence acceleration could revise trajectory estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market