
 Automotive Airbag Inflator Market | 2026-2036
Automotive Airbag Inflator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag Inflator Market Outlook
Passenger vehicle electrification is rebalancing the end-use mix, with battery-electric platforms requiring redesigned cabin architectures and novel inflator placement strategies. Autoliv Inc. leverages its pyrotechnic expertise to anchor supply relationships with European premium automakers. Daicel Corporation sustains dominance in hybrid inflator chemistry through proprietary gas-generant formulations. Joyson Safety Systems competes aggressively in the Chinese OEM channel with localized production scale.
An automotive airbag inflator is a gas-generating device that initiates rapid inflation of a nylon fabric airbag cushion within milliseconds of a crash pulse detection, typically using sodium azide-based or nitroguanidine-driven pyrotechnic reactions producing gas volumes of 60–200 liters depending on seating position and occupant classification. Combo inflators lead unit volume due to their dual-stage deployment architecture satisfying frontal and side-impact requirements in a single module, while hybrid inflators command premium positioning through stored-gas augmentation that enables cooler deployment temperatures and reduced particulate emissions. Sensor-based activation technology is displacing mechanical-only trigger designs as automakers integrate inflator control with central domain architectures and pre-crash sensing algorithms.
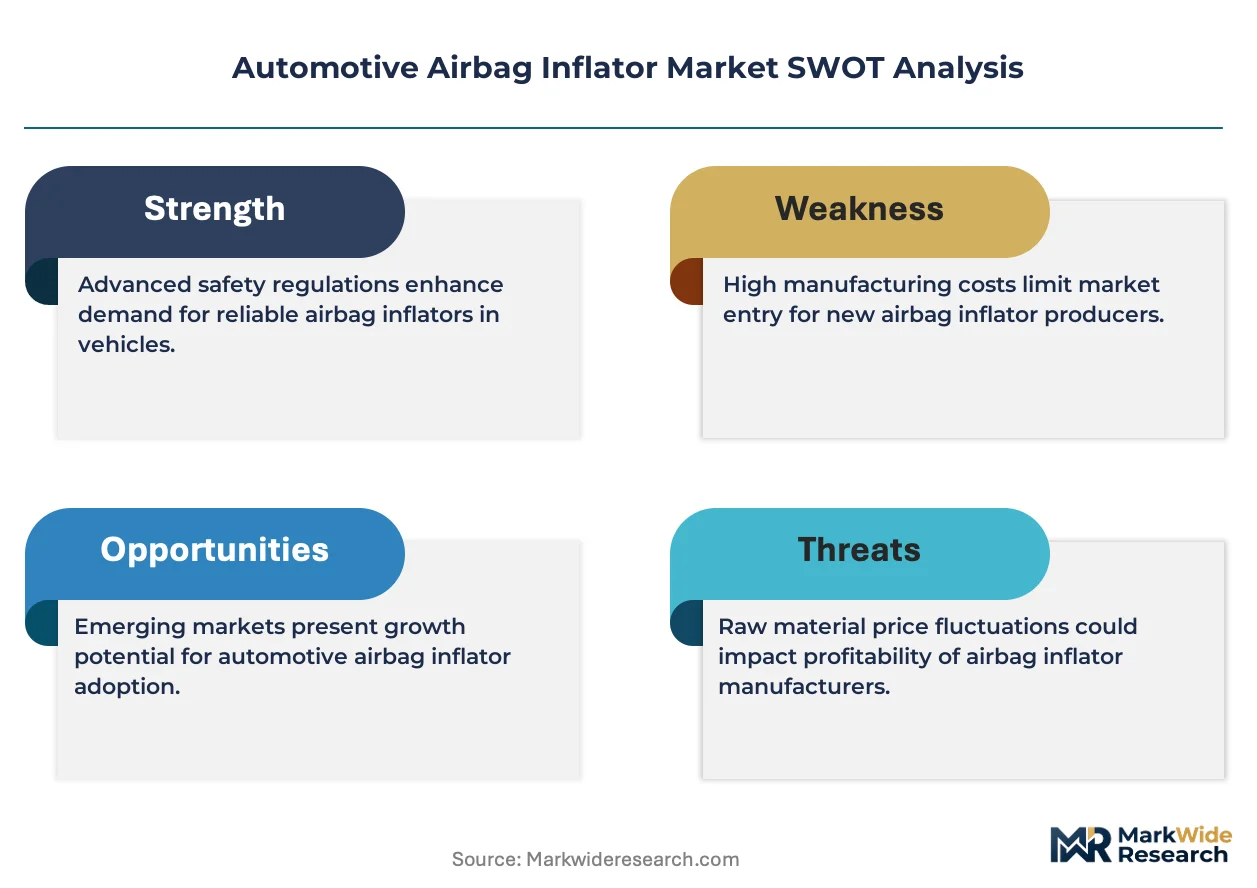
NHTSA enforces FMVSS 208 occupant crash protection standards that mandate specific deployment force curves and out-of-position testing protocols, while ECE Regulation 14 governs frontal impact restraint performance across European type-approval jurisdictions. IATF 16949 quality management certification functions as a de facto market access barrier, excluding non-audited suppliers from direct OEM supply. Stakeholders must monitor the trajectory of chemical-reaction-system regulations in China under SAMR and MIIT oversight, where domestic standard harmonization with UN Global Technical Regulations is accelerating.
Market Dynamics
Multi-chamber inflator architectures are forcing wholesale redesign of pyrotechnic supply chains as battery-electric platforms demand cooler, faster deployment profiles that legacy single-stage systems cannot deliver.
Growth Catalysts
- FMVSS 208 Timing Mandates:NHTSA's tightened deployment windows are compelling OEMs to upgrade from mechanical triggers to sensor-integrated inflator modules, expanding the addressable hardware envelope.
- Electric Vehicle Cabin Redesign:Battery pack placement beneath passenger compartments is creating novel mounting locations for side-curtain and far-side inflators, multiplying unit counts per vehicle platform.
- China Domestic OEM Scaling:BYD, NIO, and XPeng are integrating advanced restraint systems as standard equipment, concentrating demand within domestic supply channels.
Market Restraints
- Nitroguanidine Cost Volatility:The primary gas-generant precursor faces price swings tied to agricultural fertilizer feedstock markets, compressing margin stability for hybrid inflator producers.
- Japanese Chemical Concentration:Proprietary gas-generant formulations remain captive to three specialized chemical houses, creating single-source vulnerability for tier-one module assemblers.
- ECE Regulation 14 Testing Burden:The frontal impact protocol's out-of-position dummy requirements extend development cycles by eight to fourteen months for new inflator variants.
Strategic Opportunities
- India Passenger Safety Mandates:The country's automotive safety regulator is phasing in frontal airbag requirements for all passenger vehicles, opening a greenfield replacement market for inflator suppliers.
- Pre-Crash Sensing Convergence:Integration of radar and camera fusion with inflator firing algorithms enables predictive deployment, commanding premium positioning in European premium segments.
- Direct OEM Channel Expansion:Safety system houses are bypassing tier-one module integrators to supply inflators directly to emerging EV-native manufacturers, capturing margin previously lost to intermediaries.
Industry Challenges
- IATF 16949 Certification Timelines:New entrant suppliers face eighteen-to-twenty-four month audit cycles before qualifying for direct OEM supply, freezing out capital-constrained competitors.
- Legacy Mechanical Trigger Integration:Cost-optimized vehicle programs in Southeast Asia continue specifying mechanical-only activation, forcing parallel product architectures that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag Inflator Market |
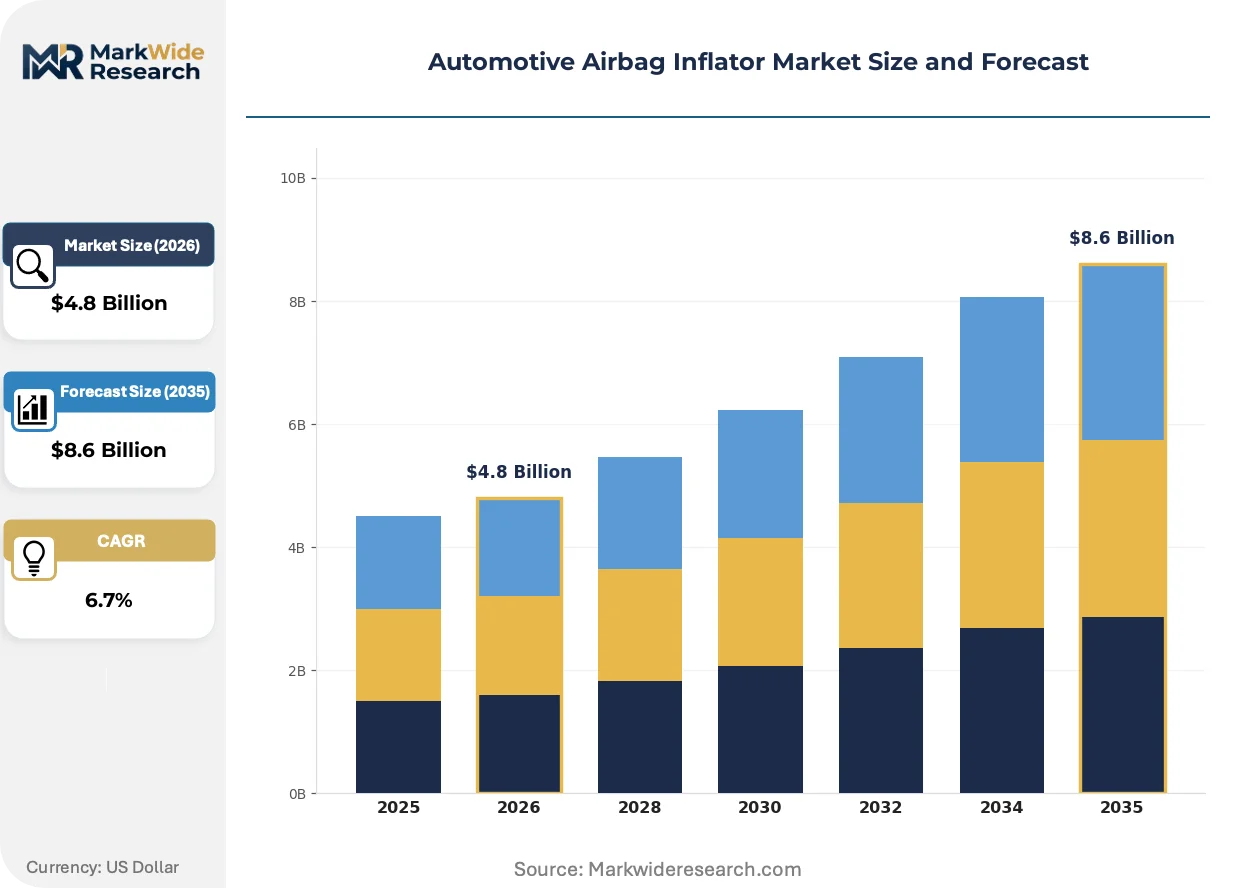
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combo Inflators, Pyrotechnic Inflators, Non-Pyrotechnic Inflators, Hybrid Inflators Technology: Advanced Safety Systems, Sensor-Based Activation, Chemical Reaction Systems, Electronic Trigger Mechanisms End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Certification: ISO 9001, ECE Regulation 14, FMVSS 208, IATF 16949 |
| Companies Covered | Autoliv Inc., Daicel Corporation, ARC Automotive, Inc., Toyoda Gosei Co., Ltd., Joyson Safety Systems, ZF Friedrichshafen AG, Nippon Kayaku Co., Ltd., Key Safety Systems, Inc., Jinzhou Jinheng Automotive Safety System Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag Inflator Market Strategic Shifts
Pyrotechnic chemistry, sensor fusion, and procurement centralization are converging to redefine how inflator systems are specified, validated, and sourced across passenger vehicle programs.
Hybrid inflator technology combining stored argon with reduced gas-generant loads is electrifying deployment thermal management. European premium OEMs are specifying these systems for battery-electric platforms where cabin heat rejection is constrained. The technology is compressing the addressable market for pure pyrotechnic designs while expanding total content value per vehicle.
China's SAMR is accelerating harmonization with UN Global Technical Regulations for chemical reaction systems, forcing domestic suppliers to retool testing protocols. The industrial consequence is a bifurcation between export-qualified and domestic-only producers. Hybrid inflator categories face the steepest compliance burden as stored-gas components fall under pressure vessel regulations.
Fleet procurement centralization among multi-brand automotive groups is consolidating inflator specification authority at the holding-company level. Tier-one safety module suppliers are responding with platform-scale pricing agreements that span multiple OEM nameplates. This pattern is most visible in Germany where Volkswagen Group, BMW, and Mercedes-Benz have each consolidated global restraint system tenders.
Automotive Airbag Inflator Market Segmentation
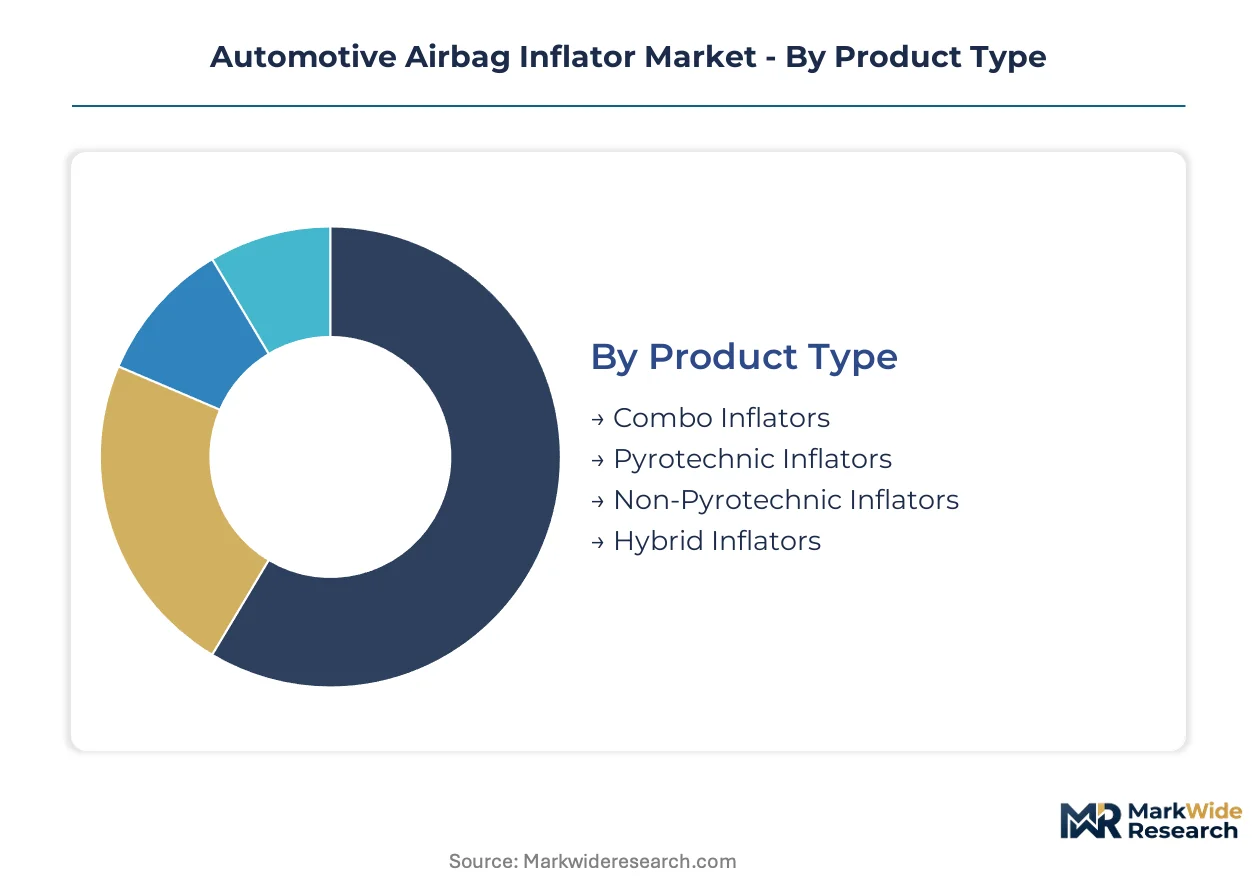
Inflator specification varies sharply by integration depth, from standalone modules for aftermarket replacement to embedded systems co-designed with vehicle domain architectures. Segmentation reveals how chemistry choices, trigger technologies, and certification tiers partition margin pools across the supply chain.
Product Type:
Standalone inflator modules serve replacement channels and legacy retrofits, while embedded systems dominate new vehicle programs where pyrotechnic chemistry must synchronize with crash sensor calibration.
- Combo Inflators:Dual-stage deployment architecture combines frontal and side-impact capability within a single housing, reducing module count per vehicle. Chinese domestic OEMs specify these for mid-platform cost optimization while maintaining ECE Regulation 14 compliance.
- Hybrid Inflators:Stored argon augmentation reduces gas-generant loads and deployment temperatures, critical for battery-electric cabin architectures where thermal management is constrained. European premium automakers mandate these for EV-native platforms.
- Pyrotechnic Inflators:Sodium azide or nitroguanidine-driven single-stage systems persist in cost-optimized vehicle programs across Southeast Asia.
- Non-Pyrotechnic Inflators:Compressed gas-only designs serve specialized commercial vehicle applications with extended service intervals.
Combo inflators lead volumes today; hybrid inflators are gaining share fastest.
Technology:
Cost tier stratification separates mechanical triggers for economy segments from sensor-fused systems commanding premium positioning in electrified platforms.
- Sensor-Based Activation:Radar and accelerometer fusion enables predictive deployment algorithms integrated with central domain controllers. European OEMs specify these for pre-crash sensing convergence.
- Chemical Reaction Systems:Proprietary gas-generant formulations from Japanese chemical houses remain the dominant propulsion method, though nitroguanidine feedstock volatility compresses margins.
- Advanced Safety Systems:Multi-chamber architectures with independent firing zones serve far-side and rear-seat protection in luxury vehicle programs.
- Electronic Trigger Mechanisms:Solid-state firing circuits replace mechanical initiators, reducing part count and improving deployment timing precision.
Chemical reaction systems anchor current production; sensor-based activation shows steepest expansion trajectory.
End User:
Customer type determines specification authority, with direct OEM relationships capturing margin previously absorbed by tier-one integrators.
- Automakers:Volkswagen Group, BMW, and Mercedes-Benz consolidate global restraint tenders at holding-company level, demanding platform-scale pricing agreements.
- Tier-1 Suppliers:Module integrators face margin compression as inflator houses bypass them for direct EV-native manufacturer supply.
- Aftermarket Providers:Replacement demand concentrates in India as frontal airbag mandates phase in across all passenger vehicles.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands specify inflators separately from established safety module suppliers.
Tier-1 suppliers handle majority volume today; direct automaker channels are expanding most quickly.
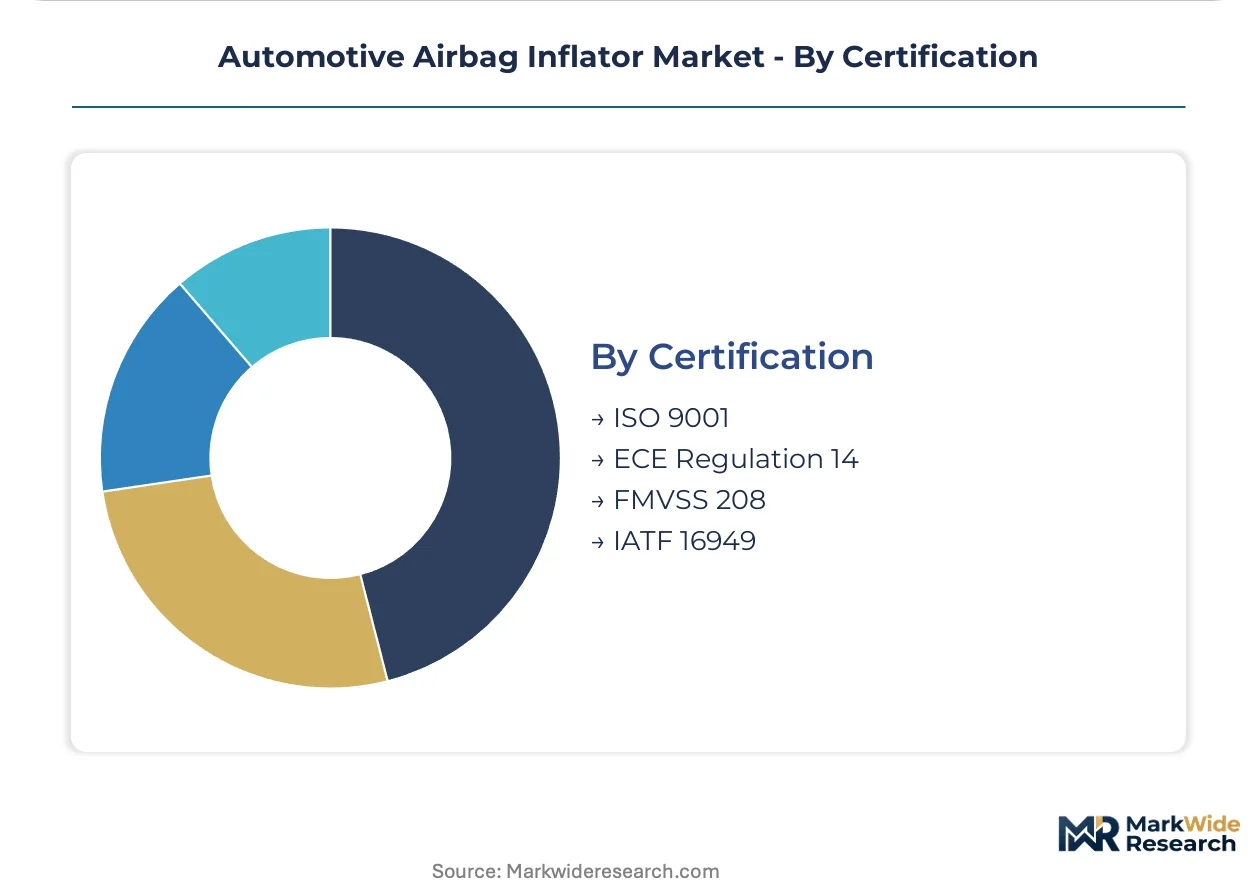
Certification:
Certification tier functions as market access gate, with IATF 16949 excluding non-audited suppliers from direct OEM qualification.
- IATF 16949:Automotive quality management certification requires eighteen-to-twenty-four month audit cycles, freezing out capital-constrained entrants.
- FMVSS 208:NHTSA deployment timing mandates compel upgrade from mechanical to sensor-integrated modules in US-bound production.
- ECE Regulation 14:Out-of-position dummy protocols extend development cycles by eight to fourteen months for new inflator variants.
- ISO 9001:Baseline quality certification serves aftermarket and non-automotive industrial applications with reduced testing burden.
IATF 16949 dominates OEM supply today; harmonization with UN Global Technical Regulations is climbing the fastest in China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate capacity to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between established and emerging regulatory regimes now determine where new inflator assembly capacity anchors.
United States
NHTSA's FMVSS 208 deployment timing mandates are compelling sensor-integrated module upgrades across Detroit Three production lines. The regulation's out-of-position testing protocols extend development cycles for new variants. Manufacturing clusters in Michigan and Ohio concentrate module assembly operations serving North American vehicle programs.
Germany
Volkswagen Group, BMW, and Mercedes-Benz have consolidated global restraint tenders at holding-company level, demanding platform-scale pricing agreements. KBA enforces ECE Regulation 14 type-approval standards that govern frontal impact restraint performance. The Baden-Württemberg industrial corridor hosts specialized chemical processing and inflator component fabrication.
China
BYD, NIO, and XPeng are integrating advanced restraint systems as standard equipment, concentrating demand within domestic supply channels. SAMR and MIIT oversight is accelerating harmonization with UN Global Technical Regulations for chemical reaction systems. The Yangtze River Delta manufacturing belt anchors inflator module assembly for both domestic OEMs and export programs.
Japan
Proprietary gas-generant formulations from specialized chemical houses remain captive to domestic suppliers, creating single-source vulnerability for tier-one module assemblers. METI oversees industrial standards coordination with international regulatory frameworks. The Nagoya industrial corridor concentrates pyrotechnic chemistry research and precision component manufacturing.
India
The country's automotive safety regulator is phasing in frontal airbag requirements for all passenger vehicles, opening a greenfield replacement market for inflator suppliers. BIS certification timelines for automotive components extend qualification periods for new entrants. Manufacturing investments in Maharashtra and Tamil Nadu are scaling assembly capacity to serve domestic OEM demand.
Automotive Airbag Inflator Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers position for EV-native platform awards. The vendor base stratifies between integrated safety system houses, specialized pyrotechnic chemical suppliers, and regional module assemblers. Three archetypes occupy distinct competitive positions: chemistry-anchored specialists controlling gas-generant formulations, scale-driven module integrators serving holding-company tenders, and regionally focused assemblers capturing domestic OEM volume. M&A activity and direct OEM channel expansion represent the dominant competitive vectors as tier-one relationships face disintermediation pressure.
Among chemistry-anchored specialists, Daicel Corporation and Nippon Kayaku Co., Ltd. exemplify the proprietary formulation archetype that underpins hybrid inflator supply. Autoliv Inc. occupies a position representing the integrated safety system house model with pyrotechnic expertise anchoring European premium supply relationships. Joyson Safety Systems sits within the regional scale tier, competing through localized production presence in the Chinese OEM channel.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Daicel Corporation |
| ARC Automotive, Inc. |
| Toyoda Gosei Co., Ltd. |
| Joyson Safety Systems |
| ZF Friedrichshafen AG |
| Nippon Kayaku Co., Ltd. |
| Key Safety Systems, Inc. |
| Jinzhou Jinheng Automotive Safety System Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
UN Global Technical Regulation harmonization under SAMR and MIIT oversight gates qualified supply access and premium-tier pricing power for hybrid inflator producers seeking Chinese OEM qualification. Battery-electric platform thermal constraints further segment pricing tiers, with stored-gas augmentation commanding certification-linked premiums unavailable to pure pyrotechnic suppliers.
Pricing Analysis
Direct-to-OEM channel discounts compress tier-one module integrator margins as Autoliv and Daicel bypass traditional distribution to supply EV-native manufacturers. Pricing stratifies across premium, standard, and economy tiers keyed to IATF 16949 certification status, deployment temperature specifications, and gas-generant chemistry sophistication. Cost compression in the economy tier intensifies because nitroguanidine feedstock volatility transmits directly to contract pricing. Fleet procurement managers at Volkswagen Group and BMW holding-company levels exhibit lowest price sensitivity, while Southeast Asian mechanical-trigger programs retain highest sensitivity.
Supply Chain Analysis
China's domestic-content acceleration under SAMR oversight reshapes sourcing patterns, compelling module assemblers to qualify Yangtze River Delta suppliers for BYD and NIO programs. Proprietary gas-generant formulations draw from Japanese chemical houses concentrated in the Nagoya corridor, with sodium azide and nitroguanidine precursors anchored in agricultural fertilizer feedstock markets. Single-source vulnerability pervades the hybrid inflator segment where stored-argon pressure vessels face extended KBA and NHTSA approval cycles. Distribution runs through tier-one safety module integrators facing disintermediation pressure from direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory mandate stacking, with India's phased frontal airbag requirements opening greenfield replacement demand alongside EV-native platform proliferation.
For Market Incumbents: Anchor IATF 16949 certification investments to defend against emerging Chinese chemical houses seeking direct OEM qualification. Deepen backward integration into nitroguanidine precursor supply to offset agricultural feedstock volatility compressing hybrid inflator margins. Prioritize multi-chamber architecture R&D to capture battery-electric platform awards before module integrators consolidate specification authority. For New Entrants and Emerging Players: Aftermarket distributors in India represent the most penetrable channel partner type for non-audited suppliers blocked from direct OEM qualification by eighteen-to-twenty-four month certification timelines. Target standalone inflator module replacement demand as domestic safety mandates phase in across all passenger vehicles. Pursue white-label supply agreements with established tier-one module integrators lacking hybrid chemistry expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among regional module assemblers with IATF 16949 credentials but limited gas-generant chemistry capabilities, positioning them as acquisition targets for integrated safety houses seeking Chinese OEM channel access. Five-to-ten year viability hinges on EV platform content expansion sustaining per-vehicle inflator counts. Monitor NHTSA FMVSS 208 timing mandate enforcement as the inflection signal for sensor-based activation module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Inflator Capacity Expansion | Stored-argon augmentation meets European premium OEM EV thermal constraints. |
| Direct OEM Channel Development | Bypassing tier-one integrators captures margin from NIO and XPeng procurement. |
| Gas-Generant Backward Integration | In-house nitroguanidine production insulates against fertilizer feedstock volatility. |
| Multi-Chamber Architecture R&D | Far-side and rear-seat protection modules serve luxury vehicle program requirements. |
| India Market Entry Partnership | Localized assembly positions for phased frontal airbag mandate compliance. |
Study Parameters
Multiple input streams — OEM platform engineering disclosures, tier-one supplier procurement data, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with safety module procurement directors, inflator chemistry R&D leads, and aftermarket distribution channel managers were validated against secondary sources including NHTSA FMVSS 208 dockets, ECE Regulation 14 type-approval records, and vehicle production registration databases. SAMR and MIIT regulatory harmonization documents provided Chinese market structure inputs.
Data-stream reconciliation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from production volume trajectories weighted by inflator specification intensity per platform. Chemistry cost curves, certification timeline distributions, and OEM platform lifecycle schedules constituted industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nitroguanidine feedstock volatility, ECE Regulation 14 testing burden extensions, and Chinese domestic OEM consolidation patterns. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and EV platform adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market