
 Europe Automotive Night Vision System Market | 2026-2036
Europe Automotive Night Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Night Vision System Market Foresight
Thermal imaging sensor substrates are decoupling from legacy germanium wafer dependence as silicon-based alternatives reduce unit costs. Robert Bosch GmbH leverages in-house MEMS fabrication to control sensor yield and thermal calibration. Valeo SA anchors its competitive position through integrated camera-software bundles supplied to French and German OEM assembly lines. Continental AG differentiates via multi-sensor fusion architectures that combine thermal and near-infrared inputs.
Automotive night vision systems are active safety assemblies that detect infrared radiation emitted by objects and render thermal or enhanced visual imagery for drivers, typically operating at wavelengths between 8 and 14 micrometers for far-infrared detection and 0.7 to 1.4 micrometers for near-infrared illumination. These systems reduce pedestrian strike incidents in low-visibility conditions and support automated emergency braking decision paths. Thermal imaging leads technology adoption in European premium segments due to superior range performance in fog and darkness, while near-infrared occupies cost-sensitive mid-tier platforms through structured LED illumination. Camera systems dominate product-type revenue pools because OEMs specify integrated lens-sensor-processor modules rather than discrete components.
The EU General Safety Regulation mandates intelligent speed assistance and advanced driver distraction warning systems, creating compliance pathways that night vision suppliers must satisfy for type approval. ECE R79 and ECE R130 standards govern steering equipment and advanced emergency braking, indirectly elevating sensor redundancy requirements for systems operating beyond visible spectrum. REACH compliance constrains material selection for sensor housings and optical coatings across European manufacturing footprints. Stakeholders must monitor how the EU AI Act classifies perception algorithms and whether thermal data processing triggers high-risk system designations affecting product liability and insurance frameworks.
Market Dynamics
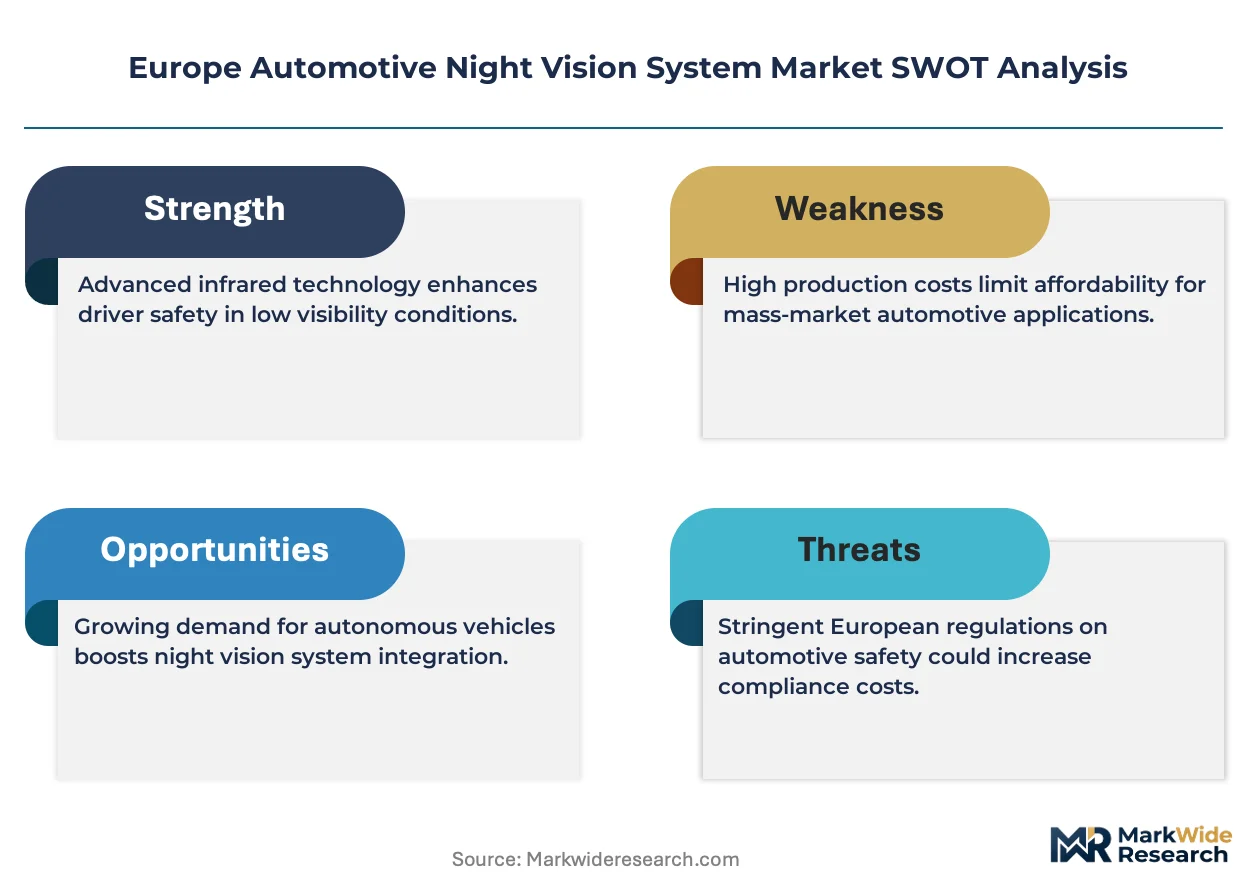
Thermal imaging sensor substrates are decoupling from legacy germanium wafer dependence as silicon-based alternatives reduce unit costs and expand supplier pools. This materials transition is compressing bill-of-materials structures while forcing incumbent optical houses to retool coating lines.
Growth Catalysts
- EU General Safety Regulation:Mandates for intelligent speed assistance and advanced driver distraction warning systems create compliance pathways that night vision suppliers must satisfy for type approval in German and French assembly plants.
- Silicon substrate migration:Foundry-scale CMOS processes enable cost-down trajectories for far-infrared sensor arrays, opening mid-tier sedan segments previously blocked by germanium wafer economics.
- Stuttgart-Munich corridor:Premium OEM clusters in southern Germany specify night vision as standard equipment in flagship lines, generating concentrated demand pull for integrated camera-software bundles.
Market Restraints
- Germanium supply concentration:Optical-grade germanium refining capacity clusters in Chinese and Russian state-controlled entities, exposing European sensor manufacturers to input volatility and export licensing friction.
- REACH compliance burden:Material selection for sensor housings and optical coatings faces constrained substitution options as ECHA restricts candidate substance lists, extending qualification timelines.
- Near-infrared cost floor:Structured LED illumination platforms in mid-tier vehicles cap pricing power for thermal imaging suppliers seeking volume expansion below premium segments.
Strategic Opportunities
- Polish and Czech manufacturing zones:Greenfield sensor packaging and calibration facilities can leverage EU structural funds and proximity to German OEM assembly networks.
- EU AI Act classification pathways:Thermal data processing algorithms that avoid high-risk system designations unlock streamlined product liability frameworks and insurance underwriting.
- Multi-sensor fusion architectures:Integration of thermal and near-infrared inputs with radar returns creates differentiated Tier 1 offerings for automated emergency braking decision stacks.
Industry Challenges
- Thermal calibration expertise scarcity:MEMS fabrication yield optimization requires specialized process engineers concentrated in German and Austrian research institutes, constraining workforce scaling.
- ECE R79 and ECE R130 certification timelines:Steering equipment and advanced emergency braking standards demand extended validation cycles for sensor redundancy configurations.
- Legacy vehicle integration complexity:Retrofit night vision systems face CAN bus architecture mismatches with pre-2020 European vehicle fleets, limiting aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Night Vision System Market |
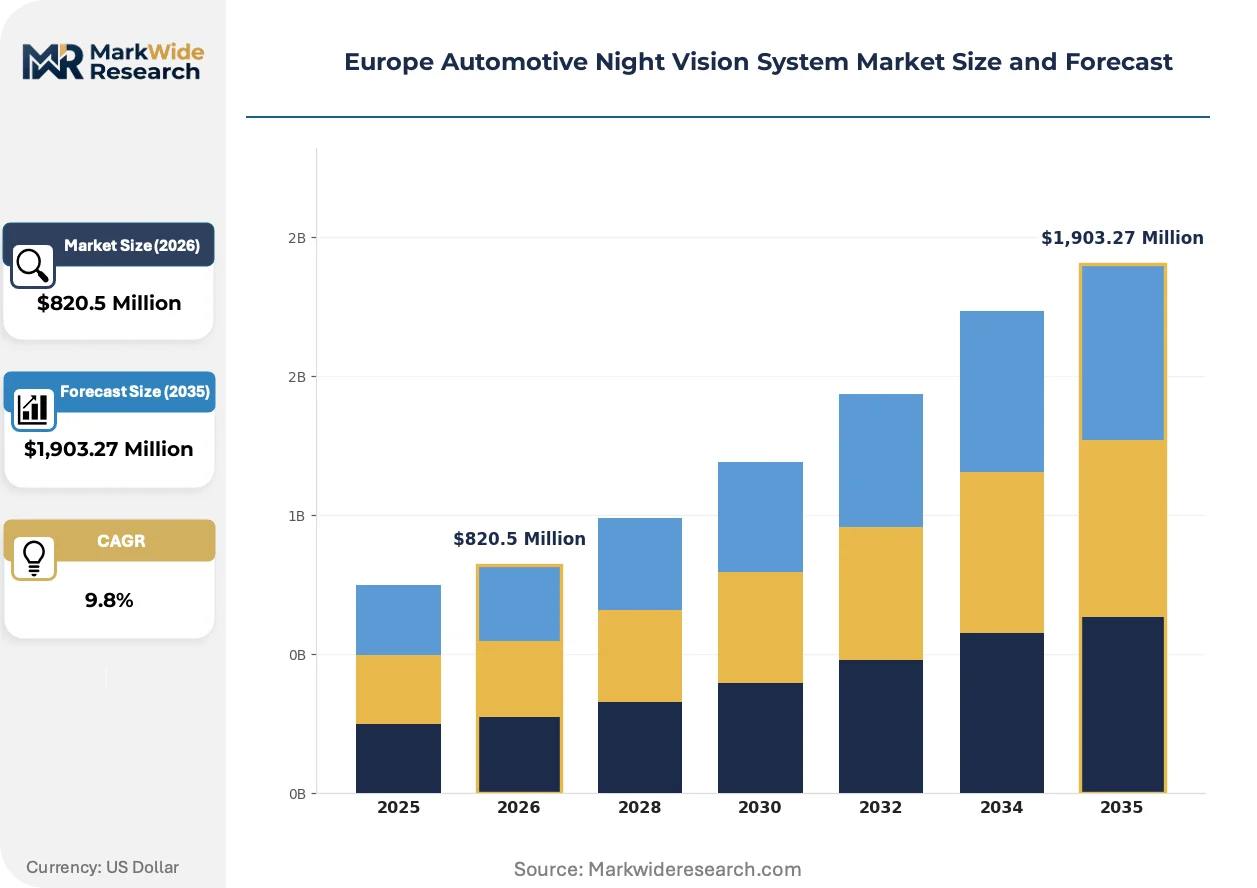
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,903.27 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
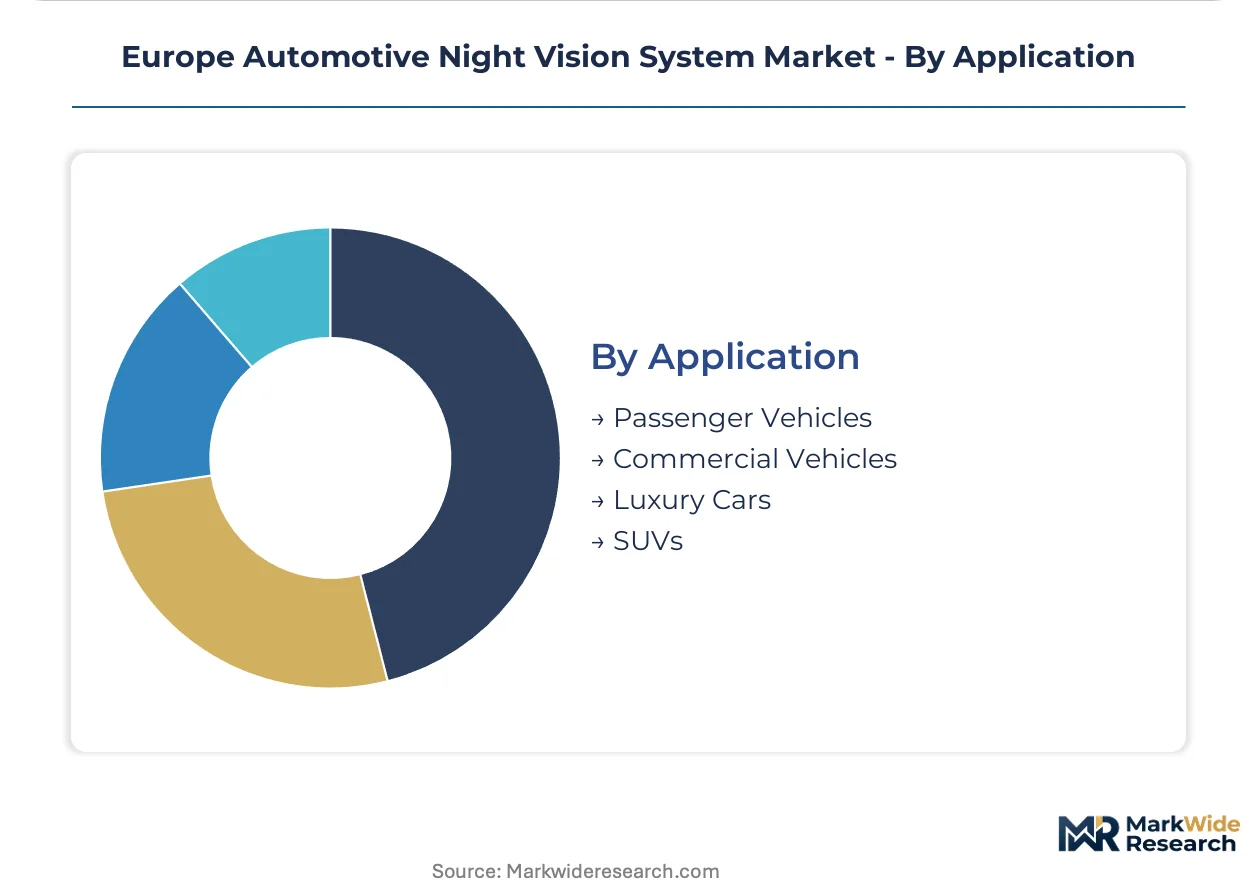
| Segmentation | Technology: Infrared, Near-Infrared, Thermal Imaging, LIDAR Product Type: Camera Systems, Sensor Modules, Display Units, Control Units End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, SUVs |
| Companies Covered | Valeo SA, HELLA GmbH and Co. KG, Robert Bosch GmbH, Teledyne FLIR LLC, ZF Friedrichshafen AG, Continental AG, Denso Corporation, Magna International Inc., Autoliv Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Night Vision System Market Shifts & Advancements
Far-infrared detection architectures are converging with silicon photonics processes, compressing sensor form factors while expanding wavelength sensitivity. This materials-platform shift is redrawing competitive boundaries between optical specialists and semiconductor foundries.
Silicon-based microbolometer arrays are converging with automotive-grade ASIC integration, enabling single-chip thermal sensing solutions. Tier 1 suppliers in Bavaria and Baden-Württemberg are adopting these fused designs for 2027 model-year platforms. The convergence is collapsing the traditional separation between sensor fabrication and signal processing, forcing optical houses to develop foundry partnerships or face margin compression.
REACH substance restrictions are tightening optical coating chemistries, eliminating legacy anti-reflective formulations. ECHA candidate list expansions are accelerating substitution programs among Stuttgart-area lens manufacturers. French and German OEMs are responding with accelerated qualification timelines for fluoropolymer alternatives in far-infrared transmission layers.
Fleet procurement contracts are consolidating night vision specification authority at OEM group level, displacing individual brand-level sourcing decisions. Centralized purchasing desks in Munich and Paris are extracting volume commitments across sedan and SUV portfolios. This concentration is most visible in German premium automotive clusters, where platform-sharing strategies bundle night vision across multiple nameplates.
Europe Automotive Night Vision System Market Segmentation
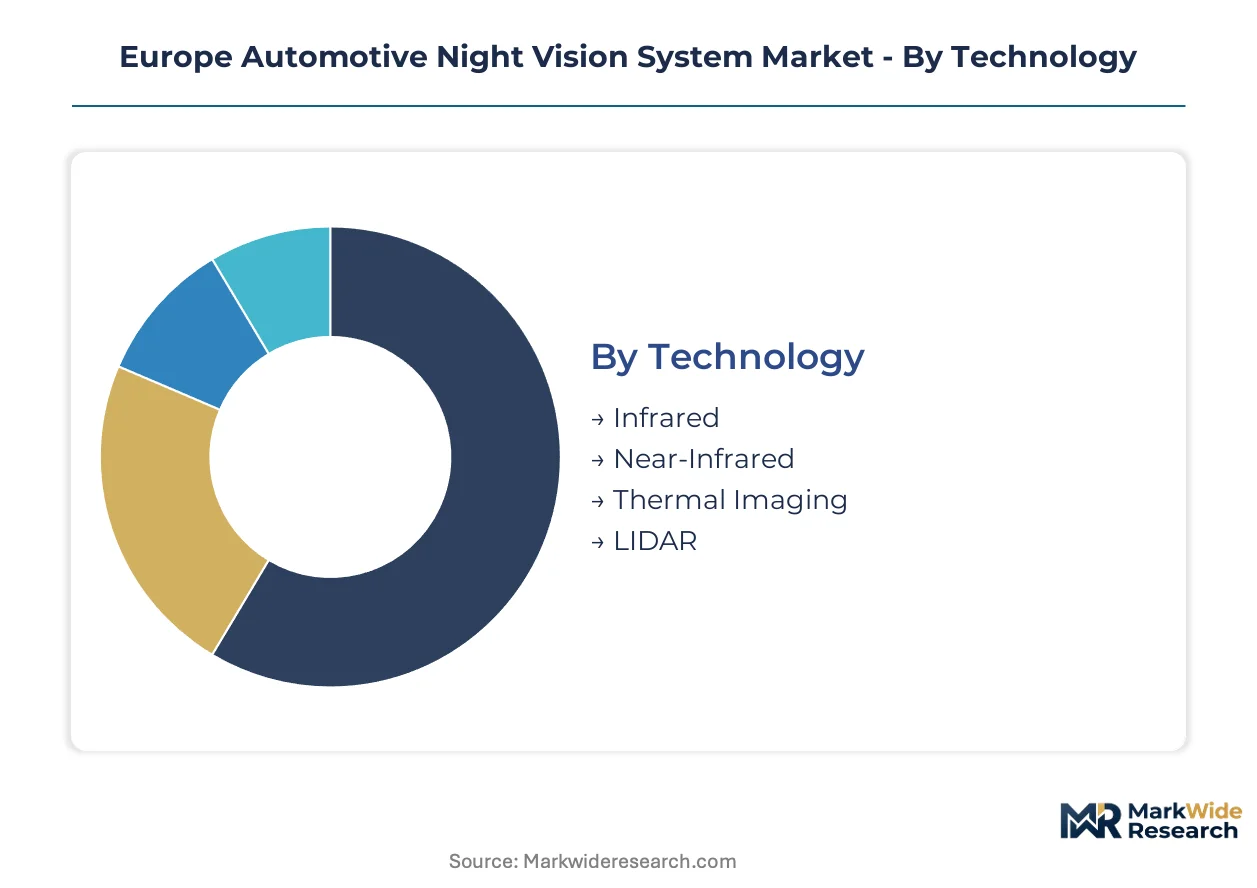
Technology-platform choices determine thermal range performance and unit economics for European night vision procurement. Product architecture decisions by Stuttgart and Munich OEM clusters cascade through supplier tiers, shaping margin structures across sensor and display categories.
Technology:
Premium vehicle buyers prioritize detection range and all-weather reliability over acquisition cost.
- Thermal Imaging:Far-infrared microbolometer arrays detect passive heat signatures at 8-14 micrometer wavelengths without active illumination. German luxury OEMs in Baden-Württemberg specify thermal imaging as standard equipment for flagship sedans, driven by EU General Safety Regulation pedestrian detection mandates and superior fog penetration.
- Near-Infrared:Active LED illumination at 0.7-1.4 micrometers enables structured light pattern recognition at lower bill-of-materials cost. French and German mid-tier platforms adopt near-infrared for cost-sensitive SUV variants, constrained by reduced effective range in precipitation and dependence on unobstructed emitter paths.
- Infrared:Broad-spectrum detection architectures span multiple wavelength bands for redundancy.
- LIDAR:Time-of-flight laser ranging complements thermal detection for three-dimensional object classification.
Volume sits with near-infrared for mid-tier penetration; growth tilts toward thermal imaging as silicon substrate costs decline.
Product Type:
Supplier integration depth determines which component layer captures value in OEM supply agreements.
- Camera Systems:Integrated lens-sensor-processor modules dominate procurement specifications from Munich purchasing desks. Bavarian Tier-1 suppliers bundle thermal cores with automotive-grade ASICs, collapsing traditional boundaries between optical fabrication and signal processing.
- Sensor Modules:Discrete thermal arrays and MEMS packages serve second-source strategies and repair channel demand. Polish packaging facilities near German assembly networks concentrate calibration expertise for far-infrared sensor output standardization.
- Display Units:Head-up and dashboard-integrated screens render thermal overlays for driver consumption.
- Control Units:Processing hardware executes fusion algorithms combining multi-spectral inputs.
Revenue concentrates in camera systems; expansion opportunity clusters in sensor modules as silicon photonics enables new entrant supply.
End User:
Procurement authority centralization at OEM group level is displacing brand-level sourcing autonomy.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz AG specify night vision across platform-shared nameplates through consolidated Munich and Stuttgart purchasing desks. Fleet procurement contracts extract volume commitments spanning sedan and SUV portfolios.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG integrate thermal and near-infrared inputs with radar returns for automated emergency braking decision stacks.
- Aftermarket Providers:Retrofit installation faces CAN bus architecture mismatches with pre-2020 European vehicle fleets.
- Vehicle Assemblers:Contract manufacturing facilities execute factory-fit integration per OEM specifications.
Demand concentrates with OEMs; supplier tier expansion tilts toward Tier-1 fusion architecture providers.
Application:
Vehicle segment positioning dictates performance specifications and price-band targeting.
- Luxury Cars:Mercedes-Benz S-Class and BMW 7-Series platforms specify thermal imaging as standard equipment with pedestrian highlighting and animal detection algorithms. EU Green Deal safety requirements and brand positioning sustain premium pricing for far-infrared systems in this segment.
- SUVs:Porsche Cayenne and Audi Q8 variants balance thermal performance with volume manufacturing economics. Stuttgart-area OEMs bundle night vision across premium SUV nameplates, generating concentrated demand pull for integrated camera-software bundles.
- Passenger Vehicles:Mid-tier sedans adopt near-infrared solutions for cost-controlled active safety compliance.
- Commercial Vehicles:Fleet operators evaluate night vision for accident liability reduction in long-haul trucking.
Specification authority sits with luxury cars; volume expansion tilts toward SUVs as platform-sharing extends thermal imaging down-segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive night vision systems concentrates in German premium automotive clusters, where OEM procurement desks in Stuttgart and Munich drive specification standards across European supply chains. French and Italian manufacturers follow with platform-specific integrations, while Eastern European packaging facilities capture sensor calibration work.
Germany
Mercedes-Benz AG and BMW Group procurement desks in Stuttgart and Munich specify thermal imaging as standard equipment for S-Class and 7-Series flagship lines. KBA type-approval requirements under ECE R79 and ECE R130 mandate extended validation cycles for sensor redundancy configurations. The Baden-Württemberg and Bavaria industrial corridors concentrate MEMS fabrication expertise and Tier-1 supplier headquarters.
France
Renault Group and Stellantis purchasing authorities in Paris consolidate night vision specifications across SUV and sedan portfolios. ANSM and CNIL guidance intersects with EU AI Act implementation for thermal data processing algorithms. The Île-de-France region anchors Valeo SA's integrated camera-software bundle development for domestic OEM assembly networks.
Italy
Stellantis design centers in Turin and Modena specify night vision integration for Maserati and Alfa Romeo performance variants. CE marking requirements under EU General Safety Regulation drive compliance investments for intelligent speed assistance systems. The Emilia-Romagna and Piedmont manufacturing zones concentrate optical coating suppliers serving German and French Tier-1 contractors.
Poland
Greenfield sensor packaging investments near Wrocław and Kraków leverage EU structural funds for calibration facility construction. REACH substance restrictions from ECHA constrain material selection for housings and optical coatings, extending qualification timelines. Polish manufacturing zones supply standardized sensor modules to German OEM assembly plants with 48-hour logistics windows.
United Kingdom
Jaguar Land Rover specification teams in Gaydon and Whitley integrate night vision for Defender and Range Rover luxury SUV lines. Brexit-adjusted type-approval pathways require parallel UKCA marking alongside CE conformity for dual-market vehicle programs. The Midlands automotive cluster hosts calibration service providers supporting German and French Tier-1 supply chains.
Europe Automotive Night Vision System Market Competitive Landscape
Multi-sensor fusion architecture development dominates the current landscape as Tier-1 suppliers differentiate through integrated thermal and near-infrared offerings. The vendor base structures around three tiers: diversified automotive electronics conglomerates with captive MEMS fabrication, specialized thermal imaging houses dependent on external foundry partnerships, and optical component suppliers facing margin compression from silicon substrate migration. Two competitive vectors define positioning: backward integration into sensor fabrication to control yield and thermal calibration, and forward integration into software bundles that lock OEM specification authority.
Among French and German diversified suppliers, Valeo SA and Robert Bosch GmbH exemplify the fusion-architecture tier, occupying positions that span camera hardware through algorithm integration. Continental AG anchors the multi-sensor convergence segment, representing suppliers that combine spectral inputs with radar returns for automated emergency braking stacks. These three GmbH and SA structures illustrate how European automotive electronics conglomerates leverage geographic proximity to Stuttgart-Munich OEM clusters for specification influence.
| Leading Market Players |
|---|
| Valeo SA |
| HELLA GmbH and Co. KG |
| Robert Bosch GmbH |
| Teledyne FLIR LLC |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| Magna International Inc. |
| Autoliv Inc. |
| Others |
Supply & Pricing Matrix
Silicon-based microbolometer migration is collapsing sensor fabrication costs while redistributing supply power from optical specialists to semiconductor foundries across Europe. This substrate transition simultaneously compresses bill-of-materials structures and concentrates procurement leverage among Bavarian and Baden-Württemberg OEM clusters that specify integrated camera-software bundles.
Pricing Analysis
Volume sits with near-infrared LED platforms for mid-tier SUVs where French and German OEMs prioritize cost-controlled active safety compliance; margins concentrate in thermal imaging for Stuttgart-specified flagship sedans where EU General Safety Regulation pedestrian detection mandates sustain premium positioning. Price differentiation hinges on ECE R79 certification tier and thermal calibration precision grade. Pricing pressure stems from silicon photonics foundries entering far-infrared sensor supply, eroding legacy germanium-based optical house margins. Tier-1 suppliers face acute price sensitivity in fleet procurement contracts where Munich purchasing desks extract volume commitments across platform-shared nameplates.
Supply Chain Analysis
ECE R130 certification timelines and REACH substance restrictions gate qualified supplier participation, extending sensor module qualification cycles for Polish packaging facilities near Wrocław and Kraków. Optical-grade germanium refining draws from Chinese and Russian state-controlled entities, exposing European manufacturers to export licensing friction. Raw material dependencies center on silicon wafers, MEMS fabrication equipment, and fluoropolymer optical coatings. Single-source vulnerability concentrates in thermal calibration expertise anchored at German and Austrian research institutes. Distribution runs through consolidated OEM purchasing desks in Stuttgart and Munich that bundle night vision specifications across sedan and SUV portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's automotive night vision sector is traversing a technology-transition phase where silicon-based microbolometer arrays displace legacy germanium-dependent thermal sensors, reshaping competitive boundaries between optical specialists and semiconductor foundries.
For Market Incumbents: Anchor defensive positioning through captive MEMS fabrication investments in Bavaria and Baden-Württemberg to control thermal calibration yield against silicon photonics foundry encroachment. Deepen backward integration into sensor packaging via Polish greenfield facilities leveraging EU structural funds, while accelerating REACH-compliant fluoropolymer coating qualifications to preempt ECHA candidate list restrictions. Certification investment in ECE R79 and ECE R130 redundancy configurations protects specification authority against emerging multi-sensor fusion competitors. For New Entrants and Emerging Players: Tier-1 supplier engineering partnerships offer the most penetrable channel for silicon photonics specialists lacking automotive qualification track records. Target aftermarket retrofit segments where CAN bus architecture complexity limits incumbent dominance, particularly for pre-2020 European fleet upgrades. White-space exists in sensor module second-source strategies for Munich and Stuttgart OEM clusters seeking supply diversification beyond Robert Bosch GmbH and Continental AG captive production. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified automotive electronics conglomerates pursuing multi-sensor fusion capabilities. Long-term viability favors targets with silicon-based thermal array IP and established ECE certification histories over germanium-dependent optical houses facing materials obsolescence. The signal to watch is EU AI Act classification rulings on thermal data processing algorithms, which could trigger high-risk system designations affecting product liability frameworks and insurance underwriting structures.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Enables cost-down trajectories for far-infrared microbolometers targeting mid-tier sedan segments. |
| REACH-Compliant Coating Qualification | Secures ECHA-aligned material substitution for Stuttgart-area lens manufacturers facing substance restrictions. |
| Multi-Sensor Fusion Architecture Development | Integrates thermal and near-infrared inputs with radar for automated emergency braking decision stacks. |
| Polish Calibration Facility Expansion | Leverages EU structural funds to supply standardized sensor modules within 48-hour German OEM logistics windows. |
| EU AI Act Compliance Pathway Investment | Avoids high-risk system classification for thermal data processing algorithms affecting liability frameworks. |
Research Methodology
Document review covered ECE R79 and ECE R130 regulatory filings, REACH substance restriction updates from ECHA, and vehicle production databases from IHS Markit, complemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers in Stuttgart and Munich, aftermarket distributors, and thermal calibration specialists at German research institutes. Secondary validation drew from KBA type-approval records, EU General Safety Regulation implementation guidance, and customs data on germanium and silicon wafer trade flows. Bottom-up sensor shipment estimates triangulated against top-down OEM platform content analysis.
Segment-level projections across thermal imaging, near-infrared, and broad-spectrum architectures were generated through technology adoption curves weighted by EU Green Deal safety mandate timelines and silicon substrate cost-down trajectories. Vehicle class segmentation modeled luxury sedan, premium SUV, mid-tier passenger vehicle, and commercial fleet demand pools. CAGRs were derived from regression analysis of historical premium safety feature penetration rates and OEM platform-sharing strategies. Key forecast inputs included MEMS fabrication capacity expansion announcements and ECHA candidate list revision schedules affecting optical coating chemistry.
Caveats apply where EU AI Act classification rulings, germanium export licensing disruptions, or REACH substance restriction accelerations could materially shift the outlook for thermal imaging sensor economics. Forecasts reflect assumptions on silicon photonics yield maturation and OEM procurement desk consolidation trajectories. A model refresh is warranted upon material change in ECE certification timelines or ECHA regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Biometric in the Automotive Market