
 Automotive Rear View Mirror Market | 2026-2036
Automotive Rear View Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear View Mirror Market Intelligence
The rise of asset-light manufacturing models, which rely on outsourced component fabrication, is tilting the competitive balance away from purely vertically integrated incumbents. Gentex Corporation leads in electrochromic technology and smart mirror features. Magna International Inc. leverages its scale and broad automotive systems portfolio to secure large OEM contracts. Ficosa International SA specializes in advanced vision systems, including integrated cameras and communication modules.
Automotive rear view mirrors are safety devices that provide drivers with visibility of the area behind their vehicle. These systems often incorporate precisely curved glass with a reflective silvering or aluminum coating to expand the field of view. Electrochromic technology continues to dominate the premium passenger car segment, offering automatic dimming capabilities. The proliferation of camera-based systems, supplied directly to OEMs, represents the fastest-growing technology category, fundamentally altering product design and functionality.
Product specifications are governed by safety mandates from regulators like the US National Highway Traffic Safety Administration (NHTSA) and conform to European vehicle type-approval standards. In China, the Ministry of Industry and Information Technology (MIIT) influences standards, particularly for camera-based systems in new energy vehicles. Supplier decisions will hinge on balancing investment in legacy electrochromic mirrors against the capital required for developing next-generation camera monitor systems.
Market Dynamics
The fundamental dynamic shaping the automotive rear view mirror market is the technological transition from analog glass components to digital vision systems. This shift is driven by the rapid adoption of electric vehicles and intensifying safety mandates from global regulators.
Growth Catalysts
- Safety Mandates:Regulations like the US NHTSA's rear visibility rule and European type-approval standards for field of view compel the adoption of advanced mirror systems.
- Electric Vehicle Integration:Advanced mirror systems, including camera-based options, are increasingly standard features in new electric vehicles to improve aerodynamics and integrate with driver-assist platforms.
- Government Support in China:Policies from China's MIIT promoting new energy vehicles (NEVs) accelerate demand for camera monitor systems, which are integral to modern EV design.
Market Restraints
- High Retooling Costs:Significant capital investment is required for manufacturers to transition production lines from traditional glass mirror fabrication to complex camera-monitor system assembly and testing.
- System Latency and Reliability:Performance issues with camera systems, such as image latency, glare in direct sunlight, and obstruction by weather, can slow OEM adoption and regulatory approval.
- Regulatory Lag:In certain jurisdictions, regulations have not yet fully permitted the complete removal of traditional physical mirrors, forcing a costly dual-system approach for OEMs.
Strategic Opportunities
- ADAS and V2X Integration:Opportunities exist in combining mirror systems with ADAS sensors and vehicle-to-everything (V2X) communication modules to create a centralized situational awareness hub.
- Commercial Vehicle Segment:The commercial truck and bus segment remains an underpenetrated market for advanced camera systems that can drastically reduce blind spots and improve operational safety.
- Aftermarket Upgrade Solutions:Developing smart mirror kits for the aftermarket allows suppliers to capture value from the vast existing vehicle parc not originally equipped with advanced vision systems.
Industry Challenges
- Software Integration Complexity:A key challenge is ensuring seamless software integration of camera feeds with multiple in-vehicle displays and the central electronic control unit without creating system conflicts.
- Semiconductor Supply Chain:Dependence on a specialized supply chain for high-resolution image sensors and processors creates vulnerability to shortages and price volatility, impacting production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear View Mirror Market |
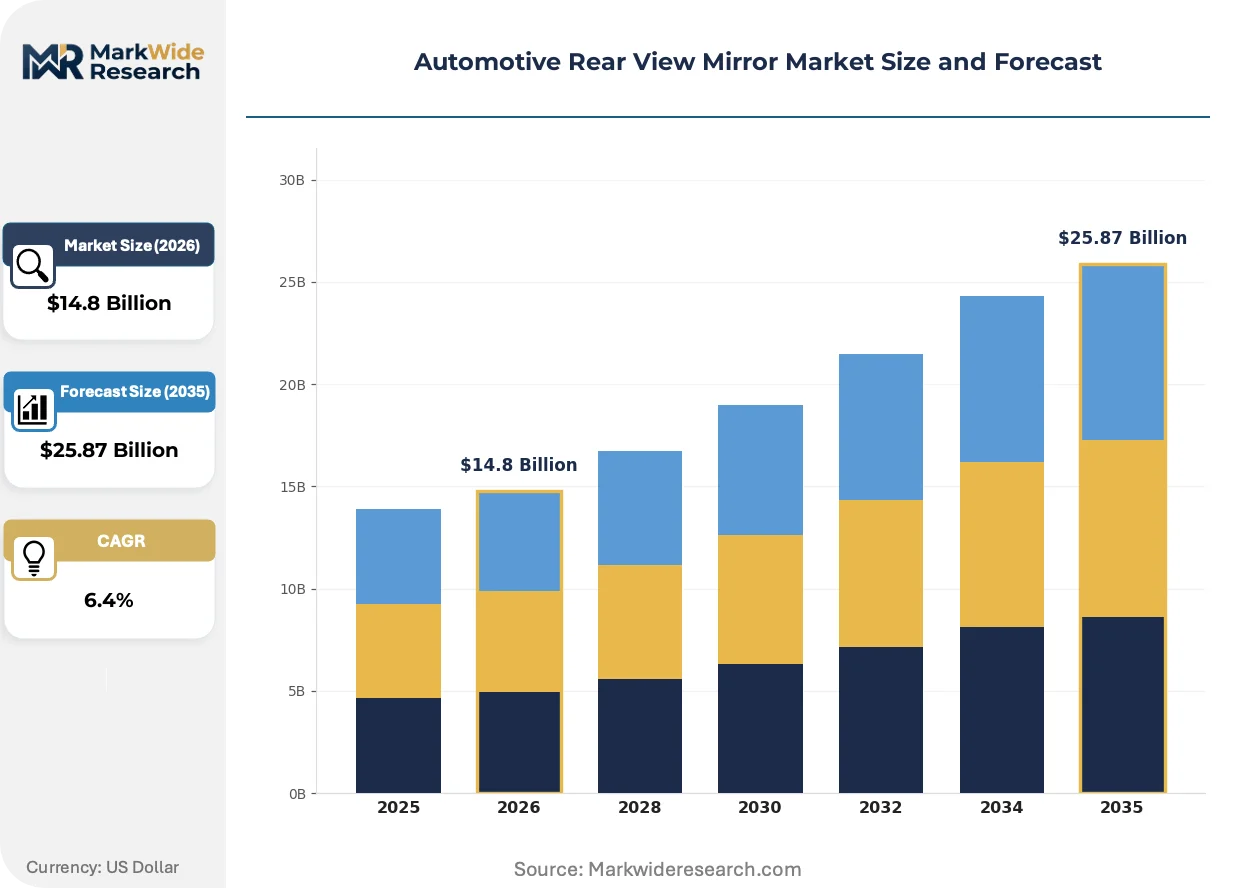
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Mirrors, Automatic Dimming, Heated Mirrors, Power Adjustable Mirrors, Wide-Angle Mirrors Technology: Electrochromic, Ultrasonic, Camera-based, LED Indicator, Anti-glare Vehicle Application: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Electric Vehicles, Two-Wheelers Distribution Channel: OEMs, Aftermarket Dealers, Online Retailers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Continental AG, Ficosa International SA, Gentex Corporation, Samvardhana Motherson Reflectec, SL Corporation, Magna International Inc., Valeo SA, Burco Inc., Murakami Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear View Mirror Market Strategic Shifts & Innovations
Digitalization is transforming the rear view mirror from a passive safety device into an active, data-rich node within the vehicle's electronic architecture. This evolution is driven by advancements in sensor technology and software-defined vehicle platforms.
Camera-monitor systems (CMS) employ digital displays to provide a live video feed from exterior-mounted cameras, offering an expanded field of view. The premium passenger car segment and the broader electric vehicle market are adopting this technology at a rapid pace. This technology is hybridizing the mirror by merging traditional reflective surfaces with on-demand digital displays, creating multifunctional smart mirrors.
New European vehicle type-approval standards and proposals from the US NHTSA are beginning to permit the complete replacement of side-view mirrors with camera-based systems. This regulatory evolution reduces design constraints related to aerodynamics, directly impacting EV range and fuel efficiency. The heavy-duty truck segment is most affected, as manufacturers can now design vehicles with significantly reduced blind spots and improved drag coefficients.
Automotive OEMs are moving away from procuring mirrors as standalone components and toward sourcing integrated vision systems from a single, capable supplier. This shift disfavors smaller specialists and benefits large Tier 1s with deep software integration expertise. This pattern is most visible in China, where new energy vehicle manufacturers prioritize development speed and seek turnkey solutions that bundle cameras, displays, and control software.
Automotive Rear View Mirror Market Segmentation
Understanding the varied requirements across vehicle types and technological preferences is essential for suppliers in the automotive rear view mirror market. This segmentation analysis dissects the market into its core components, highlighting the distinct dynamics influencing demand and technological adoption within each category.
Product Type:
The use-case spectrum for rear view mirrors ranges from fundamental visibility to integrated safety and convenience features, addressing diverse driver needs and regulatory mandates.
- Automatic Dimming:These mirrors utilize electrochromic technology to automatically reduce glare from headlights of following vehicles, enhancing driver comfort and safety, with strong demand in premium passenger car segments.
- Power Adjustable Mirrors:These systems allow electronic adjustment of mirror angles from inside the vehicle cabin, a standard feature across most modern passenger cars and light commercial vehicles, driven by convenience expectations.
- Manual Mirrors:These basic mirrors require physical adjustment by hand, primarily found in entry-level vehicle models and certain commercial applications where cost efficiency is a primary concern.
- Heated Mirrors:Integrated heating elements prevent fogging and ice buildup on the mirror surface, providing clear visibility in cold climates, particularly common in European and North American markets.
- Wide-Angle Mirrors:Designed with a greater curvature, these mirrors expand the field of view to reduce blind spots, often mandated for commercial vehicles and increasingly adopted in passenger cars for enhanced safety.
Established volume favors Manual Mirrors; emerging adoption favors Automatic Dimming.
Technology:
Functional integration defines the technological landscape, with systems evolving from passive reflective surfaces to active digital vision solutions.
- Electrochromic:This technology employs an electrically dimmable medium that darkens automatically to prevent glare, widely adopted in the premium passenger car segment for its proven effectiveness and high reliability.
- Camera-based:These systems replace traditional glass mirrors with digital cameras and in-cabin displays, offering an expanded field of view and improved aerodynamics, representing the fastest-growing technology category due to EV integration.
- Ultrasonic:Primarily used for blind spot detection, ultrasonic sensors complement mirror systems by alerting drivers to obstacles in adjacent lanes, increasing overall vehicle safety.
- LED Indicator:Light-emitting diodes integrated into mirror housings provide turn signal indications or blind spot warnings, enhancing vehicle visibility to other road users and improving safety.
- Anti-glare:Passive anti-glare coatings or designs reduce reflected light, providing a basic level of glare protection in more cost-sensitive applications compared to active electrochromic solutions.
The market share for electrochromic technology remains substantial, while camera-based systems gain share rapidly across new vehicle platforms.
Vehicle Application:
Market penetration varies significantly across different vehicle types, driven by specific safety requirements, design constraints, and consumer expectations.
- Passenger Cars:This segment represents the largest volume market for rear view mirrors, incorporating a wide range of technologies from basic manual mirrors to advanced electrochromic and camera-based systems.
- Electric Vehicles:Advanced mirror systems, particularly camera-based solutions, are increasingly standard in EVs to improve aerodynamics and optimize range, driving significant demand in this rapidly expanding segment.
- Light Commercial Vehicles:These vehicles often prioritize durability and functional utility, incorporating robust mirror designs with features like heating and wide-angle views to support varied operational demands.
- Heavy Trucks:The heavy-duty truck segment increasingly adopts camera monitor systems to eliminate large blind spots and improve operational safety, driven by stringent regulatory requirements and fleet efficiency goals.
- Two-Wheelers:Mirrors for motorcycles and scooters focus on compact design and vibration resistance, providing essential rearward visibility for rider safety, often with basic manual adjustment.
Safety mandates strongly influence adoption in heavy trucks, while consumer preferences and range optimization drive innovation in electric vehicles.
Distribution Channel:
Supply chain concentration dictates how rear view mirror systems reach vehicle manufacturers and end-users, reflecting varying levels of integration and aftermarket opportunities.
- OEMs:Original Equipment Manufacturers represent the primary channel, with mirror suppliers delivering integrated systems directly to vehicle assembly lines for new vehicle production.
- Tier-1 Suppliers:These large automotive component manufacturers often integrate mirror systems into broader vehicle modules before supplying them to OEMs, leveraging extensive engineering and logistics capabilities.
- Aftermarket Dealers:This channel caters to replacement parts and upgrades for existing vehicles, offering a range of standard and enhanced mirror options to consumers and repair shops.
- Online Retailers:E-commerce platforms provide a convenient channel for consumers and small businesses to purchase replacement mirrors and upgrade kits, expanding access to a broader product selection.
- Vehicle Assemblers:Companies specializing in vehicle assembly, often for niche markets or custom builds, procure mirror components directly or through Tier-1 suppliers to meet specific design and regulatory needs.
Direct supply to OEMs commands the highest volume, while Tier-1 suppliers offer integrated solutions across the value chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive rear view mirror market exhibits varied regional demand and supply dynamics, with certain regions demonstrating a net export position for advanced systems while others rely on imports. This balance is shifting as local manufacturing capabilities for digital vision systems mature across key automotive hubs. Regulatory frameworks and consumer preferences significantly shape technology adoption rates in different geographies.
China
China's market demand for advanced rear view mirrors is propelled by extensive new energy vehicle production and strong domestic sales. The Ministry of Industry and Information Technology (MIIT) promotes camera monitor systems as integral to modern EV design. Manufacturing clusters in the Yangtze River Delta drive innovation in integrated vision solutions for OEMs.
United States
United States demand is driven by stringent safety mandates and consumer preference for advanced driver-assistance features. The US National Highway Traffic Administration (NHTSA) regulations compel sophisticated mirror technology integration. Automotive manufacturing centers in Michigan, like Detroit, focus on research into next-generation mirror systems and ADAS integration.
Germany
Germany represents a significant segment for premium automotive rear view mirrors, characterized by high demand for electrochromic and digital systems. European vehicle type-approval standards ensure consistent quality benchmarks for mirror components. The automotive industry in Bavaria, centered around Munich, spearheads integrated smart mirror functionalities for luxury and performance vehicles.
Japan
Japanese automotive manufacturers drive demand for compact, high-reliability rear view mirror systems, often integrating advanced sensor technologies. The Ministry of Economy, Trade and Industry (METI) supports research into lightweight and energy-efficient components. Major automotive production hubs in the Kanto region focus on refining camera-based systems for domestic and export markets.
India
India's market for rear view mirrors is expanding rapidly, fueled by increasing vehicle production and evolving safety regulations for commercial and passenger vehicles. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for automotive components. The automotive belt around Chennai and Pune witnesses increased investment in production capabilities for advanced mirror systems.
Automotive Rear View Mirror Market Key Industry Players
On the supply side, the industry is transitioning from a traditional component supply chain to one dominated by integrated vision system providers. This shift creates a tiered structure, with large Tier 1 suppliers leveraging economies of scale and software integration capabilities. Strategic archetypes include established electrochromic specialists, diversified automotive system integrators, and advanced vision system innovators. Dominant competitive moves involve strategic partnerships with OEMs for early technology integration and significant investment in R&D for next-generation camera monitor systems.
Among established automotive suppliers, Gentex Corporation exemplifies leadership in electrochromic technology and smart mirror features, catering predominantly to the premium passenger car segment. Magna International Inc., a diversified automotive systems provider, leverages its extensive scale and broad portfolio to secure large OEM contracts for integrated solutions. Ficosa International SA, with its focus on advanced vision systems, occupies a position as a specialist in camera-based systems, including integrated cameras and communication modules, particularly for next-generation vehicle platforms.
| Leading Market Players |
|---|
| Continental AG |
| Ficosa International SA |
| Gentex Corporation |
| Samvardhana Motherson Reflectec |
| SL Corporation |
| Magna International Inc. |
| Valeo SA |
| Burco Inc. |
| Murakami Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for automotive component delivery, influence pricing dynamics by adding significant logistical costs, which then get factored into long-term supply contracts and affect downstream price differentiation for advanced mirror systems.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements, ensuring stable supply and predictable costs for integrated mirror systems. Price differentiation stems from the quality grade, particularly stringent safety certifications required for advanced vision systems, and the volume scale of OEM orders. Pricing pressure intensifies due to the high retooling costs associated with transitioning to camera-based systems and OEM demands for cost-effective integration. Aftermarket buyers exhibit higher price sensitivity compared to vehicle manufacturers who prioritize reliability and seamless integration.
Supply Chain Analysis
Specialized technology export controls increasingly limit the free flow of high-resolution image sensors and advanced processors, impacting the global automotive mirror supply chain. Supply concentration for critical components rests primarily in China, Germany, and Japan, which are major manufacturing hubs. Raw material dependencies include specialized glass, electrochromic chemicals, and semiconductors for digital systems. The semiconductor supply chain creates a structural risk due to its vulnerability to shortages and price volatility. Distribution runs through a dual model, with direct supply to OEMs dominating and Tier-1 suppliers integrating broader modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers fragmentation opportunities as the shift towards electric vehicles and advanced driver-assistance systems creates distinct niches for specialized vision solutions.
For Market Incumbents: Entrench existing OEM relationships by investing heavily in next-generation camera monitor systems and software integration capabilities. Secure long-term contracts for hybrid mirror solutions, mitigating the threat from specialized vision system innovators. Deepen vertical integration into critical software development to control intellectual property and reduce reliance on third-party solutions.
For New Entrants and Emerging Players: Build out targeted solutions for underpenetrated segments, such as the commercial vehicle market where advanced camera systems drastically reduce blind spots. Focus on modular, cost-effective camera-only solutions tailored for specific regional safety mandates. A go-to-market angle could involve offering integrated ADAS functionalities as a bundled package for fleet operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from large diversified automotive system integrators seeking to divest non-core traditional mirror assets. Long-term viability favors specialists in vision processing software and high-resolution sensor technology. Acquire firms with proven expertise in AI-driven image analysis for enhanced situational awareness. The signal to watch for inflection is widespread regulatory approval for complete mirror replacement across major automotive markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enhances mirror system integration with central vehicle architectures for advanced functionality. |
| Platform Standardization for CMS | Reduces development costs and accelerates adoption of camera monitor systems across vehicle lines. |
| Geographic Manufacturing Footprint Expansion | Mitigates supply chain risks and supports regional OEM production requirements in key markets. |
| Long-term OEM Supply Agreements | Secures stable revenue streams and provides capital for R&D in next-generation technologies. |
| Acquisition of Vision Software Specialists | Strengthens in-house capabilities for AI-driven image processing and sensor fusion. |
Research Approach
Initial hypotheses were tested against primary input from OEM procurement managers, Tier 1 R&D leads, automotive safety regulators, and aftermarket distributors, then refined through iterative validation. This process combined in-depth primary interviews with extensive secondary data analysis, drawing from NHTSA safety reports, MIIT policy documents, automotive industry association publications, and company financial filings. Bottom-up market sizing and top-down validation ensured comprehensive data triangulation.
The analytical framework balanced demand-supply dynamics to project market evolution across the analysis window. Segmentation dimensions modeled included vehicle class, propulsion architecture, technology type, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected technological shifts, with key industry-specific forecast inputs including vehicle production forecasts and regulatory mandate schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized vision system innovators or large tech companies would shift outcomes. Forecasts reflect assumptions regarding technological maturation and regulatory pathways. Material shifts in EV adoption rates or unforeseen semiconductor supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market