
 Autonomous Warehouse Charging Infrastructure Market | 2026-2036
Autonomous Warehouse Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Warehouse Charging Infrastructure Market Insights
The convergence of wireless power transfer and fleet management software is narrowing the gap between opportunistic charging and continuous robot uptime. WiBotic leverages its specialization in autonomous wireless charging for mobile robots across warehousing environments. Wiferion anchors its position through in-house production of inductive charging coils optimized for industrial automation cycles. KUKA competes by extending its robotic systems portfolio with integrated conductive charging modules for automated guided vehicles.
Autonomous warehouse charging infrastructure encompasses hardware and software systems that replenish energy stores for mobile robots and automated material handling equipment without human intervention, typically operating at power levels from kilowatt-scale conductive pads to high-frequency resonant inductive coils rated for continuous industrial duty cycles. These installations serve the primary commercial purpose of eliminating manual battery swaps and scheduled downtime in high-throughput logistics operations. Inductive and conductive charging technologies dominate current deployment volumes, with inductive systems capturing premium margin pools in cleanroom and cold storage applications where connector corrosion poses operational risk. Fleet charging and order fulfillment applications are outpacing inventory management in growth velocity as multi-robot orchestration platforms mature.
OSHA electrical safety standards, FCC Part 18 rules governing industrial radio-frequency equipment, and EU CE marking requirements under the Low Voltage Directive collectively shape product certification pathways and market access conditions for charging infrastructure vendors. The EPA's ENERGY STAR specifications for industrial equipment and emerging state-level building codes in California and New York are tightening efficiency benchmarks for fixed charging station deployments. Stakeholders must weigh the trade-off between standardizing on conductive architectures today versus investing in wireless systems that promise greater layout flexibility as warehouse automation densities climb.
Market Dynamics
The collision between warehouse automation density targets and power delivery constraints is forcing infrastructure architects to abandon fixed charging stations in favor of mobile, opportunity-based replenishment architectures that track robot fleets in real time.
Growth Catalysts
- F-Gas Regulation:The EU's phase-down of hydrofluorocarbon cooling in cold storage logistics accelerates adoption of sealed inductive charging systems that eliminate connector corrosion risks in sub-zero environments.
- E-commerce fulfillment:Same-day delivery guarantees from Amazon, JD.com, and Zalando require 22-hour robot uptime that only continuous wireless charging corridors can sustain.
- Conductive pad miniaturization:Advances in gallium nitride power electronics enable kilowatt-scale contact charging in footprints under 15 centimeters, unlocking retrofit deployment in legacy facilities.
Market Restraints
- Copper and rare earth magnet costs:Inductive coil assemblies depend on neodymium-iron-boron magnets and high-purity copper windings subject to price volatility from Chinese export quotas.
- RF interference thresholds:FCC Part 18 field strength limits constrain resonant frequency selection, capping power transfer efficiency in high-density robot deployments.
- Conductive connector durability:Mechanical contact pads in automated guided vehicles face mean-time-between-failure compression under continuous duty cycles exceeding 20,000 annual mating events.
Strategic Opportunities
- India warehousing:PLI scheme subsidies for electronics manufacturing and the absence of legacy automation create first-mover positioning for wireless charging-native facility designs.
- Pharmaceutical cold chain:EU GDP guidelines for temperature-controlled logistics mandate sealed power interfaces, opening premium deployment of resonant inductive systems in vaccine distribution hubs.
- 5G private networks:Integration of ultra-reliable low-latency communication with charging management software enables millisecond-precision robot-to-station handoff coordination.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdiction testing for CE marking, FCC Part 18, and China's SRRC approval extends product launch timelines by 8-14 months.
- Retrofit integration complexity:Legacy warehouse management systems from the 2010s lack API endpoints for real-time state-of-charge telemetry, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Warehouse Charging Infrastructure Market |
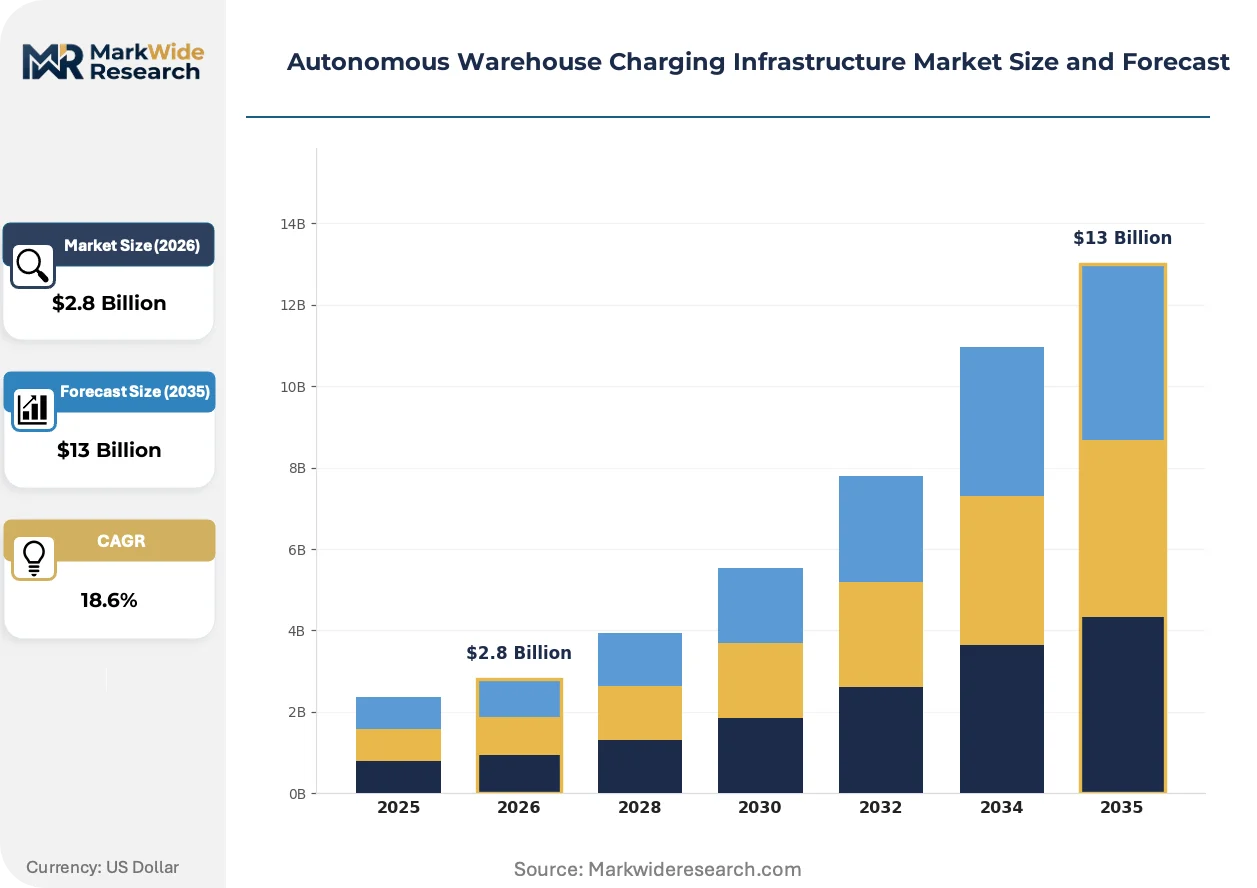
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: Inductive, Conductive, Battery Swap, Solar-Powered, Wireless Application: Inventory Management, Automated Sorting, Material Handling, Fleet Charging, Order Fulfillment End User: E-commerce Fulfillment Centers, Third-Party Logistics, Cold Storage Facilities, Parcel Distribution Hubs Deployment Type: Fixed Charging Stations, Mobile Charging Units, On-Demand Chargers, Robotic Docking Systems |
| Companies Covered | WiBotic, Wiferion, Mobile Industrial Robots, KUKA, Omron, AutoStore, Locus Robotics, Geekplus, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Warehouse Charging Infrastructure Market Trends and Innovations
Power delivery architectures are fragmenting across three competing paradigms—conductive, inductive, and capacitive—each carving distinct territory based on cleanliness requirements, robot density, and legacy system constraints.
Resonant inductive coupling is migrating from cleanroom pharmaceuticals into ambient-temperature e-commerce fulfillment as coil efficiency crosses 93% at 300-millimeter air gaps. Amazon Robotics and Ocado Engineering deploy these systems in new-build facilities where floor-embedded transmitter arrays eliminate charging dead zones. The technology is migrating from premium niche applications toward standardized warehouse infrastructure, compressing the price premium over conductive systems from 4x to 1.5x.
The EU Green Deal's 2030 building renovation targets now classify warehouse charging stations as fixed electrical installations subject to embodied carbon disclosure under the CSRD. Facility operators in Germany and the Netherlands must document cradle-to-grave emissions for charging hardware, favoring vendors with modular, repairable designs over sealed disposable units. Cold storage operators face the strictest compliance burdens, driving preference for inductive systems that eliminate refrigerant-leak risks from connector maintenance.
Third-party logistics providers now specify charging infrastructure as a separate procurement category from robot hardware, unbundling what OEMs previously sold as integrated packages. DHL Supply Chain and GXO Logistics issue RFPs dedicated to power delivery systems, enabling specialist vendors to compete against vertically integrated robot manufacturers. This unbundling is most advanced in the United States, where IRA clean energy tax credits apply to charging station depreciation but exclude mobile robot capital costs.
Autonomous Warehouse Charging Infrastructure Market Segmentation
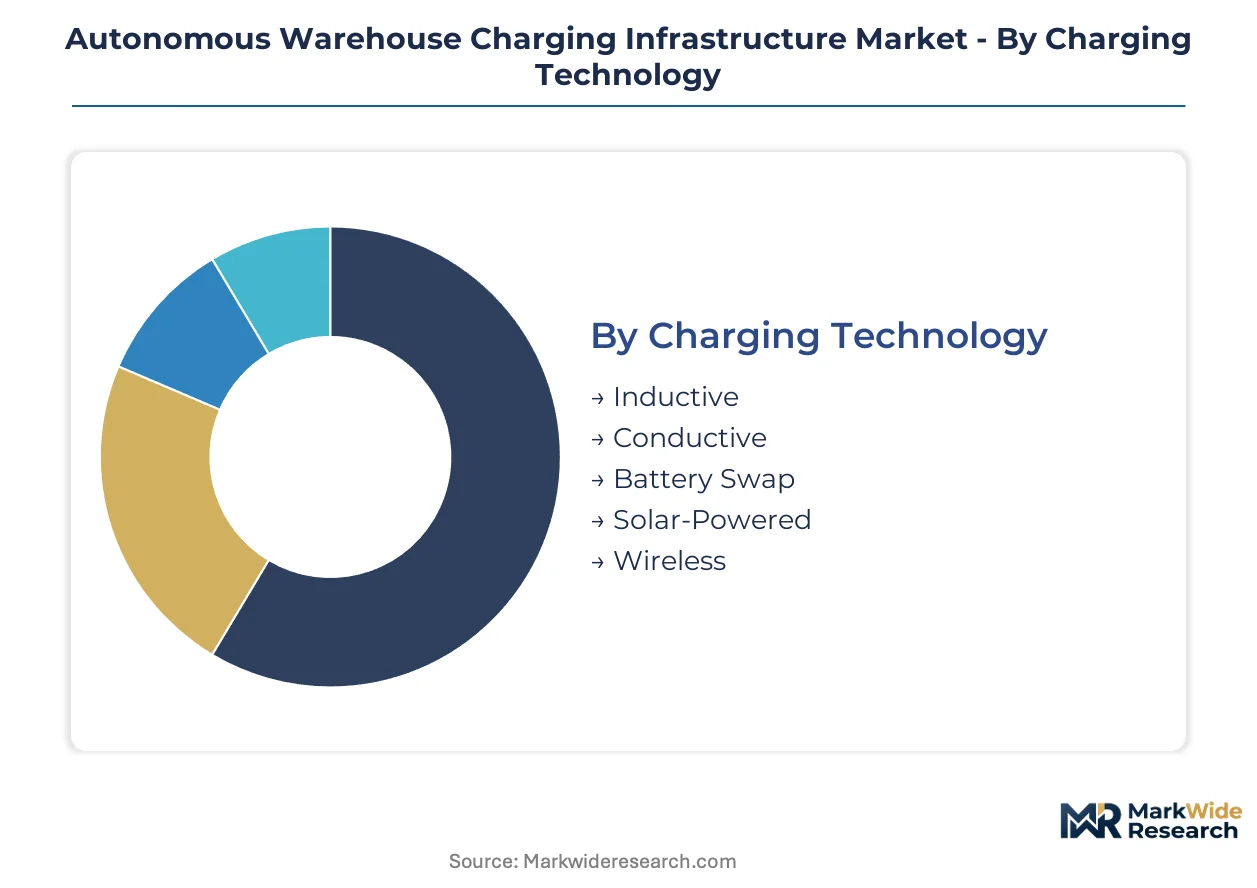
Segmentation in autonomous warehouse charging infrastructure reveals divergent equipment lifecycles, maintenance protocols, and upgrade pathways that reshape vendor-customer relationships. After-sales service intensity varies dramatically across charging technologies and deployment architectures, creating distinct margin profiles and contract structures for infrastructure providers.
Charging Technology:
After-sales service intensity peaks with inductive systems requiring coil alignment calibration and resonant frequency tuning, while conductive pads demand mechanical contact refurbishment programs.
- Inductive:Resonant magnetic coupling systems operate through sealed transmitter-receiver coil pairs with no exposed electrical contacts. Cold storage facilities in Germany and the Netherlands specify these for sub-zero environments where connector corrosion would trigger refrigerant leaks under F-Gas Regulation compliance audits.
- Conductive:Direct contact charging via spring-loaded pogo pins or sliding brushes delivers kilowatt-scale power transfer with 94-96% efficiency. E-commerce fulfillment centers in the United States favor retrofit deployments where gallium nitride power electronics enable compact pad footprints beneath existing robot fleets.
- Battery Swap:Automated exchange stations replace depleted packs with charged units in under 90 seconds. Third-party logistics providers specify these for peak-season surge capacity where charging downtime is unacceptable.
- Solar-Powered:Photovoltaic-integrated charging surfaces supplement grid power for daytime operations. Parcel distribution hubs in California deploy these to capture IRA clean energy tax credits.
- Wireless:Capacitive and microwave power transfer variants serve specialized cleanroom pharmaceutical applications requiring absolute isolation from conductive elements.
By volume, Conductive leads. By growth pace, Inductive is ahead.
Application:
Application segmentation tracks power consumption profiles and robot duty cycles, with fleet charging commanding the highest infrastructure investment per square meter of warehouse footprint.
- Inventory Management:Cyclic charging patterns for automated storage and retrieval systems operating on predictable retrieval schedules. These installations emphasize overnight depot charging rather than opportunity-based replenishment.
- Automated Sorting:High-frequency shuttle systems in parcel hubs require distributed charging nodes every 50-100 meters along conveyor networks. The United States Postal Service specifications for next-generation facilities mandate conductive pad redundancy.
- Material Handling:Forklift AGVs and tugger trains operating continuous loops favor mobile charging units that track fleet movement. German automotive suppliers specify these for just-in-sequence production feed operations.
- Fleet Charging:Centralized power hubs serving 50+ robots simultaneously with coordinated load balancing. Amazon Robotics and Ocado Engineering deploy these in new-build e-commerce fulfillment centers with embedded floor transmitter arrays.
- Order Fulfillment:Piece-picking robots with intermittent mobility patterns suit opportunity charging corridors. Zalando and JD.com facilities integrate wireless power transfer at pick stations to sustain 22-hour operational uptime.
Fleet Charging captures the largest capital allocation. Order Fulfillment is expanding most quickly.
End User:
End user categories separate facilities by environmental control requirements and regulatory exposure, with cold storage commanding premium pricing for sealed inductive architectures.
- E-commerce Fulfillment Centers:High-velocity operations with 500+ mobile robots per facility. These buyers unbundle charging infrastructure from robot procurement, issuing dedicated RFPs for power delivery systems.
- Third-Party Logistics:Multi-tenant facilities serving diverse client requirements with flexible charging configurations. DHL Supply Chain and GXO Logistics standardize on modular conductive pads with hot-swappable connector heads.
- Cold Storage Facilities:Temperature-controlled warehouses at -25°C to +2°C where connector icing and thermal cycling degrade mechanical contacts. EU GDP guidelines for pharmaceutical distribution mandate sealed power interfaces, favoring resonant inductive systems.
- Parcel Distribution Hubs:High-throughput sortation facilities with continuous robot traffic and minimal dwell time. These operations specify on-demand charging corridors integrated with warehouse control software.
E-commerce Fulfillment Centers dominate installed base. Cold Storage Facilities show the steepest expansion trajectory.
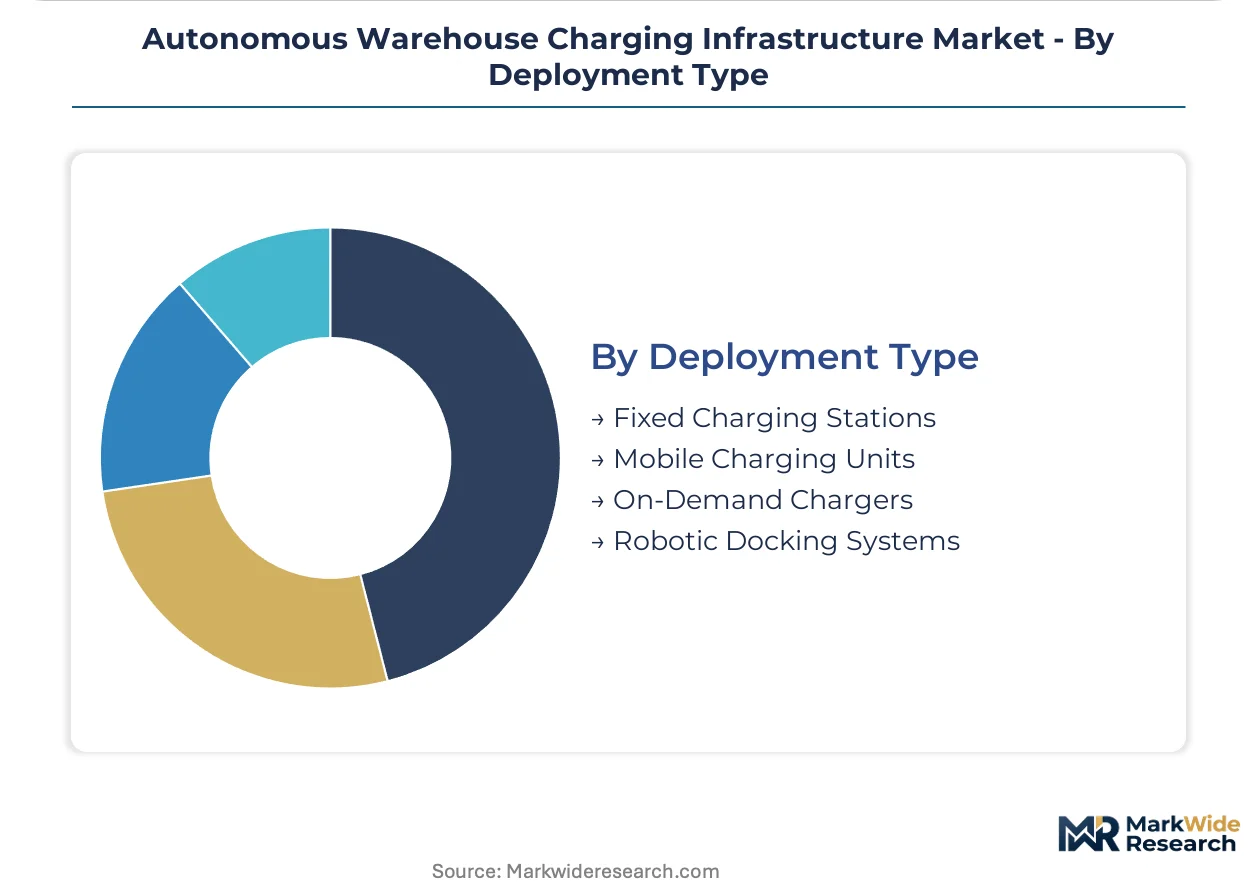
Deployment Type:
Deployment architecture determines facility modification requirements and capital expenditure timing, with robotic docking systems demanding the most extensive civil engineering coordination.
- Fixed Charging Stations:Permanent installations with embedded power distribution and cooling infrastructure. Legacy facilities from the 2010s often lack API endpoints for state-of-charge telemetry, forcing middleware development.
- Mobile Charging Units:Autonomous platforms that reposition to robot concentration zones. These systems suit seasonal demand fluctuations and pilot deployments where permanent infrastructure commitment is premature.
- On-Demand Chargers:Triggered activation systems that energize only during active charging sessions, reducing standby power consumption. California and New York state building codes increasingly mandate these efficiency features.
- Robotic Docking Systems:Precision alignment mechanisms with mechanical latching and data exchange protocols. These installations require sub-millimeter positional accuracy and integration with fleet management software for millisecond-precision handoff coordination.
Fixed Charging Stations retain the largest installed base. Robotic Docking Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in charging infrastructure components tilt heavily toward export surpluses in Germany and China, while the United States and India absorb the bulk of import volumes for domestic facility deployment. Capital equipment shipments from these manufacturing hubs determine regional deployment timelines and technology standardization.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg drive demand for mobile charging units in just-in-sequence production feed operations. The EU F-Gas Regulation mandates sealed power interfaces in pharmaceutical cold chain facilities, accelerating resonant inductive system adoption. The Eindhoven-Randstad corridor hosts concentrated pilot deployments of floor-embedded transmitter arrays in new-build fulfillment centers.
United States
E-commerce fulfillment operators issue dedicated RFPs for power delivery systems, unbundling charging infrastructure from robot procurement. IRA clean energy tax credits apply to charging station depreciation, favoring capital investment in fixed installations. The California Central Valley and Texas Triangle warehouse clusters lead retrofit deployment of gallium nitride-based conductive pads.
China
JD.com and domestic logistics platforms sustain 22-hour robot uptime through continuous wireless charging corridors in Yangtze River Delta fulfillment hubs. The country's dual carbon goals tighten efficiency benchmarks for industrial electrical installations. Shenzhen and Shanghai manufacturing districts concentrate coil assembly production for regional export.
India
PLI scheme subsidies for electronics manufacturing attract first-mover wireless charging-native facility designs in the absence of legacy automation. The national warehousing regulator emphasizes energy-efficient building codes for new logistics parks. Maharashtra and Karnataka industrial corridors host pilot deployments targeting pharmaceutical distribution compliance.
Netherlands
CSRD embodied carbon disclosure requirements classify warehouse charging stations as fixed electrical installations subject to cradle-to-grave emissions documentation. Rotterdam port logistics operators specify modular, repairable designs over sealed disposable units. The Randstad logistics cluster leads European deployment of on-demand charging corridors integrated with warehouse control software.
Autonomous Warehouse Charging Infrastructure Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: vertically integrated robot OEMs, specialist charging technology vendors, and third-party logistics providers unbundling infrastructure procurement. Specialist vendors compete through resonant coil efficiency optimization and gallium nitride power electronics miniaturization. Dominant competitive moves include strategic partnerships between charging hardware vendors and fleet management software platforms, plus geographic expansion through local manufacturing partnerships to circumvent rare earth magnet export constraints.
Within the specialist charging tier, WiBotic occupies a position exemplifying wireless power transfer optimization for mobile robot environments. Wiferion anchors the inductive systems segment through in-house production of charging coils. KUKA sits within the integrated robotics tier, extending system portfolios with conductive charging modules. These three represent distinct strategic archetypes: pure-play wireless specialists, coil manufacturing-anchored inductive vendors, and diversified automation OEMs.
| Leading Market Players |
|---|
| WiBotic |
| Wiferion |
| Mobile Industrial Robots |
| KUKA |
| Omron |
| AutoStore |
| Locus Robotics |
| Geekplus |
| Zebra Technologies |
| Others |
Pricing and Supply Chain Analysis
Neodymium-iron-boron magnet production concentrates in Chinese processing facilities, tethering inductive coil assembly costs to export quota volatility and concentrating margin pools with vendors who secured long-term magnet offtake agreements. This upstream concentration forces downstream pricing stratification between gallium nitride conductive systems and resonant inductive architectures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning for EU F-Gas Regulation compliance in cold storage, while economy tiers serve retrofit conductive pad deployments in legacy US fulfillment centers. Price differentiation rests on coil efficiency ratings and after-sales calibration intensity. Cost compression in standard-tier conductive modules is intensifying because gallium nitride power electronics miniaturization erodes hardware differentiation. Third-party logistics providers exhibit highest price sensitivity due to unbundled procurement practices, whereas pharmaceutical cold chain operators accept premium positioning for sealed inductive architectures.
Supply Chain Analysis
Contract manufacturing for resonant coil assemblies concentrates with Shenzhen and Shanghai-based EMS providers holding dedicated magnet wire winding capacity. Raw material flows draw from Chinese rare earth processing, German copper refining, and Taiwanese gallium nitride foundry output. Supply chain risk centers on single-source vulnerability for neodymium-iron-boron magnet supply subject to export licensing. Distribution runs through robot OEM integrated channels and direct-to-facility infrastructure specialists serving unbundled procurement RFPs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous warehouse charging infrastructure market is cycling through a capital equipment replacement wave as 2010s-era fixed stations reach end-of-life and EU CSRD disclosure requirements force hardware refresh decisions.
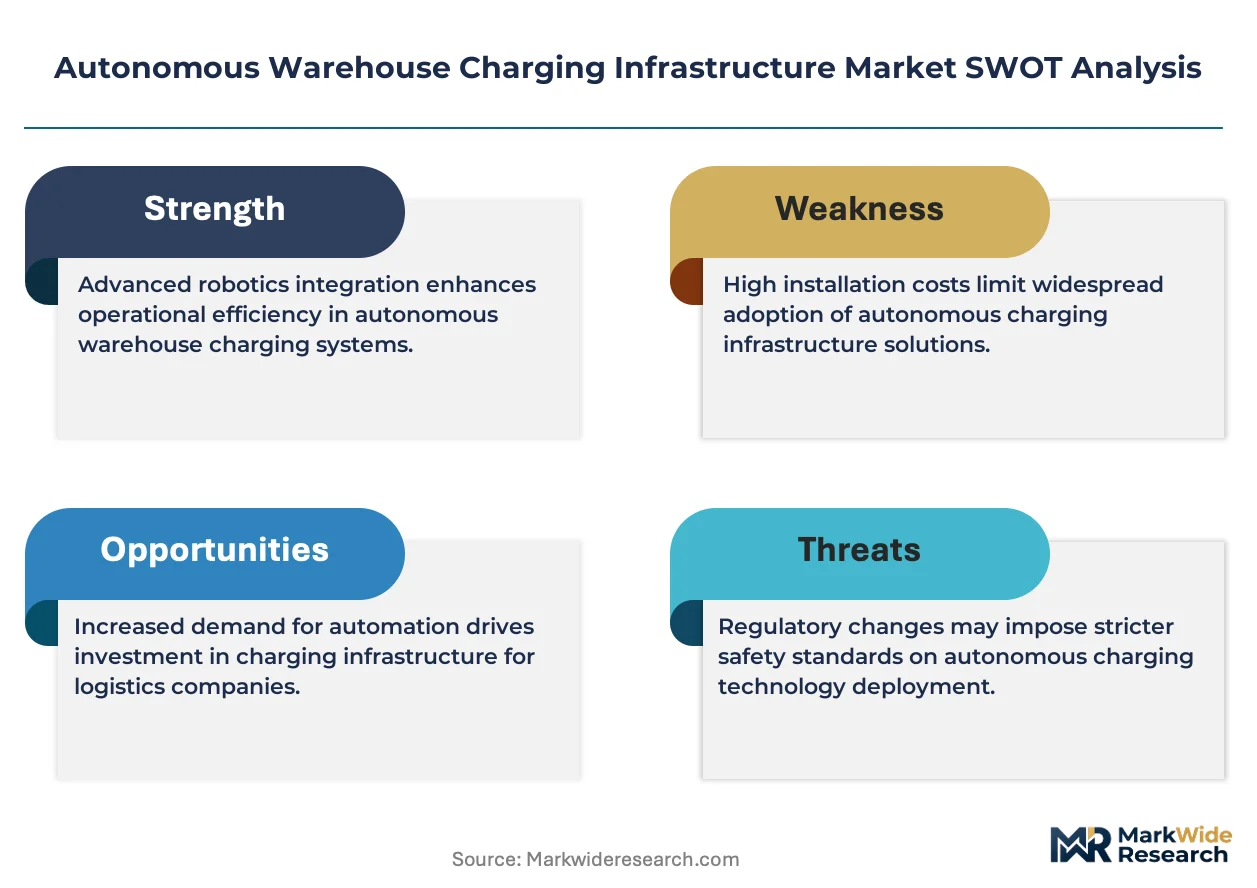
For Market Incumbents: Insulate coil assembly margins through backward integration into magnet wire drawing or captive supply agreements with Chinese rare earth processors. Defend installed base positions by embedding API-native state-of-charge telemetry into legacy warehouse management system middleware, neutralizing the retrofit integration threat from wireless-native challengers. Prioritize CE marking and FCC Part 18 certification maintenance as regulatory moats against unapproved competitors.
For New Entrants and Emerging Players: Pursue white-space positioning in India's PLI-subsidized electronics manufacturing corridor where absence of legacy automation enables wireless charging-native facility design without retrofit constraints. Target pharmaceutical cold chain GDP compliance segments in Germany and the Netherlands where sealed inductive interfaces command premium positioning. Lead with 5G private network integration as a go-to-market differentiator for millisecond-precision robot-to-station coordination.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across gallium nitride power electronics miniaturization as chip-scale integration reduces coil assembly labor content. Long-term viability favors specialist vendors with resonant frequency tuning IP and software-defined charging management platforms over pure hardware assemblers. Acquisition target archetype: inductive coil designers with in-house magnet wire winding and existing CE/FCC certification portfolios. Monitor gallium nitride foundry capacity utilization as inflection indicator for conductive system cost compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Resonant Coil Efficiency Optimization | WiBotic and Wiferion compete on 93% efficiency at 300-millimeter air gaps for cleanroom migration. |
| Gallium Nitride Power Electronics Miniaturization | Enables sub-15-centimeter conductive pad footprints unlocking US legacy facility retrofit deployment. |
| 5G Private Network Integration | Millisecond-precision handoff coordination between robot fleets and charging stations via ultra-reliable low-latency communication. |
| Geographic Manufacturing Partnerships | Circumvents Chinese rare earth magnet export constraints through local coil assembly in target markets. |
| Fleet Management Software Partnerships | Unbundled procurement RFPs from DHL Supply Chain and GXO Logistics favor charging-native software integration. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with charging infrastructure vendors, warehouse automation OEM procurement teams, and third-party logistics facility engineering directors; and secondary validation through EU CE marking databases, FCC Part 18 equipment authorization records, and customs trade flows for inductive coil assemblies. Bottom-up triangulation against top-down facility deployment estimates anchored market sizing across the projection horizon.
Forecast inputs considered charging technology segmentation by conductive, inductive, and battery swap architectures; deployment type across fixed stations, mobile units, and robotic docking systems; and end-user categories spanning e-commerce fulfillment, cold storage, and parcel distribution. CAGRs were derived from facility automation density trajectories and power delivery efficiency improvement curves. Industry-specific inputs included F-Gas Regulation compliance timelines and IRA clean energy tax credit depreciation schedules.
Macroeconomic conditions sit as an overlay; deviation in warehouse construction starts, rare earth magnet export quotas, or e-commerce fulfillment capital expenditure cycles would shift the trajectory. Forecasts assume sustained regulatory pressure for energy-efficient industrial electrical installations and continued unbundling of charging infrastructure from robot hardware procurement. Quarterly review of CE marking application volumes and gallium nitride foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Mobility Technologies Market