
 India Airbag Systems Market | 2026-2036
India Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Airbag Systems Market Foresight
Market Context
The capability gap between capital-heavy integrated suppliers and module assemblers is redrawing competitive tiers in India's airbag landscape. Autoliv Inc. leverages its in-house inflator production to control cost structures across the value chain. Robert Bosch GmbH anchors its position through advanced sensor integration capabilities that feed directly into crash detection algorithms. Hyundai Mobis Co. Ltd. dominates supply to its parent group's extensive India assembly operations, creating a captive demand base that competitors struggle to penetrate.
Technical Definition and Segment Structure
India airbag systems comprise pyrotechnic inflator units, woven nylon fabric cushions, and electronic control modules calibrated to deploy within milliseconds of collision detection, primarily serving occupant protection in automotive applications. Front airbags retain the largest volume share given regulatory mandates, while curtain airbags represent the fastest-growing product category as OEMs extend protection to side-impact scenarios in SUVs and premium hatchbacks. Among vehicle types, SUVs command the highest airbag content per vehicle, creating concentrated margin pools for suppliers aligned with Mahindra, Tata Motors, and Hyundai's expanding SUV portfolios in India.
Regulatory Framework and Outlook
The Ministry of Road Transport and Highways mandates dual front airbags for all passenger vehicles sold in India, while BIS certification requirements govern inflator reliability standards and fabric tensile specifications. CDSCO oversight extends to pyrotechnic materials classified under explosive substances regulations, adding compliance layers to import and local manufacturing operations. Stakeholders must monitor proposed Bharat NCAP protocol expansions and state-level electric vehicle safety mandates that will reshape airbag specification requirements for battery-platform architectures.
Market Dynamics
The mandatory dual airbag rule from the Ministry of Road Transport and Highways is compressing supplier margins while forcing module assemblers to secure inflator supply or exit the market entirely.
Growth Catalysts
- Regulatory Mandate Expansion:The Ministry of Road Transport and Highways' dual front airbag requirement applies to all passenger vehicle categories, eliminating variance in OEM fitment strategies and standardizing baseline demand.
- SUV Platform Proliferation:Mahindra, Tata Motors, and Hyundai are expanding SUV portfolios that carry four to six airbag configurations, multiplying unit content per vehicle beyond hatchback baselines.
- Curtain Airbag Adoption:Side-impact protection modules are penetrating mass-market SUVs and premium hatchbacks as OEMs anticipate Bharat NCAP protocol expansions.
Market Restraints
- Inflator Supply Concentration:Pyrotechnic inflator production concentrates among integrated Tier 1 suppliers with captive chemistry capabilities, creating bottleneck risk for module assemblers lacking backward integration.
- CDSCO Explosives Compliance:Pyrotechnic materials classification under explosive substances regulations adds import licensing delays and local manufacturing qualification timelines.
- Nylon 66 Price Volatility:Woven cushion fabric depends on petrochemical feedstocks exposed to crude price swings, compressing margin predictability for fabric processors.
Strategic Opportunities
- Tamil Nadu Manufacturing Corridor:Sriperumbudur's supplier ecosystem offers land-banked expansion capacity for inflator localization serving Chennai-based OEM assembly plants.
- Electric Vehicle Safety Mandates:State-level EV regulations are anticipated to prescribe enhanced occupant protection for battery-platform architectures, creating specification upgrade cycles.
- Sensor-Airbag Convergence:Integration of accelerometer and pressure sensor data streams with deployment algorithms enables predictive crash detection and tiered inflation force modulation.
Industry Challenges
- BIS Certification Timelines:Inflator reliability testing and fabric tensile validation under Bureau of Indian Standards protocols extend product qualification cycles.
- Pyrotechnic Chemistry Talent Scarcity:Formulation expertise for stable propellant compounds remains concentrated among a narrow specialist workforce, constraining R&D velocity for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Airbag Systems Market |
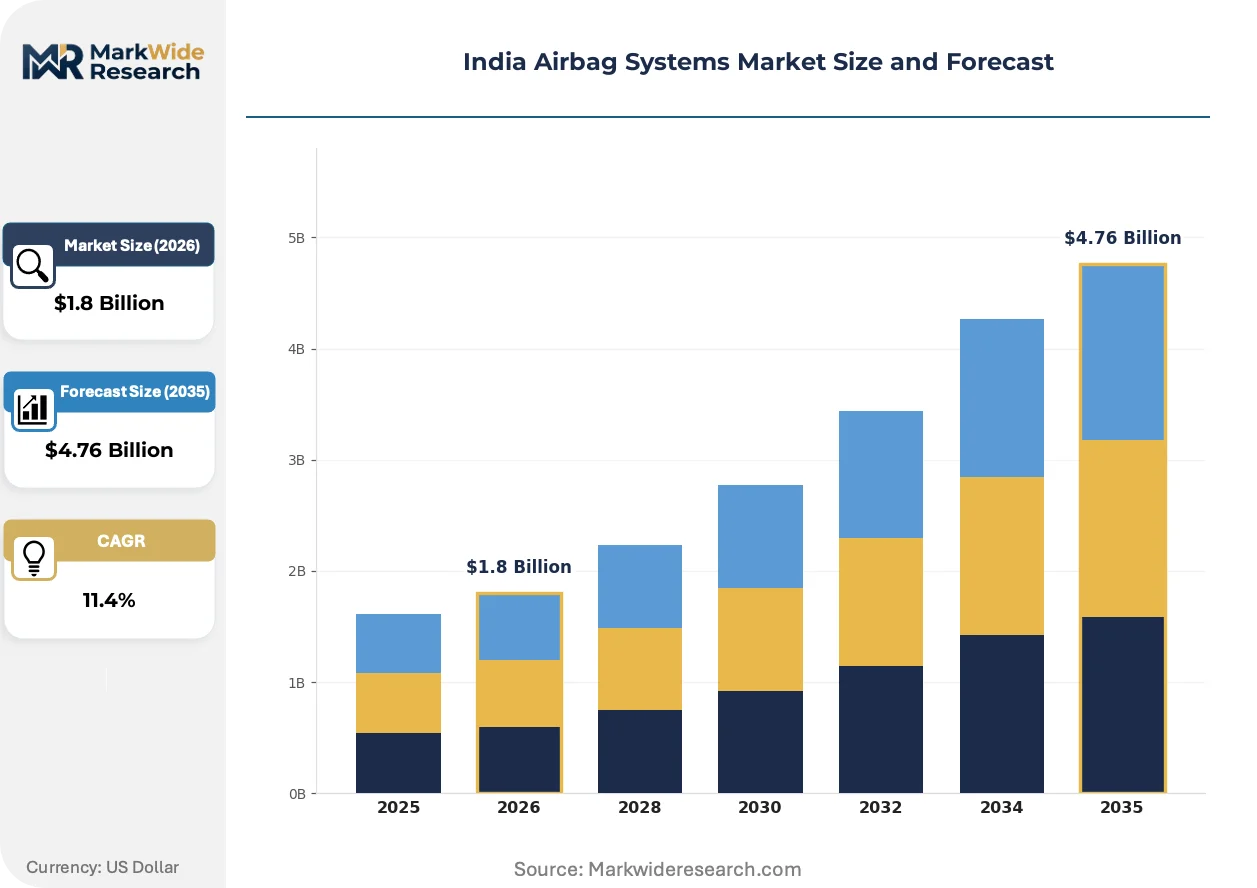
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Airbags, Side Airbags, Curtain Airbags, Knee Airbags Vehicle Type: Sedans, SUVs, Hatchbacks, Commercial Vehicles Technology: Standard, Adaptive, Advanced, Hybrid End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Autoliv Inc., Takata Corporation, Toyoda Gosei Co. Ltd., ZF Friedrichshafen AG, Continental AG, Joyson Safety Systems, Hyundai Mobis Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Airbag Systems Market Shifts & Advancements
Deployment architecture is fragmenting from centralized control modules toward distributed sensor networks, while regulatory pressure and buyer sophistication accelerate specification tiering.
Multi-chamber airbag designs are decomposing the traditional single-cushion configuration into segmented inflation zones that modulate pressure based on occupant position and crash severity. Maruti Suzuki and Hyundai Motor India are piloting these systems in flagship SUVs ahead of broader rollout. The technology is decomposing cost structures by reducing propellant mass per deployment while enabling Tier 1 suppliers to command premium positioning through algorithmic differentiation.
Bharat NCAP protocol development is forcing OEMs to pre-certify vehicles for star ratings that explicitly weight side-impact and pedestrian protection scores. This regulatory pressure is accelerating curtain airbag and far-side protection module fitment in vehicles priced below ten lakh rupees. Suppliers with pre-validated BIS-certified component families capture specification lock-in earlier in platform development cycles.
Fleet operators and insurance underwriters are beginning to specify airbag configuration tiers in procurement criteria, creating channel segmentation between safety-maximized and cost-minimized vehicle variants. This buyer-driven stratification is most visible in Maharashtra's corporate fleet market, where leasing companies negotiate volume commitments contingent on six-airbag standardization across mid-size sedans.
India Airbag Systems Market Segmentation
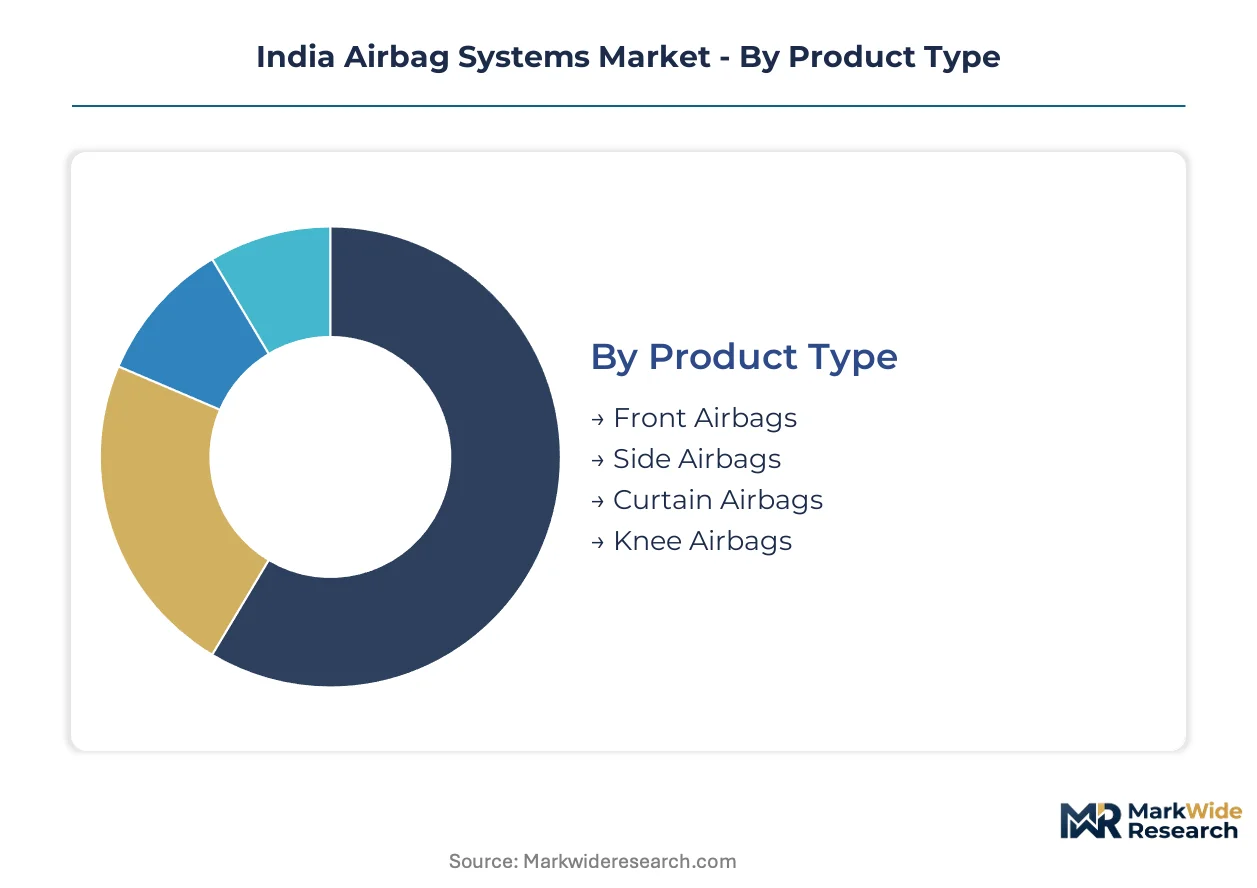
India's airbag systems market segments reflect divergent cost pressures and regulatory exposure across product architectures and vehicle platforms. Understanding these fault lines reveals where supplier margins concentrate and which categories face displacement risk from alternative safety technologies.
Product Type:
Front airbags face minimal substitution threat given the Ministry of Road Transport and Highways' dual-front mandate, while knee airbags confront cost-driven elimination as OEMs prioritize curtain modules for Bharat NCAP scoring.
- Front Airbags:Pyrotechnic driver and passenger modules with nylon 66 cushion fabrics calibrated for 30-50 millisecond deployment. Maharashtra's Pune manufacturing belt and Chennai's Sriperumbudur corridor concentrate demand as Maruti Suzuki, Hyundai Motor India, and Tata Motors anchor assembly operations. Regulatory mandate eliminates variance in OEM fitment strategies.
- Curtain Airbags:Side-curtain modules deploying from roof rails to protect occupant heads during rollover and side-impact scenarios. Mahindra's Thar and Scorpio-N SUVs, plus Tata Motors' Nexon and Punch platforms, drive specification in vehicles priced above eight lakh rupees. Bharat NCAP protocol development accelerates penetration into mass-market segments.
- Side Airbags:Torso-protection units integrated into seat structures for lateral impact mitigation. Compact sedan platforms from Honda Cars India and Toyota Kirloskar Motor specify these modules in mid-trim variants.
- Knee Airbags:Lower-dash deployment modules protecting femur and patella from steering column intrusion. Premium sedan and SUV platforms from Skoda Auto India and Volkswagen India retain fitment; mass-market variants increasingly delete this content to manage bill-of-material costs.
Front airbags retain volume leadership; curtain airbags hold the steepest expansion curve.
Vehicle Type:
Cost tier stratification separates high-airbag-content SUVs from price-sensitive hatchback configurations, with commercial vehicles presenting a distinct procurement logic driven by fleet operator specifications rather than retail buyer preferences.
- SUVs:Four-to-six airbag configurations standard across Mahindra's XUV700, Tata Motors' Harrier, and Hyundai Motor India's Creta and Alcazar platforms. High beltline architectures and rollover risk profiles mandate comprehensive side-impact protection. Margins concentrate here for suppliers with BIS-certified curtain and far-side module families.
- Sedans:Mid-size three-box platforms from Honda City to Hyundai Verna typically specify dual front plus side airbags in upper trims. Corporate fleet procurement in Maharashtra increasingly demands six-airbag standardization for leasing contracts.
- Hatchbacks:Compact two-box vehicles including Maruti Suzuki's Swift and Baleno, plus Tata Motors' Altroz, face acute cost pressure limiting airbag content to regulatory minimums. Dual front modules dominate; curtain fitment remains rare below ten lakh rupees.
- Commercial Vehicles:Light and medium commercial vehicle segments fall outside passenger vehicle mandates, creating specification variance. Ashok Leyland and Tata Motors' truck platforms specify airbags selectively in premium cab variants for long-haul applications.
SUVs command the highest unit content; hatchbacks represent the largest absolute volume pool.
Technology:
Application maturity separates proven standard architectures from emerging adaptive systems, with hybrid configurations gaining traction as OEMs bridge cost and performance requirements across platform tiers.
- Standard:Single-stage pyrotechnic inflators with fixed deployment force calibrated to 50th percentile male occupant. Dominates mass-market hatchback and entry sedan platforms where cost minimization overrides position-sensitive modulation.
- Adaptive:Dual-stage or variable-force inflators adjusting deployment energy based on crash severity and occupant presence detection. Hyundai Motor India and Kia India deploy these systems in mid-size SUVs to optimize protection across unbelted and small-stature occupant scenarios.
- Advanced:Multi-chamber cushions with segmented inflation zones and predictive deployment algorithms integrating accelerometer and pressure sensor data streams. Maruti Suzuki pilots these architectures in flagship Grand Vitara variants ahead of broader rollout.
- Hybrid:Combinations of pyrotechnic and stored gas inflator technologies optimizing packaging efficiency for knee and far-side protection modules. Emerging specification in compact SUV platforms seeking space-constrained solutions.
Standard technology retains cost-driven dominance; adaptive systems gain share fastest as sensor integration costs decline.
End User:
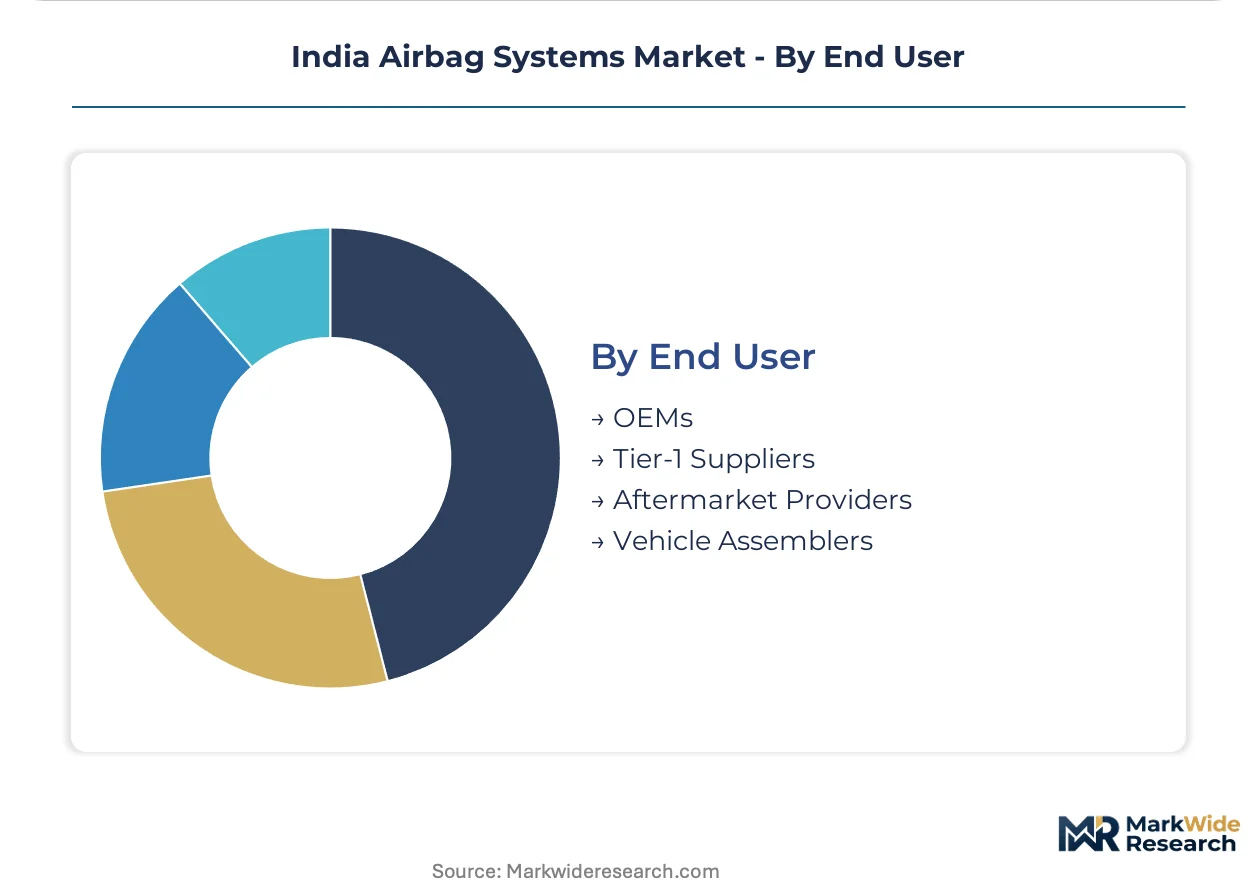
Customer type fragmentation creates divergent procurement patterns, with captive OEM supply relationships constraining independent Tier-1 expansion and aftermarket channels remaining underdeveloped due to safety-critical installation requirements.
- OEMs:Original equipment manufacturers including Maruti Suzuki, Hyundai Motor India, Tata Motors, and Mahindra & Mahindra direct specification and source airbag systems through nominated supplier programs. Direct relationships with Autoliv and Hyundai Mobis lock in volume commitments.
- Tier-1 Suppliers:Module assemblers including Bosch and ZF Group integrate inflators, cushions, and control units for delivery to vehicle assembly plants. Backward integration pressure intensifies as inflator supply concentrates among integrated producers.
- Vehicle Assemblers:Contract manufacturers and joint venture operations including Toyota Kirloskar Motor and Kia India procure airbag systems through parent-group supply agreements or open tender processes.
- Aftermarket Providers:Independent distributors and fitment shops face regulatory barriers including CDSCO explosives licensing and BIS certification requirements for pyrotechnic components. Channel remains marginal due to installation liability and warranty voidance risks.
OEMs and Tier-1 suppliers capture the value chain's dominant share; aftermarket channels remain structurally constrained.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across India's automotive belt. Fleet buyers in western Maharashtra negotiate aggressively on per-unit costs, while Chennai's export-oriented OEMs absorb premium specifications for NCAP compliance.
Maharashtra
Maruti Suzuki and Tata Motors anchor assembly demand across Pune and Nashik corridors. The state's industrial promotion schemes incentivize supplier co-location near Chakan and Talegaon automotive clusters. BIS certification facilities in Mumbai accelerate inflator qualification timelines for western-region suppliers.
Tamil Nadu
Hyundai Motor India and Kia India drive four-to-six airbag specifications from Sriperumbudur assembly plants. CDSCO explosives licensing for pyrotechnic imports processes through Chennai port customs. The Oragadam supplier belt is land-banking capacity for inflator localization serving export markets.
Haryana
Maruti Suzuki's Gurugram and Manesar plants represent India's largest single-site airbag procurement volume. The state offers production-linked incentive offsets for advanced safety component manufacturing. IMT Manesar hosts module assembly operations feeding directly into adjacent vehicle assembly lines.
Gujarat
Tata Motors' Sanand facility and Suzuki Motor Gujarat's Hansalpur complex anchor western-region demand. The state's port infrastructure reduces import lead times for nylon 66 fabric and sensor components. GIFT City's financial incentives attract Tier-1 supplier regional headquarters.
Karnataka
Toyota Kirloskar Motor's Bidadi operations and Volvo Group's bus and truck platforms specify airbags selectively in premium cab variants. The state's electronics manufacturing cluster near Bengaluru supports sensor integration capabilities. Startup incubation programs at IISc are cultivating predictive algorithm talent for next-generation deployment systems.
India Airbag Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in India's airbag systems market. Integrated suppliers with captive inflator production command margin control, while module assemblers compete on logistics proximity and OEM relationship depth. Three archetypes dominate: chemistry-capable integrated manufacturers, sensor-anchored electronics specialists, and captive suppliers serving parent-group assembly operations. Competitive dynamics center on backward integration pressure and BIS certification speed rather than price alone.
Among integrated Tier-1 suppliers, Autoliv Inc. and ZF Friedrichshafen AG exemplify the chemistry-capable archetype with in-house propellant formulation. Robert Bosch GmbH anchors the sensor-integration specialist tier, leveraging accelerometer and pressure-sensing expertise. Hyundai Mobis Co. Ltd. occupies the captive-supply position, serving its parent group's extensive India assembly footprint through nominated supplier programs that competitors struggle to displace.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Autoliv Inc. |
| Takata Corporation |
| Toyoda Gosei Co. Ltd. |
| ZF Friedrichshafen AG |
| Continental AG |
| Joyson Safety Systems |
| Hyundai Mobis Co. Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Maruti Suzuki and Autoliv lock in pyrotechnic inflator supply while anchoring price visibility across multi-year platform cycles, insulating both parties from nylon 66 feedstock volatility that otherwise disrupts module assembler margins.
Pricing Analysis
After-sales service contracts and replacement inflator programs drive lifetime value for integrated Tier 1 suppliers, with pricing stratifying across BIS-certified premium tiers, volume-scaled standard configurations, and economy-grade module assembler offerings. Price differentiation hinges on captive chemistry capabilities versus third-party inflator sourcing, with cost compression in hatchback segments intensifying as OEMs delete knee airbags to manage bill-of-materials. Fleet buyers in Maharashtra exhibit highest price sensitivity, while export-oriented Chennai OEMs absorb premium specifications for Bharat NCAP compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites pyrotechnic chemical feedstock flows from East Asian formulation centers, creating bottleneck exposure for Indian module assemblers lacking backward integration. Supply concentrates in Japan, South Korea, and Germany for precision sensor components, while woven nylon 66 fabric draws from petrochemical processors in China and the United States. Single-source vulnerability pervades inflator supply, with distribution running through nominated supplier programs directly into Pune, Sriperumbudur, and Manesar assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active safety sensor fusion and autonomous emergency braking systems pose credible substitution threats to airbag-centric occupant protection, forcing incumbents to defend specification lock-in through predictive deployment algorithms and integrated crash detection architectures.
For Market Incumbents: Compound defensive positioning through in-house propellant formulation capabilities that neutralize module assembler competition, while securing BIS certification speed advantages ahead of Bharat NCAP protocol expansions. Prioritize capacity addition in Tamil Nadu's Oragadam belt to capture Hyundai and Kia volume commitments. Sensor-airbag convergence R&D represents the critical lever against active safety displacement. For New Entrants and Emerging Players: Anchor in curtain airbag localization for Mahindra and Tata Motors' expanding SUV portfolios, where four-to-six airbag configurations outpace hatchback regulatory minimums. Target the Sriperumbudur supplier ecosystem for land-banked expansion capacity serving export markets. A go-to-market angle through CDSCO explosives licensing partnerships with established chemistry houses accelerates market entry timelines. For Investors and Strategic Acquirers: Sensor-anchored electronics specialists with accelerometer integration capabilities offer asymmetric exposure to deployment algorithm premiumization. Long-term viability centers on consolidation of Tier 2 fabric processors and inflator assemblers into integrated platforms capable of serving both domestic OEMs and export markets. Watch Bharat NCAP star rating adoption rates as the inflection signal for specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Inflator Localization | Reduces CDSCO import licensing delays while securing supply continuity for Chennai-based OEM assembly. |
| Sensor-Airbag Integration | Enables predictive crash detection algorithms that differentiate Tier 1 suppliers in Maruti Suzuki flagship platforms. |
| BIS Certification Acceleration | Captures specification lock-in earlier in platform development cycles ahead of Bharat NCAP expansions. |
| Curtain Airbag Capacity Expansion | Serves Mahindra and Tata Motors SUV proliferation with four-to-six airbag configurations above hatchback baselines. |
| Pyrotechnic Chemistry Talent Acquisition | Addresses formulation expertise scarcity constraining R&D velocity for stable propellant compound development. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association disclosures, combining structured interviews with Tier 1 supplier procurement leads, OEM platform engineers, and CDSCO licensing officers alongside validation through BIS standards documentation, Ministry of Road Transport and Highways circulars, and vehicle production registries. Bottom-up segment sizing triangulates against top-down market envelope checks.
Segmentation dimensions modeled span product architecture, vehicle class, technology tier, and regional production cluster, with value and volume outputs derived through driver-linked elasticity modeling across the projection horizon. CAGRs reflect trajectory convergence from historical fitment rate analysis, regulatory mandate timing, and OEM platform pipeline visibility, incorporating nylon 66 price sensitivity and inflator supply concentration as industry-specific forecast inputs.
Material uncertainties — regulatory delay in Bharat NCAP implementation, pyrotechnic import licensing disruptions, and active safety technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as these factors evolve. Practitioners should keep alternative scenarios live as battery-platform EV safety mandates and sensor fusion adoption curves mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Park Assist System Market