
 Dual Clutch Transmission (DCT) Market | 2026-2036
Dual Clutch Transmission (DCT) Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Clutch Transmission (DCT) Market Analysis
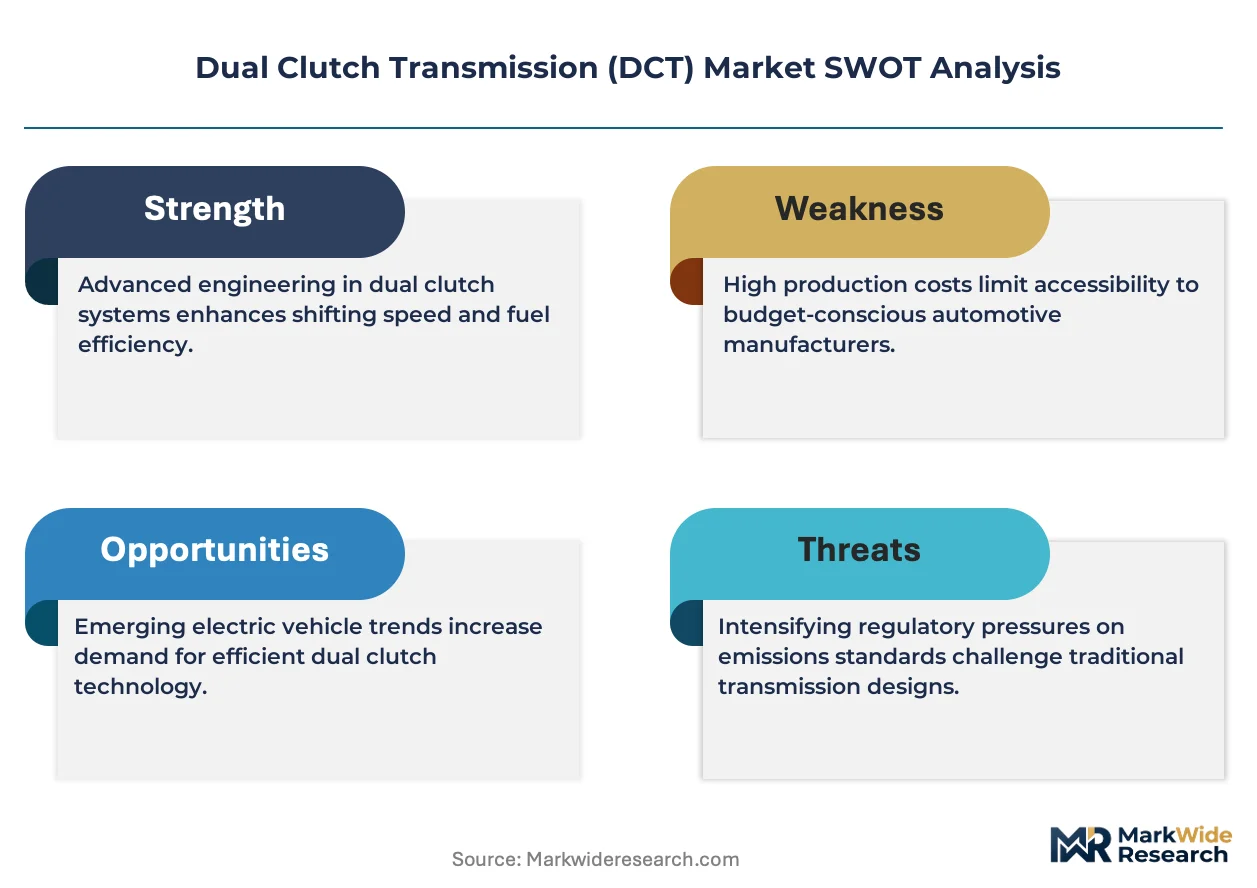
The capital-intensity divergence between integrated transmission specialists and component suppliers is rotating competitive advantage toward players with captive manufacturing of clutch packs and mechatronic control units. ZF Friedrichshafen leverages its integrated powertrain division to sustain full-system design authority from hydraulic actuation through electronic control software. BorgWarner competes through specialized wet clutch engineering for high-performance applications. Schaeffler anchors its position via precision bearing and friction plate technologies that occupy critical tier-two supply roles across multiple OEM platforms.
A dual clutch transmission employs two separate clutches for odd and even gear sets, enabling sub-200 millisecond shift times through pre-selected gears while maintaining torque delivery during changes. The architecture serves primarily to bridge fuel efficiency advantages of manual transmissions with the convenience of automatic operation, particularly in front-wheel-drive passenger car architectures where packaging constraints dominate. Performance and wet clutch segments lead margin pools due to thermal management complexity and premium vehicle application density, while electromechanical actuation represents the fastest-growing technology category as OEMs pursue elimination of hydraulic fluid systems. Heavy-duty applications remain comparatively mature with slower penetration owing to torque capacity validation cycles and fleet operator conservatism.
EPA fuel economy standards and the EU Green Deal's CO2 fleet targets are forcing powertrain diversification strategies that elevate DCT relevance alongside hybridization. NHTSA safety protocols and the EU's F-Gas Regulation shape hydraulic system material choices and refrigerant compatibility in integrated thermal management designs. China's MIIT new energy vehicle quotas and SAMR quality certification requirements create distinct market access conditions for domestic versus imported transmission suppliers. Stakeholders must monitor regulatory calibration between ICE efficiency mandates and electrification timelines to determine DCT platform investment durability against dedicated hybrid and full-electric alternatives.
Market Dynamics
Wet clutch thermal management complexity and electromechanical actuation migration are compressing hydraulic system dominance while fragmenting supplier capability requirements across powertrain architectures.
Growth Catalysts
- EU Green Deal CO2 mandates:German passenger car OEMs expand DCT deployment to meet fleet emission targets without full electrification cost burdens.
- Wet clutch engineering advances:Higher torque capacity designs penetrate performance vehicle segments previously reserved for torque converter automatics.
- China MIIT new energy quotas:Domestic automakers accelerate in-house DCT production to satisfy local content requirements and reduce import dependency.
Market Restraints
- Electrification substitution threat:Battery-electric powertrains eliminate multi-speed transmission needs in dedicated EV platforms.
- Specialized bearing supply concentration:Precision friction plate manufacturing clusters in German and Japanese industrial corridors.
- Heavy-duty validation cycles:Fleet operator conservatism slows torque capacity certification for commercial vehicle applications.
Strategic Opportunities
- Electromechanical-hydraulic convergence:Integrated mechatronic control units enable elimination of hydraulic fluid systems in next-generation architectures.
- China SAMR quality certification:Domestic suppliers capture market access advantages over imported transmission systems.
- Front-wheel-drive packaging optimization:Compact DCT designs penetrate subcompact vehicle segments previously served by manual transmissions.
Industry Challenges
- Mechatronics software integration:Control algorithm development requires rare cross-functional expertise spanning mechanical and electronic engineering.
- Legacy platform compatibility:Electromechanical actuation retrofits face interface standardization delays with existing vehicle electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Clutch Transmission (DCT) Market |
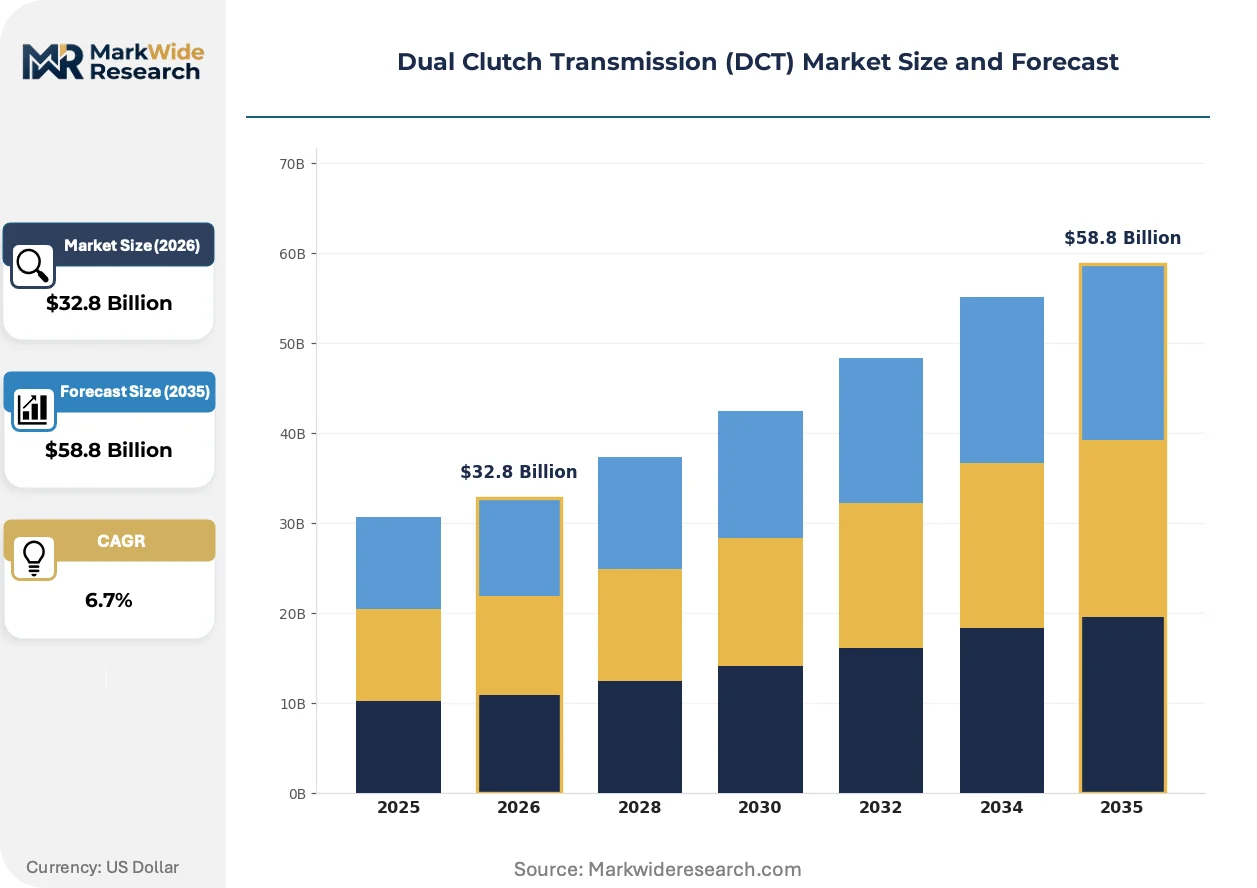
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Performance, Heavy-Duty, Electromechanical Application: Passenger Cars, Commercial Vehicles, Racing, Motorcycles End User: OEMs, Aftermarket, Fleet Operators, Enthusiasts Technology: Wet Clutch, Dry Clutch, Hydraulic Actuation, Electronic Control |
| Companies Covered | ZF Friedrichshafen AG, BorgWarner Inc., Schaeffler AG, Magna International, Continental AG, Eaton Corporation, Volkswagen AG, Getrag, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Clutch Transmission (DCT) Market Emerging Trajectories
Powertrain electrification timelines and thermal efficiency imperatives are forcing simultaneous investment in DCT refinement and hybrid-compatible architectures.
Electromechanical actuation is fragmenting traditional hydraulic system supply chains by eliminating fluid-based components. Tier-one suppliers with captive solenoid and motor manufacturing are capturing control module integration roles. This technology compression is reducing subsystem supplier count while elevating software competency requirements.
The EU F-Gas Regulation restricts refrigerant choices in integrated thermal management designs, forcing clutch cooling circuit material substitutions. NHTSA safety protocols add validation burden for electronic control redundancy. European performance vehicle platforms face the tightest compliance timelines.
Chinese domestic automakers are consolidating transmission procurement around state-backed supplier consortia. Tier-two component vendors face margin compression as volume concentrates with captive manufacturing arms. This buyer consolidation is most visible in Jiangsu and Zhejiang industrial clusters serving BYD and Geely platforms.
Dual Clutch Transmission (DCT) Market Segmentation
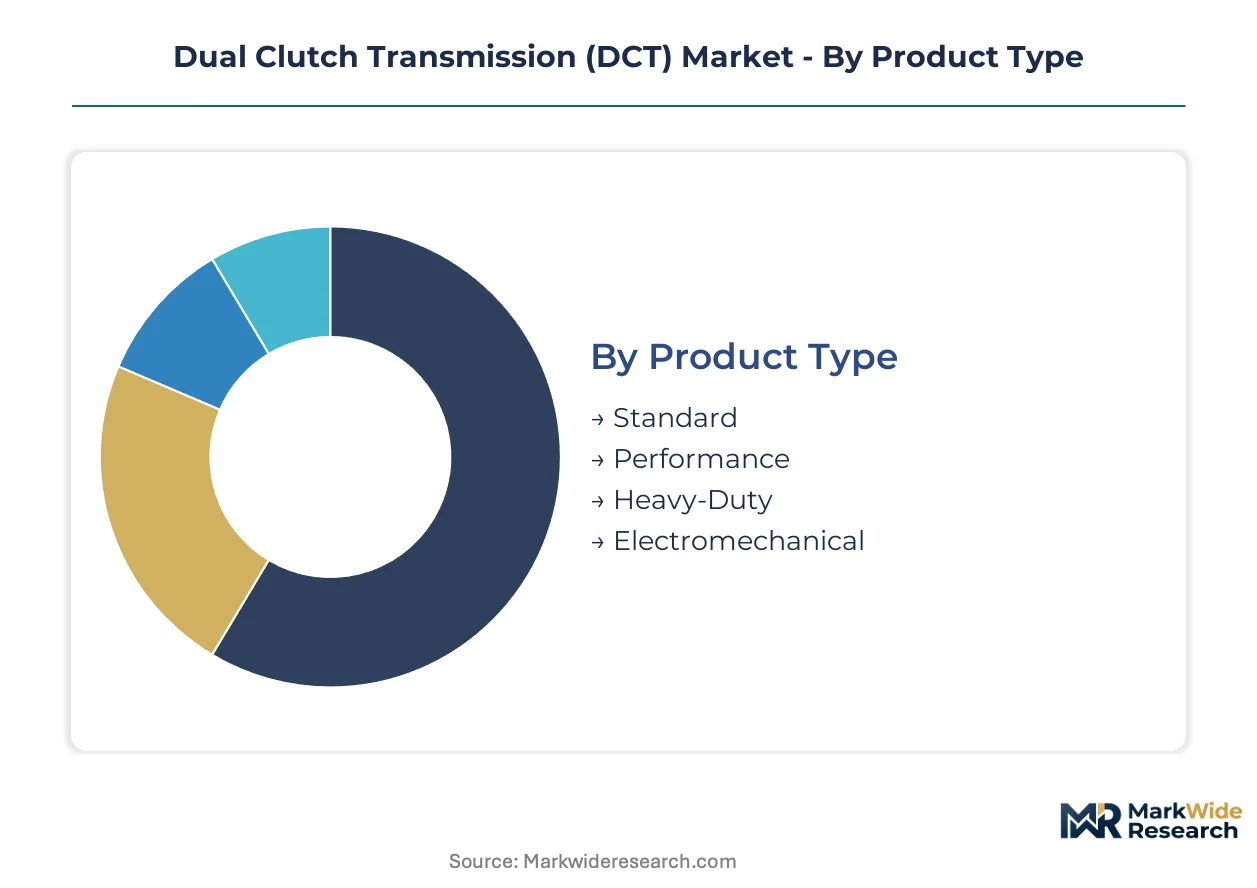
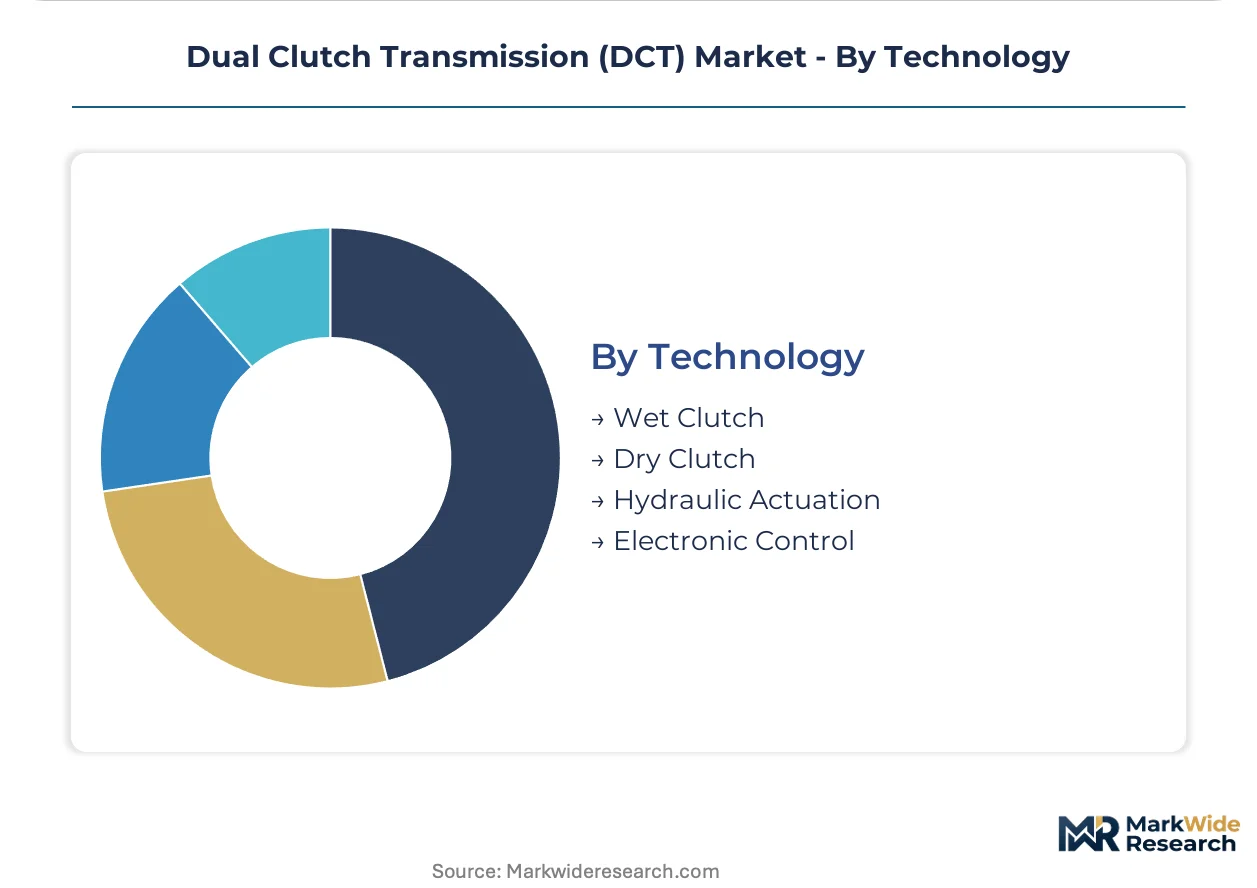
DCT market segmentation reveals divergent vulnerability to electrification displacement across product tiers. Technology and application boundaries are shifting as wet clutch architectures capture torque-intensive segments while electromechanical systems erode hydraulic dominance in efficiency-focused applications.
Product Type:
Substitution pressure from battery-electric powertrains intensifies toward standard and economy-tier architectures, while performance and heavy-duty segments retain structural insulation through torque density requirements.
- Performance:High-torque wet clutch configurations dominate premium passenger car platforms. German OEMs deploy these systems in rear-wheel-drive sport architectures where shift speed precision commands engineering priority over cost minimization.
- Heavy-Duty:Extended validation cycles and fleet operator conservatism slow penetration in commercial applications. Torque capacity certification requirements from NHTSA and equivalent regulators create multi-year barrier-to-entry timelines for new suppliers.
- Standard:Front-wheel-drive compact vehicle applications face margin compression from manual transmission residual demand and entry-level hybrid alternatives.
- Electromechanical:Elimination of hydraulic fluid systems accelerates in next-generation architectures. MIIT efficiency mandates in China and EU Green Deal compliance timelines drive OEM adoption curves.
Standard configurations retain volume leadership; electromechanical systems hold the steepest expansion curve.
Application:
Cost tier differentiation separates premium passenger car deployment from commercial vehicle restraint, with racing and motorcycle segments occupying specialized margin pools.
- Passenger Cars:German and Chinese OEMs anchor deployment in front-wheel-drive platforms where packaging constraints dominate. EPA and EU fleet emission mandates force powertrain diversification strategies that elevate DCT relevance alongside mild-hybrid architectures.
- Racing:Sub-200 millisecond shift requirements sustain premium engineering investment. Thermal management complexity and F-Gas refrigerant compliance add regulatory burden to clutch cooling circuit designs.
- Commercial Vehicles:Fleet procurement cycles favor proven torque converter automatics. Validation conservatism from long-haul operators slows DCT penetration despite fuel economy advantages.
- Motorcycles:Compact packaging requirements drive specialized dual-clutch architectures distinct from automotive designs. Japanese and Italian manufacturers lead platform-specific engineering.
Passenger car applications command revenue concentration; racing segments deliver premium margin extraction.
End User:
Customer type fragmentation creates divergent procurement patterns, with OEM captive production concentrating volume while aftermarket and enthusiast channels sustain specialized component demand.
- OEMs:Integrated transmission specialists and in-house manufacturing arms capture primary volume. Chinese state-backed supplier consortia in Jiangsu and Zhejiang industrial clusters are consolidating procurement around domestic captive production.
- Fleet Operators:Total cost of ownership calculations and maintenance network availability drive conservative adoption timelines. Heavy-duty validation requirements from national transport regulators extend procurement decision cycles.
- Aftermarket:Replacement clutch packs and mechatronic control units sustain tier-two supplier revenue. Precision bearing and friction plate technologies occupy critical supply roles across multiple refurbishment platforms.
- Enthusiasts:Performance upgrade demand concentrates in wet clutch engineering for high-torque applications. Specialized tuning markets in Germany, Japan, and the United States support low-volume premium pricing.
OEM channels dominate volume absorption; enthusiast segments generate disproportionate margin contribution.
Technology:
Supply concentration in precision manufacturing corridors shapes competitive access, with wet clutch and electronic control systems gaining share against legacy hydraulic architectures.
- Wet Clutch:Oil-bath thermal management enables higher torque capacity than dry alternatives. German and Japanese industrial corridors concentrate precision friction plate manufacturing, creating geographic supply constraints.
- Electronic Control:Mechatronic integration eliminates hydraulic fluid systems while adding software competency requirements. Cross-functional expertise spanning mechanical and electronic engineering remains scarce across supplier bases.
- Dry Clutch:Lower cost and simplified maintenance sustain presence in compact passenger car segments. Efficiency advantages diminish as wet clutch engineering advances reduce parasitic losses.
- Hydraulic Actuation:Legacy platform compatibility sustains residual demand. NHTSA safety protocols and EU F-Gas Regulation add validation burden and material substitution requirements to fluid-based system designs.
Wet clutch architectures retain technology leadership; electronic control systems gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the highest price elasticity as domestic automakers aggressively localize DCT production, while German OEMs show lower sensitivity due to performance-tier engineering premiums. Japanese and South Korean markets occupy intermediate positions with technology-driven procurement criteria.
China
Domestic automakers accelerate in-house DCT manufacturing to satisfy MIIT new energy vehicle quotas and reduce import dependency. SAMR quality certification requirements create market access barriers for foreign transmission suppliers. Jiangsu and Zhejiang industrial clusters consolidate procurement around state-backed supplier consortia serving BYD and Geely platforms.
Germany
Passenger car OEMs expand wet clutch DCT deployment to meet EU Green Deal CO2 fleet targets without absorbing full electrification costs. KBA type-approval processes and F-Gas Regulation compliance shape clutch cooling circuit material selections. Baden-Württemberg's precision manufacturing corridor anchors friction plate and bearing supply concentration.
United States
EPA fuel economy standards drive powertrain diversification strategies elevating DCT relevance alongside mild-hybrid architectures. NHTSA safety protocols add validation burden for electronic control redundancy in mechatronic systems. Michigan and Ohio automotive corridors sustain engineering centers focused on front-wheel-drive packaging optimization.
Japan
METI energy efficiency guidelines and corporate average fuel economy targets sustain DCT engineering investment in compact vehicle platforms. JIS standards govern precision component interoperability across supplier networks. Aichi Prefecture's industrial belt concentrates clutch pack manufacturing for both automotive and motorcycle applications.
South Korea
Domestic OEMs balance DCT deployment with dedicated hybrid transmission development under government carbon neutrality roadmaps. MFDS automotive component certification aligns with international type-approval mutual recognition agreements. Gyeonggi Province assembly plants integrate transmission production with battery-electric platform manufacturing.
Dual Clutch Transmission (DCT) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-system design authority separating hydraulic-electronic integrators from component-focused suppliers. The competitive terrain rewards captive manufacturing of clutch packs and mechatronic control units. Two dominant strategic archetypes emerge: integrated powertrain divisions leveraging backward integration into precision components, and specialized friction engineering houses occupying critical tier-two supply roles. Competitive moves concentrate on electromechanical actuation migration and China market access qualification through SAMR certification pathways.
Within the integrated tier, ZF Friedrichshafen AG and BorgWarner Inc. exemplify divergent positioning strategies. ZF Friedrichshafen AG represents the full-system design archetype with powertrain division integration spanning hydraulic actuation through electronic control. BorgWarner Inc. occupies a specialized engineering position emphasizing wet clutch architectures for torque-intensive applications. Schaeffler AG anchors the precision component tier through friction plate and bearing technologies that supply across multiple OEM platforms regardless of transmission architecture.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Schaeffler AG |
| Magna International |
| Continental AG |
| Eaton Corporation |
| Volkswagen AG |
| Getrag |
| Aisin Seiki |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with precision component suppliers lock in clutch pack availability and cost visibility for German and Chinese OEMs navigating MIIT quota compliance and EU Green Deal timelines. These arrangements tether transmission system pricing to bearing and friction plate supply security while insulating integrated manufacturers from spot market volatility in specialized steel alloys.
Pricing Analysis
After-sales service and replacement clutch pack revenue drives lifetime value capture across DCT platforms. Three-tier pricing structure across premium performance, standard front-wheel-drive, and economy compact applications separates wet clutch thermal management systems from dry clutch alternatives. Pricing pressure stems from Chinese domestic automakers consolidating procurement around state-backed supplier consortia in Jiangsu and Zhejiang. Fleet operators demonstrate highest price sensitivity due to total cost of ownership calculations, while performance vehicle OEMs absorb engineering premiums for sub-200 millisecond shift capability.
Supply Chain Analysis
Germany and China anchor precision friction plate and mechatronic control unit production for global DCT supply. Japan and South Korea feed specialized bearing technologies and compact motorcycle transmission architectures. The chain draws from rare earth magnet suppliers for electromechanical actuation motors and advanced steel alloy foundries for clutch housing castings. Single-source vulnerability concentrates in Baden-Württemberg's precision manufacturing corridor for critical tier-two components. Distribution runs through OEM captive manufacturing arms and consolidated state-backed supplier networks rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional expertise spanning mechanical engineering and electronic control algorithm development represents the scarcest capability layer in DCT competitive positioning. Suppliers with captive software competency and precision manufacturing assets command disproportionate margin extraction against component-only competitors.
For Market Incumbents: Shield full-system design authority by deepening backward integration into solenoid manufacturing and mechatronic control module production. Battery-electric powertrain substitution threatens standard-tier DCT volume, making captive clutch pack production and SAMR certification pathways essential defensive levers. Prioritize electromechanical actuation R&D to eliminate hydraulic fluid dependencies ahead of EU F-Gas Regulation tightening. For New Entrants and Emerging Players: SAMR quality certification fast-track programs unlock market access advantages over imported transmission systems serving Chinese domestic OEMs. White-space concentrates in aftermarket replacement clutch packs and mechatronic control unit refurbishment for aging European vehicle fleets. Target enthusiast upgrade segments in Germany and Japan with specialized wet clutch engineering for high-torque applications. For Investors and Strategic Acquirers: Precision component specialists with friction plate and bearing technologies that supply across multiple OEM platforms represent the most defensible acquisition archetype. Long-term viability hinges on DCT platform durability against dedicated hybrid and full-electric alternatives across the mid-decade transition window. Monitor MIIT new energy vehicle quota calibration and EPA fuel economy standard stringency as inflection signals for transmission technology investment priority.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuation Migration | Eliminates hydraulic fluid systems while elevating software competency requirements for ZF and BorgWarner. |
| China SAMR Certification Investment | Domestic suppliers capture procurement consolidation from BYD and Geely platforms versus imported alternatives. |
| Wet Clutch Thermal Engineering Advancement | Higher torque capacity penetrates performance segments previously reserved for torque converter automatics. |
| Backward Integration into Solenoid Manufacturing | Tier-one suppliers capture control module integration roles fragmenting traditional hydraulic supply chains. |
| Aftermarket Control Unit Refurbishment | Replacement mechatronic modules sustain tier-two revenue as European vehicle fleets age. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution managers, and mechatronic control specialists and refined through secondary validation. Bottom-up demand modeling triangulated with top-down macroeconomic drivers drew from vehicle production databases, IHS Markit registration data, MIIT new energy vehicle quota filings, and EU CO2 fleet compliance disclosures. Primary fieldwork captured clutch pack manufacturing cost structures and electromechanical actuation adoption timelines across German, Chinese, and Japanese supplier bases.
Variance decomposition across the projection horizon isolated volume, mix, and pricing drivers by vehicle class, propulsion architecture, clutch type, and regional production cluster. CAGRs derived from segment-level unit economics and content-per-vehicle trajectories incorporated wet clutch thermal management complexity premiums and electromechanical system cost-down curves. Forecast inputs included EPA and EU regulatory stringency scenarios, Chinese domestic automaker localization targets, and fleet operator adoption conservatism for heavy-duty applications.
Underlying assumptions cover regulatory calibration between ICE efficiency mandates and electrification timelines, with deviation risk concentrated in battery-electric platform substitution rates and SAMR certification pathway durations for foreign suppliers. Recalibration cycles align with material shifts in MIIT quota enforcement, EU Green Deal compliance deadlines, and NHTSA safety protocol updates for electronic control redundancy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Camshaft Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Automotive Engine Market
Powertrain
Carburetor Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Crate Engines Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Natural Gas Engines Market