
 Collision Mitigation Technology Market | 2026-2036
Collision Mitigation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Collision Mitigation Technology Market Outlook
Automotive safety integrity level upgrades are redrawing competitive boundaries in collision mitigation. Continental AG leverages its sensor fusion expertise to anchor European OEM supply chains. Robert Bosch GmbH sustains R&D intensity across radar and camera domains. Mobileye specializes in vision-based algorithms that dominate premium passenger vehicle segments.
Collision mitigation technology encompasses integrated sensor arrays, electronic control units, and actuation systems designed to detect imminent collisions and autonomously initiate braking or steering interventions, typically operating within 100-300 millisecond response windows to reduce impact severity. The technology serves commercial and passenger vehicle applications where occupant protection and liability reduction drive procurement. Automatic Emergency Braking commands the largest installed base among product types, while Camera-Based Systems capture expanding share as algorithm accuracy improves. Factory-Fitted installations concentrate margin pools with OEMs, though Aftermarket Providers are gaining traction in commercial fleet retrofits.
NHTSA mandates automatic emergency braking for heavy trucks in the United States, while the EU General Safety Regulation requires intelligent speed assistance and lane-keeping systems across new vehicle categories. Japan's Ministry of Land, Infrastructure, Transport and Tourism aligns type approval standards with United Nations ECE protocols, creating transnational compliance pressure. Stakeholders must monitor regulatory divergence between North American and European test protocols when allocating platform development resources.
Market Dynamics
Sensor fusion architectures are compressing tier-two supplier margins as OEMs consolidate electronic control unit sourcing around vertically integrated platform providers capable of delivering radar-camera-lidar bundles under unified software stacks.
Growth Catalysts
- NHTSA Heavy Truck Mandate:Automatic emergency braking requirements for commercial vehicles above 10,000 pounds are forcing fleet-wide retrofits across US long-haul operators.
- EU General Safety Regulation:Intelligent speed assistance and advanced driver-assistance system mandates are embedding collision mitigation as baseline equipment across new passenger vehicle registrations.
- LiDAR Cost Curves:Solid-state manufacturing advances are driving unit economics below $500 per sensor, enabling mass-market penetration previously restricted to luxury segments.
Market Restraints
- Semiconductor Concentration:Advanced driver-assistance system chip supply concentrates among TSMC and Samsung foundries, exposing tier-one suppliers to 18-month allocation cycles.
- Test Protocol Divergence:NHTSA NCAP assessment criteria diverge from United Nations ECE R131 standards, forcing parallel validation streams that inflate development overhead.
- False Positive Calibration:Urban environment edge cases generate nuisance braking events that erode driver trust and trigger warranty claims.
Strategic Opportunities
- India Commercial Fleet:Underpenetrated heavy truck population exceeds 4 million vehicles with zero automatic emergency braking penetration, creating retrofit channel potential.
- V2X Convergence:Cellular vehicle-to-everything integration with onboard sensor fusion enables cooperative collision avoidance beyond line-of-sight limitations.
- Brazil ANVISA Alignment:Pending adoption of UN ECE protocols for commercial vehicle safety equipment opens regulatory pathway for factory-fit system exports.
Industry Challenges
- Functional Safety Engineering Gap:ISO 26262 ASIL-D certification expertise concentrates among German and Japanese engineering consultancies, constraining supplier scaling.
- Legacy Fleet Integration:Controller area network protocol fragmentation across 2010-2018 commercial vehicle vintages complicates aftermarket retrofit electronics packaging.
- Sensor Cleaning Reliability:Adverse weather performance degradation in camera and LiDAR units requires redundant radar architectures that inflate bill-of-materials complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collision Mitigation Technology Market |
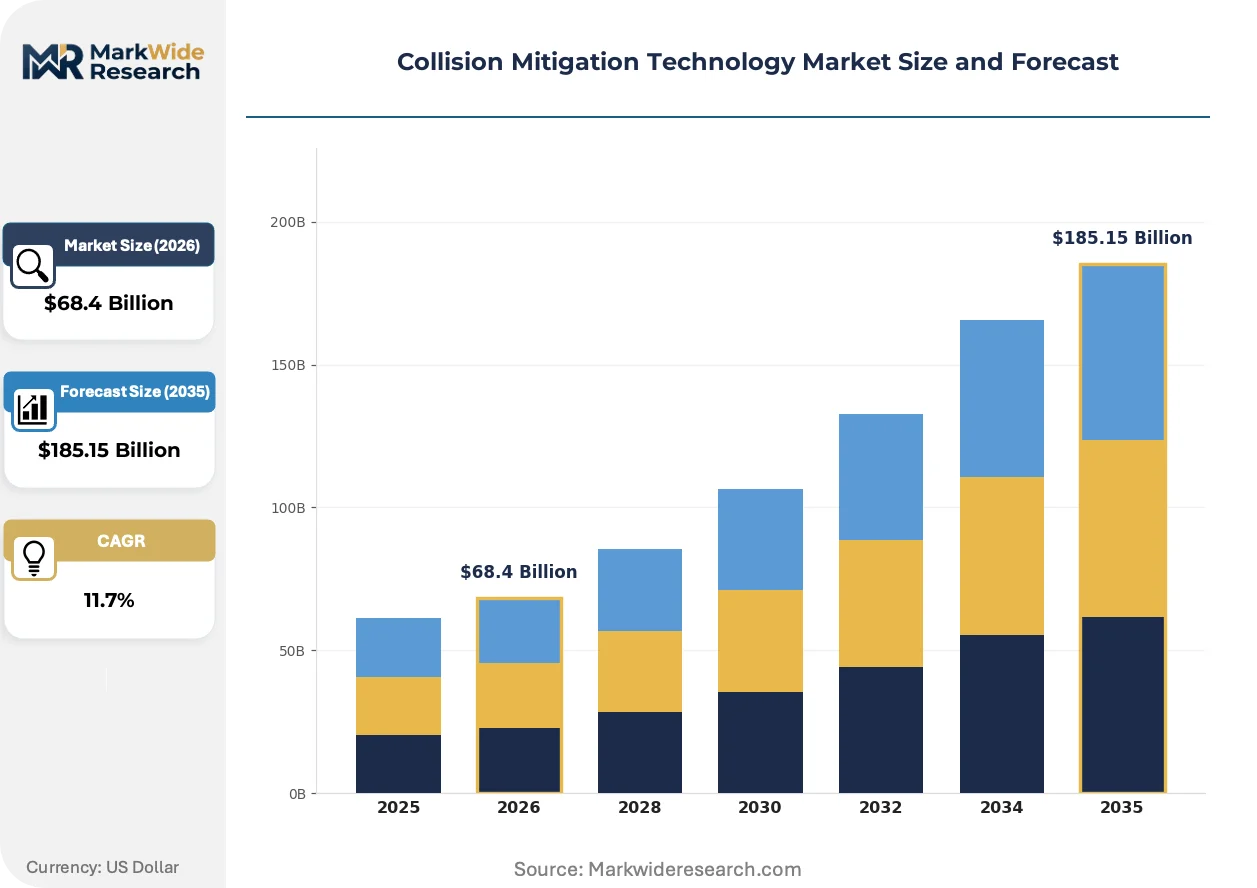
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Emergency Braking, Lane Departure Warning, Adaptive Cruise Control, Collision Warning Systems End User: OEMs, Fleet Operators, Aftermarket Providers, Insurance Companies Technology: Radar Systems, Lidar Systems, Camera-Based Systems, Ultrasonic Sensors Installation: Factory-Fitted, Aftermarket, Retrofitted, Integrated Systems |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Bosch, Aptiv PLC, Valeo SA, Infineon Technologies AG, Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collision Mitigation Technology Market Strategic Shifts
Computational architectures are redistributing processing load between edge devices and cloud infrastructure, reshaping how collision mitigation systems validate threat hypotheses and update operational parameters.
4D imaging radar is fragmenting the traditional sensor hierarchy by delivering dense point clouds at sub-$200 unit costs. Mid-size passenger vehicle platforms are adopting these units as primary perception layers. Tier-one suppliers are compressing LiDAR design wins in mainstream segments where 4D radar performance adequacy meets cost thresholds.
EU AI Act risk classification frameworks are reclassifying collision mitigation algorithms as high-risk artificial intelligence systems. Automotive OEMs are restructuring development documentation and human-oversight protocols to satisfy conformity assessment requirements. German KBA type approval processes are extending by 4-6 months as notified bodies adapt evaluation criteria.
Fleet procurement departments are unbundling hardware acquisition from software subscription services. Commercial vehicle operators in North America are shifting from capital expenditure models to per-mile safety service fees. This consumption-pattern shift concentrates vendor selection authority among fleet management technology platforms rather than traditional parts distributors.
Collision Mitigation Technology Market Segmentation
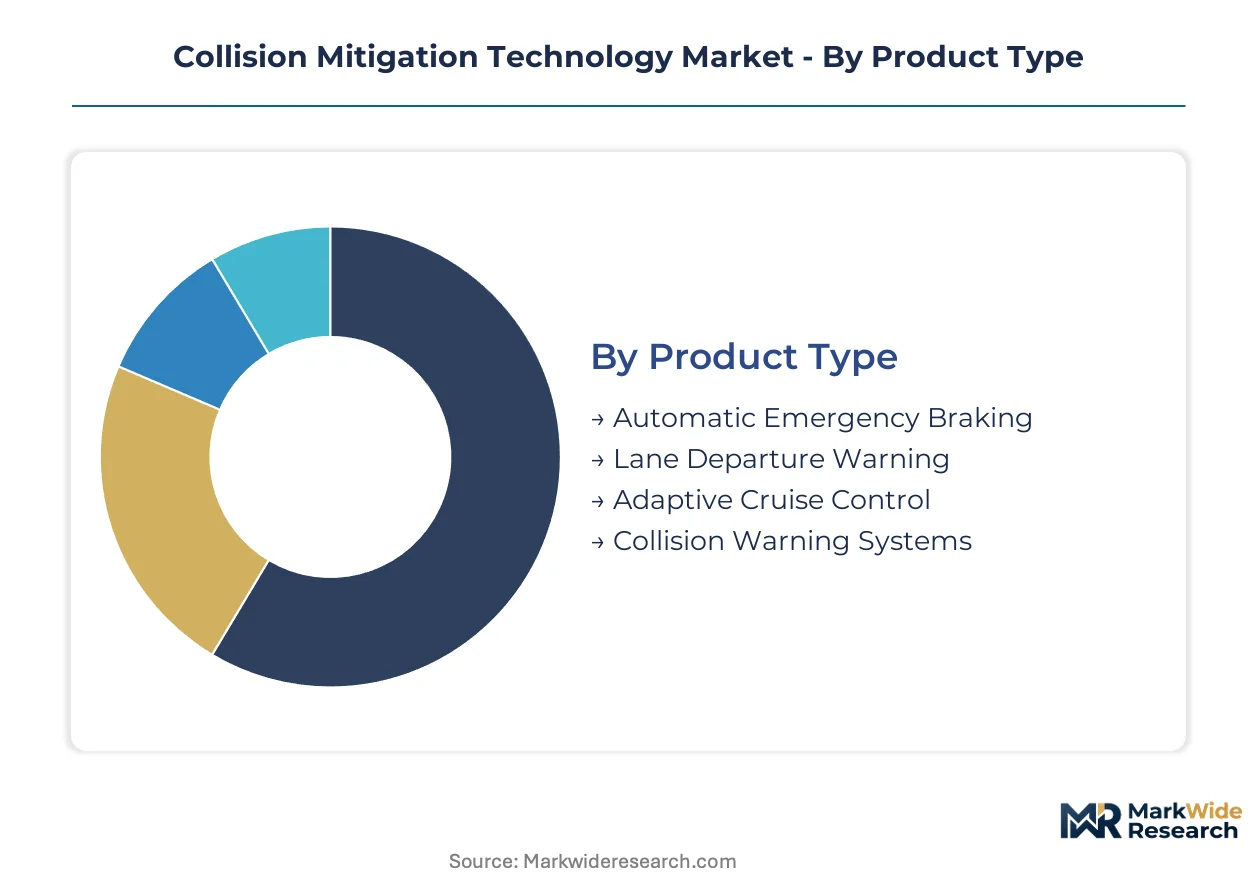
Collision mitigation technology segments reflect divergent procurement patterns across passenger and commercial vehicle ecosystems. Margin pools concentrate where sensor fusion complexity meets regulatory compliance thresholds, while aftermarket channels capture residual value in legacy fleet retrofits.
Product Type:
Margin concentration tracks regulatory mandate intensity and sensor integration complexity across intervention categories.
- Automatic Emergency Braking:Systems autonomously apply maximum braking force when forward collision risk exceeds calibrated thresholds, typically engaging within 300 milliseconds of threat detection. NHTSA mandates for heavy trucks above 10,000 pounds are concentrating procurement among US long-haul fleet operators facing compliance deadlines. The dominant share belongs to Automatic Emergency Braking, while Collision Warning Systems is closing the gap fastest.
- Lane Departure Warning:Camera-based lane boundary monitoring triggers haptic or auditory alerts when unintended drift is detected without turn signal activation. European OEM integration lines in Germany prioritize this capability for EU General Safety Regulation compliance on new passenger vehicle registrations.
- Adaptive Cruise Control:Radar-camera fusion maintains set following distances through automated throttle and braking modulation.
- Collision Warning Systems:Auditory-visual alerts precede autonomous intervention, serving as lower-cost entry points for price-sensitive fleet segments.
Automatic Emergency Braking commands the dominant revenue position, though Collision Warning Systems gains traction as retrofit economics improve.
End User:
Procurement authority patterns diverge sharply between factory integration and post-sale service channels.
- OEMs:Vehicle manufacturers specify sensor fusion architectures during platform development, locking tier-one suppliers into multi-year program contracts with ASIL-D functional safety requirements. German and Japanese automotive engineering centers concentrate specification authority for radar-camera-lidar bundles. OEMs retain the dominant share, while Fleet Operators are expanding procurement fastest.
- Fleet Operators:Commercial vehicle owners above 10,000 pounds face NHTSA retrofit mandates, shifting procurement toward aftermarket channel partners capable of controller area network integration across 2010-2018 vehicle vintages.
- Aftermarket Providers:Independent installers serve uninsured legacy fleets and owner-operator segments outside factory warranty coverage.
- Insurance Companies:Risk-based premium pricing creates indirect procurement influence through telematics-linked coverage incentives.
OEMs dominate absolute volume, yet Fleet Operators drive the steepest expansion trajectory as regulatory deadlines approach.
Technology:
Cost-performance tradeoffs are compressing traditional sensor hierarchies as solid-state manufacturing matures.
- Radar Systems:77 GHz and 79 GHz frequency modulated continuous wave units deliver all-weather reliability with proven automotive qualification paths. Continental AG and Robert Bosch GmbH anchor European supply chains through vertically integrated radar production. Radar Systems holds the dominant share, while Lidar Systems is climbing the fastest.
- Lidar Systems:Solid-state manufacturing advances have driven unit economics below $500 per sensor, enabling mass-market penetration beyond luxury segments previously served by mechanical scanning architectures.
- Camera-Based Systems:Vision algorithms from Mobileye and competitors dominate premium passenger vehicle segments where semantic segmentation accuracy supports complex urban scenarios.
- Ultrasonic Sensors:Low-cost proximity detection serves parking assistance and low-speed maneuvering where range requirements remain minimal.
Radar Systems maintains volume leadership, though Lidar Systems captures accelerating design wins as cost curves flatten.
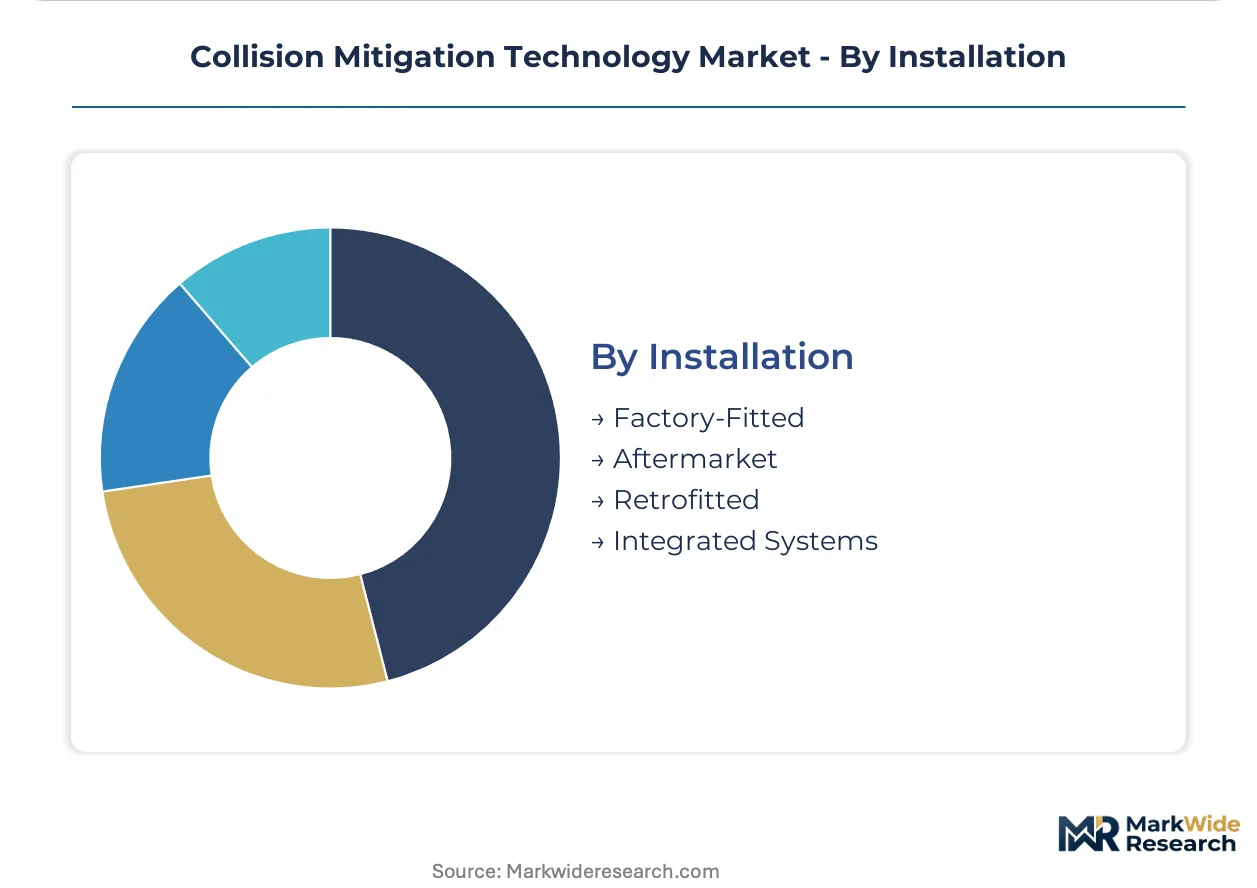
Installation:
Channel economics separate capital expenditure absorption between vehicle lifecycle stages.
- Factory-Fitted:OEM integration during assembly captures highest margin pools through unified software stack validation and warranty alignment. Japan's Ministry of Land, Infrastructure, Transport and Tourism type approval standards favor factory-fit configurations for UN ECE protocol compliance. Factory-Fitted commands the dominant share, while Retrofitted is gaining share fastest.
- Retrofitted:Post-production installation serves commercial fleets facing NHTSA mandates without vehicle replacement budgets, requiring controller area network protocol adaptation across fragmented 2010-2018 vintages.
- Aftermarket:Independent channel serves uninsured owner-operators and developing market segments outside OEM service networks.
- Integrated Systems:Unified sensor-actuator packages consolidate electronic control unit sourcing around platform providers.
Factory-Fitted retains the dominant revenue position, though Retrofitted channels expand most quickly as compliance deadlines force fleet-wide upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan generate substantial collision mitigation technology exports while the United States remains a net importer of advanced sensor fusion systems. Trade flows concentrate around automotive engineering clusters where tier-one suppliers anchor regional supply chains.
United States
NHTSA mandates for heavy trucks above 10,000 pounds are accelerating fleet-wide retrofits among long-haul operators. The Federal Motor Carrier Safety Administration enforces compliance timelines through roadside inspection protocols. Detroit's automotive corridor concentrates radar-camera integration facilities serving domestic OEM production lines.
Germany
KBA type approval standards for UN ECE protocol alignment extend development cycles by 4-6 months, compressing supplier margins. The EU General Safety Regulation embeds intelligent speed assistance as baseline equipment across new passenger registrations. Stuttgart and Munich engineering centers dominate radar production for European OEM supply chains.
Japan
MLIT alignment with United Nations ECE protocols creates transnational compliance pressure for domestic manufacturers. METI funding programs support solid-state LiDAR development for mass-market cost curves. Nagoya's Chubu region anchors tier-one supplier clusters specializing in 77 GHz radar qualification.
China
MIIT new energy vehicle safety standards mandate automatic emergency braking on battery electric platforms above specific price thresholds. GB standards for intelligent connected vehicles require V2X interoperability with onboard sensor fusion. Yangtze River Delta manufacturing bases concentrate domestic LiDAR assembly for local OEM integration.
India
Underpenetrated heavy truck population exceeding 4 million vehicles creates retrofit channel potential for aftermarket providers. BIS automotive safety standards are converging with UN ECE frameworks through phased implementation timelines. Tamil Nadu and Maharashtra industrial corridors attract tier-one suppliers establishing local radar assembly for domestic OEM programs.
Collision Mitigation Technology Market Competitive Environment
Concentration sits with diversified automotive electronics conglomerates capable of delivering radar-camera-lidar bundles under unified software stacks. The vendor base stratifies between vertically integrated platform providers and specialized algorithm developers. Three archetypes dominate: sensor fusion generalists, vision-based software specialists, and semiconductor-integrated module suppliers. Competitive moves center on ASIL-D certification acquisition and multi-year OEM program contract locking.
Among European diversified suppliers, Continental AG and Robert Bosch GmbH exemplify the sensor fusion generalist archetype through captive radar production and tier-one OEM relationships. Mobileye occupies a distinct position as a vision-based algorithm specialist anchored in premium passenger vehicle segments. These three companies represent the structural poles around which procurement authority concentrates in collision mitigation technology markets.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Bosch |
| Aptiv PLC |
| Valeo SA |
| Infineon Technologies AG |
| Mobileye |
| Others |
Value Chain & Pricing Dynamics
4D imaging radar substitution for mechanical LiDAR is redrawing procurement economics across collision mitigation platforms, compressing sensor bill-of-materials while shifting assembly geography toward Yangtze River Delta and Chubu region manufacturing clusters where solid-state fabrication achieves scale.
Pricing Analysis
Industrial OEM buyers anchor contract structures around multi-year program commitments with ASIL-D certification premiums. Three-tier pricing structure across premium, standard, and economy levels reflects software stack complexity and sensor fusion bundle density. Price differentiation tracks ISO 26262 certification grade and volume scale commitments. Cost compression in mid-tier radar-camera bundles is intensifying because 4D imaging radar manufacturers are undercutting legacy LiDAR unit economics. Fleet operators show highest price sensitivity due to retrofit budget constraints, while premium passenger OEMs absorb certification premiums with minimal negotiation.
Supply Chain Analysis
Just-in-time inventory strategies dominate tier-one supplier relationships with German and Japanese OEMs, though strategic stockpiling of semiconductor wafers has intensified following allocation cycle disruptions. Geographic concentration centers on Taiwan and South Korea for ADAS processor fabrication, Germany for radar module assembly, and Japan for 77 GHz frequency components. Raw material dependencies include silicon carbide substrates, gallium nitride semiconductors, and automotive-grade epoxy resins. Single-source vulnerability in TSMC advanced node capacity represents the dominant structural risk. Distribution runs through captive OEM supply chains and authorized tier-one distributor networks serving aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collision mitigation technology is transitioning toward service-attach revenue models where per-mile safety subscriptions expand faster than hardware shipments, creating recurring revenue pools that outpace unit sales growth across North American commercial fleets.
For Market Incumbents: Fortify ASIL-D certification barriers by deepening captive radar production in Stuttgart engineering corridors. Accelerate software-defined platform consolidation to neutralize emerging algorithm specialists threatening premium passenger segments. Lock multi-year OEM program contracts before EU AI Act conformity assessment timelines extend competitive windows.
For New Entrants and Emerging Players: Aftermarket fleet retrofit service gaps where incumbents under-serve legacy CAN protocol fragmentation present immediate white-space opportunity. Target India's 4 million vehicle heavy truck population with controller area network adaptation expertise for 2010-2018 vintages. Pursue direct fleet operator relationships bypassing traditional parts distribution channels.
For Investors and Strategic Acquirers: Capital is best deployed toward vision-based algorithm specialists with automotive safety integrity level certification traction and OEM validation pipeline. Long-term viability favors assets capable of spanning passenger and commercial vehicle regulatory convergence. Watch NHTSA heavy truck mandate enforcement intensity as inflection signal for retrofit channel profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Reduces OEM validation overhead across NHTSA and UN ECE dual compliance requirements. |
| Software Subscription Service Launch | Captures per-mile revenue from fleet operators shifting from capital expenditure models. |
| ASIL-D Certification Investment | Creates regulatory moat against emerging algorithm competitors lacking functional safety documentation. |
| Retrofit Channel Partnership | Unlocks India's underpenetrated heavy truck population through localized CAN integration capabilities. |
| Solid-State LiDAR Manufacturing Scale-Up | Enables mass-market penetration below $500 unit cost thresholds in mid-size passenger segments. |
Study Parameters
Desk research of regulatory filing databases, automotive production registries, and tier-one supplier technical documentation preceded structured interviews with OEM platform engineers, aftermarket fleet operations directors, and semiconductor procurement leads. Primary fieldwork across Stuttgart, Nagoya, and Detroit engineering corridors validated sensor fusion architecture roadmaps and compliance timeline assumptions. Secondary triangulation drew from NHTSA rulemaking dockets, EU General Safety Regulation implementation guidance, and MLIT type approval standards. Bottom-up unit economics modeling converged with top-down market sizing across passenger and commercial vehicle installation channels.
Variance decomposition across technology adoption curves, regulatory mandate phasing, and fleet replacement cycles shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled include product intervention type, end-user procurement authority, sensor technology hierarchy, and installation channel economics. CAGRs were derived from installed base penetration rates and content-per-vehicle trajectories. Industry-specific forecast inputs encompass NHTSA enforcement intensity projections and EU AI Act conformity assessment timeline evolution.
Underlying assumptions cover regulatory deadline adherence, semiconductor allocation cycle normalization, and fleet operator budget availability, with deviation risk concentrated in NHTSA mandate delay scenarios or LiDAR cost curve inflection timing. Forecasts reflect these documented assumptions with explicit sensitivity bands. Revision becomes warranted when NHTSA roadside inspection protocol enforcement crosses compliance threshold acceleration points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market