
 Hysteroscopy Procedures Market | 2026-2036
Hysteroscopy Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Hysteroscopy Procedures Market Intelligence
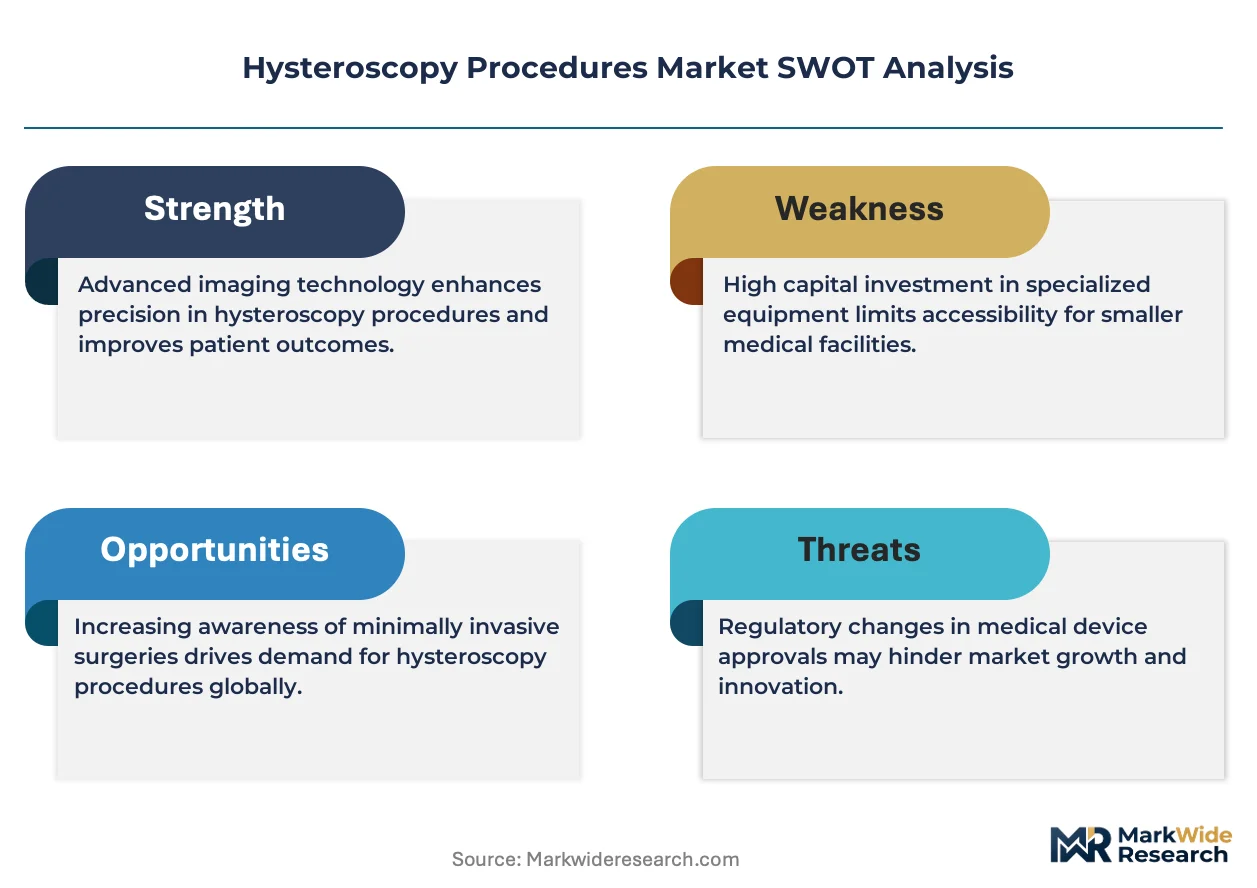
The hysteroscopy procedures market is rebalancing between premium integrated systems and commodity diagnostic devices. KARL STORZ SE and Co. KG leverages its rigid endoscope manufacturing heritage to dominate high-definition optical stacks for operative suites. Boston Scientific Corporation anchors its position through fluid management systems that integrate with electrosurgical platforms. Hologic, Inc. differentiates via diagnostic hysteroscopes paired with proprietary tissue acquisition devices.
Hysteroscopy procedures involve the insertion of a narrow, illuminated endoscope through the cervix to examine or treat the uterine cavity, typically employing distension media such as normal saline or carbon dioxide to expand the cavity for visualization. Operative hysteroscopy systems command premium pricing due to integrated bipolar electrosurgical capabilities and continuous-flow fluid management, while diagnostic hysteroscopy serves as the high-volume entry point across outpatient settings. Ambulatory surgical centers represent the fastest-growing end-user segment as payors shift reimbursement toward same-day polypectomy and endometrial biopsy procedures. Robotic-assisted hysteroscopy remains nascent but concentrates development investment among manufacturers seeking differentiation in complex myomectomy cases.
The FDA enforces 510(k) clearance for hysteroscopic devices with escalating scrutiny of biocompatibility and electrical safety under IEC 60601 standards, while the EU MDR requires updated clinical evidence and post-market surveillance for hysteroscope reclassification. Health Canada and Japan's PMDA maintain parallel quality system expectations that shape export strategies for device manufacturers. Stakeholders must monitor reimbursement parity between office-based and facility-based hysteroscopy as payor policies determine site-of-service economics.
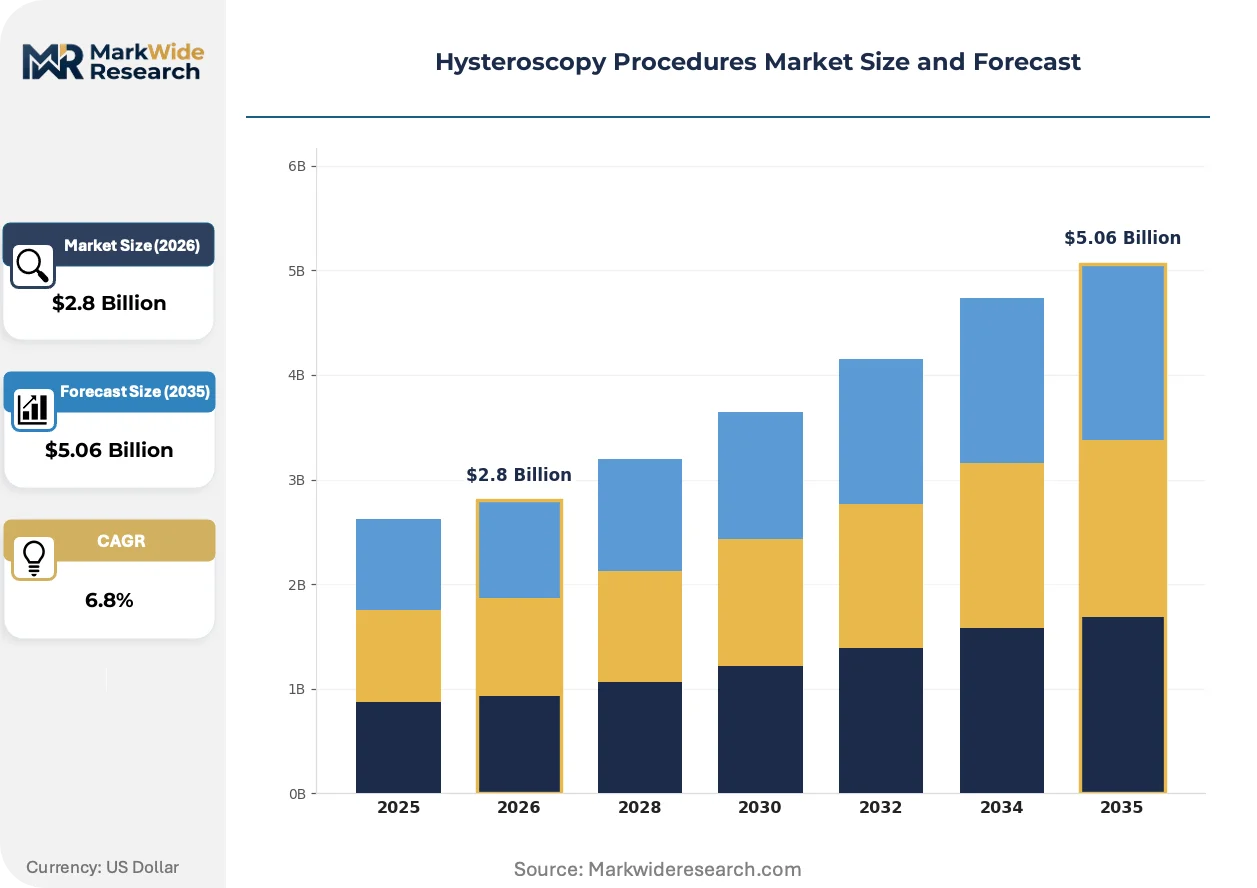
Market Dynamics
The hysteroscopy procedures market is restructuring around site-of-service economics as payor reimbursement policies increasingly favor ambulatory surgical centers over hospital-based procedures, compressing capital equipment cycles while expanding disposable device volumes.
Growth Catalysts
- EU MDR Reclassification:The Medical Device Regulation's updated clinical evidence requirements for hysteroscopes are accelerating manufacturer investment in next-generation platforms with enhanced biocompatibility profiles.
- Ambulatory Surgical Center Expansion:United States payor networks are routing diagnostic hysteroscopy and polypectomy procedures to outpatient settings, driving demand for compact, portable systems.
- Bipolar Electrosurgery:Integration of advanced electrosurgical capabilities into operative hysteroscopy systems is enabling complex myomectomy and adhesiolysis procedures in office-based environments.
Market Restraints
- Optical Stack Concentration:High-definition camera and light source manufacturing concentrates among German and Japanese precision optics suppliers, creating supply vulnerability for second-tier device manufacturers.
- FDA 510(k) Scrutiny:Escalating biocompatibility testing requirements under updated IEC 60601 electrical safety standards are extending clearance timelines for novel hysteroscopic instruments.
- Distension Media Cost Volatility:Normal saline and carbon dioxide supply chains face input cost pressure from pharmaceutical-grade packaging material inflation and sterilization service bottlenecks.
Strategic Opportunities
- Japan PMDA Pathway:Japan's Pharmaceutical and Medical Devices Agency maintains parallel quality system recognition agreements that enable streamlined market entry for manufacturers with FDA or EU MDR clearance.
- Robotic-Assisted Integration:Convergence of haptic feedback systems with miniaturized hysteroscopic platforms is creating white space for precision tissue manipulation in complex uterine pathology cases.
- Health Canada Alignment:Canadian regulatory harmonization with FDA 510(k) pathways offers near-term geographic expansion potential for manufacturers with established United States market presence.
Industry Challenges
- Fluid Management Certification:Continuous-flow hysteroscopy systems require specialized training in pressure monitoring and media deficit calculation, creating workforce pipeline constraints.
- Legacy System Integration:Hospital capital equipment refresh cycles lag behind ambulatory surgical center procurement, forcing manufacturers to maintain backward compatibility with decade-old electrosurgical generators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hysteroscopy Procedures Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Hysteroscopy, Operative Hysteroscopy, Hysteroscopic Accessories, Hysteroscopic Fluid Management End User: Hospitals, Outpatient Clinics, Specialty Clinics, Ambulatory Surgical Centers Procedure Type: Polypectomy, Myomectomy, Endometrial Biopsy, Infertility Treatment Technology: Wireless Hysteroscopy, High-Definition Hysteroscopes, Digital Hysteroscopy, Robotic-Assisted Hysteroscopy |
| Companies Covered | Stryker Corporation, Boston Scientific Corporation, KARL STORZ SE and Co. KG, B. Braun Melsungen AG, CooperSurgical, Inc., OLYMPUS CORPORATION, Medtronic, Richard Wolf GmbH, Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hysteroscopy Procedures Market Strategic Shifts & Innovations
Digital imaging and disposable instrumentation are converging to reshape hysteroscopy economics, compressing the traditional capital equipment model while elevating single-use device revenue streams across outpatient settings.
Single-use hysteroscopes with integrated distal chip cameras are electrifying the diagnostic segment by eliminating reprocessing infrastructure requirements and turnover time constraints. Ambulatory surgical centers in the United States are adopting these platforms at accelerated procurement cycles compared to hospital systems. The technology is compressing the installed base of reusable rigid scopes while expanding addressable procedure volume through simplified workflow integration.
The EU Medical Device Regulation's post-market surveillance mandates are forcing hysteroscope manufacturers to rebuild clinical evidence portfolios for legacy product lines. This regulatory pressure is diverting R&D investment toward platforms with embedded connectivity for real-world performance tracking. Operative hysteroscopy systems with integrated fluid management are most affected, as reclassification under Class IIa rules demands expanded clinical follow-up protocols.
Site-of-service economics are driving procurement consolidation among United States gynecology practice networks seeking standardized platforms across office and facility settings. Bundled device contracts are displacing capital purchase models, with distributors capturing expanded service revenue through preventive maintenance and training subscriptions. This shift is most visible in metropolitan markets where hospital-employed physician networks dominate referral patterns.
Hysteroscopy Procedures Market Segmentation
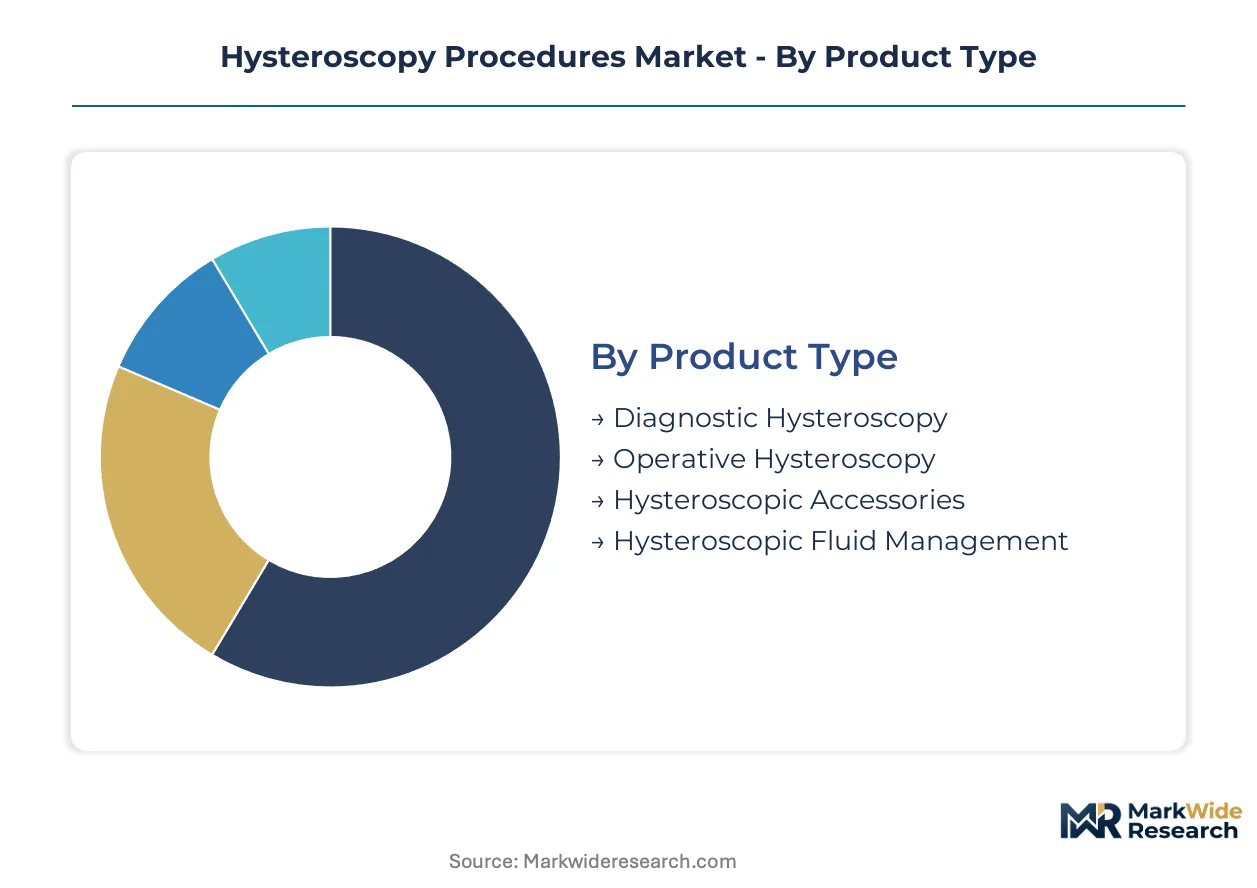
Segmentation in hysteroscopy procedures reveals how technology tiers, site-of-service economics, and procedure complexity create distinct commercial battlegrounds. Manufacturers must align portfolio depth against capital intensity preferences and reimbursement pathways that vary sharply across settings.
Product Type:
Optical specifications and electrosurgical integration define the technology axis across product categories.
- Diagnostic Hysteroscopy:Entry-level rigid scopes with fiber-optic illumination dominate high-volume outpatient screening. Demand concentrates in United States ambulatory surgical centers where same-day reimbursement policies favor rapid patient turnover.
- Operative Hysteroscopy:Integrated bipolar electrosurgical platforms with continuous-flow fluid management enable complex intrauterine interventions. German hospital systems anchor premium procurement for myomectomy suites requiring submillimeter tissue resection precision.
- Hysteroscopic Accessories:Disposable graspers, scissors, and biopsy forceps complete procedure sets.
- Hysteroscopic Fluid Management:Pressure-controlled irrigation systems with media deficit monitoring ensure patient safety during extended operative cases.
Diagnostic hysteroscopy leads on scale; operative hysteroscopy leads on momentum.
End User:
Capital equipment cycles and disposable consumption patterns diverge sharply across facility types.
- Hospitals:Multi-specialty surgical departments maintain centralized sterilization infrastructure and legacy electrosurgical generator compatibility. Japanese tertiary centers anchor installed base stability through decade-long depreciation schedules.
- Ambulatory Surgical Centers:Physician-owned facilities prioritize single-use scopes and compact footprints to eliminate reprocessing overhead. United States payor networks are routing diagnostic and polypectomy cases to these settings fastest.
- Outpatient Clinics:Office-based gynecology practices perform limited diagnostic screening without anesthesia support.
- Specialty Clinics:Fertility-focused centers demand high-resolution optics for subtle endometrial pathology assessment.
Hospitals retain the deepest installed base; ambulatory surgical centers show the steepest expansion trajectory.
Procedure Type:
Reimbursement codes and anesthesia requirements shape procedure economics across clinical indications.
- Polypectomy:Mechanical or electrosurgical removal of endometrial polyps represents the highest-volume operative indication. German outpatient networks are standardizing same-day protocols to capture facility fee optimization.
- Myomectomy:Submucosal fibroid resection demands advanced bipolar energy platforms with tissue morcellation capability. United States academic medical centers concentrate complex cases requiring prolonged operative time.
- Endometrial Biopsy:Minimally invasive tissue sampling for malignancy screening drives diagnostic scope utilization.
- Infertility Treatment:Adhesiolysis and septum resection procedures require precision optics for fertility preservation outcomes.
Polypectomy dominates procedure volume; myomectomy commands the highest per-case device revenue.
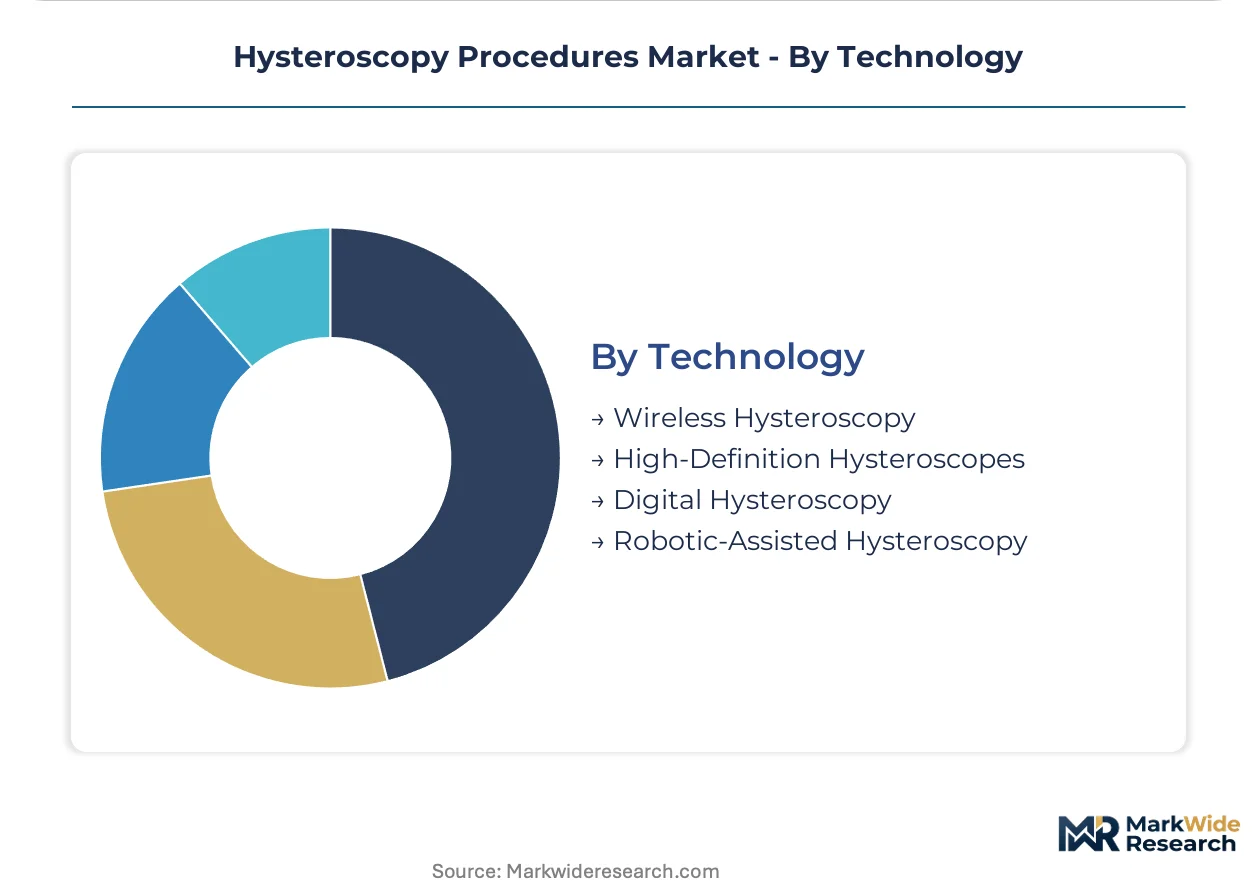
Technology:
Imaging resolution and connectivity features differentiate platform generations across the installed base.
- High-Definition Hysteroscopes:1080p camera systems with enhanced depth perception anchor operative suite visualization standards. Japanese precision optics suppliers concentrate manufacturing for premium surgical stacks.
- Digital Hysteroscopy:Distal chip CMOS sensors eliminate fiber-optic bundles and enable integrated image capture. United States ambulatory surgical centers are adopting these platforms to streamline documentation workflows.
- Wireless Hysteroscopy:Cable-free scopes reduce operative field clutter and turnover preparation time.
- Robotic-Assisted Hysteroscopy:Haptic feedback and tremor filtration remain developmental for complex uterine pathology cases.
High-definition hysteroscopes hold current market depth; digital hysteroscopy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics engineers and Japanese surgical instrument specialists anchor the global hysteroscopy workforce, concentrating manufacturing expertise in Stuttgart and Tokyo metropolitan clusters.
United States
Ambulatory surgical center networks in Texas and Florida are routing diagnostic hysteroscopy cases away from hospital settings. The FDA 510(k) pathway enforces escalating biocompatibility scrutiny under updated IEC 60601 electrical safety standards. Greater Boston's medical device corridor hosts development operations for next-generation fluid management platforms.
Germany
Tertiary hospital systems in Bavaria and North Rhine-Westphalia maintain premium procurement cycles for operative hysteroscopy suites. The EU MDR reclassification demands updated clinical evidence portfolios for legacy hysteroscope product lines. Stuttgart's precision optics cluster supplies high-definition camera stacks to global surgical equipment manufacturers.
Japan
Academic medical centers in Tokyo and Osaka concentrate complex myomectomy cases requiring submillimeter tissue resection precision. The PMDA maintains quality system recognition agreements that streamline market entry for manufacturers with FDA or EU MDR clearance. Nagoya's industrial corridor houses electrosurgical generator manufacturing for integrated hysteroscopy systems.
United Kingdom
NHS payor networks are consolidating gynecology service procurement across London and Southeast England hospital trusts. MHRA alignment with EU MDR post-market surveillance mandates shapes device registration timelines. The Cambridge medical technology cluster incubates digital hysteroscopy platforms with embedded connectivity features.
Canada
Provincial health authorities in Ontario and Quebec are expanding same-day polypectomy reimbursement parity between office and facility settings. Health Canada regulatory harmonization with FDA 510(k) pathways offers streamlined geographic expansion for United States-established manufacturers. Toronto's hospital network anchors national training protocols for continuous-flow fluid management certification.
Hysteroscopy Procedures Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the hysteroscopy market structure. German and Japanese precision optics manufacturers anchor consolidated supply positions in high-definition camera stacks. Three archetypes dominate: integrated system vendors bundling electrosurgical and fluid management capabilities, specialized optical component suppliers, and disposable instrument specialists compressing reprocessing economics. Competitive moves concentrate on M&A for technology tuck-ins and strategic partnerships for regulatory pathway acceleration.
Among integrated system vendors, KARL STORZ SE and Co. KG and OLYMPUS CORPORATION exemplify the precision optics heritage archetype, occupying positions anchored in rigid endoscope manufacturing traditions. Boston Scientific Corporation sits within the fluid management integration tier, representing convergence between irrigation systems and electrosurgical platforms. These three entities illustrate how competitive positioning stratifies between optical technology depth and systems integration breadth.
| Leading Market Players |
|---|
| Stryker Corporation |
| Boston Scientific Corporation |
| KARL STORZ SE and Co. KG |
| B. Braun Melsungen AG |
| CooperSurgical, Inc. |
| OLYMPUS CORPORATION |
| Medtronic |
| Richard Wolf GmbH |
| Hologic, Inc. |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of high-definition optical stacks by German and Japanese precision optics specialists anchors both supply security and premium pricing power for integrated hysteroscopy system vendors. This backward integration into camera and light source production insulates tier-one manufacturers from component cost volatility while enabling sustained margin capture on operative platforms sold to tertiary hospital systems.
Pricing Analysis
Bundled service contracts encompassing preventive maintenance, training subscriptions, and software updates now command 40-60% of lifetime customer value, displacing pure capital equipment transactions. Price differentiation rests on electrosurgical integration depth and FDA 510(k) clearance tier, with ambulatory surgical centers exhibiting acute price sensitivity compared to hospital systems absorbing premium pricing for myomectomy suite configurations. Pricing pressure stems from single-use hysteroscope commoditization in diagnostic segments, compressing per-procedure revenue for reusable platform vendors.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital purchasing committees and European procurement consortiums require qualified secondary suppliers for fiber-optic bundles and electrosurgical generators. Manufacturing concentrates in Germany, Japan, and the United States for precision optics and electrosurgical components, with supply chains drawing from pharmaceutical-grade saline suppliers and sterilization service providers. Single-source vulnerability concentrates in CMOS sensor fabrication for digital hysteroscope platforms. Distribution runs through specialized surgical device distributors and direct hospital contracting teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR reclassification and FDA 510(k) biocompatibility escalation are accelerating replacement demand for next-generation platforms with embedded connectivity and enhanced clinical evidence portfolios.
For Market Incumbents: Acquire disposable instrumentation specialists to capture ambulatory surgical center volume shifting toward single-use scopes. Consolidate fluid management technology assets to defend against emerging platform competitors bundling irrigation with electrosurgical capabilities. Prioritize M&A targets with established Health Canada or Japan PMDA quality system recognition to accelerate geographic expansion.
For New Entrants and Emerging Players: Distal chip CMOS sensor miniaturization offers a technology-first wedge against fiber-optic incumbents in the diagnostic hysteroscopy segment. Target United States metropolitan ambulatory surgical center networks seeking rapid patient turnover without reprocessing infrastructure. Pursue GPO contract participation alongside distributor partnerships for initial installed base penetration.
For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with captive service revenue streams because site-of-service consolidation is compressing capital equipment cycles while expanding recurring maintenance and training subscriptions. The 5-10 year viability window favors platform vendors with software companion development capabilities and real-world performance tracking infrastructure. Monitor reimbursement parity shifts between office-based and facility-based hysteroscopy as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Biocompatibility testing under IEC 60601 standards gates market entry for novel instruments. |
| CE Marking Pathway | EU MDR Class IIa reclassification demands expanded clinical evidence for hysteroscope platforms. |
| Hospital System Partnership | Bundled contracts with United States gynecology practice networks displace capital purchase models. |
| Software Companion Development | Embedded connectivity satisfies EU MDR post-market surveillance mandates for real-world performance tracking. |
| Reimbursement Strategy | Payor policy alignment between office and facility settings determines site-of-service economics. |
Research Approach
Multiple input streams — primary interviews with hysteroscope product managers, hospital biomedical engineers, and GPO contracts specialists; secondary validation through FDA 510(k) clearance databases, EU MDR notified body documentation, and CMS Medicare reimbursement files; and trade data from surgical device import records — were reconciled through bottom-up procedure volume modeling and top-down manufacturer revenue triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, end-user facility category, procedure complexity, and technology generation to isolate price-volume elasticities. CAGRs were derived from installed base turnover dynamics and ambulatory surgical center expansion trajectories, incorporating bipolar electrosurgical adoption curves and single-use scope penetration rates as industry-specific forecast inputs.
The model holds under stable reimbursement parity between settings; deviation in United States payor site-of-service policy or EU MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
China Arthroscopy Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Endoscopy Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Global Disposable Endoscope Market