
 Endoscopic Balloon Dilator Market | 2026-2036
Endoscopic Balloon Dilator Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Balloon Dilator Market Analytics
Specialized interventional endoscopy training is redrawing competitive boundaries as hospitals struggle to staff advanced therapeutic procedures. Boston Scientific Corporation leverages its integrated ecosystem of endoscopic tools and physician education programs to sustain loyalty across academic medical centers. Cook Medical anchors its position through deep specialization in balloon dilator catheters with controlled radial expansion profiles. Olympus Corporation dominates the visualization and access layer, competing on channel density rather than balloon economics alone.
An endoscopic balloon dilator is a catheter-mounted inflatable device deployed through the working channel of an endoscope to mechanically widen stenotic lumens in the gastrointestinal, urological, or aerodigestive tracts, typically constructed from polyethylene terephthalate or nylon with rated burst pressures between 3 and 20 atmospheres depending on indication. Double-lumen configurations command premium positioning because they enable simultaneous guidewire retention and contrast injection, reducing procedural complexity and fluoroscopy exposure. Polymer-based balloon materials lead volume production due to cost scalability, though composite constructions incorporating braided metallic layers are capturing share in high-pressure biliary and achalasia applications where dimensional stability under inflation stress determines clinical outcomes.
FDA 510(k) clearance pathways and EU MDR Class IIa conformity requirements shape product development timelines and sterilization validation burdens for manufacturers seeking dual-market access. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 further constrain material selection and supplier qualification processes. Stakeholders must monitor how Japan's PMDA and South Korea's MFDS evolve their reimbursement frameworks for therapeutic endoscopy, as these decisions will determine whether premium dilator technologies achieve sustainable adoption in Asia's highest-value procedural markets.
Market Dynamics
Interventional gastroenterology training bottlenecks are compressing procedural capacity expansion faster than device innovation cycles, forcing hospitals to prioritize multi-use platforms over single-purpose tools. This talent scarcity is decomposing traditional purchasing patterns and elevating vendor education ecosystems to primary competitive moats.
Growth Catalysts
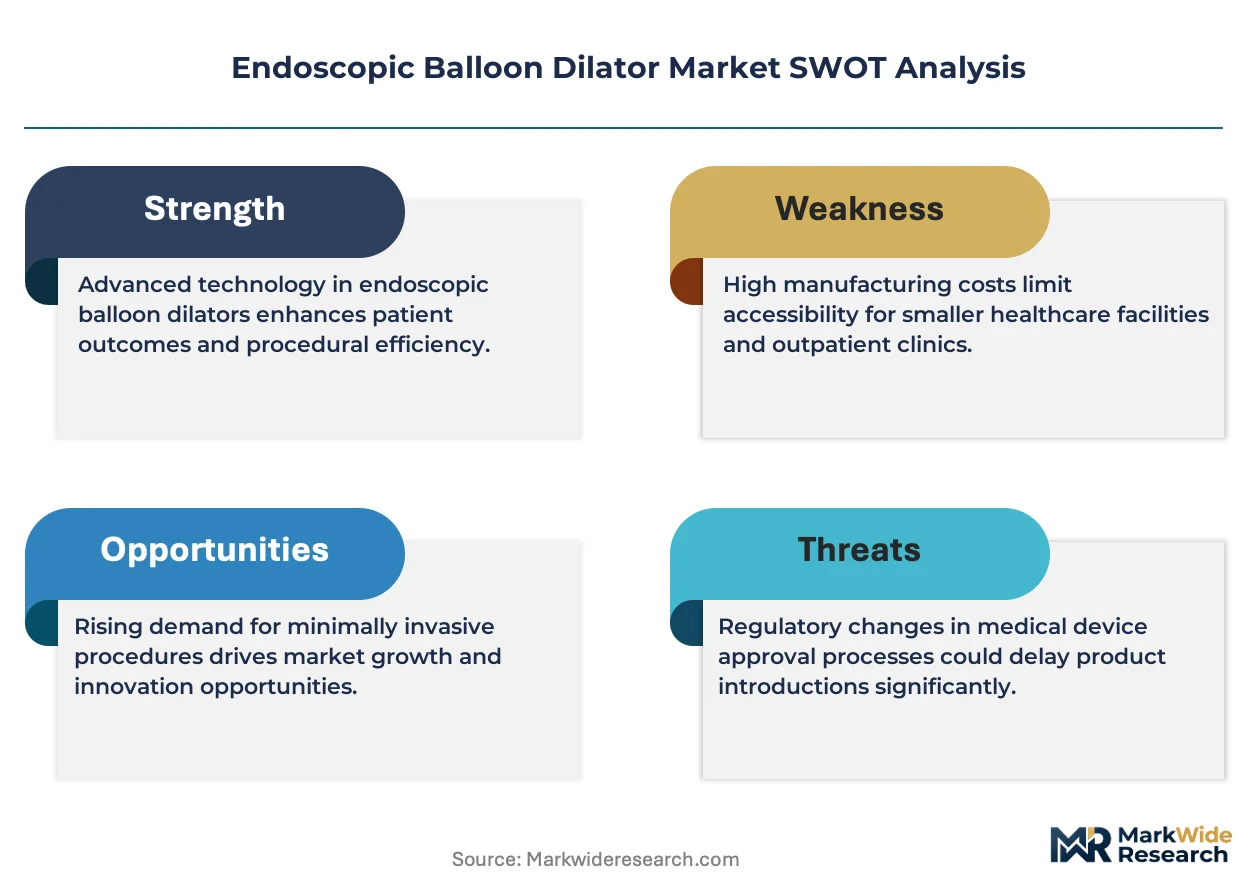
- EU MDR Class IIa conformity pathways:Elevated sterilization validation standards are filtering out marginal suppliers and concentrating procurement among qualified manufacturers with established quality management systems.
- Japan's aging demographic profile:PMDA reimbursement frameworks for therapeutic endoscopy are expanding addressable procedural volumes in achalasia and biliary stricture management.
- Double-lumen catheter architectures:Simultaneous guidewire retention and contrast injection capabilities are reducing fluoroscopy exposure and driving preference in academic medical centers.
Market Restraints
- Polymer feedstock volatility:Polyethylene terephthalate and nylon resin prices fluctuate with petrochemical indices, compressing margin stability for volume manufacturers.
- High-pressure composite supply concentration:Braided metallic layer fabrication for biliary applications depends on a limited supplier base in Germany and Japan.
- FDA 510(k) timeline uncertainty:Predicate device substantiation requirements for novel balloon geometries extend clearance cycles unpredictably.
Strategic Opportunities
- South Korea's MFDS reimbursement evolution:Therapeutic endoscopy coverage expansion creates white space for premium dilator technologies in Seoul's tertiary hospital network.
- Composite-nylon hybrid materials:Convergence of polymer cost scalability with metallic dimensional stability enables next-generation achalasia devices.
- Direct-to-hospital digital procurement:Bypassing distributor markups through vendor-managed inventory platforms is penetrating Germany's hospital purchasing consortia.
Industry Challenges
- Interventional endoscopist training pipelines:Fellowship program capacity constraints limit the pool of physicians qualified for advanced stricture management procedures.
- ISO 10993 biocompatibility testing backlogs:Third-party laboratory queue times for cytotoxicity and sensitization studies delay product launch schedules.
- Legacy endoscope channel incompatibility:Newer balloon catheter diameters require working channel upgrades that strain capital equipment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Balloon Dilator Market |
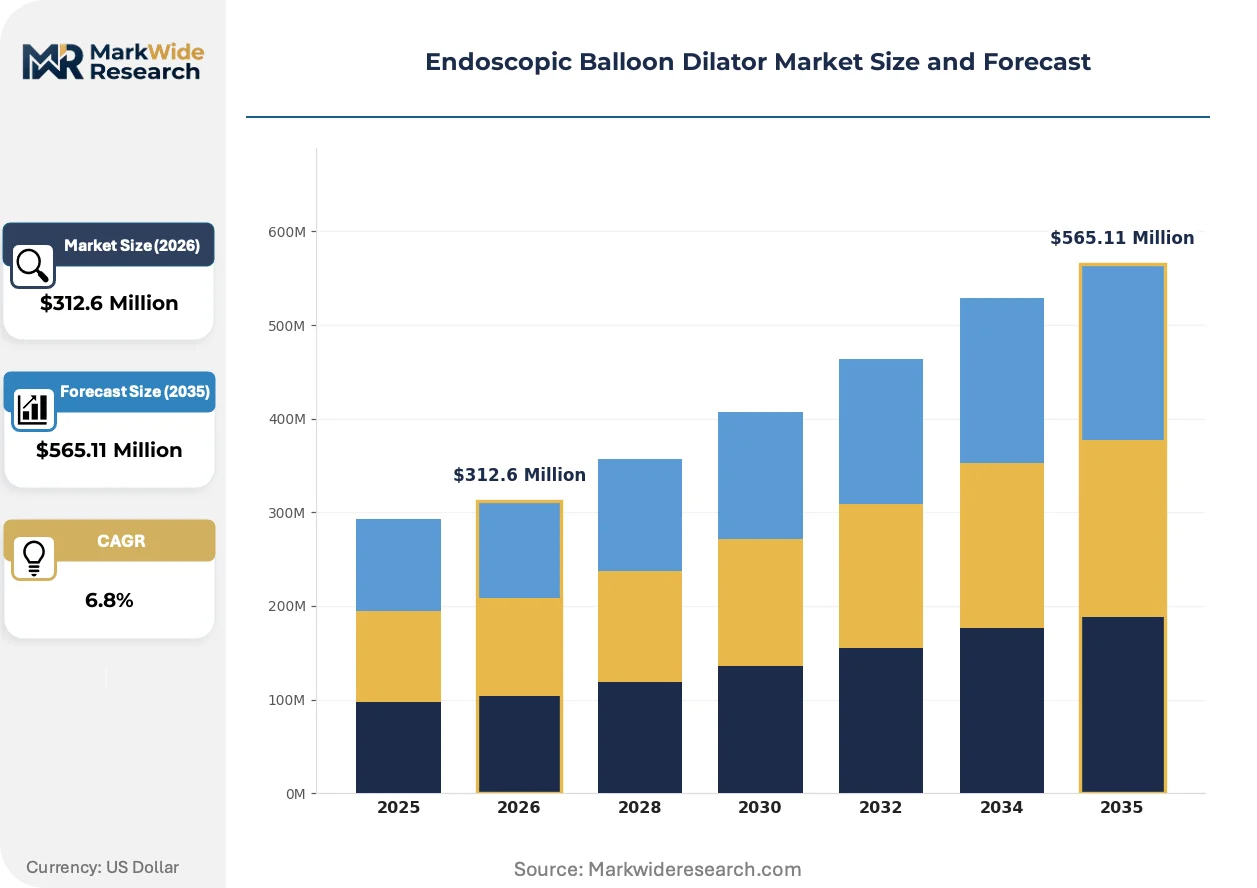
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Double-Lumen, Triple-Lumen, Pediatric End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Practices Application: Gastrointestinal Procedures, Urological Procedures, ENT Procedures, Cardiovascular Interventions Material: Polymer, Metallic, Composite, Others |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Cook Medical, Medtronic, CONMED Corporation, Merit Medical Endotek, Medi-Globe GmbH, Micro-Tech Endoscopy, PanMed US, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Balloon Dilator Market Evolving Landscape
Material science advances and regulatory harmonization pressures are simultaneously elevating performance thresholds and compressing commercialization timelines. Device architectures are fragmenting into indication-specific platforms rather than universal designs.
Composite balloon constructions incorporating braided stainless steel or nitinol layers are decomposing the traditional trade-off between cost and pressure tolerance. Tertiary care centers in the United States and Germany are adopting these platforms for pneumatic dilation in achalasia where radial force consistency determines esophageal perforation risk. The technology is decomposing single-material dominance by enabling premium pricing for mechanical performance that polymer-only designs cannot replicate.
EU MDR technical documentation requirements for Class IIa devices are extending conformity assessment durations and elevating notified body audit intensity. Manufacturers face expanded clinical evidence expectations for biocompatibility and sterilization validation that strain smaller players with limited regulatory affairs capacity. European hospital procurement groups are responding by consolidating supplier panels to reduce qualification overhead, favoring established multinationals with dedicated MDR transition resources.
Hospital purchasing consortia are unbundling device procurement from procedure reimbursement, forcing vendors to justify capital outlays through utilization guarantees rather than list price discounts. Germany's regional hospital alliances and Japan's academic medical center networks are piloting consumption-based contracting where payment ties to confirmed procedural volumes. This behavioral shift is most pronounced in biliary and pancreatic endoscopy where procedure complexity elevates device failure costs.
Endoscopic Balloon Dilator Market Segmentation
Endoscopic balloon dilator procurement channels diverge sharply by procedural setting and reimbursement intensity. Academic medical centers concentrate demand for multi-lumen platforms with advanced guidewire management, while ambulatory settings prioritize cost-scalable single-use configurations. Understanding these channel dynamics enables targeted portfolio positioning across divergent purchasing workflows.
Product Type:
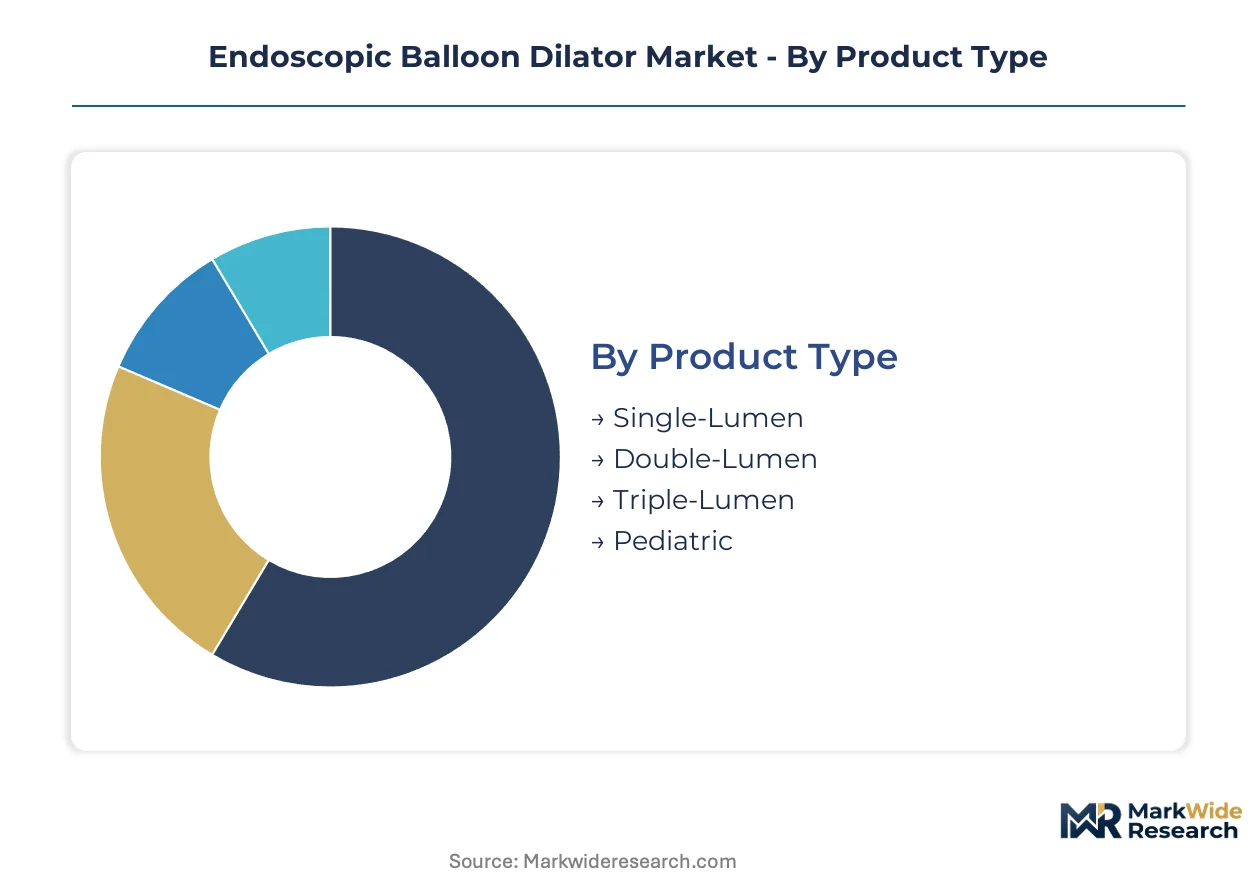
Channel mix varies by lumen count: double-lumen and triple-lumen platforms flow predominantly through hospital GPO contracts with bundled procedure reimbursement, while single-lumen variants penetrate price-sensitive ambulatory channels through distributor networks.
- Single-Lumen:Polyethylene terephthalate construction with burst pressures between 3-8 atmospheres. Demand concentrates in United States ambulatory surgical centers where Medicare reimbursement compression favors disposable economics over feature depth.
- Double-Lumen:Simultaneous guidewire retention and contrast injection capabilities reduce fluoroscopy exposure. Academic medical centers in Germany and Japan absorb premium pricing for procedural efficiency gains in complex biliary stricture management.
- Triple-Lumen:Dedicated irrigation channels enable continuous visualization during high-pressure pneumatic dilation. Specialized achalasia treatment centers in Seoul and Tokyo represent concentrated uptake.
- Pediatric:Smaller French sizes with compliant balloon materials adapted to narrow working channels. Children's hospitals in Boston and Philadelphia anchor procurement volumes for congenital esophageal stricture interventions.
By volume, Single-Lumen leads. By growth pace, Double-Lumen is ahead.
End User:
Procurement authority and reimbursement frameworks determine cost-tier tolerance across settings.
- Hospitals:Integrated delivery networks negotiate multi-year vendor contracts with utilization guarantees. Gastroenterology departments in tertiary centers absorb premium device costs through DRG-based procedure bundling.
- Clinics:Independent gastroenterology practices in the United States face Medicare reimbursement cuts that compress device selection toward standard-tier single-lumen platforms.
- Ambulatory Surgical Centers:CMS site-of-service differentials create margin pressure that favors high-volume, low-unit-cost procurement through distributor consignment models.
- Specialty Practices:Urological and ENT-focused groups in Germany's regional hospital networks access dilators through purchasing consortia with standardized device formularies.
Hospitals generate the highest absolute revenue per account. Ambulatory Surgical Centers expand most quickly as procedure migration accelerates.
Application:
Clinical indication dictates pressure rating requirements and material selection, fragmenting demand across specialty silos.
- Gastrointestinal Procedures:Esophageal and colonic stricture management requires pressure-rated balloons with controlled radial expansion. United States academic centers drive adoption of composite constructions for achalasia pneumatic dilation where perforation risk elevates performance requirements.
- Urological Procedures:Urethral and bladder neck stricture applications demand hydrophilic coatings and low-profile catheter designs. German urology clinics concentrate procurement of metallic-layer platforms for recurrent stricture cases.
- ENT Procedures:Subglottic and tracheal stenosis interventions require small-diameter balloons with precise inflation control. Pediatric otolaryngology units in Tokyo and Osaka represent specialized demand pockets.
- Cardiovascular Interventions:Peripheral vascular and valvular applications utilize high-pressure rated balloons with radiopaque markers. Cardiac catheterization labs in Seoul's tertiary hospitals absorb specialized inventory.
Gastrointestinal Procedures dominate current procedural volume. Urological Procedures gain share fastest as outpatient stricture management protocols expand.
Material:
Supply concentration and sterilization validation burdens stratify manufacturing economics across material classes.
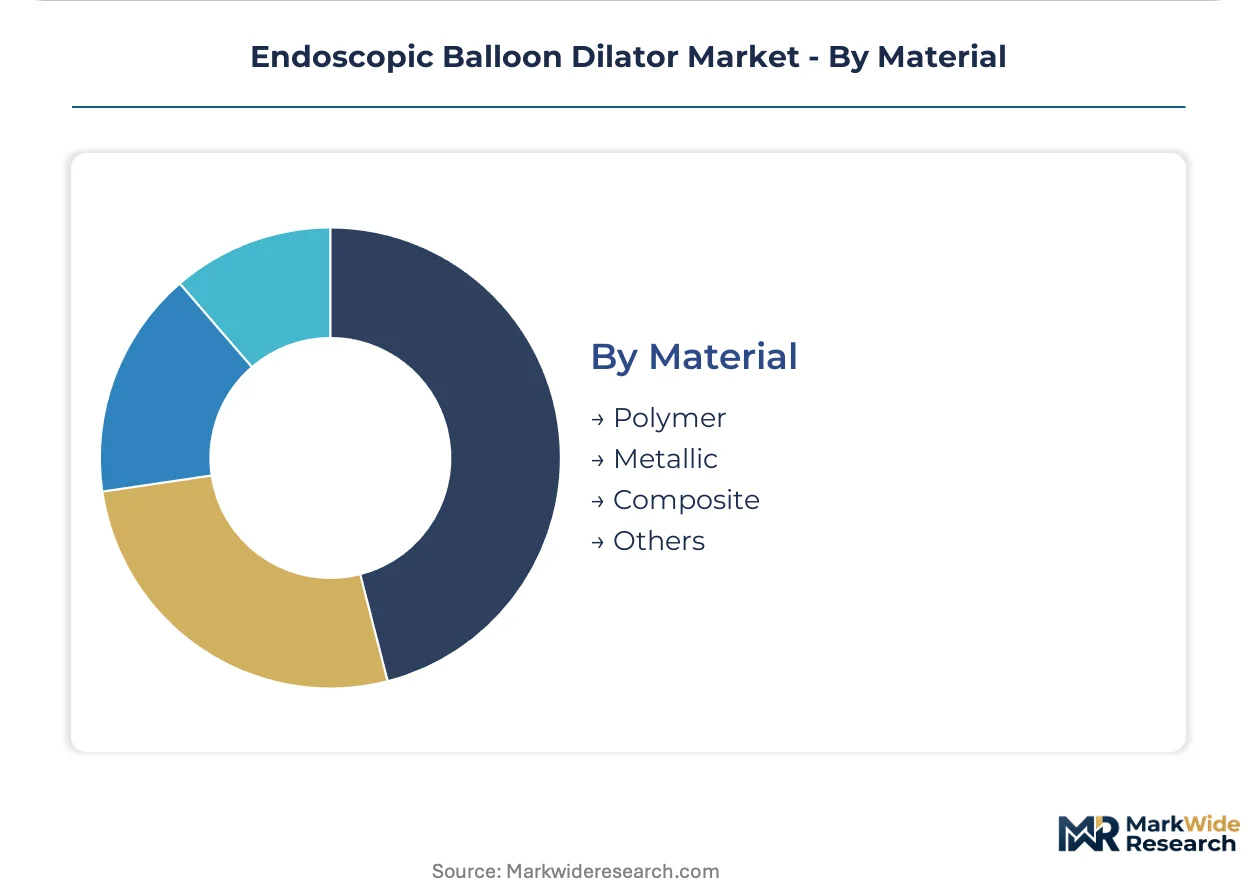
- Polymer:Polyethylene terephthalate and nylon dominate volume production through injection molding scalability. United States and Chinese contract manufacturers supply cost-optimized platforms for high-turnover single-use applications.
- Metallic:Braided stainless steel and nitinol layers enable pressure ratings exceeding 15 atmospheres. German and Japanese suppliers concentrate fabrication capacity for achalasia and biliary specialty devices.
- Composite:Hybrid polymer-metallic constructions balance cost and mechanical performance. Tertiary centers in Germany and the United States pilot adoption for complex stricture cases requiring dimensional stability.
- Others:Silicone and polyurethane variants serve niche pediatric and highly compliant applications. Limited production runs constrain channel penetration to specialized procurement pathways.
Polymer materials lead by unit volume. Composite platforms command the steepest expansion trajectory as performance requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy double-lumen platforms for complex biliary strictures, while German centers favor composite constructions for achalasia pneumatic dilation, and Japanese clinics concentrate triple-lumen uptake in specialized esophageal centers.
United States
Academic medical centers in Boston and Philadelphia drive demand for pediatric and high-pressure composite platforms. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking market access. The Cleveland Clinic and Mayo Clinic anchor procurement volumes for advanced therapeutic endoscopy programs.
Germany
Regional hospital alliances prioritize vendor-managed inventory platforms to bypass distributor markups. EU MDR Class IIa conformity requirements filter procurement toward established quality management systems. The Ruhr-Rhine metropolitan corridor concentrates purchasing consortia for biliary and pancreatic endoscopy devices.
Japan
PMDA reimbursement frameworks for therapeutic endoscopy expand procedural volumes in achalasia and stricture management. METI standards guide biocompatibility validation for polymer-metallic hybrid constructions. Tokyo and Osaka academic centers absorb premium pricing for triple-lumen irrigation capabilities.
South Korea
MFDS reimbursement evolution creates white space for premium dilator technologies in Seoul's tertiary hospital network. The national health insurance system increasingly covers therapeutic endoscopy procedures. Seoul National University Hospital and Asan Medical Center pilot consumption-based contracting models.
China
NMPA regulatory harmonization accelerates localization requirements for imported device platforms. Domestic manufacturers scale polyethylene terephthalate production for cost-optimized single-lumen applications. Shanghai and Beijing medical device clusters concentrate contract manufacturing capacity for regional supply.
Endoscopic Balloon Dilator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital GPO contracts through bundled procedure ecosystems while specialists capture niche indication segments. The market structure rewards vertical integration into physician education programs and sterilization validation capabilities. Three archetypes dominate: integrated endoscopy platform vendors, catheter specialization houses, and regional contract manufacturers. Competitive moves concentrate on M&A for regulatory capacity and strategic partnerships for distribution reach.
Among integrated platform vendors, Boston Scientific Corporation and Olympus Corporation exemplify the ecosystem approach, anchoring hospital loyalty through visualization and therapeutic tool integration. Cook Medical occupies a specialist position within the catheter fabrication tier, representing deep narrow focus on controlled radial expansion profiles. These three names illustrate how competitive boundaries redraw around training infrastructure and quality system depth rather than device economics alone.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Cook Medical |
| Medtronic |
| CONMED Corporation |
| Merit Medical Endotek |
| Medi-Globe GmbH |
| Micro-Tech Endoscopy |
| PanMed US |
| Others |
Value Network & Pricing Analysis
Injection molding scale economies in Chinese and United States contract manufacturing facilities compress unit costs for polyethylene terephthalate platforms while elevating price floors for composite constructions requiring German or Japanese metallic braiding capacity. This asymmetry stratifies procurement tiers: volume buyers access single-lumen disposables through distributor consignment, while academic centers absorb premiums for multi-lumen architectures with controlled radial expansion profiles.
Pricing Analysis
Long-term offtake agreements anchor hospital GPO procurement for double-lumen and triple-lumen platforms, with spot purchasing limited to emergency replenishment of single-lumen inventory. Price differentiation rests on ISO 13485 certification tier and guidewire management complexity, with FDA 510(k) predicate device status commanding additional premiums. Cost compression in standard-tier single-lumen segments intensifies as Medicare reimbursement compression forces ambulatory surgical centers toward distributor private-label alternatives. Independent gastroenterology clinics in the United States exhibit highest price sensitivity, while German academic medical centers absorb premium positioning for EU MDR Class IIa validated platforms.
Supply Chain Analysis
Germany and Japan anchor fabrication capacity for braided stainless steel and nitinol layers enabling pressure ratings above 15 atmospheres, while China and the United States scale polyethylene terephthalate injection molding for high-volume single-use applications. Raw material sourcing draws from petrochemical feedstocks for polymer resins and specialty metal suppliers for composite reinforcements. Single-source vulnerability concentrates in metallic braiding equipment where German and Japanese OEMs control precision winding technology. Distribution runs through hospital purchasing consortia in Germany, GPO contracts in the United States, and regional distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation requirements and composite material advances are accelerating capability gaps between integrated platform vendors and marginal suppliers. This regulatory-technological inflection compresses commercialization timelines while elevating sterilization validation burdens.
For Market Incumbents: Compound ecosystem stickiness by embedding balloon dilator procurement within bundled endoscopy platform contracts spanning visualization, therapeutic tools, and physician education programs. Anchor hospital loyalty through vendor-managed inventory platforms that bypass distributor markups in Germany's regional alliances. Prioritize backward integration into metallic braiding capacity to secure supply continuity for high-pressure achalasia devices.
For New Entrants and Emerging Players: FDA 510(k) predicate device pathways offer fastest clearance velocity for novel balloon geometries targeting underserved pediatric stricture segments. White space concentrates in South Korea's MFDS reimbursement evolution, where therapeutic endoscopy coverage expansion precedes established vendor lock-in. Seoul's tertiary hospital network represents the most penetrable geography for premium double-lumen platforms. Deploy direct-to-hospital digital procurement to circumvent incumbent distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catheter specialization houses with deep ISO 13485 quality systems and established sterilization validation infrastructure. Long-term viability over a multi-year horizon favors targets with dedicated MDR transition resources and physician education program assets. Acquisition priority rests on mid-tier manufacturers with composite material capabilities but limited regulatory affairs capacity. Monitor PMDA reimbursement framework decisions for therapeutic endoscopy as the critical inflection signal for Asia-Pacific premium device adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Conformity Pathway | Accelerates market concentration by filtering procurement toward established quality management systems. |
| Composite-Nylon Hybrid Development | Enables next-generation achalasia devices with dimensional stability under inflation stress. |
| Hospital System Partnership | Secures utilization guarantees through consumption-based contracting in Germany's regional alliances. |
| Physician Education Program Expansion | Addresses interventional endoscopist training bottlenecks that constrain procedural capacity. |
| Direct-to-Hospital Digital Procurement | Bypasses distributor markups through vendor-managed inventory platforms penetrating purchasing consortia. |
Research Methodology
Initial hypotheses were tested against primary input from interventional gastroenterologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers, then refined through secondary validation across FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, application, material, and geography dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation granularity spanning lumen count configurations, pressure rating tiers, and regional regulatory clusters. CAGRs were derived from procedure volume elasticity to aging demographic profiles and reimbursement coverage expansion. Forecast inputs incorporated PMDA framework evolution, MFDS coverage decisions, and polymer feedstock price trajectories.
Decision-makers should treat outputs as directional under base assumptions of stable FDA 510(k) timeline predictability and sustained EU MDR notified body capacity; material deviation in regulatory processing velocity or metallic braiding supply continuity would warrant model refresh. Recalibration cycles align with material shifts in reimbursement framework decisions and sterilization validation standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Global Endoscopes Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
US Colonic Stents Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Endoscopy Fluid Management Systems Market