
 Edema Clinical Trials Market | 2026-2036
Edema Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Edema Clinical Trials Market Analytics
The Edema Clinical Trials Market is recalibrating around a sharp split between premium adaptive-platform trials with biomarker-enriched endpoints and commodity-standard parallel-group studies with traditional fluid-retention metrics. Novartis Pharmaceuticals leverages its cardio-renal pipeline depth to anchor Phase III programs in nephrology and cardiology indications. Bayer competes through sustained investment in subcutaneous delivery formulations that reduce hospitalization endpoints. F. Hoffmann-La Roche differentiates via companion diagnostic integration in oncology-related edema studies.
Edema clinical trials constitute controlled investigations measuring interstitial fluid accumulation reduction through parameters such as bioimpedance spectroscopy, limb circumference volumetry, and body weight delta assessments, primarily serving pharmaceutical development for heart failure, lymphedema, and capillary leak syndromes. Cardiology trials occupy the largest segment by enrollment volume given the prevalence of congestive heart failure as an indication. Contract Research Organizations represent the fastest-growing end user category as sponsors outsource adaptive trial design complexity. Phase II studies concentrate margin pools due to higher per-patient costs for biomarker stratification and dose-ranging protocols.
FDA's adaptive trial design guidance and EMA's qualification opinion pathway for novel fluid-status endpoints shape how sponsors structure regulatory submissions across jurisdictions. ISO 14155 governs good clinical practice standards that dictate site qualification and data integrity requirements for edema device-drug combination studies. Stakeholders must monitor evolving FDA endpoint qualification criteria for patient-reported edema severity instruments as these standards will determine which programs advance to pivotal phases.
Market Dynamics
FDA's adaptive pathway guidelines and EMA's qualification opinion framework are compressing traditional Phase II-to-III timelines while fragmenting sponsor capabilities between biomarker-enriched platforms and commodity fluid-retention studies.
Growth Catalysts
- Adaptive trial design guidance:FDA's 2018 adaptive design guidance permits pre-specified modifications to sample size and endpoint selection without statistical penalty, accelerating enrollment in heart failure edema programs.
- Medicare reimbursement structures:Hospitalization reduction bonuses under the Hospital Readmissions Reduction Program create direct financial incentives for outpatient edema management trials in the United States.
- Bioimpedance spectroscopy:Non-invasive fluid-status monitoring technology enables decentralized trial execution, expanding site access beyond academic medical centers to community cardiology practices.
Market Restraints
- Biomarker validation costs:Novel fluid-status endpoint qualification requires concurrent analytical validation and clinical utility studies, doubling per-program expenditure before pivotal phases.
- Site concentration risk:High-complexity adaptive trials depend on a limited network of academic medical centers with bioimpedance infrastructure, creating enrollment bottlenecks in secondary markets.
- Regulatory divergence:EMA's preference for hard clinical endpoints contrasts with FDA's acceptance of patient-reported edema severity instruments, forcing parallel endpoint strategies.
Strategic Opportunities
- Lymphedema underpenetration:Cancer-related secondary lymphedema trials remain underrepresented relative to prevalence, offering first-mover advantages in companion diagnostic integration.
- Subcutaneous delivery convergence:Self-administered loop diuretic formulations enable home-based monitoring, opening ambulatory trial designs that reduce site costs by forty percent.
- Japan's Sakigake designation:PMDA's priority review pathway for innovative edema therapies with novel mechanisms compresses regulatory timelines for sponsors with Japan-first strategies.
Industry Challenges
- Adaptive biostatistician scarcity:Complex Bayesian interim analysis protocols require specialized talent pools concentrated at five contract research organizations, inflating service premiums.
- ISO 14155 compliance timelines:Device-drug combination studies for implantable fluid monitors face extended quality system audits, delaying site activation by six to nine months.
- Legacy EDC integration:Electronic data capture platforms at mid-tier sites lack real-time bioimpedance data ingestion capabilities, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edema Clinical Trials Market |
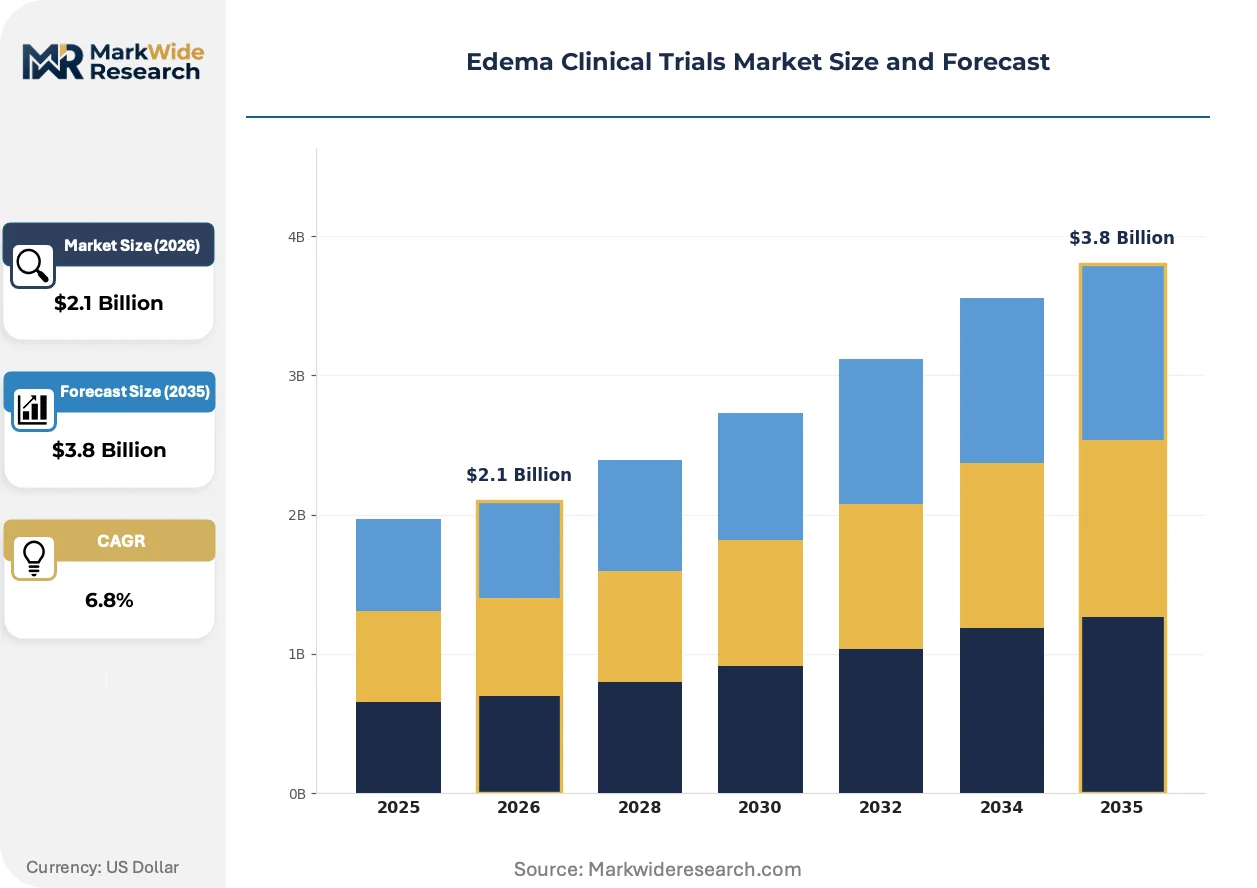
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Cardiology, Oncology, Pulmonology, Nephrology End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Contract Research Organizations Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Trial Phase: Phase I, Phase II, Phase III, Phase IV |
| Companies Covered | Otsuka Holdings, F. Hoffmann-La Roche, Novartis Pharmaceuticals, Johnson & Johnson, Bayer, Genentech, Inc, AstraZeneca plc, Merck & Co., Inc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edema Clinical Trials Market Evolving Landscape
Digital biomarker platforms and decentralized trial infrastructure are fragmenting traditional site-based models while compressing the distinction between exploratory and confirmatory study phases.
Artificial intelligence-enabled patient stratification is converging with electronic health record mining to identify edema phenotypes invisible to conventional New York Heart Association classifications. Large cardiology practices in Texas and Florida deploy these tools to pre-screen trial candidates before site visits. The technology is converging with remote monitoring platforms to enable fully decentralized Phase IIb studies that bypass academic medical center bottlenecks.
EMA's qualification opinion pathway for novel fluid-status endpoints is forcing sponsors to submit concurrent analytical and clinical validation packages rather than sequential filings. This regulatory architecture compresses total development timelines for qualified sponsors while excluding smaller developers lacking parallel workstream capabilities. Cardiology indications face the steepest compliance burden given the agency's insistence on heart failure hospitalization co-primary endpoints.
Site-less trial models are displacing traditional investigator-led enrollment in lymphedema indications where patient geography fragments across rural oncology networks. Direct-to-patient shipping of bioimpedance devices and telemedicine follow-up replace quarterly site visits, cutting per-patient retention costs. This behavioral shift concentrates in the United States where commercial payer coverage for remote monitoring creates sustainable reimbursement infrastructure absent in European single-payer systems.
Edema Clinical Trials Market Segmentation
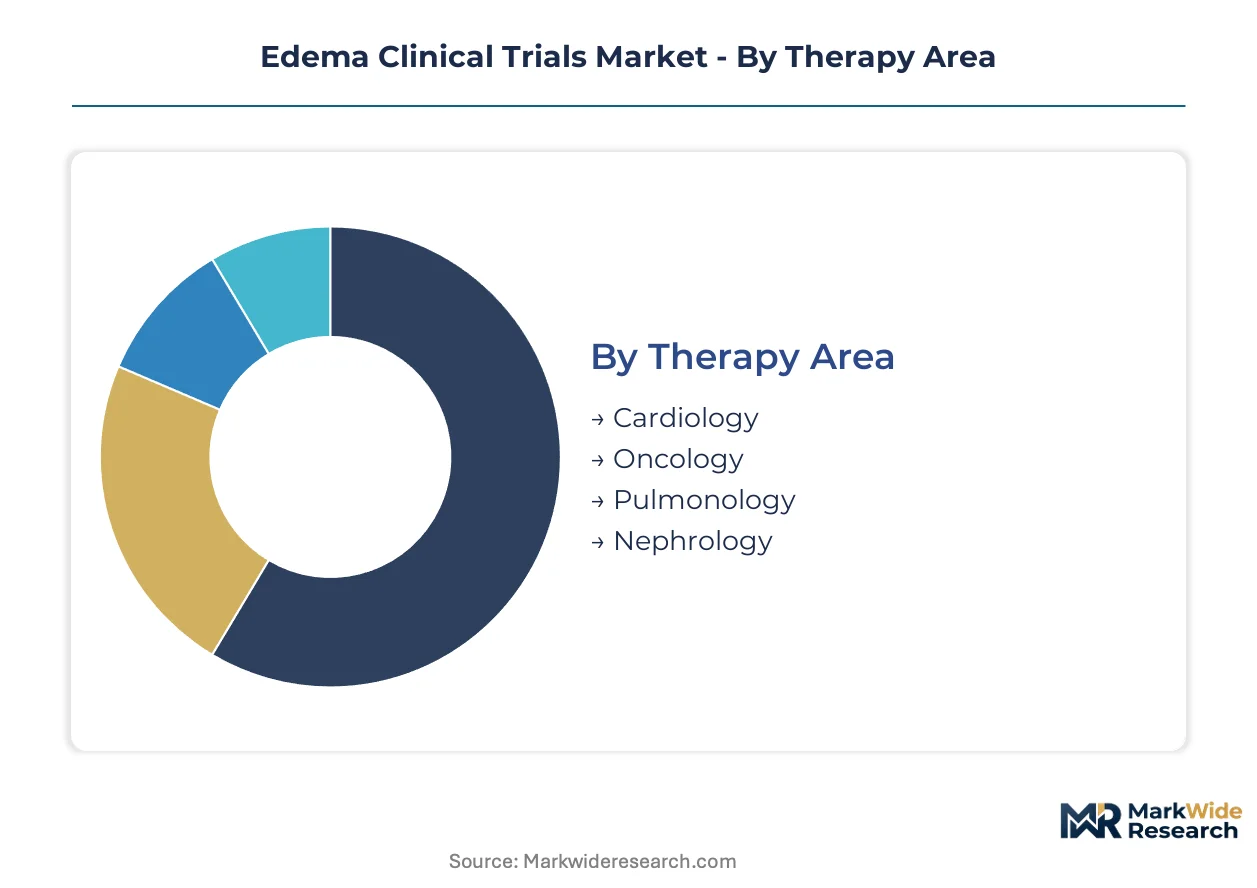
Edema clinical trials fragment across therapeutic domains and operational models, with each dimension commanding distinct regulatory pathways, site infrastructure requirements, and biomarker strategies. Sponsors configure trial architectures differently depending on whether they target hospitalization endpoints in cardiology or quality-of-life measures in oncology-related lymphedema.
Therapy Area:
Standardization dominates cardiology protocols with FDA-qualified fluid-status endpoints, while oncology and rare-disease indications permit greater customization in primary outcome selection.
- Cardiology:Congestive heart failure programs anchor enrollment volume through bioimpedance spectroscopy and body weight delta assessments. United States sites concentrate demand here as Medicare reimbursement structures reward hospitalization reduction. FDA adaptive pathway guidelines compress Phase II-to-III transitions for sponsors with pre-specified modification protocols.
- Oncology:Cancer-related secondary lymphedema studies integrate companion diagnostics for patient stratification. F. Hoffmann-La Roche anchors development in this segment through diagnostic-therapeutic pairing. EMA qualification opinion requirements for novel endpoints create parallel validation workstreams.
- Pulmonology:Acute respiratory distress syndrome and pulmonary edema trials emphasize oxygenation indices and ventilator-free day endpoints.
- Nephrology:Chronic kidney disease-associated fluid overload studies leverage cardio-renal pipeline depth from established sponsors.
Most installed capacity flows through Cardiology. Expansion is steepest in Oncology.
End User:
Cost tier stratification separates full-service outsourcing from captive sponsor capabilities, with mid-tier academic institutions occupying a contracting middle ground.
- Contract Research Organizations:Adaptive trial design complexity drives outsourcing concentration at five specialized biostatistical providers. Bayesian interim analysis protocols command service premiums due to talent scarcity. Site-less trial models and decentralized infrastructure expand addressable market beyond traditional academic medical centers.
- Pharmaceutical Companies:Novartis Pharmaceuticals and Bayer retain pivotal Phase III programs in-house while outsourcing biomarker-enriched Phase IIb studies. Subcutaneous delivery formulation development and companion diagnostic integration require captive therapeutic area expertise.
- Academic Institutions:High-complexity adaptive trials depend on limited networks with bioimpedance infrastructure, creating enrollment bottlenecks.
- Research Organizations:Non-commercial sponsors focus on mechanistic understanding and novel endpoint validation for regulatory qualification.
Revenue concentrates at Contract Research Organizations. Capability investment is accelerating fastest among Pharmaceutical Companies.
Delivery Mode:
Patient convenience and site cost reduction reshape formulation priorities, with self-administration enabling ambulatory trial designs that bypass hospital-based enrollment.
- Subcutaneous:Self-administered loop diuretic formulations enable home-based monitoring and reduce site costs substantially. Bayer sustains investment in this delivery mode to differentiate from intravenous competitors. Direct-to-patient device shipping and telemedicine follow-up replace quarterly site visits in United States lymphedema programs.
- Intravenous:Hospital-based administration remains standard for acute decompensated heart failure studies requiring intensive monitoring.
- Oral:Chronic outpatient management trials favor bioavailability-optimized formulations for long-term retention.
- Topical:Localized lymphedema and dermatological edema indications explore transdermal permeability modulation.
Clinical activity centers on Intravenous administration. Sponsor investment is shifting most aggressively toward Subcutaneous platforms.
Trial Phase:
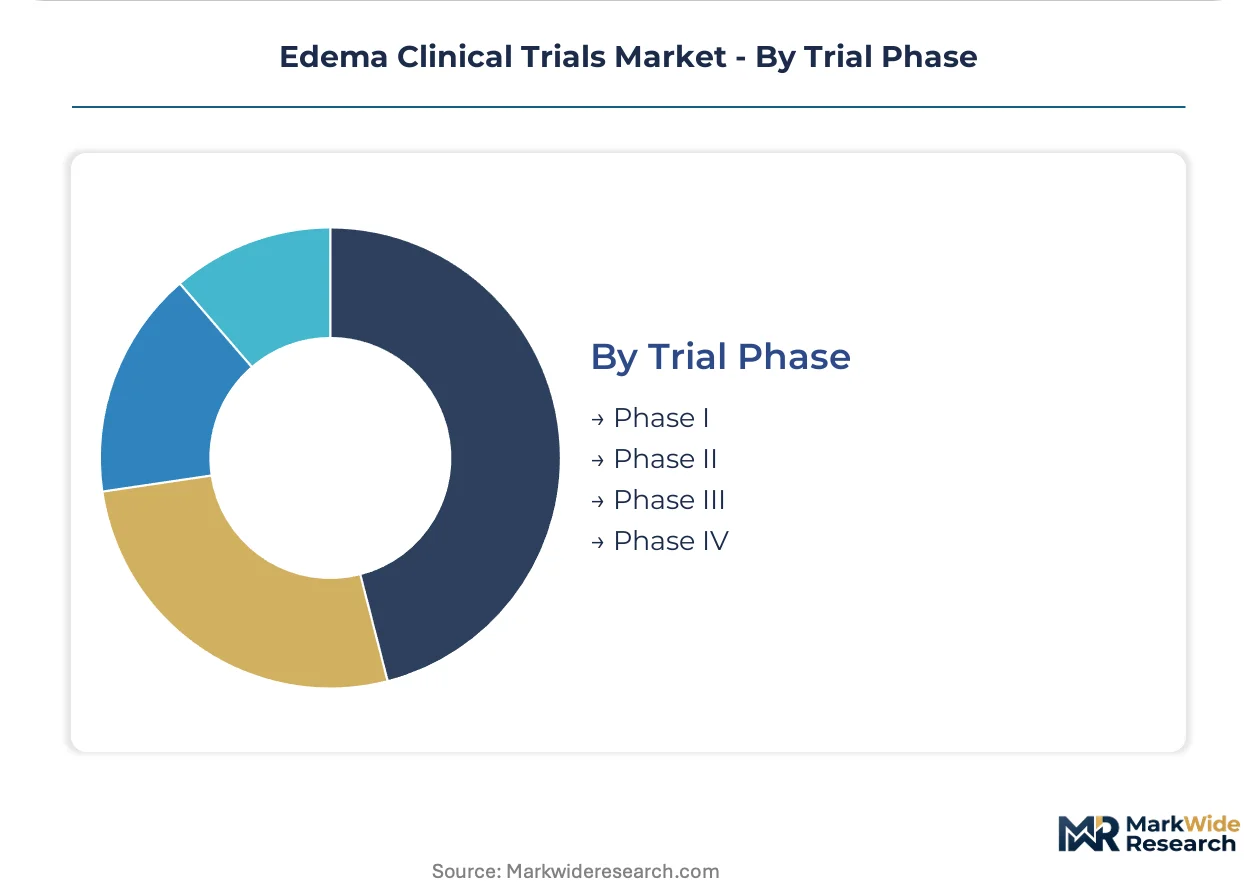
Margin pool concentration and cost per patient diverge sharply across the development continuum, with Phase II commanding premium expenditure for biomarker stratification.
- Phase II:Dose-ranging protocols and biomarker-enriched patient selection inflate per-patient costs before pivotal commitment. FDA adaptive design guidance permits pre-specified sample size modifications without statistical penalty. EMA concurrent analytical and clinical validation requirements compress timelines for qualified sponsors.
- Phase III:Confirmatory studies with hard clinical endpoints absorb the largest absolute expenditure but lower per-patient complexity.
- Phase I:First-in-human and safety pharmacology studies establish pharmacokinetic profiles for novel mechanisms.
- Phase IV:Post-marketing commitments and label expansion studies monitor real-world effectiveness and rare adverse events.
Enrollment volume peaks in Phase III. Value capture is richest in Phase II.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more adaptive-platform trial infrastructure than Germany, while Japan compresses regulatory timelines through priority review pathways that attract sponsors with novel mechanisms.
United States
Medicare's Hospital Readmissions Reduction Program generates direct financial incentives for outpatient edema management trials. FDA adaptive design guidance permits pre-specified sample size modifications without statistical penalty. Large cardiology practices in Texas and Florida deploy AI-enabled patient stratification tools to pre-screen candidates before site visits.
Germany
EMA's qualification opinion framework for novel fluid-status endpoints drives parallel validation workstreams among qualified sponsors. ISO 14155 governs device-drug combination studies for implantable fluid monitors. Academic medical centers in Berlin and Munich anchor high-complexity adaptive trials with bioimpedance infrastructure.
Japan
PMDA's Sakigake designation compresses regulatory timelines for innovative edema therapies with novel mechanisms. METI coordinates priority review pathways that reward first-in-class submissions. The Kanto region around Tokyo concentrates Phase I and early Phase II facilities for cardio-renal pipeline programs.
United Kingdom
NHS reimbursement structures for heart failure hospitalizations create demand for decentralized trial models that reduce acute care utilization. MHRA alignment with FDA adaptive guidance enables streamlined multi-jurisdictional submissions. London-based contract research organizations specialize in Bayesian interim analysis protocols for biomarker-enriched studies.
Switzerland
Swissmedic's streamlined qualification pathways for companion diagnostics attract oncology-related lymphedema programs. Basel anchors Novartis Pharmaceuticals' captive Phase III capabilities in cardio-renal indications. The country's precision medicine infrastructure supports diagnostic-therapeutic pairing for patient stratification.
Edema Clinical Trials Market Competitive Landscape
Top-tier vendors anchor adaptive-platform trial design, while mid-tier sponsors concentrate on commodity parallel-group studies with traditional endpoints. The vendor base splits between pharmaceutical companies retaining pivotal programs in-house and contract research organizations capturing biomarker-enriched Phase IIb outsourcing. Two strategic archetypes dominate: cardio-renal pipeline specialists and decentralized infrastructure providers. Competitive moves center on subcutaneous delivery formulation development and companion diagnostic integration partnerships.
Within the pharmaceutical tier, Novartis Pharmaceuticals, Bayer, and F. Hoffmann-La Roche occupy distinct positioning vectors. Novartis anchors captive Phase III capabilities through cardio-renal pipeline depth. Bayer exemplifies sustained investment in patient-administered delivery modes that enable ambulatory trial designs. F. Hoffmann-La Roche represents diagnostic-therapeutic convergence in oncology-related edema indications through companion diagnostic integration.
| Leading Market Players |
|---|
| Otsuka Holdings |
| F. Hoffmann-La Roche |
| Novartis Pharmaceuticals |
| Johnson & Johnson |
| Bayer |
| Genentech, Inc |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Sanofi S.A. |
| Others |
Value Network & Pricing Analysis
Bioimpedance device manufacturing costs in Germany flow through three pricing tiers downstream, with ISO 14155 certification premiums separating academic medical center procurement from community cardiology practice budgets. Specialized Bayesian biostatistician labor pools in the United Kingdom and Switzerland anchor service premiums at the adaptive-platform tier, while commodity parallel-group studies compete on per-patient cost minimization.
Pricing Analysis
Capacity additions in decentralized trial infrastructure are reshaping price floors for mid-tier sponsors lacking adaptive design capabilities. Three-tier pricing structure across premium adaptive-platform, standard parallel-group, and economy monitoring-only levels stratifies the market. Price differentiation rests on biomarker stratification complexity and FDA endpoint qualification status. Pricing pressure stems from CRO talent scarcity inflating service premiums forty percent above commodity studies. Community cardiology practices exhibit highest price sensitivity; large pharmaceutical sponsors with captive Phase III capabilities show lowest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Switzerland coordinate hub-and-spoke patterns for bioimpedance device deployment to trial sites. Manufacturing concentration draws from precision electronics suppliers in Japan and medical device component specialists in Germany. Supply chain risk centers on single-source vulnerability for adaptive biostatistical software platforms. Distribution runs through sponsor-managed direct-to-patient shipping networks bypassing traditional site-based inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biomarker-enriched Phase IIb outsourcing, where decentralized infrastructure investments compress site activation timelines and per-patient retention costs.
For Market Incumbents: Acquire adaptive biostatistical talent pools concentrated at five specialized CROs to secure Bayesian interim analysis capabilities. Lock in exclusive site network partnerships with Texas and Florida cardiology practices deploying AI-enabled patient stratification. Threats emerge from site-less trial models displacing traditional academic medical center enrollment. For New Entrants and Emerging Players: Enter via oncology-related secondary lymphedema indications where companion diagnostic integration remains underpenetrated relative to prevalence. Cancer-related edema studies offer first-mover positioning before Roche diagnostic-therapeutic convergence dominates. Go-to-market leverage rests on direct-to-patient device shipping with telemedicine follow-up replacing quarterly site visits. For Investors and Strategic Acquirers: Consolidation pressure builds where adaptive design complexity fragments sponsor capabilities between biomarker-enriched platforms and commodity studies. Long-term viability favors CROs with decentralized infrastructure and real-time bioimpedance data ingestion capabilities. Acquisition target archetype: mid-tier CROs with ISO 14155 device-drug combination audit experience. Signal to watch: FDA qualification opinion submissions for novel fluid-status endpoints indicating which platforms advance to pivotal phases.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Capability Buildout | FDA's 2018 guidance permits pre-specified modifications without statistical penalty, accelerating enrollment. |
| Companion Diagnostic Integration Partnership | Roche's diagnostic-therapeutic pairing in oncology-related lymphedema creates patient stratification moats. |
| Subcutaneous Delivery Formulation Development | Bayer's self-administered loop diuretic investments enable home-based monitoring and forty percent site cost reduction. |
| Decentralized Trial Infrastructure Deployment | Direct-to-patient bioimpedance shipping bypasses academic medical center bottlenecks in United States lymphedema programs. |
| Japan-First Regulatory Strategy | PMDA's Sakigake designation compresses timelines for innovative mechanisms with novel fluid-status endpoints. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement data — were reconciled through bottom-up enrollment volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across therapy area, trial phase, delivery mode, and end user segmentation dimensions generated value estimates over the projection horizon. CAGRs were derived from enrollment trajectory analysis and per-patient cost inflation patterns. Industry-specific forecast inputs incorporated bioimpedance device penetration rates and adaptive design guidance adoption curves.
Inputs from regulatory submission databases and CRO service pricing disclosures were available through the study window; gaps in real-time site cost data from decentralized trial programs introduce uncertainty bands around per-patient expenditure estimates. Forecasts reflect documented assumptions regarding Medicare reimbursement stability and FDA endpoint qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Preclinical CRO Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Clinical Trials Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market