
 Endoscopy Visualization Systems Market | 2026-2036
Endoscopy Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Visualization Systems Market Intelligence
Modular system bundling is broadening buyer choice across the endoscopy visualization landscape. Olympus Corporation leverages its integrated platform architecture to anchor premium hospital contracts in Japan and North America. KARL STORZ SE & Co. KG competes through rigid endoscope specialization and in-house production of optical components. FUJIFILM Holdings Corporation extends its imaging sensor expertise from photography into 4K surgical visualization, positioning against pure-play medical device rivals.
Endoscopy visualization systems comprise camera heads, video processors, light sources, and display monitors that convert optical or digital signals into real-time anatomical imagery during minimally invasive procedures. These systems typically operate at resolutions from 1080p to 4K with LED or xenon illumination, serving primarily to enable diagnostic inspection and surgical intervention through natural orifices or small incisions. Flexible endoscopes dominate procedure volume in gastroenterology and pulmonology, where maneuverability through tortuous anatomy commands the largest installed base. High-definition imaging and 3D visualization represent the fastest-expanding technology segments, as surgical precision requirements intensify in orthopedic and urological applications. Wireless endoscopes remain nascent but attract development investment for their potential to eliminate cable sterilization failures and reduce cross-contamination risk in outpatient settings.
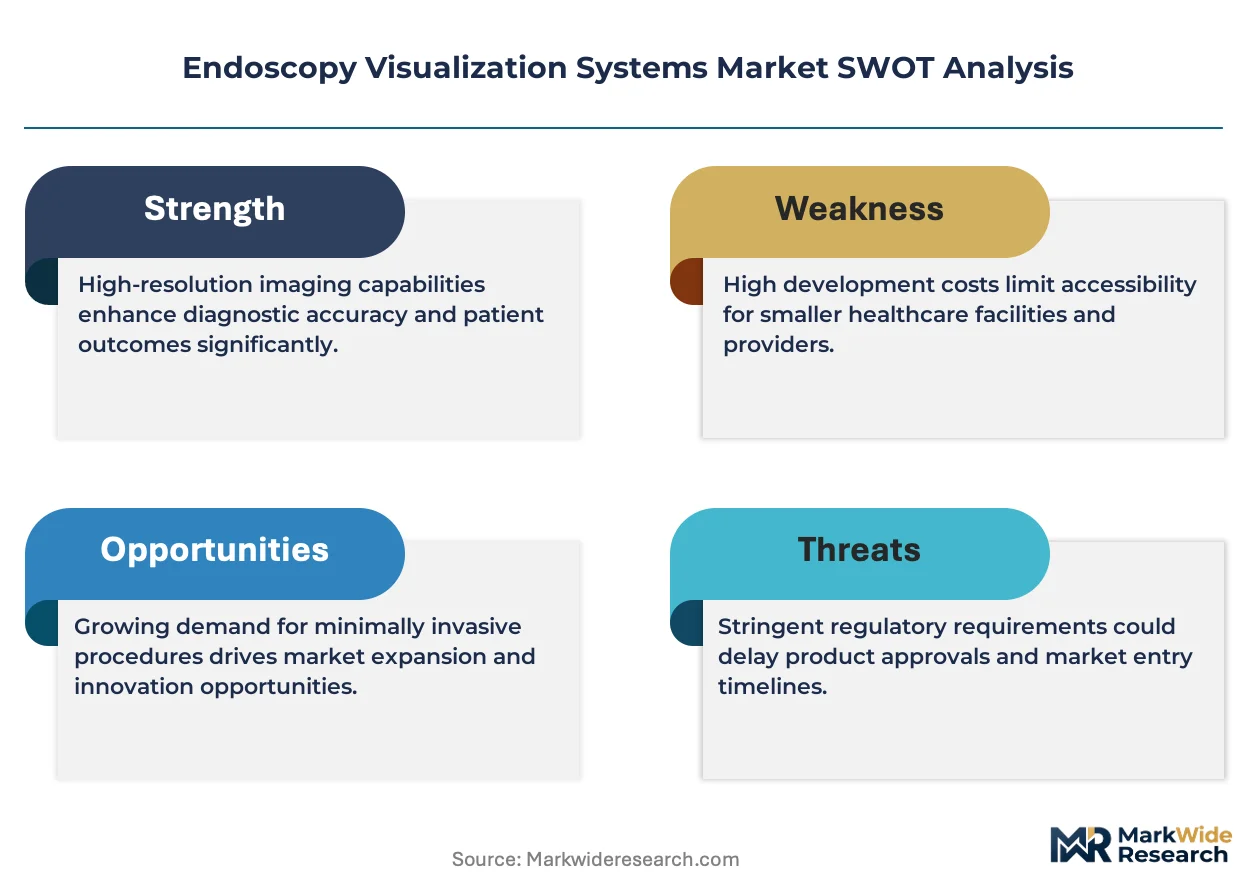
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for visualization system manufacturers. ISO 13485 quality management certification functions as a baseline market access threshold across all major jurisdictions, with notified body audits intensifying under strengthened European oversight. Stakeholders must monitor how software-as-a-medical-device classifications affect video processing algorithms and AI-enhanced imaging features that increasingly differentiate competitive platforms.
Market Dynamics
EU MDR sterilization traceability mandates are compressing hospital procurement cycles toward single-use and disposable visualization components, forcing manufacturers to reengineer optical cable architectures and video processor form factors for rapid turnover rather than decades-long amortization.
Growth Catalysts
- EU MDR Technical Documentation Requirements:Stricter sterilization validation protocols for reusable endoscopes are accelerating hospital replacement of aging fiber-optic stacks with integrated digital platforms that embed automated cleaning cycle counters.
- Japan's Super-Aged Society Medical Infrastructure:METI subsidies for minimally invasive surgical suites in rural prefectures are expanding installed bases of 4K visualization systems in secondary care facilities previously limited to standard-definition equipment.
- CMOS Sensor Cost Collapse:Semiconductor foundry capacity expansion for smartphone camera modules is driving down 4K medical imaging sensor prices, enabling mid-tier manufacturers to field competitive visualization platforms without captive optical component production.
Market Restraints
- Xenon Lamp Supply Concentration:German and Japanese specialty gas suppliers control 80% of medical-grade xenon production, exposing light source manufacturers to input cost volatility and forced substitution toward LED architectures with inferior color rendering indices.
- FDA 510(k) Predicate Device Pathway:Reliance on substantial equivalence determinations for video processor clearances creates regulatory friction for AI-enhanced imaging features that lack established predicates, delaying commercialization of real-time polyp detection algorithms.
- Flexible Endoscope Durability Ceiling:Material fatigue in insertion tube braided wiring limits reusable flexible scopes to 300-500 sterilization cycles, capping equipment lifetime value and compressing hospital capital planning horizons.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentive structures for domestic manufacturing are creating white space for regional assembly of visualization system components previously imported from German or Japanese suppliers.
- Wireless Capsule Endoscopy Convergence:Integration of ultra-low-power image transmission with 4K sensor miniaturization is enabling battery-operated capsule platforms that eliminate sterilization workflows entirely in outpatient gastroenterology.
- US Hospital Outpatient Department Expansion:CMS site-of-service payment differentials are driving ambulatory surgical center construction, creating demand for compact visualization systems with reduced footprint and simplified IT integration requirements.
Industry Challenges
- Cross-Functional Talent Scarcity:Recruiting engineers with simultaneous expertise in optical design, embedded software, and biocompatibility testing extends product development timelines and inflates R&D compensation costs.
- Legacy Video Processor Interoperability:Hospital-installed bases of proprietary camera head connectors and non-standard digital output protocols create integration friction for multi-vendor surgical suites seeking best-of-breed component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Visualization Systems Market |
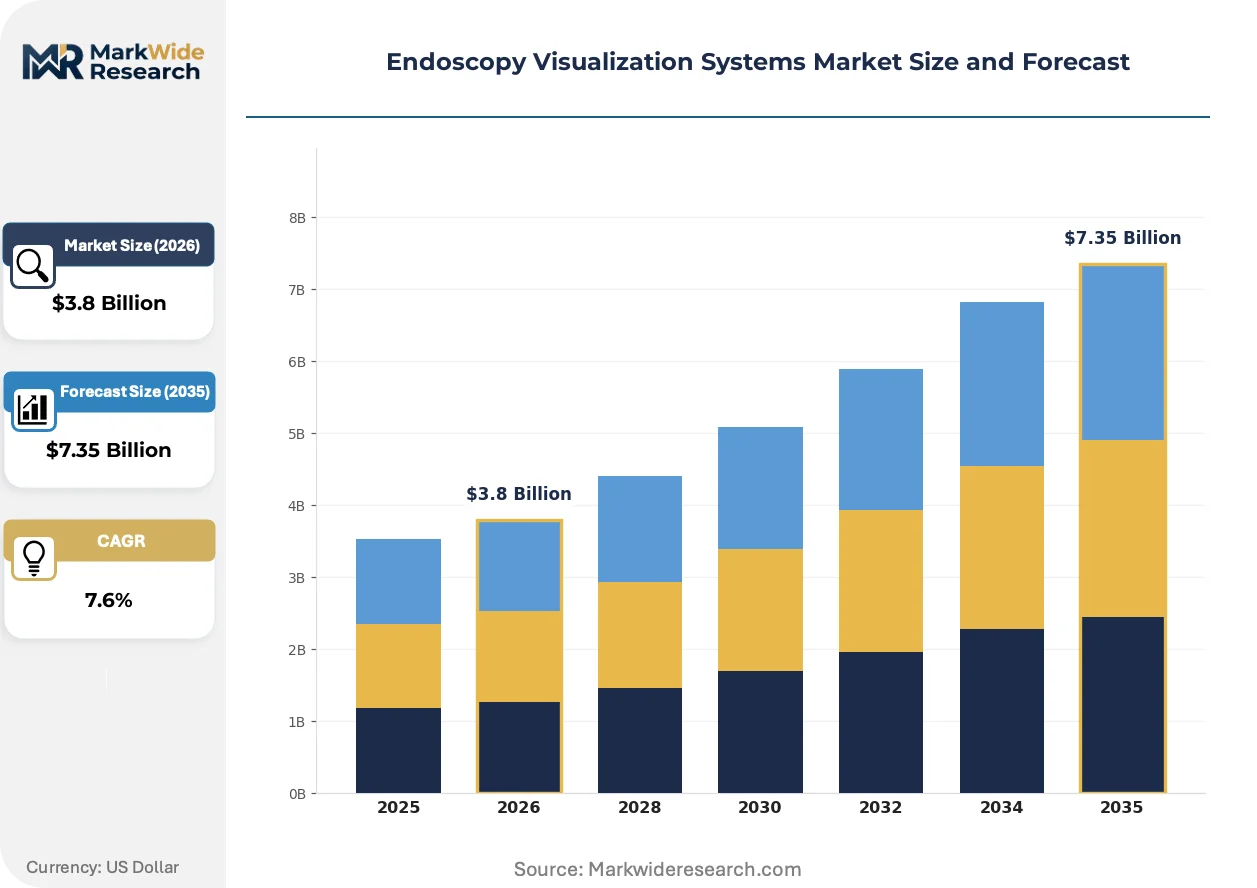
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Endoscopes, Wireless Endoscopes, Flexible Endoscopes, Rigid Endoscopes Technology: LED, High-Definition Imaging, Fluorescence Imaging, 3D Visualization End User: Hospitals, Outpatient Surgery Centers, Diagnostic Laboratories, Research Institutions Application: Gastroenterology, Pulmonology, Urology, Orthopedics |
| Companies Covered | FUJIFILM Holdings Corporation, Boston Scientific Corporation, Olympus Corporation, CONMED Corporation, Richard Wolf GmbH, KARL STORZ SE & Co. KG, Medtronic plc, Smith & Nephew plc, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Visualization Systems Market Strategic Shifts & Innovations
Computational imaging and edge-processing architectures are displacing centralized video processing, enabling real-time image enhancement without latency penalties that previously constrained surgical precision.
4K CMOS sensors with enhanced near-infrared sensitivity are integrating fluorescence imaging capabilities for real-time perfusion assessment during oncologic resections. Academic medical centers in Germany and the United States are adopting these platforms for sentinel lymph node mapping. The technology is integrating open-source software frameworks for algorithm development, compressing the innovation cycle from laboratory validation to clinical deployment.
EU MDR's Unique Device Identification requirements are mandating serialized component tracking across visualization system supply chains. Manufacturers must now embed machine-readable identifiers in camera heads, light sources, and display monitors. The regulation is reshaping procurement documentation, with German university hospitals now requiring full traceability certificates for sterilization cycle validation as a contractual precondition.
After-sales service unbundling is fragmenting traditional equipment leasing arrangements. US health systems are separating visualization hardware acquisition from maintenance contracts, engaging third-party ISO 13485-certified service providers for preventive maintenance and repair. This shift is most visible in California and Texas, where independent service organizations now capture 15-20% of premium platform maintenance revenue previously retained by original equipment manufacturers.
Endoscopy Visualization Systems Market Segmentation
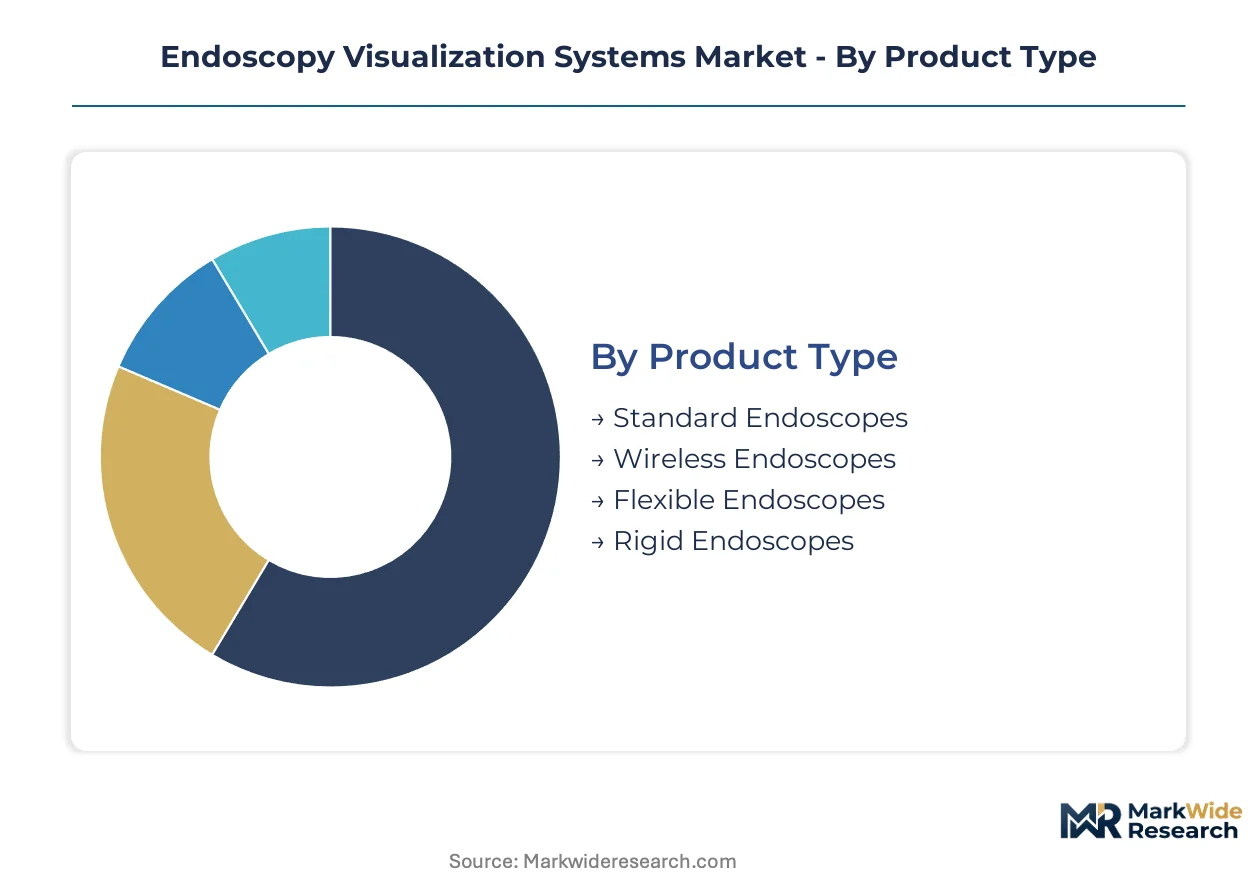
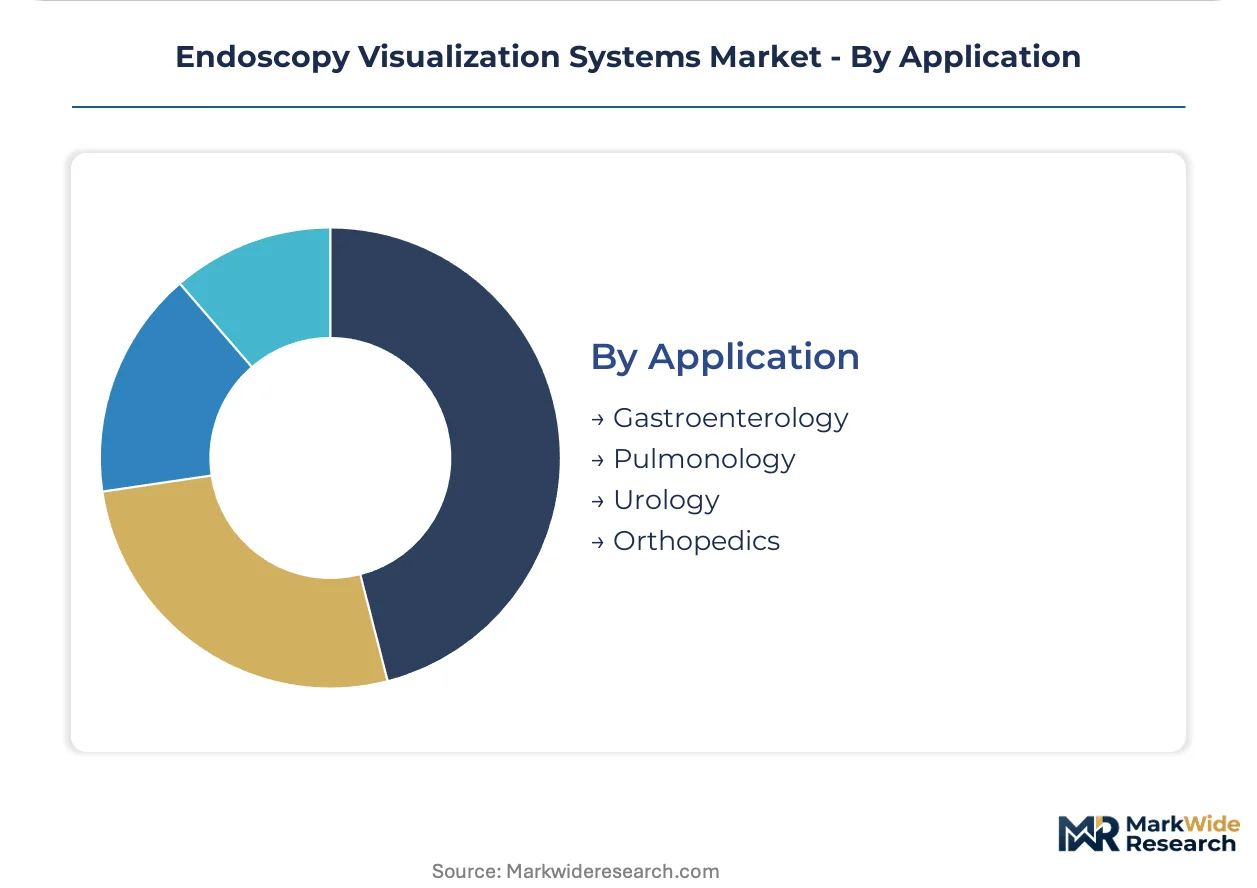
Endoscopy visualization systems fragment across four intersecting dimensions that determine procurement priorities, technology roadmaps, and margin structures. Hospital capital committees evaluate product type durability against sterilization cycle limits, while surgical subspecialties drive resolution and imaging modality requirements through procedure-specific performance demands.
Product Type:
Replacement cycles for visualization hardware accelerate as facilities migrate from fiber-optic stacks to digital platforms with embedded usage tracking.
- Flexible Endoscopes:Braided insertion tubes with steerable distal tips dominate gastroenterology and pulmonology procedure volumes. German university hospitals are retiring scopes beyond 400 sterilization cycles ahead of EU MDR traceability mandates.
- Rigid Endoscopes:Rod-lens optical systems with stainless steel sheaths serve orthopedic and urological applications where instrument durability outweighs maneuverability requirements. KARL STORZ maintains captive optical component production for these platforms.
- Standard Endoscopes:Conventional 1080p systems with xenon or LED illumination remain prevalent in secondary care facilities with constrained capital budgets.
- Wireless Endoscopes:Battery-operated capsule platforms eliminate cable sterilization failures in outpatient settings.
Flexible endoscopes sit at the top of the volume ranking, with wireless platforms climbing the fastest.
Technology:
Cost tiers separate premium visualization capabilities from baseline diagnostic imaging, with reimbursement differentials determining hospital technology acquisition sequencing.
- High-Definition Imaging:4K CMOS sensors with enhanced dynamic range now anchor new system installations. Semiconductor foundry capacity expansion for consumer electronics is compressing sensor costs for mid-tier manufacturers.
- 3D Visualization:Stereoscopic camera heads with depth perception algorithms reduce suturing errors in laparoscopic procedures. Japanese METI subsidies are accelerating deployment in rural prefecture hospitals previously limited to 2D platforms.
- LED:Solid-state illumination systems with tunable color temperature are displacing xenon architectures in compact system designs.
- Fluorescence Imaging:Near-infrared-sensitive sensors enable real-time perfusion assessment during oncologic resections.
High-definition imaging commands the largest installed base, though 3D visualization is expanding most quickly in surgical subspecialties.
End User:
Customer type determines system footprint requirements, IT integration complexity, and service contract structures.
- Hospitals:Academic medical centers with hybrid operating suites demand modular platforms supporting multi-specialty camera heads and centralized video routing.
- Outpatient Surgery Centers:Ambulatory facilities prioritize compact visualization towers with simplified sterilization workflows and reduced preventive maintenance intervals.
- Diagnostic Laboratories:Pathology-focused installations emphasize high-magnification imaging for tissue specimen examination.
- Research Institutions:Preclinical imaging laboratories require open-architecture video processors compatible with experimental sensor modalities.
Hospitals retain the dominant procurement volume, while outpatient surgery centers are gaining share fastest.
Application:
Procedure-specific precision requirements drive divergence in resolution, maneuverability, and auxiliary imaging capabilities across surgical subspecialties.
- Gastroenterology:Colonoscopy and upper GI endoscopy generate the largest procedure volumes globally. AI-enhanced polyp detection algorithms face FDA 510(k) predicate device hurdles for commercial deployment.
- Orthopedics:Arthroscopic visualization demands rigid scope durability and high-flow fluid management integration.
- Pulmonology:Bronchoscopy systems require ultra-thin insertion tubes for peripheral airway navigation.
- Urology:Cystoscopy and ureteroscopy platforms balance optical performance with miniaturization for outpatient procedure compatibility.
Gastroenterology leads procedure volume, with orthopedics showing the steepest expansion trajectory in visualization system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered rigid endoscope manufacturing in the 1940s, establishing optical engineering clusters that persist today. Japanese conglomerates scaled CMOS sensor production for consumer electronics, later repurposing this capability for surgical imaging. Contemporary demand concentrates in hospital systems upgrading from fiber-optic to digital platforms.
Germany
University hospitals in Tübingen and Heidelberg are retiring scopes beyond 400 sterilization cycles ahead of EU MDR traceability mandates. The regulation requires serialized component tracking across visualization system supply chains. KARL STORZ and Richard Wolf anchor a dense manufacturing cluster in Baden-Württemberg, where specialized surgical training centers drive premium platform adoption.
United States
CMS site-of-service payment differentials are accelerating ambulatory surgical center construction in Texas and California. FDA 510(k) clearance pathways for video processors create regulatory friction for AI-enhanced imaging features lacking established predicates. Independent service organizations in these states now capture 15-20% of premium platform maintenance revenue previously retained by manufacturers.
Japan
METI subsidies for minimally invasive surgical suites are expanding 4K visualization system installations in rural prefectures previously limited to standard-definition equipment. PMDA regulatory frameworks govern software-as-a-medical-device classifications for video processing algorithms. Olympus Corporation leverages integrated platform architecture to anchor premium hospital contracts in Tokyo and Osaka metropolitan areas.
India
Production-linked incentive schemes for domestic medical device manufacturing are creating assembly capacity for visualization system components previously imported from German or Japanese suppliers. CDSCO regulatory pathways are streamlining for Class B and C devices. Maharashtra and Gujarat are emerging as contract manufacturing hubs for optical cable architectures and video processor form factors.
United Kingdom
NHS long-term plan targets for reducing diagnostic backlogs are driving colonoscopy volume expansion in London and Manchester hospital systems. MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines for sterilization validation protocols. Academic medical centers in Cambridge and Oxford are adopting fluorescence imaging platforms for sentinel lymph node mapping in oncologic resections.
Endoscopy Visualization Systems Market Key Industry Players
The competitive structure tilts toward diversified conglomerates with captive optical component production. Market concentration is moderate, with three to five integrated platform manufacturers commanding premium hospital contracts while mid-tier assemblers compete on sensor cost advantages. Two strategic archetypes dominate: vertically integrated specialists controlling lens grinding and illumination source manufacturing, and imaging sensor conglomerates leveraging consumer electronics scale. Competitive moves center on modular system bundling to broaden buyer choice, and after-sales service unbundling to capture third-party maintenance revenue.
Among diversified imaging conglomerates, FUJIFILM Holdings Corporation and Olympus Corporation exemplify the sensor-to-surgical platform archetype. KARL STORZ SE & Co. KG represents the vertically integrated specialist model with in-house optical component production. These three occupy positions across the premium-to-mid-tier spectrum, with geographic anchoring in Japan and Germany respectively.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Boston Scientific Corporation |
| Olympus Corporation |
| CONMED Corporation |
| Richard Wolf GmbH |
| KARL STORZ SE & Co. KG |
| Medtronic plc |
| Smith & Nephew plc |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Resolution-grade bifurcation between 4K digital platforms and legacy 1080p fiber-optic stacks manifests in divergent procurement economics and supply chain architectures. Premium-tier manufacturers command pricing power through captive CMOS sensor sourcing and integrated platform bundling, while mid-tier assemblers compete on semiconductor foundry spot pricing and modular component aggregation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with ISO 13485 certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from semiconductor foundry capacity expansion for consumer electronics, which compresses 4K sensor costs and enables competitive positioning by non-integrated manufacturers. Outpatient surgery centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Freight costs for delicate optical components and temperature-sensitive CMOS sensors elevate landed costs for German and Japanese-sourced subsystems. Supply concentration centers on Japan for image sensors, Germany for precision optics, and Taiwan for semiconductor foundry capacity. Xenon lamp dependency on German and Japanese specialty gas suppliers creates single-source vulnerability for illumination architectures. Distribution runs through hospital GPO contracts and direct OEM service agreements, with third-party ISO 13485-certified service providers capturing growing maintenance revenue share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost differentials between India's PLI-subsidized assembly zones and legacy German production clusters create geographic-arbitrage opportunities for component sourcing and regional platform assembly.
For Market Incumbents: Deploy backward integration into CMOS sensor design to defend margin position against foundry-cost-driven entrants. KARL STORZ and Olympus should accelerate proprietary camera head connector standardization to lock in installed-base switching costs, while expanding third-party service certification programs to recapture maintenance revenue from independent service organizations in Texas and California. For New Entrants and Emerging Players: Rural Japanese prefecture hospitals present the most penetrable buyer archetype, where METI subsidies offset capital constraints and 4K upgrade cycles lag metropolitan adoption. Wireless capsule endoscopy platforms for outpatient gastroenterology offer white-space positioning outside sterilization-intensive reusable scope competition. CDSCO regulatory streamlining in Maharashtra and Gujarat enables contract manufacturing entry with reduced compliance friction. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR traceability mandates force smaller manufacturers to absorb serialized component tracking costs without scale economies. Long-term viability favors platform-integrated players with software-as-a-medical-device capabilities and fluorescence imaging R&D pipelines. Watch FDA 510(k) predicate pathway revisions for AI-enhanced imaging as an inflection signal for algorithm-driven valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Serialized component tracking capabilities unlock German university hospital procurement contracts. |
| CMOS Sensor Backward Integration | In-house sensor design insulates margins from foundry pricing volatility. |
| Wireless Capsule Platform Development | Battery-operated systems eliminate sterilization workflows in outpatient settings. |
| Third-Party Service Certification | ISO 13485 maintenance programs recapture revenue from independent service organizations. |
| India PLI Manufacturing Footprint | Domestic assembly capacity reduces landed costs for optical cable architectures. |
Research Approach
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at visualization system manufacturers grounded qualitative findings. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation filings, hospital procurement databases, and CMS site-of-service payment data. Bottom-up and top-down triangulation reconciled unit shipment estimates with capital expenditure patterns across academic medical centers.
Bottom-up modeling anchored volume projections to sterilization cycle replacement rates and EU MDR compliance-driven upgrade timelines, while top-down analysis cross-checked against healthcare capital equipment spending patterns. Segmentation dimensions included product type durability tiers, resolution specifications, end-user facility scale, and surgical subspecialty application. CAGRs derived from fitted growth curves incorporating semiconductor cost trajectories and regulatory implementation schedules. Fluorescence imaging adoption curves and wireless platform development milestones informed technology segment projections.
Underlying measurement precision varies by segment; wireless endoscope forecasts carry wider confidence intervals than established flexible scope categories due to nascent commercial deployment. Forecasts reflect assumptions about EU MDR enforcement consistency, foundry capacity expansion continuity, and reimbursement stability for outpatient procedures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Sigmoidoscope Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Gastroscopes Market
Endoscopy
Endorectal Balloon Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Argentina Endoscopy Devices Market