
 Capsule Endoscopy Market | 2026-2036
Capsule Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Endoscopy Market Intelligence
Project finance for mobile diagnostic units and leasing arrangements for capsule inventory is tilting competitive dynamics toward asset-light operators. Medtronic leverages its installed base of GI platforms to sustain recurring revenue from consumable capsules. Olympus Corporation anchors its position through specialized optical imaging pipelines optimized for luminal diagnostics. Chongqing Jinshan Science & Technology competes on manufacturing scale, supplying cost-optimized video capsules across Asia-Pacific markets.
Capsule endoscopy comprises a swallowable, wireless imaging device encased in a biocompatible shell, typically measuring 11 mm by 26 mm, equipped with a CMOS or CCD sensor, LED illumination, and radio telemetry for real-time image transmission to an external receiver; its primary purpose is non-invasive visualization of the gastrointestinal mucosa for lesion detection and bleeding source identification. The video capsule segment dominates current procedure volumes due to established reimbursement codes and physician familiarity, while the robotic capsule category represents the fastest-expanding margin pool as magnetically steerable platforms command premium pricing in tertiary hospitals. Application demand concentrates in small bowel diagnosis where capsule endoscopy offers unique diagnostic access beyond the reach of standard endoscopes.
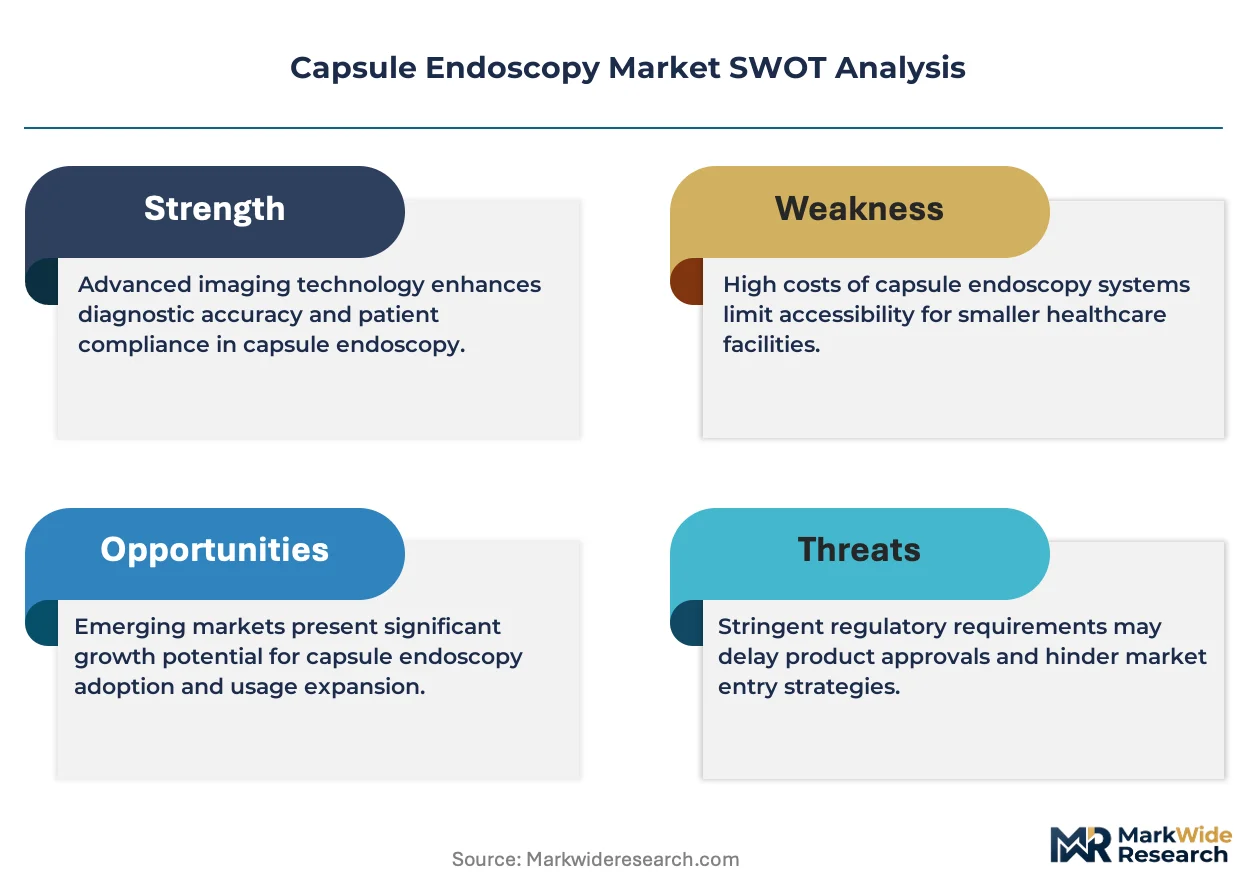
FDA premarket notification requirements and EU MDR conformity assessment procedures impose substantial clinical validation burdens on new capsule entrants, effectively filtering out undercapitalized developers. Japan's PMDA maintains distinct quality management system audits that delay market access for non-domestic manufacturers. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC standards bodies as connected capsule receivers and cloud-based image analysis platforms expand the attack surface for networked medical devices.
Market Dynamics
Magnetically steerable capsule platforms are compressing procedure times and expanding addressable anatomical targets beyond the small bowel, forcing incumbents to accelerate R&D timelines or cede tertiary hospital accounts to robotics specialists.
Growth Catalysts
- EU MDR pathway alignment:Streamlined conformity assessment procedures for legacy device renewals are accelerating CE marking timelines for established capsule manufacturers, reducing regulatory friction for portfolio expansions.
- Japan's aging cohort:PMDA reimbursement revisions favoring minimally invasive GI diagnostics are pulling capsule volumes into prefectural hospital networks previously dependent on conventional endoscopy suites.
- CMOS sensor cost curves:Semiconductor foundry scale economies are compressing imaging module costs, enabling single-use capsule economics at price points viable for emerging market screening programs.
Market Restraints
- Biocompatible shell material concentration:Medical-grade polymer supply chains cluster in German and Swiss chemical conglomerates, exposing capsule assemblers to input cost volatility and qualification delays.
- Receiver hardware lock-in:Proprietary radio telemetry protocols tether hospitals to single-vendor ecosystems, raising switching costs and limiting procurement leverage.
- Capsule retention risk:Structural contraindications in patients with known strictures or prior abdominal surgery constrain addressable populations and inflate liability premiums.
Strategic Opportunities
- India's tier-2 hospital expansion:CDSCO fast-track pathways for indigenously manufactured diagnostic devices create first-mover advantages for localized capsule assembly operations serving Maharashtra and Karnataka healthcare networks.
- AI-assisted image analysis:Cloud-based lesion detection algorithms are converging with capsule workflows, creating subscription revenue streams and reducing radiologist interpretation bottlenecks.
- Direct-to-consumer screening channels:Employer-sponsored wellness programs and private diagnostic chains in Germany are piloting capsule-based colorectal screening outside traditional hospital procurement.
Industry Challenges
- Electromagnetic compatibility certification:IEC 60601-1-2 testing timelines for wireless capsule receivers extend 14-18 months, compressing product launch windows and straining regulatory affairs staffing.
- GI specialist training pipelines:Capsule interpretation competency requirements outpace fellowship program adaptations, creating credentialing backlogs and procedure volume constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Endoscopy Market |
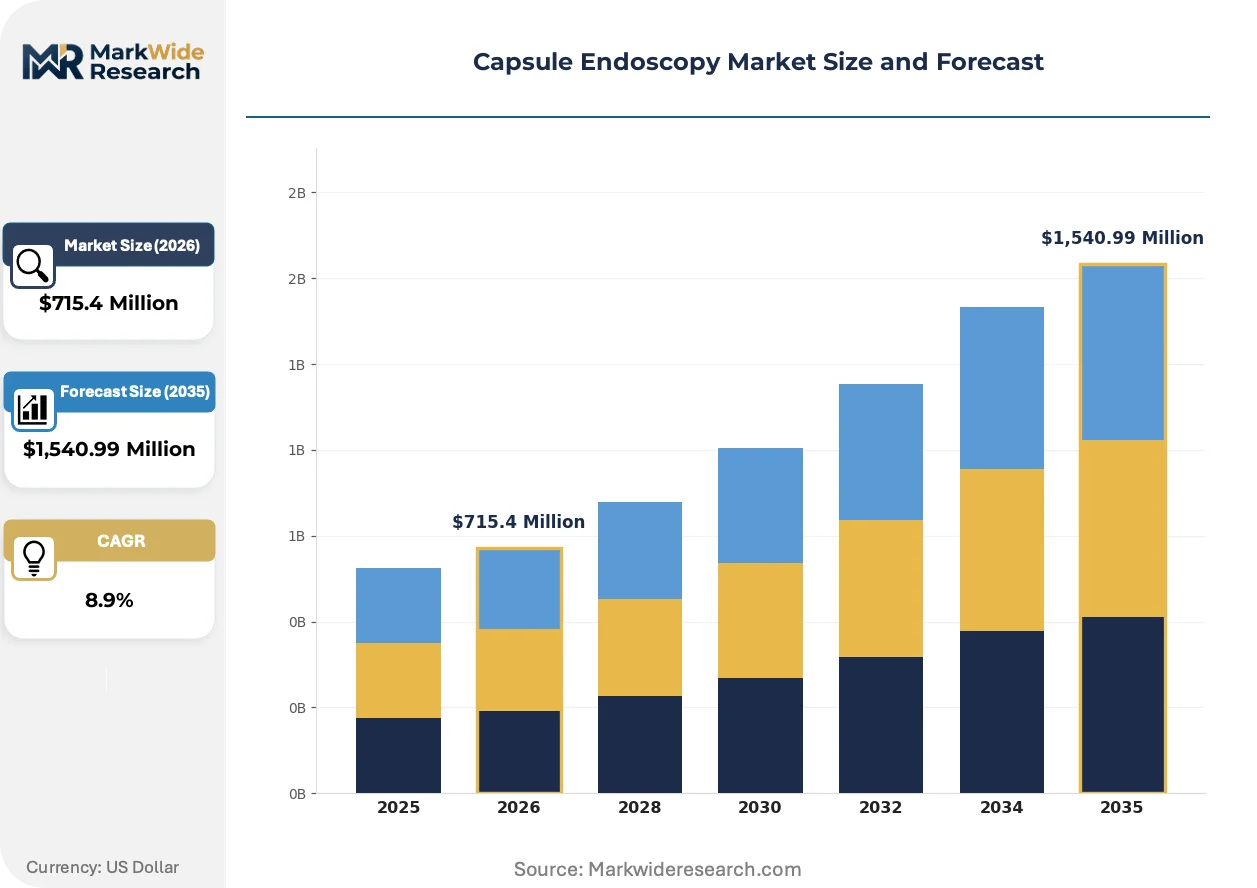
| Market Size in 2026 | $715.4 Million |
| Market Size in 2035 | $1,540.99 Million |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
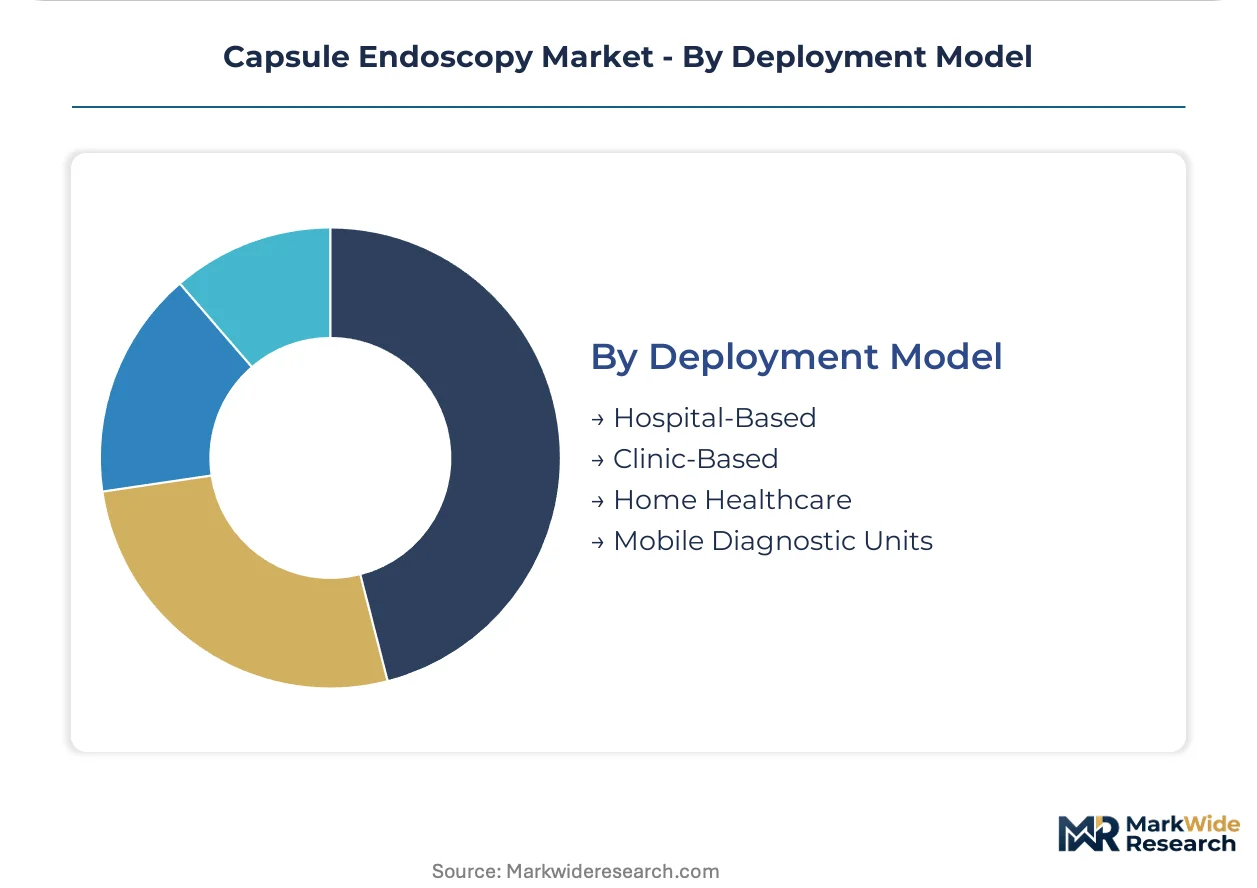
| Segmentation | Product Type: Video Capsule, Imaging Capsule, Robotic Capsule, Magnetic Capsule, Disposable Capsule Application: Gastrointestinal Tract Imaging, Small Bowel Diagnosis, Colon Examination, Esophageal Assessment, Crohn’s Disease Monitoring End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics Deployment Model: Hospital-Based, Clinic-Based, Home Healthcare, Mobile Diagnostic Units |
| Companies Covered | IntroMedic Co., Ltd., RF Co., Ltd., Medtronic, Check-Cap, AnX Robotics, Olympus Corporation, Chongqing Jinshan Science & Technology, Shangxian Minimal Invasive Inc., CapsoVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Endoscopy Market Strategic Shifts & Innovations
Computational imaging and autonomous navigation are redefining capsule functional boundaries, shifting competitive advantage from optical hardware precision to software-defined diagnostic workflows and real-time therapeutic intervention capabilities.
Magnetic steering systems employing external field generators are digitizing capsule endoscopy by enabling active locomotion through peristaltic-resistant segments. Tertiary hospitals in Japan and Germany are deploying these platforms for gastric and colonic applications at triple-digit annual installation rates. This capability compression is collapsing the historical distinction between diagnostic and interventional endoscopy, forcing conventional endoscope manufacturers to defend installed base positions.
FDA's evolving cybersecurity guidance for networked medical devices is mandating encrypted telemetry channels and firmware update architectures for capsule receivers. Hardware manufacturers must embed secure boot protocols and vulnerability disclosure programs, extending development cycles by 8-12 months. Cloud-connected image analysis platforms face the steepest compliance burdens, with FDA 510(k) submissions now requiring documented threat modeling and penetration testing.
Hospital procurement committees are consolidating diagnostic service contracts around integrated GI platform vendors, displacing standalone capsule suppliers. Health systems in the United States and Germany are bundling capsule procedures with pathology and anesthesia services, compressing vendor count per supply agreement. This concentration is most visible in integrated delivery networks where single-source contracting reduces total cost of ownership metrics.
Capsule Endoscopy Market Segmentation
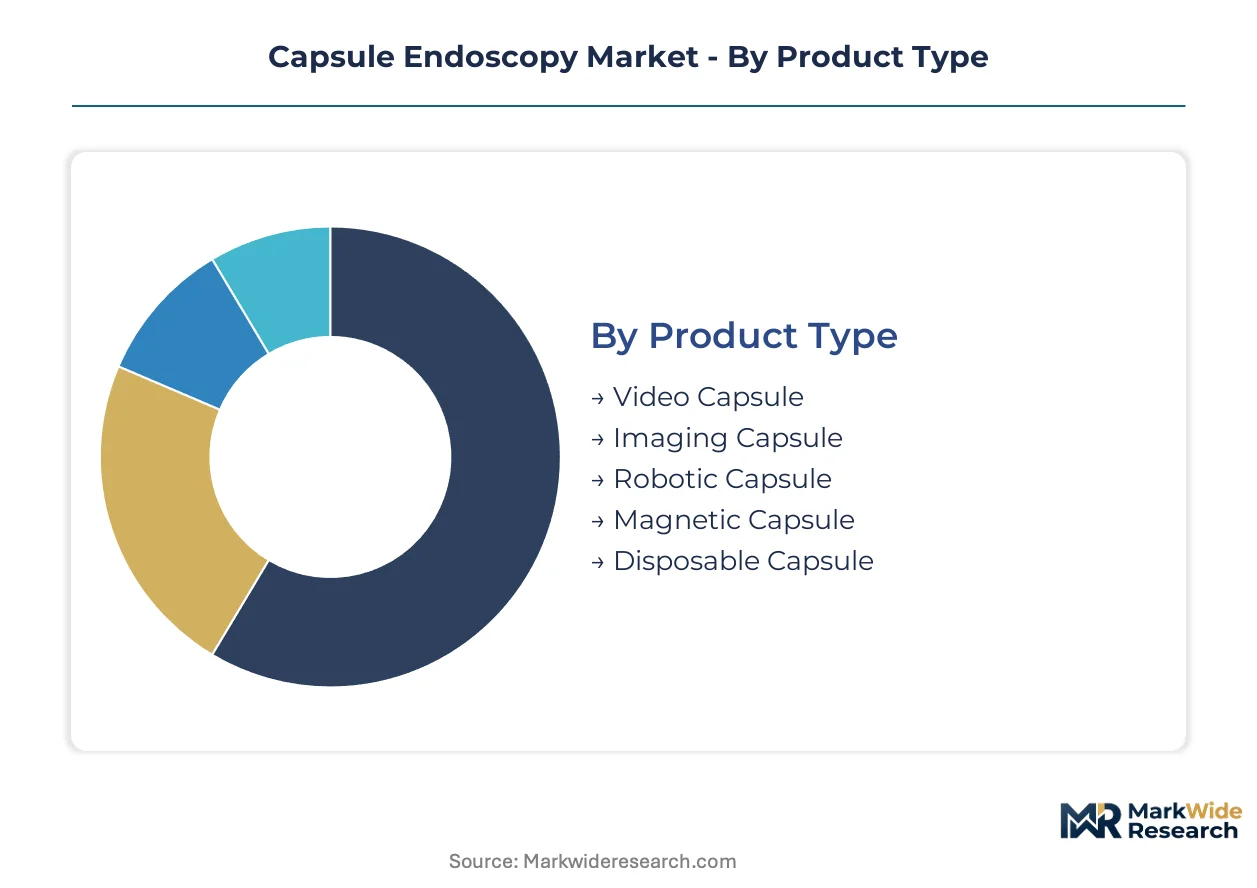
Segmentation in capsule endoscopy reveals distinct procurement cycles and margin architectures across product categories, clinical applications, and care delivery settings. Understanding these divisions exposes where capital intensity concentrates versus where consumable economics dominate recurring revenue streams.
Product Type:
Cycle times vary dramatically across this category, with single-use disposable platforms turning inventory weekly while capital-intensive robotic systems depreciate over seven to ten year horizons.
- Video Capsule:A wireless imaging device housing CMOS sensors, LED arrays, and radio telemetry transmitters within a biocompatible polymer shell measuring approximately 11 mm by 26 mm. Demand clusters in United States hospital networks where established CPT reimbursement codes and physician training protocols sustain high procedure volumes. This segment anchors the volume base while Robotic Capsule gains share at the steepest rate.
- Robotic Capsule:Magnetically steerable platforms integrating external field generators with internal locomotion mechanisms, enabling active navigation through peristaltic-resistant anatomical segments. Tertiary hospitals in Germany and Japan are deploying these systems for gastric and colonic applications at accelerating installation rates, drawn by procedure time compression and expanded diagnostic reach beyond passive capsule capabilities.
- Imaging Capsule:Specialized optical configurations optimized for specific wavelength detection or fluorescence-based lesion identification, typically deployed in academic medical center research protocols.
- Magnetic Capsule:Platforms combining passive imaging with external magnetic control for targeted tissue sampling or drug delivery applications, currently limited to investigational use in major European teaching hospitals.
- Disposable Capsule:Single-use devices engineered for cost-minimized screening programs, with manufacturing scale concentrated in Asia-Pacific contract facilities serving emerging market health systems.
Video Capsule generates the majority of current procedure volumes through established reimbursement pathways, while Robotic Capsule commands the fastest expansion trajectory as magnetically steerable platforms penetrate tertiary hospital accounts.
Application:
Clinical utility and reimbursement density separate high-value diagnostic targets from screening applications, with small bowel procedures maintaining premium positioning against commoditized colorectal screening alternatives.
- Small Bowel Diagnosis:The primary clinical indication where capsule endoscopy delivers unique diagnostic access beyond the reach of conventional endoscopes, particularly for obscure gastrointestinal bleeding and suspected inflammatory pathology. United States gastroenterology practices and German hospital networks drive sustained demand through established referral pathways and favorable DRG classification.
- Gastrointestinal Tract Imaging:Comprehensive luminal visualization spanning esophageal, gastric, small intestinal, and colonic mucosa, increasingly bundled with AI-assisted image analysis platforms in integrated health systems.
- Colon Examination:Screening applications competing directly with conventional colonoscopy, with adoption constrained by reimbursement differentials and patient preference variability across United States and German markets.
- Esophageal Assessment:Targeted evaluation of mucosal disorders including Barrett's esophagus surveillance, currently limited by capsule transit time constraints and image quality requirements.
- Crohn's Disease Monitoring:Serial assessment of disease activity and mucosal healing in inflammatory bowel disease populations, with demand concentrated in pediatric and young adult cohorts where repeated conventional endoscopy carries higher procedural risk.
Small Bowel Diagnosis commands the highest reimbursement rates per procedure while Colon Examination expands most quickly as screening programs incorporate capsule alternatives for non-compliant populations.
End User:
Capital deployment requirements and procurement authority distribution shape vendor access patterns, with hospital systems consolidating purchasing power against fragmented clinic-level decision-making.
- Hospitals:Integrated delivery networks and academic medical centers with dedicated gastroenterology departments, representing the primary volume concentration for both diagnostic and interventional capsule platforms. These institutions command dedicated capital equipment budgets and maintain specialized interpretation expertise through fellowship-trained physicians.
- Ambulatory Surgical Centers:Freestanding facilities focused on same-day procedures, increasingly adopting capsule screening as lower-acuity alternatives to conventional endoscopy suite utilization.
- Diagnostic Laboratories:Centralized interpretation services and mobile capsule deployment operations, particularly prevalent in German and United States metropolitan markets where economies of scale in image analysis justify dedicated infrastructure.
- Specialty Clinics:Gastroenterology-focused private practices with limited procedure volume, typically accessing capsule technology through leasing arrangements or third-party service contracts rather than capital acquisition.
Hospitals anchor the installed base through direct capital purchasing while Diagnostic Laboratories capture the fastest growth trajectory via asset-light service models and centralized interpretation platforms.
Deployment Model:
Patient proximity and equipment mobility determine operational cost structures, with fixed hospital installations carrying depreciation burdens against variable-cost mobile and home-based alternatives.
- Hospital-Based:Traditional deployment within dedicated endoscopy units or radiology departments, requiring fixed receiver infrastructure and specialized nursing support for capsule ingestion and data retrieval protocols.
- Mobile Diagnostic Units:Vehicle-mounted or transportable capsule systems enabling screening outreach to underserved geographic areas, with project finance structures and equipment leasing arrangements reducing upfront capital requirements for operators.
- Clinic-Based:Office-based administration of capsule procedures within specialty practice settings, typically limited to lower-complexity indications without same-day therapeutic intervention capabilities.
- Home Healthcare:Direct-to-consumer capsule screening with remote monitoring and cloud-based image transmission, currently piloted in German employer wellness programs and select United States private diagnostic chains outside traditional hospital procurement channels.
Hospital-Based deployment maintains the dominant volume position while Mobile Diagnostic Units expand most rapidly through asset-light financing structures and rural screening program mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and regulatory clearance pathways are concentrating demand in health systems with established minimally invasive diagnostic protocols. Government screening mandates and aging demographics are pulling procedure volumes into hospital networks previously dependent on conventional endoscopy suites.
United States
Integrated delivery networks in Texas and Florida are bundling capsule procedures with pathology services, compressing vendor count per supply agreement. FDA premarket notification requirements filter undercapitalized developers from 510(k) pathways. The Greater Boston cluster anchors AI-assisted image analysis development for cloud-based lesion detection platforms.
Germany
Employer-sponsored wellness programs in Bavaria and Baden-Württemberg are piloting direct-to-consumer colorectal screening outside traditional hospital procurement. EU MDR streamlined conformity assessment procedures accelerate CE marking timelines for established manufacturers. The Munich medical technology corridor concentrates magnetic steering system development for tertiary hospital deployments.
Japan
Prefectural hospital networks in Kanto and Kansai regions are expanding capsule volumes following PMDA reimbursement revisions favoring minimally invasive GI diagnostics. METI quality management system audits delay market access for non-domestic manufacturers. The Tokyo-Osaka corridor drives triple-digit annual installation rates for magnetically steerable platforms in gastric applications.
India
CDSCO fast-track pathways for indigenously manufactured diagnostic devices create first-mover advantages in Maharashtra and Karnataka healthcare networks. Tier-2 hospital expansion in Pune and Bengaluru pulls localized capsule assembly operations. The Hyderabad medical device cluster supplies cost-optimized video capsules for emerging market screening programs.
China
NMPA medical device registration requirements impose clinical validation burdens that favor domestic manufacturers with established quality management systems. Yangtze River Delta health systems in Shanghai and Jiangsu province deploy capsule screening for rural outreach programs. The Shenzhen electronics corridor compresses CMOS sensor module costs through semiconductor foundry scale economies.
Capsule Endoscopy Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base organizes around three strategic archetypes: integrated GI platform vendors defending installed base positions, robotics specialists commanding premium pricing in tertiary hospitals, and manufacturing-scale suppliers serving emerging market screening programs. Competitive dynamics center on M&A consolidation of diagnostic service contracts and strategic partnerships for AI-assisted image analysis capabilities.
Among integrated platform vendors, Medtronic and Olympus Corporation exemplify the channel-control archetype through recurring revenue from consumable capsules and specialized optical imaging pipelines. IntroMedic Co., Ltd. occupies a position within the robotics-specialist tier, representing the magnetically steerable platform segment that is compressing procedure times and expanding anatomical targets beyond passive capsule capabilities. These three companies anchor the competitive structure without exhaustively mapping the field.
| Leading Market Players |
|---|
| IntroMedic Co., Ltd. |
| RF Co., Ltd. |
| Medtronic |
| Check-Cap |
| AnX Robotics |
| Olympus Corporation |
| Chongqing Jinshan Science & Technology |
| Shangxian Minimal Invasive Inc. |
| CapsoVision |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's logistics cost dynamics amplify supply concentration effects in medical-grade polymer sourcing while compressing downstream price differentiation between FDA-grade and standard-tier capsules. German and Swiss chemical conglomerates anchor biocompatible shell material production, translating transport cost volatility into tiered pricing spreads that widen during feedstock qualification delays.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium robotic platforms and economy disposable capsules, with CE marking under EU MDR and FDA 510(k) clearance commanding substantial brand premiums. Per-unit transactional pricing dominates consumable video capsules, while subscription-based service models are emerging for AI-assisted image analysis platforms. Pricing pressure stems from CMOS sensor cost compression enabling emerging market screening programs at reduced price points. Hospital procurement committees exhibit the highest price sensitivity, whereas tertiary academic medical centers prioritize magnetic steering capabilities over unit economics.
Supply Chain Analysis
Medical-grade polycarbonate and biocompatible polymer feedstocks concentrate in Germany, Switzerland, and select Japanese chemical manufacturers, with semiconductor imaging modules drawing from Taiwan and South Korea foundry operations. Capsule assemblers depend on specialized CMOS sensor fabrication, LED illumination arrays, and radio telemetry chipsets. Single-source vulnerability in biocompatible shell qualification creates supply chain risk during polymer grade transitions. Distribution runs through integrated GI platform vendors consolidating diagnostic service contracts, displacing standalone capsule suppliers in United States and German health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capsule endoscopy market exhibits cyclical recovery characteristics as hospital capital expenditure cycles normalize following pandemic-era procedure backlogs, with magnetic steering platform refresh cycles driving replacement demand in tertiary institutions.
For Market Incumbents: Insulate recurring revenue streams from consumable capsules by deepening backward integration into CMOS sensor module sourcing and securing exclusive GPO contracts with integrated delivery networks. Magnetically steerable platform specialists threaten installed base positions in Japan and Germany; defend through accelerated R&D timelines for active locomotion capabilities and embedded AI interpretation features. For New Entrants and Emerging Players: India's tier-2 hospital networks in Maharashtra and Karnataka represent the most penetrable entry point, with CDSCO fast-track pathways for indigenously manufactured devices creating first-mover structural advantages. Employer-sponsored wellness programs in German metropolitan areas offer direct-to-consumer screening channels outside traditional hospital procurement. Pursue asset-light mobile diagnostic unit leasing arrangements to circumvent capital intensity barriers. For Investors and Strategic Acquirers: Cloud-based AI image analysis platforms with established hospital system partnerships present the most attractive acquisition archetype for long-term viability across the 5-10 year window. FDA cybersecurity guidance enforcement and EU MDR conformity assessment bottlenecks will consolidate vendor count, favoring targets with documented threat modeling and penetration testing capabilities. Monitor PMDA reimbursement revision implementation velocity in Japan's prefectural hospital networks as inflection indicator for Asia-Pacific demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined conformity assessment accelerates portfolio expansion timelines for established manufacturers. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida bundle capsule procedures with pathology services, compressing vendor count. |
| Software Companion Development | AI-assisted lesion detection algorithms create subscription revenue streams and reduce radiologist interpretation bottlenecks. |
| Reimbursement Strategy | PMDA revisions in Japan's Kanto and Kansai regions pull volumes into prefectural hospital networks. |
| FDA Submission | Premarket notification requirements with cybersecurity documentation filter undercapitalized developers from 510(k) pathways. |
Research Approach
A spread of perspectives from hospital purchasing committee directors, biomedical engineers specializing in GI platforms, GPO contracts managers, and regulatory affairs leads at established manufacturers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EUDAMED CE marking databases, PMDA reimbursement bulletins, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down market sizing from CMOS sensor shipment data and magnetic steering platform installation records.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type (video, robotic, imaging, magnetic, disposable), clinical application (small bowel, gastric, colonic, esophageal), and deployment model (hospital-based, mobile diagnostic, home healthcare). CAGRs derived from fitted growth curves incorporating semiconductor cost curve trajectories, regulatory clearance timeline assumptions, and reimbursement policy elasticity estimates. Industry-specific inputs included magnetic steering system adoption rates in tertiary hospitals and AI image analysis platform subscription conversion metrics.
Stress conditions across EU MDR transition timelines, PMDA audit backlogs, and biocompatible polymer supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement policy stability and cybersecurity compliance burden evolution. Cross-checking against hospital capital expenditure survey data and GI specialist fellowship training pipeline statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Endoscopy Device Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Spain Endoscopy Devices Market