
 Cataract Disposable Products Market | 2026-2036
Cataract Disposable Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cataract Disposable Products Market Analytics
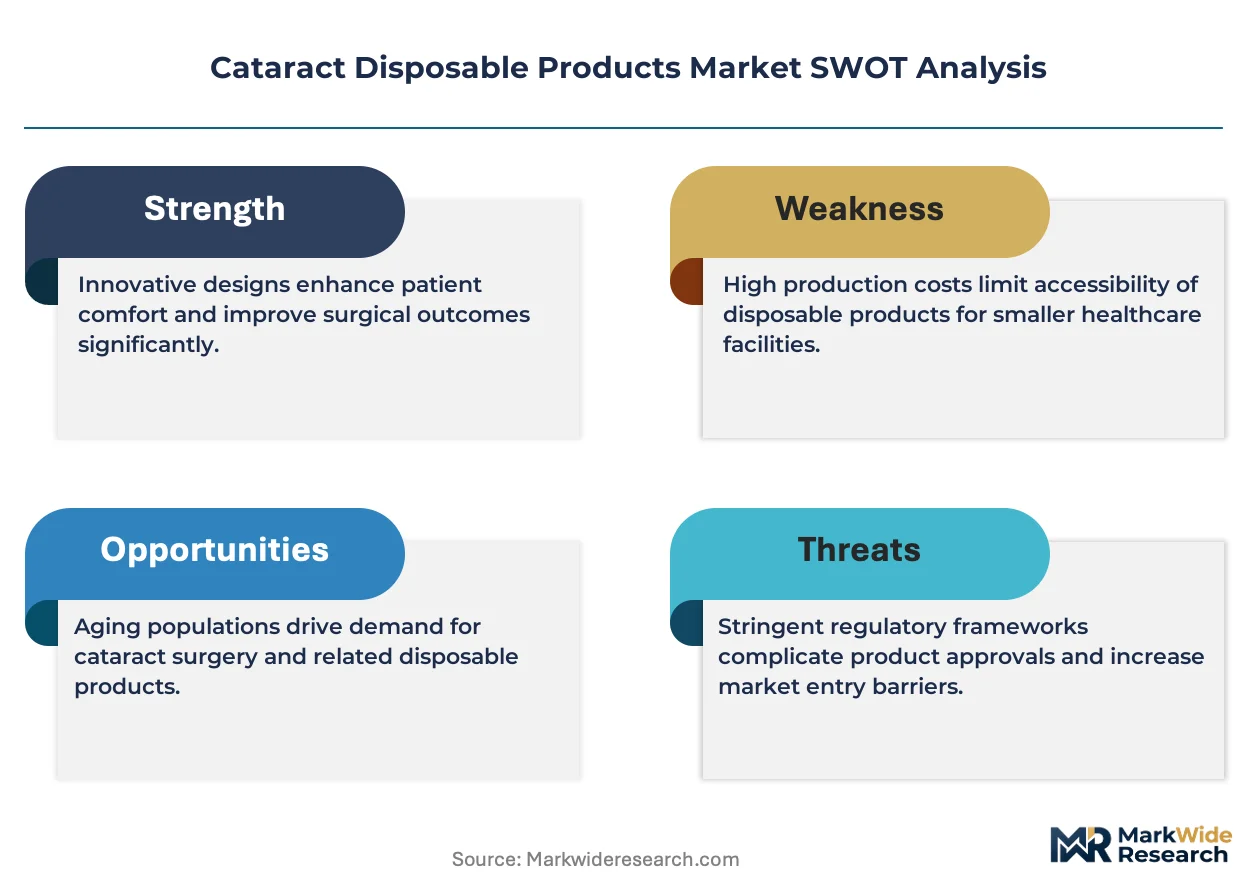
Premium hydrophobic acrylic specifications is rotating through the intraocular lens segment as surgeons prioritize posterior capsule opacification resistance. Alcon Inc leverages vertical integration across lens polymer sourcing and injector systems to sustain cost discipline. Johnson & Johnson Vision anchors its position through R&D intensity in presbyopia-correcting platforms. Carl Zeiss Meditec AG differentiates via precision optics manufacturing that controls quality thresholds for emerging markets.
Cataract disposable products encompass single-use sterile instruments, intraocular lenses, viscoelastic agents, and surgical drapes engineered for ophthalmic intervention, typically manufactured through injection molding of medical-grade silicone or acrylic polymers with particulate limits below 0.5 micrometers to ensure optical clarity and biocompatibility during phacoemulsification procedures. Intraocular lenses command the dominant value pool given material complexity and regulatory burden, while surgical packs gain volume traction through operating room efficiency protocols that consolidate draping, irrigation, and instrument delivery into sterile, procedure-matched kits. Capsular tension rings occupy a specialized niche where demand correlates with complex cataract cases and zonular weakness prevalence.
The FDA enforces Class II medical device controls with 510(k) premarket notification for intraocular lenses, while the EU Medical Device Regulation imposes notified body scrutiny and post-market surveillance obligations that extend compliance timelines for new entrants. ISO 11979 governs optical and mechanical testing protocols that manufacturers must satisfy for international market access. Stakeholders should monitor how evolving sterile barrier standards and single-use sustainability mandates reshape material selection and supplier qualification timelines.
Market Dynamics
The cataract disposable products market pivots on ambulatory surgical center expansion, which compresses procedure turnaround times and mandates pre-sterilized, procedure-matched kit formats that eliminate on-site reprocessing infrastructure.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating sterile barrier validation are capturing shelf space as competitors face extended notified body queues. German and French procurement offices now specify MDR-certified kits exclusively.
- Phacoemulsification platform upgrades:Next-generation fluidics systems demand matched disposable tubing sets with tighter particulate specifications, pulling through coordinated lens-injector-irrigation purchases.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract molders to establish ISO 13485 facilities near Mumbai and Hyderabad surgical corridors.
Market Restraints
- Medical-grade silicone feedstock volatility:Semiconductor sector competition for high-purity silicone precursors creates input cost pressure without long-term supply agreements.
- Injector system molding concentration:Three European toolmakers control precision cavity designs for hydrophobic acrylic lens delivery systems, creating single-source vulnerability.
- FDA 510(k) predicate device limitations:Novel materials lacking established predicates face 18-24 month review timelines that freeze product pipeline advancement.
Strategic Opportunities
- Brazil's SUS ophthalmology expansion:Public system cataract surgery volume targets create demand for economy-tier sterile packs with simplified instrumentation.
- Viscoelastic-sustained release convergence:Combining dispersive agents with intraoperative drug delivery opens premium positioning in complex case segments.
- Direct-to-ASC distribution platforms:Bypassing traditional distributor markups through consignment inventory models captures margin in United States outpatient settings.
Industry Challenges
- Cleanroom technician scarcity:ISO Class 7 molding operations in emerging manufacturing hubs face recruitment gaps for qualified environmental monitoring personnel.
- Legacy sterilization validation:Ethylene oxide alternative transitions require complete biological indicator requalification that stalls product line conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cataract Disposable Products Market |
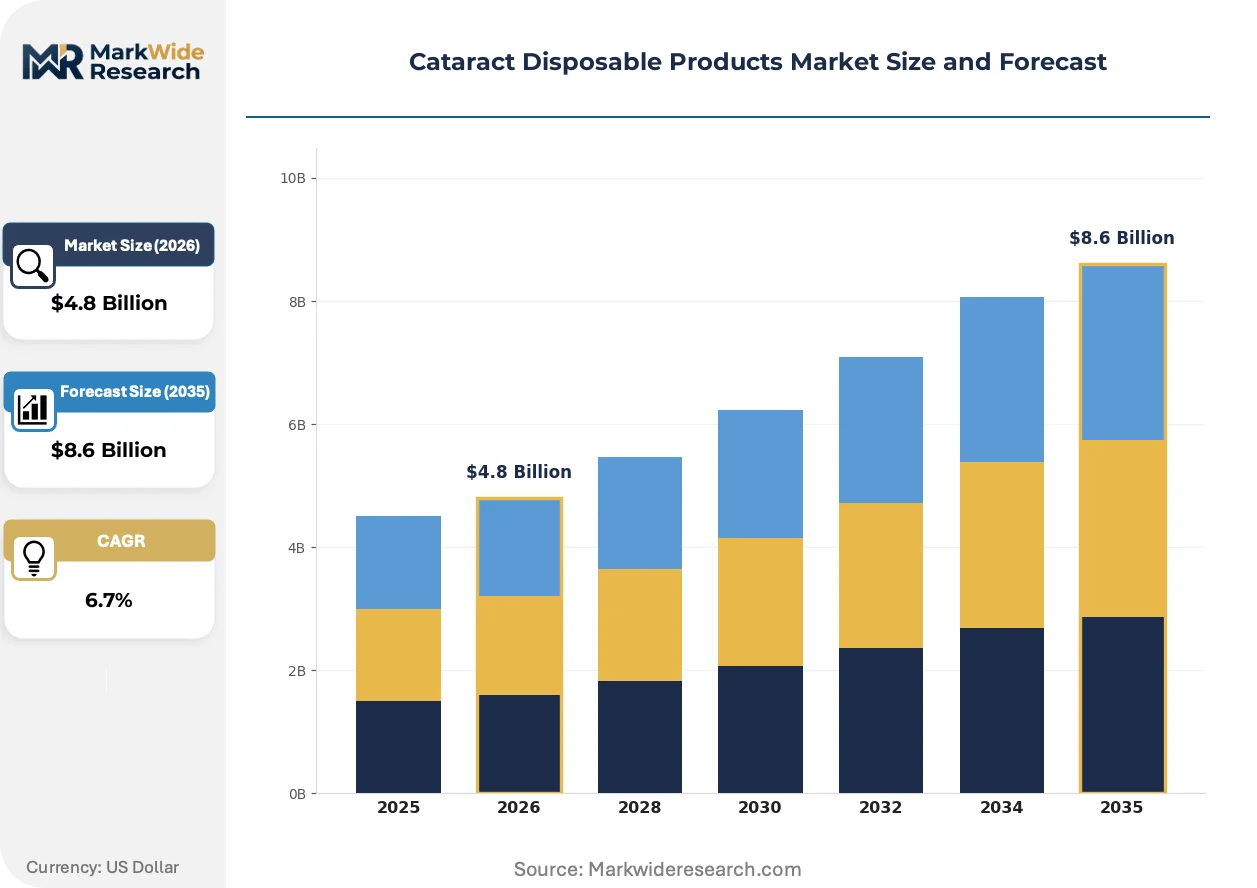
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Surgical Packs, Capsular Tension Rings, Surgical Drapes Delivery Mode: Single Use, Multi Use, Sterile Packs, Non-Sterile Packs End User: Ophthalmology Clinics, Hospitals, Surgical Centers, Research Institutions Application: Phacoemulsification, Extracapsular Surgery, Refractive Surgery, Secondary Procedures |
| Companies Covered | Alcon Inc, Bausch & Lomb, Johnson & Johnson Vision, Carl Zeiss Meditec AG, NIDEK Co Ltd, HOYA Corporation, STAAR Surgical Company, Topcon Corporation, Ziemer Ophthalmic Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cataract Disposable Products Market Evolving Landscape
Material science advances and sterile packaging automation are compressing production lead times while elevating optical performance thresholds. The competitive frontier shifts toward integrated kit design that eliminates surgical tray assembly labor.
Pre-loaded hydrophobic acrylic injectors are displacing manual lens folding forceps in premium procedure segments. United States ambulatory surgical centers adopted pre-loaded systems at accelerated pace through 2024. This format compression is displacing separate lens and injector purchasing decisions into single-SKU procurement.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations to 15 years for implantable lenses. Manufacturers must establish patient registries and periodic safety update reporting systems. German notified bodies are enforcing these timelines most stringently, compressing competitive access for resource-constrained entrants.
Consolidated kit procurement is replacing individual component ordering across United States ophthalmology clinics. Buyers now specify draping, irrigation, viscoelastic, and lens combinations in single purchase orders. This pattern concentrates most visibly in multi-site ASC chains operating across Texas, Florida, and California surgical corridors.
Cataract Disposable Products Market Segmentation
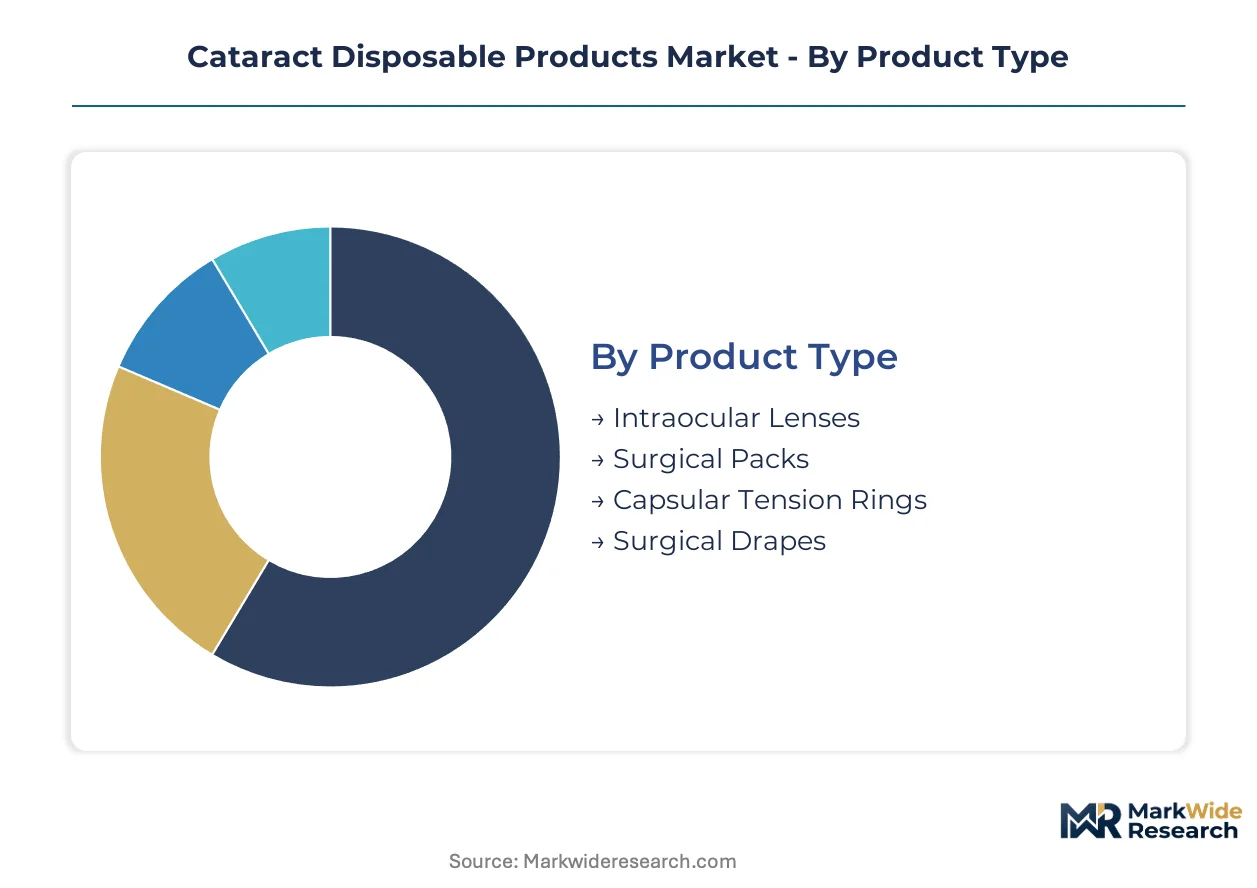
Segmentation in cataract disposable products reveals how procurement power concentrates around procedure-matched kits while material complexity drives margin stratification. Understanding these fault lines exposes where substitution pressure from reusable alternatives threatens volume, and where regulatory barriers protect premium positioning.
Product Type:
Substitution pressure from reusable forceps and manual insertion techniques weighs most heavily on segments with simpler mechanical specifications, while polymer complexity and optical tolerances shield higher-value categories.
- Intraocular Lenses:Hydrophobic acrylic and silicone optics manufactured to ISO 11979 standards with particulate limits below 0.5 micrometers. Demand concentrates in United States ambulatory surgical centers adopting pre-loaded injector systems that compress lens and delivery device procurement into single-SKU purchasing.
- Surgical Packs:Consolidated sterile kits combining draping, irrigation tubing, and instrument delivery. Ophthalmology clinics across Texas, Florida, and California surgical corridors specify procedure-matched formats that eliminate on-site tray assembly labor.
- Capsular Tension Rings:PMMA or polyimide devices for zonular weakness cases. Complex cataract segments in tertiary hospitals drive niche demand.
- Surgical Drapes:Single-use sterile barriers with adhesive apertures. Cost pressure from reusable textile alternatives constrains pricing flexibility.
Intraocular lenses anchor the volume base while surgical packs gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium sterile formats from economy non-sterile alternatives, with reimbursement differentials determining procurement patterns across facility types.
- Single Use:Pre-sterilized devices for immediate deployment. United States ASC chains mandate these formats to compress procedure turnaround times.
- Sterile Packs:FDA 510(k) cleared or EU MDR certified barrier systems. German and French procurement offices now specify exclusively MDR-validated kits.
- Multi Use:Reprocessed instruments for cost-constrained settings. Brazil's SUS ophthalmology expansion targets economy-tier procurement.
- Non-Sterile Packs:Components requiring on-site sterilization. Limited to facilities with ethylene oxide or steam infrastructure.
Sterile packs dominate revenue contribution while single-use formats climb fastest in outpatient settings.
End User:
Customer type fragmentation concentrates purchasing power in multi-site chains while independent practices retain component-level ordering flexibility.
- Ophthalmology Clinics:Specialized outpatient facilities driving phacoemulsification volume. Consolidated kit procurement is replacing individual component ordering across United States multi-site chains.
- Surgical Centers:Ambulatory facilities with compressed turnaround protocols. Pre-sterilized, procedure-matched kit formats eliminate reprocessing infrastructure requirements.
- Hospitals:Tertiary institutions handling complex cataract cases. Capsular tension ring demand correlates with zonular weakness prevalence in academic medical centers.
- Research Institutions:Investigational device evaluation sites. Extended follow-up obligations under EU MDR post-market surveillance requirements shape procurement.
Ophthalmology clinics represent the largest addressable base while surgical centers expand most quickly.
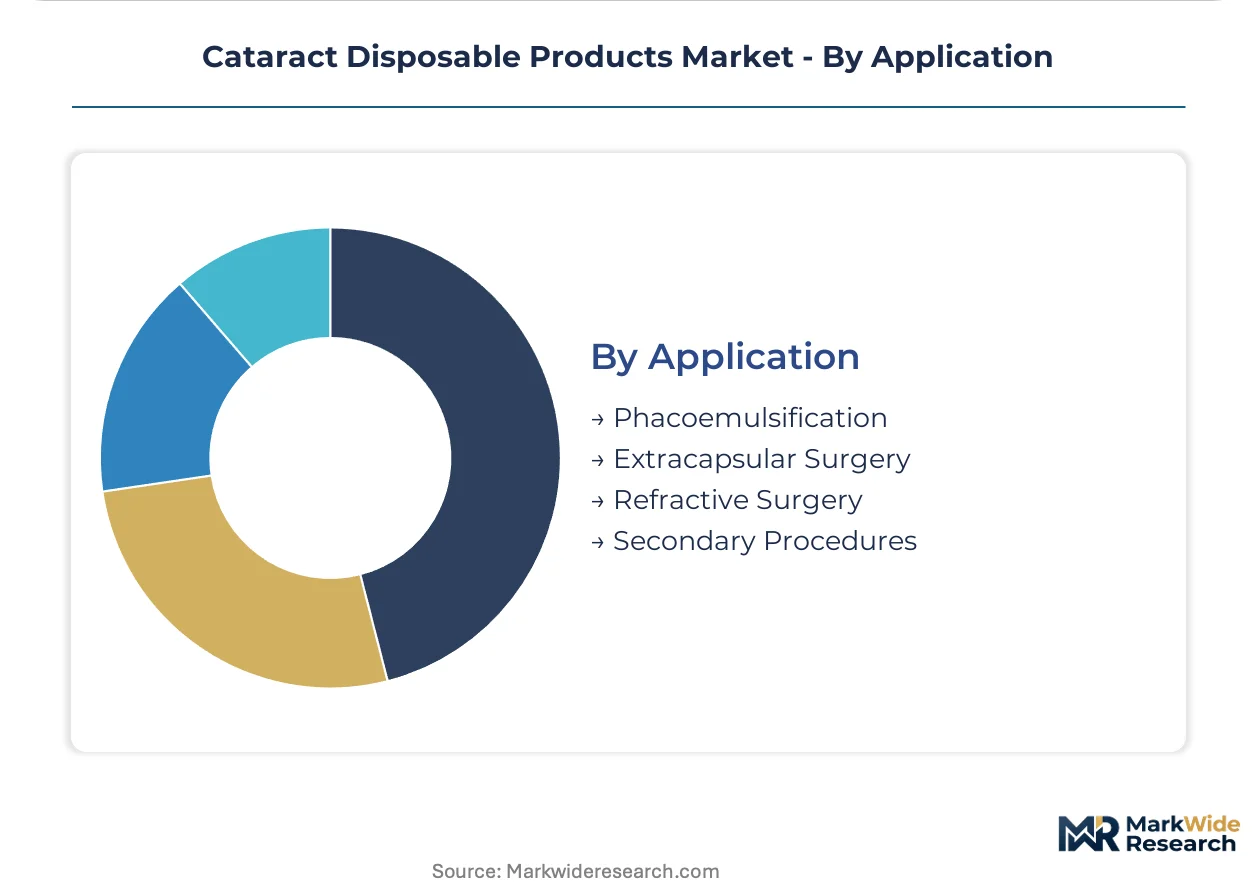
Application:
Procedure maturity diverges between established phacoemulsification volumes and emerging refractive-cataract convergence segments.
- Phacoemulsification:Ultrasound-based lens fragmentation with fluidics management. Next-generation platform upgrades demand matched disposable tubing sets with tighter particulate specifications.
- Refractive Surgery:Presbyopia-correcting and toric lens interventions. Premium positioning in complex case segments drives viscoelastic-sustained release convergence opportunities.
- Extracapsular Surgery:Manual expression techniques for dense cataracts. Declining volume in developed markets, persistent demand in resource-constrained settings.
- Secondary Procedures:IOL exchange, repositioning, or explantation. Patient registry requirements under EU MDR extend clinical follow-up obligations.
Phacoemulsification procedures anchor the volume base while refractive surgery applications expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a concentrated trade pattern where premium intraocular lenses flow from Swiss and German manufacturing clusters toward ambulatory surgical centers in the United States and ophthalmology corridors in India. Import dependency for hydrophobic acrylic feedstock shapes procurement strategies across emerging production hubs.
United States
Ambulatory surgical center expansion across Texas, Florida, and California drives pre-sterilized kit procurement at scale. FDA 510(k) clearance timelines for novel materials extend 18-24 months, freezing pipeline advancement for resource-constrained entrants. The Dallas-Fort Worth metroplex anchors distribution infrastructure for multi-site ASC chains consolidating purchasing decisions.
Germany
Notified body scrutiny under EU MDR compresses competitive access for new market entrants as German procurement offices specify exclusively MDR-certified kits. Precision optics manufacturing clusters in Oberkochen and Jena control quality thresholds for hydrophobic acrylic lens specifications. Baden-Württemberg's medical technology corridor concentrates sterile barrier validation expertise.
India
The PLI scheme for medical devices attracts contract molders to establish ISO 13485 facilities near Mumbai and Hyderabad surgical corridors. CDSCO import substitution policies accelerate domestic manufacturing of economy-tier sterile packs for public system volume targets. Maharashtra's surgical device manufacturing belt scales injection molding capacity for regional export.
Japan
PMDA post-market surveillance requirements align with extended clinical follow-up obligations for implantable lenses. METI medical device promotion programs support precision manufacturing of pre-loaded injector systems. The Nagoya medical technology cluster advances automation in sterile packaging for premium ophthalmic segments.
Brazil
SUS ophthalmology expansion targets create demand for economy-tier sterile packs with simplified instrumentation. ANVISA regulatory pathways for Class II devices shape entry strategies for multinational kit suppliers. São Paulo's surgical corridor concentrates procurement decision-making for public system cataract surgery volumes.
Cataract Disposable Products Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base stratifies between diversified ophthalmic conglomerates with polymer sourcing control and focused instrument specialists leveraging precision molding partnerships. Three archetypes dominate: integrated lens-injector manufacturers, sterile pack consolidators, and precision optics fabricators. M&A activity concentrates on injector system molding assets, while capacity expansion targets ISO Class 7 cleanroom infrastructure in emerging manufacturing hubs.
Within the integrated manufacturing tier, Alcon Inc and Johnson & Johnson Vision exemplify archetypes combining lens polymer sourcing with delivery system production. Carl Zeiss Meditec AG occupies a position representing precision optics manufacturing specialization. These three entities anchor competitive dynamics through differentiated control points across material complexity, regulatory burden management, and optical tolerance enforcement.
| Leading Market Players |
|---|
| Alcon Inc |
| Bausch & Lomb |
| Johnson & Johnson Vision |
| Carl Zeiss Meditec AG |
| NIDEK Co Ltd |
| HOYA Corporation |
| STAAR Surgical Company |
| Topcon Corporation |
| Ziemer Ophthalmic Systems AG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hydrophobic acrylic polymer suppliers and intraocular lens manufacturers lock in feedstock access while stabilizing input cost visibility across multi-year procurement cycles. These contracts concentrate pricing power with German and Swiss polymer specialists who control precision optical-grade resin specifications.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the cataract disposable products market. Price differentiation rests on ISO 11979 certification grade and volume scale, with MDR-validated sterile packs commanding premiums over FDA 510(k) cleared alternatives. Cost compression in economy-tier surgical drapes is intensifying because reusable textile substitutes gain traction in Brazil's public system. Multi-site ASC chains in the United States exhibit lowest price sensitivity due to consolidated kit procurement power, while independent ophthalmology clinics in India remain most price-conscious.
Supply Chain Analysis
Inventory buffers for hydrophobic acrylic feedstock stretch to six months as medical-grade silicone precursors face semiconductor sector competition. Manufacturing concentration centers on Germany, Switzerland, and the United States for precision lens-injector systems, while India and China scale injection molding for economy-tier sterile packs. Raw material dependencies include high-purity silicone precursors, PMMA resins, and polyimide filaments. Single-source vulnerability in European toolmaking for precision cavity designs creates structural supply risk. Distribution runs through GPO contracts and direct-to-ASC consignment models in the United States, with traditional distributor networks persisting in Europe and emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cataract disposable products market rewards players who control ISO Class 7 cleanroom operations and sterile barrier validation capabilities, assets that remain scarce outside established German and Swiss manufacturing clusters. Mastery of EU MDR compliance timelines separates viable competitors from stalled entrants.
For Market Incumbents: Secure captive supply of hydrophobic acrylic polymers through backward integration into lens material sourcing, insulating margin structures from semiconductor sector feedstock competition. Expand ISO 13485 certified capacity in Maharashtra's surgical device belt to capture India's PLI scheme incentives and anchor regional export platforms. Lock in multi-year kit procurement contracts with Texas and Florida ASC chains before competitor MDR certifications clear. For New Entrants and Emerging Players: Differentiate on viscoelastic-sustained release convergence for complex cataract segments, a white space where premium positioning remains underdeveloped. Target Brazil's SUS ophthalmology expansion with economy-tier sterile packs featuring simplified instrumentation, bypassing crowded premium lens markets. Pursue direct-to-ASC distribution partnerships in California surgical corridors to bypass entrenched distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sterile pack consolidators with multi-site ASC chain contracts, offering visibility through consignment inventory models. Over the medium-term horizon, acquisition priority rests on precision injector system molders with established European toolmaker relationships. Monitor FDA 510(k) clearance velocity for novel materials as an inflection signal for pipeline advancement capacity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | MDR-validated sterile barrier systems unlock German and French procurement office specifications exclusively. |
| Backward Integration into Polymer Sourcing | Captive hydrophobic acrylic supply insulates margin structures from semiconductor sector feedstock competition. |
| Multi-Site ASC Chain Partnership | Consolidated kit procurement contracts in Texas and Florida compress competitor access to high-volume corridors. |
| ISO Class 7 Cleanroom Expansion | Certified molding capacity in Maharashtra captures India's PLI scheme incentives and anchors regional export. |
| Viscoelastic-Sustained Release Development | Combining dispersive agents with intraoperative drug delivery opens premium positioning in complex case segments. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body databases, and hospital procurement contract disclosures preceded structured interviews with cataract surgeons, ASC operations directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from customs trade data for hydrophobic acrylic polymer flows, SEC 10-K medical device segment disclosures, and CDSCO manufacturing facility registrations. Bottom-up demand modeling across ambulatory surgical center expansion trajectories was triangulated with top-down market sizing from intraocular lens shipment volumes.
Variance decomposition across product type, delivery mode, end user, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity models and premium format adoption curves. Forecast inputs included phacoemulsification platform upgrade cycles and EU MDR compliance deadline impacts on competitive shelf space.
The analysis sits within stated boundaries; outcomes outside sustained ambulatory surgical center expansion or altered FDA sterile device guidelines would require recalibration. Forecasts reflect documented assumptions regarding MDR certification velocity and polymer feedstock availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Lab Trays Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Anti Venom Market