
 United States Endoscopy Devices Market | 2026-2036
United States Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Endoscopy Devices Market Analytics
The bifurcation between premium and commodity tiers in United States endoscopy devices is hardening as hospitals demand 4K imaging and AI-assisted polyp detection while cost-constrained clinics prioritize refurbished flexible scopes. Stryker Corporation leverages its surgical instruments portfolio to anchor integrated operating room ecosystems that bundle endoscopes with visualization towers. Olympus Corporation dominates the gastrointestinal flexible endoscope segment through its dominant service network and proprietary channel architecture across major health systems.
Endoscopy devices encompass illuminated, tubular instruments—typically 2.8–13 mm in diameter with working channels of 1.2–3.7 mm—designed for minimally invasive internal visualization, biopsy retrieval, and therapeutic intervention through natural orifices or small incisions. Their primary purpose centers on diagnostic confirmation and surgical precision without open procedures, reducing patient recovery time and facility costs. Flexible endoscopes command the largest installed base due to their essential role in colonoscopy and esophagogastroduodenoscopy workflows, while robotic endoscopy represents the fastest-expanding technology segment as systems like Medtronic's platform target autonomous navigation capabilities. Ambulatory surgical centers constitute the fastest-growing end-user channel as payor incentives and site-of-service policies redirect volume away from inpatient settings.
FDA 510(k) clearance requirements and HIPAA data security mandates govern device commercialization and connected imaging systems, respectively, elevating compliance costs but also creating barriers against low-cost imports. The Centers for Medicare & Medicaid Services reimbursement schedules directly influence hospital capital allocation cycles for endoscopy suite upgrades. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostic features and site-neutral payment policies that could redistribute volume across hospital and non-hospital settings.
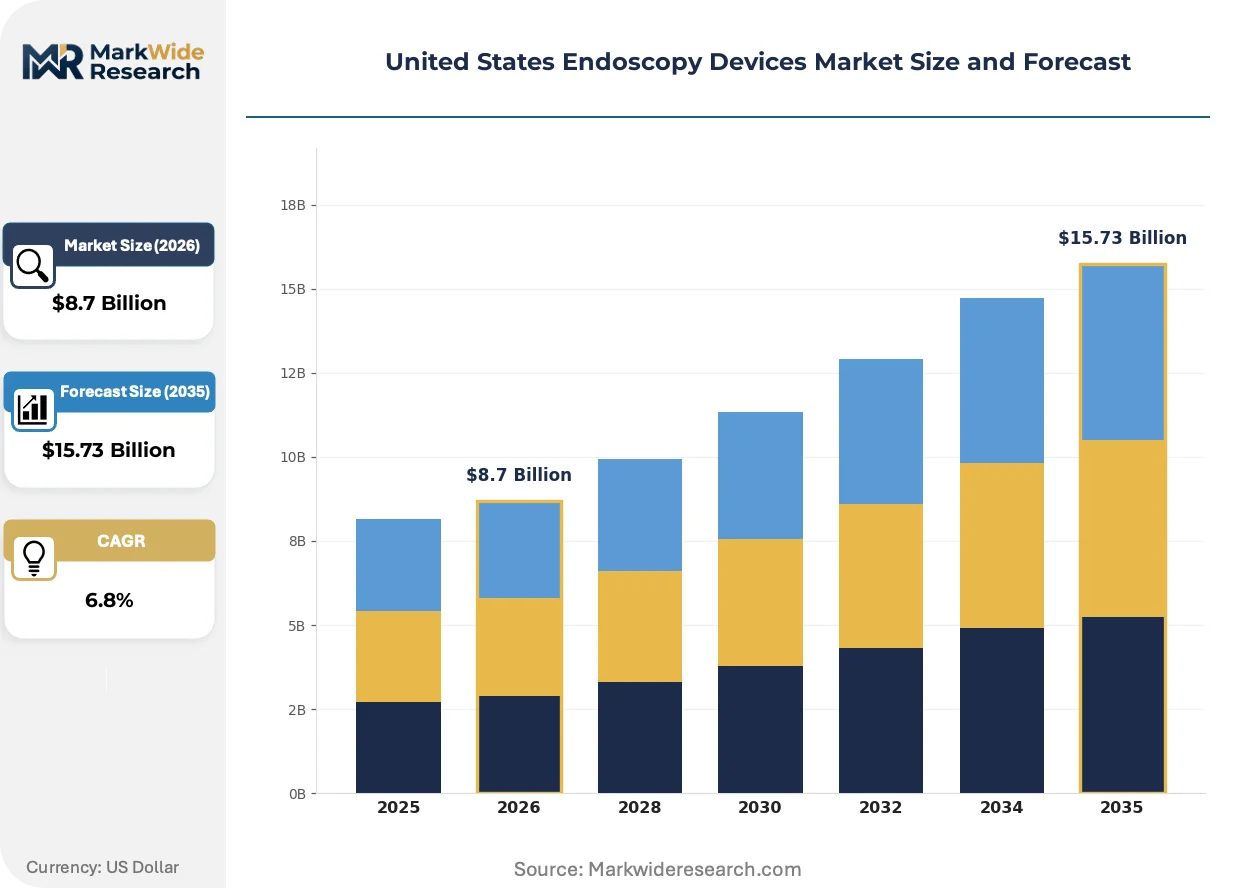
Market Dynamics
Site-neutral payment policies from CMS are accelerating patient volume migration toward ambulatory surgical centers, forcing hospital systems to defend their endoscopy service lines through capital-intensive suite upgrades and AI-enabled diagnostic differentiation.
Growth Catalysts
- CMS site-neutral reimbursement expansion:Medicare payment parity between hospital outpatient departments and freestanding ASCs redirects colonoscopy and upper endoscopy volume toward lower-cost settings.
- AI-assisted polyp detection integration:FDA-cleared computer-aided detection systems embedded in visualization towers improve adenoma detection rates and justify premium capital equipment replacement cycles.
- Southeast and Texas health system consolidation:Regional hospital networks in these states are standardizing endoscopy platforms across acquired facilities, driving bulk procurement of flexible scopes and processor towers.
Market Restraints
- Single-use endoscope cost premium:Disposable flexible scopes carry per-procedure costs 3-5x above reprocessed devices, limiting adoption to high-contamination-risk cases despite infection control benefits.
- Japanese and German optical component concentration:Specialized CMOS sensors and fiber optic bundles for high-definition scopes source from a narrow supplier base in these geographies, creating input vulnerability.
- FDA 510(k) substantial equivalence barriers:Novel endoscope designs lacking predicate devices face de novo pathway timelines extending commercialization by 18-24 months versus traditional clearances.
Strategic Opportunities
- Rural and non-metro ASC penetration:Underserved counties in the Mountain West and Great Plains present whitespace for de novo ambulatory endoscopy center development with favorable certificate-of-need environments.
- Robotic-assisted autonomous navigation:Convergence of magnetic steering platforms with real-time computer vision enables single-operator procedures reducing labor dependency.
- IRA Medicare price negotiation spillover:Hospital pharmaceutical cost containment pressures free capital for diagnostic equipment substitution toward higher-margin outpatient procedural revenue.
Industry Challenges
- Gastroenterologist workforce pipeline constraints:Fellowship training slots fail to match ASC expansion velocity, creating proceduralist scarcity in high-growth markets.
- Legacy scope reprocessing compliance burden:Joint Commission and state health department scrutiny of high-level disinfection protocols demands dedicated sterile processing infrastructure investment.
- Interoperability with EMR and PACS architectures:DICOM conformance and HL7 FHIR integration requirements extend implementation timelines for connected imaging ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Endoscopy Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Endoscopic Ultrasound End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Technology: Video Endoscopy, Fiber-Optic Technology, Robotic Endoscopy, Wireless Endoscopy Application: Gastrointestinal Surgery, Pulmonary Procedures, Urological Procedures, Otolaryngology |
| Companies Covered | Stryker Corporation, Cook Medical, Boston Scientific Corporation, Fujifilm Holdings Corporation, KARL STORZ SE & Co. KG, Olympus Corporation, Johnson & Johnson, CONMED, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Endoscopy Devices Market Evolving Landscape
Endoscopy device evolution centers on computational imaging convergence, regulatory pathway adaptation for software-enabled diagnostics, and procurement model restructuring that unbundles capital acquisition from per-procedure economics.
Single-use flexible endoscopes are absorbing contamination liability and reprocessing capital burden from health system balance sheets. ASCs in competitive metropolitan markets adopt these devices fastest, eliminating scope damage depreciation and sterile processing labor. The technology is absorbing mid-tier refurbished scope demand as buyers prioritize infection risk elimination over per-procedure cost minimization.
FDA draft guidance on predetermined change control plans for AI-enabled devices is reshaping software update commercialization. Manufacturers must pre-specify modification protocols to maintain 510(k) validity across algorithm iterations. Gastrointestinal visualization platforms with embedded polyp detection face the steepest compliance adaptation, requiring documented performance validation across demographic subgroups.
Hospital capital committees now evaluate endoscopy suites through total cost-of-ownership frameworks incorporating disposable instrument flows, service contract structures, and revenue-per-room-hour metrics. Bundled payment pilots for colonoscopy screening episodes accelerate this analytical shift. Texas and Florida health systems demonstrate the most advanced procurement sophistication, pressuring vendors toward outcome-guaranteed equipment performance contracts.
United States Endoscopy Devices Market Segmentation
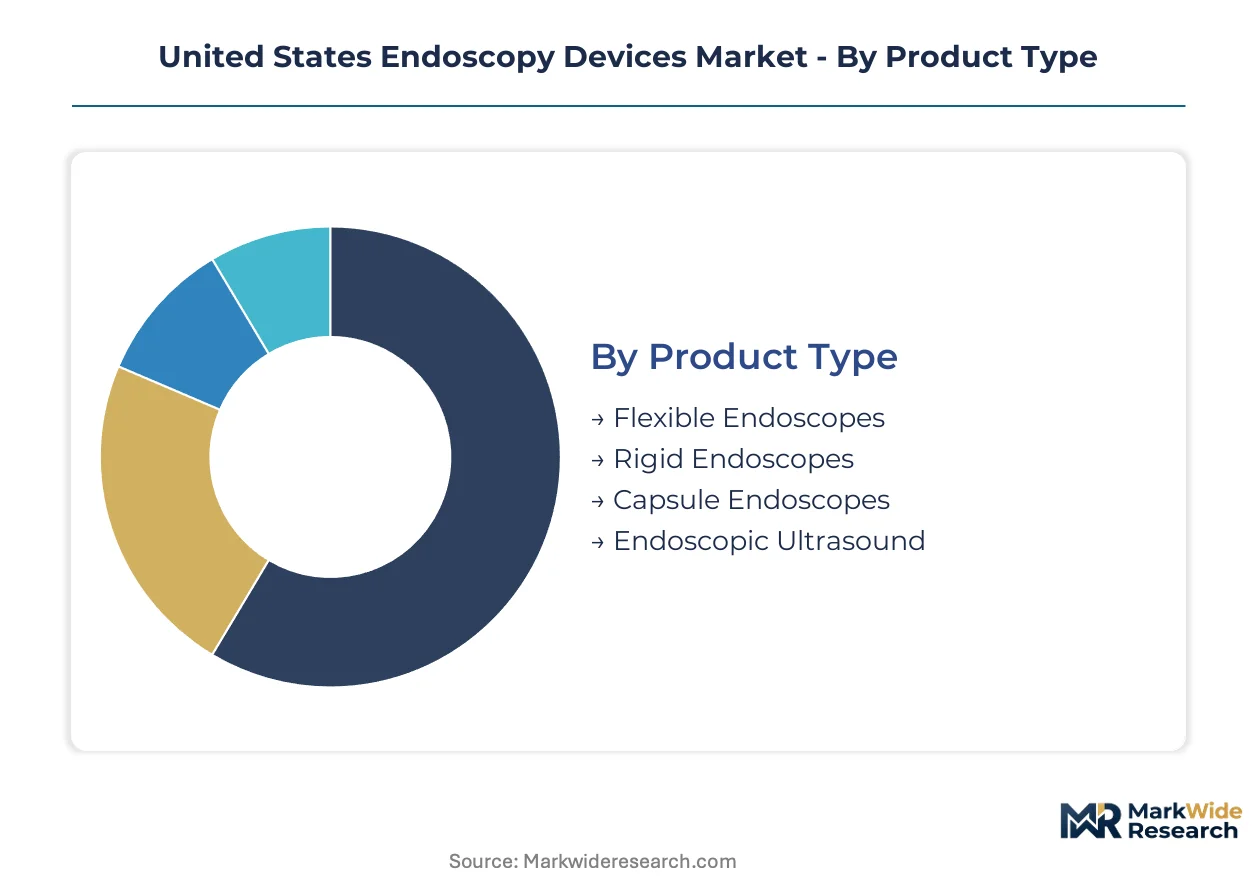
Endoscopy device segmentation in the United States reflects divergent procurement economics across care settings and the accelerating shift toward disposable and AI-enabled platforms. Understanding these segment boundaries clarifies where capital equipment investments concentrate versus where per-procedure consumables dominate purchasing decisions.
Product Type:
Flexible endoscopes function as standalone capital assets requiring dedicated processor towers and reprocessing infrastructure, while rigid and capsule systems embed more directly into surgical workflows or patient-administered diagnostics.
- Flexible Endoscopes:These instruments incorporate articulating distal tips with 1.2–3.7 mm working channels for biopsy forceps and therapeutic devices. Demand concentrates in hospital gastrointestinal suites across Texas and Florida health systems, where capital budgets for 4K visualization upgrades have expanded. Reprocessing compliance costs and infection liability are accelerating single-use alternatives in high-volume ASCs.
- Rigid Endoscopes:Stainless steel optical systems with fixed angles of 0°, 30°, and 70° serve arthroscopy, laparoscopy, and urology procedures. Orthopedic ASCs in the Southeast favor these for durability and sterilization efficiency, though video integration requirements elevate total system costs beyond standalone instrument pricing.
- Capsule Endoscopes:Ingestible wireless imaging platforms for small bowel evaluation.
- Endoscopic Ultrasound:Hybrid devices combining endoscopic access with radial or linear ultrasound transducers for fine-needle aspiration.
Flexible endoscopes lead volumes today; capsule endoscopy is gaining share fastest.
End User:
Procurement authority and payment model differences across customer types reshape vendor go-to-market strategies and equipment financing structures.
- Hospitals:Integrated delivery networks with centralized capital committees evaluate endoscopy platforms through 7–10 year total cost-of-ownership models. The Southeast and Texas hospital systems drive bulk standardization across acquired facilities, with FDA 510(k) clearance timelines influencing replacement cycle synchronization.
- Ambulatory Surgical Centers:Freestanding facilities with site-neutral CMS reimbursement privileges prioritize per-procedure economics and room turnover efficiency. These centers in competitive metropolitan markets adopt single-use scopes fastest to eliminate reprocessing labor and contamination liability.
- Specialty Clinics:Gastroenterology and pulmonology focused practices with limited capital budgets.
- Diagnostic Laboratories:Pathology-focused facilities processing endoscopically retrieved specimens.
Hospitals retain the largest installed base; ambulatory surgical centers are expanding most quickly.
Technology:
Imaging modality selection determines integration complexity with electronic medical records and downstream AI diagnostic layers.
- Video Endoscopy:CMOS and CCD sensor-based systems with digital signal processing for high-definition output. These platforms anchor hospital upgrade cycles, with 4K resolution and AI-assisted polyp detection now standard in Southeast health system RFPs.
- Robotic Endoscopy:Magnetically steered or autonomous navigation systems targeting single-operator procedures. Medtronic's platform and competing entrants focus on reducing gastroenterologist labor dependency as workforce constraints intensify.
- Fiber-Optic Technology:Legacy illumination and image transmission systems in cost-sensitive settings.
- Wireless Endoscopy:Radio-frequency data transmission for capsule and portable platforms.
Video endoscopy dominates current installations; robotic endoscopy shows the steepest expansion trajectory.
Application:
Procedure volume concentration and reimbursement rates across clinical specialties dictate capital allocation priority within health system endoscopy service lines.
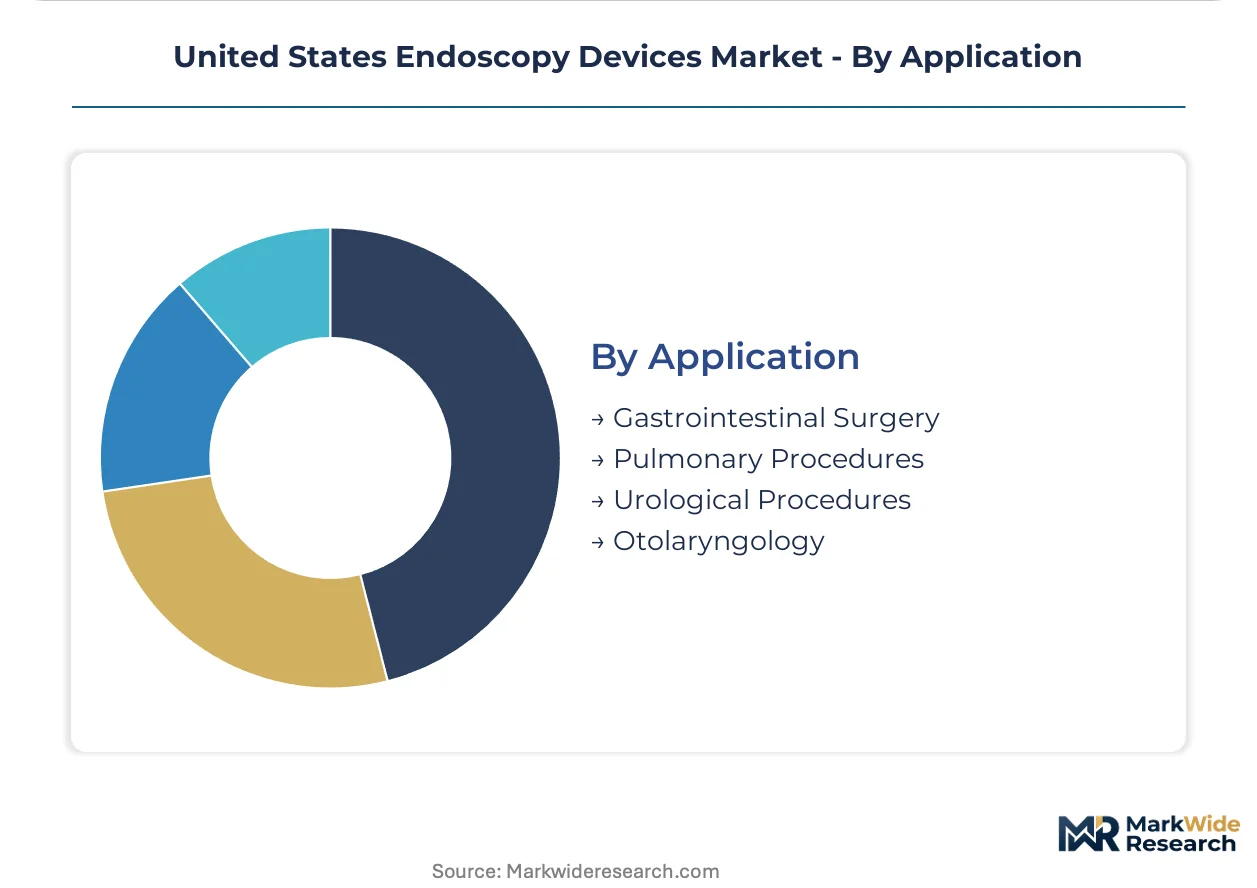
- Gastrointestinal Surgery:Colonoscopy, esophagogastroduodenoscopy, and advanced therapeutic procedures including endoscopic mucosal resection. CMS screening coverage and site-neutral payment policies redirect volume toward ASCs, while AI detection integration justifies premium equipment replacement in hospital settings.
- Pulmonary Procedures:Bronchoscopy and navigational biopsy for lung nodule evaluation. Interventional pulmonology expansion in academic medical centers drives demand for ultrasound-guided platforms and electromagnetic navigation systems.
- Urological Procedures:Cystoscopy and ureteroscopy for diagnostic and stone management applications.
- Otolaryngology:Laryngoscopy and sinus endoscopy in office-based and surgical settings.
Gastrointestinal surgery commands the largest procedure volume; pulmonary applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gastroenterologist concentration in Texas and Florida health systems anchors regional demand patterns. FDA 510(k) clearance timelines and CMS site-neutral payment policies reshape capital allocation across state-level procurement cycles. Metropolitan ASC clusters in competitive markets drive single-use scope adoption fastest.
Texas
Hospital system consolidation across Dallas-Fort Worth and Houston creates bulk procurement leverage for endoscopy platform standardization. State certificate-of-need regulations for ASC development remain permissive relative to coastal jurisdictions. The Texas Medical Center complex anchors interventional gastroenterology training pipelines that feed regional workforce expansion.
Florida
Southeast retiree demographics concentrate colonoscopy screening demand in Tampa Bay and South Florida corridors. State Medicaid managed care expansion influences hospital capital committee prioritization of outpatient procedural revenue. Jacksonville and Orlando health systems demonstrate the most advanced total cost-of-ownership procurement frameworks nationally.
Southeast (Georgia, North Carolina, Tennessee)
Atlanta and Charlotte health networks standardize acquired facility equipment post-consolidation. Certificate-of-need restrictions in North Carolina constrain greenfield ASC development relative to neighboring states. Research Triangle Park academic medical centers pilot AI-assisted polyp detection integration for adenoma detection rate improvement.
California
Integrated delivery networks in Los Angeles and Bay Area metros negotiate outcome-guaranteed equipment performance contracts. State-level infection control mandates exceed federal minimums, elevating single-use scope economics in high-volume centers. Stanford and UCSF academic anchors drive robotic endoscopy clinical trial enrollment.
Northeast Corridor (New York, Massachusetts, Pennsylvania)
Academic medical center density in Boston and Manhattan sustains premium visualization tower replacement cycles. Pennsylvania hospital systems defend endoscopy volume against ASC migration through AI-enabled diagnostic differentiation. New York State CON regulations limit freestanding ASC penetration in downstate markets.
United States Endoscopy Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the United States endoscopy devices landscape. The market structure concentrates around integrated visualization platform vendors and specialized flexible scope manufacturers. Three archetypes dominate: diversified surgical conglomerates bundling endoscopes with OR ecosystems; pure-play endoscopy specialists leveraging service network density; and disposable scope entrants unbundling reprocessing economics. M&A activity targets AI-enabled diagnostic capabilities and ASC-focused distribution channels.
Among diversified surgical conglomerates, Stryker Corporation and Johnson & Johnson exemplify platform bundling strategies that anchor integrated operating room ecosystems. Olympus Corporation occupies a distinct position as a pure-play endoscopy specialist with proprietary channel architecture. Boston Scientific Corporation represents the interventional therapeutic vector, bridging diagnostic visualization with procedural device integration. These three anchors illustrate how vendor archetypes map to distinct procurement authority centers—hospital capital committees, ASC operating partners, and academic medical center value analysis committees.
| Leading Market Players |
|---|
| Stryker Corporation |
| Cook Medical |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Johnson & Johnson |
| CONMED |
| Medtronic PLC |
| Others |
Value Network & Pricing Analysis
FDA infection control mandates gate qualified supply for flexible endoscope manufacturers while simultaneously stratifying pricing access across hospital and ASC buyer archetypes. Premium-tier 4K visualization platforms command capital committee approval only where reprocessing compliance infrastructure justifies total cost-of-ownership frameworks.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only procurement splits the market into divergent pricing regimes. Hospital systems negotiate seven-year total cost-of-ownership agreements incorporating preventive maintenance and software upgrade rights, while ASCs favor per-procedure disposable scope economics with minimal capital commitment. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance tier and AI-enabled diagnostic feature inclusion. Cost compression in refurbished flexible scopes intensifies as single-use alternatives absorb mid-tier demand. Specialty clinics exhibit highest price sensitivity, deferring processor tower upgrades until reimbursement parity stabilizes.
Supply Chain Analysis
Workforce availability constraints in Japanese and German precision optics manufacturing elevate lead times for CMOS sensor and fiber optic bundle inputs. Component sourcing draws from concentrated supplier bases in these geographies, with specialized illumination systems and high-definition image sensors anchoring flexible endoscope production. Tariff exposure on Japanese optical components creates margin vulnerability for domestic tower assemblers. Distribution runs through GPO-negotiated contracts with hospital systems and direct-to-ASC disposable scope channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States endoscopy devices market functions as a stable compounder anchored by CMS screening coverage expansion and irreversible outpatient migration toward ASC settings.
For Market Incumbents: Extend service network density in Texas and Florida health systems to defend against disposable scope entrants unbundling reprocessing economics. Consolidate AI-enabled diagnostic capabilities through proprietary algorithm development, as FDA predetermined change control plans raise compliance barriers for follower platforms. Prioritize backward integration into visualization processor manufacturing to capture margin from optical component supply constraints. For New Entrants and Emerging Players: Begin with rural Mountain West ASC development where certificate-of-need environments permit greenfield facility construction and gastroenterologist scarcity remains acute. Target non-metro counties in the Great Plains with site-neutral reimbursement privileges and limited incumbent service coverage. Pursue GPO contract access through outcome-guaranteed equipment performance structures that align capital cost with adenoma detection rate improvement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap robotic endoscopy platforms with autonomous navigation capabilities but pre-revenue hospital adoption. Long-term viability hinges on FDA de novo pathway execution and single-operator procedure validation across the projection horizon. Acquisition target archetypes include AI-assisted polyp detection software developers with embedded visualization tower integrations. The signal to watch is CMS site-neutral payment policy expansion into therapeutic procedures beyond diagnostic colonoscopy.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Enabled Detection | Clears predetermined change control pathways for algorithm iteration without redundant review cycles. |
| Hospital System Partnership for Platform Standardization | Locks bulk procurement commitments across Southeast and Texas consolidated networks. |
| Software Companion Development for EMR Integration | Resolves HL7 FHIR interoperability requirements extending implementation timelines. |
| Reimbursement Strategy for Site-Neutral Expansion | Aligns ASC equipment financing with Medicare payment parity between hospital outpatient departments. |
| CE Marking Pathway for Optical Component Export | Opens European market access for Japanese and German supplier-dependent manufacturers. |
Research Methodology
Coverage spans the Southeast, Texas, Florida, California, and Northeast Corridor, with primary inputs from each region's hospital procurement committees and ASC operating partners. The analysis combines structured interviews with gastrointestinal suite directors, biomedical engineers, GPO contracts managers, and ambulatory center administrators with secondary validation against FDA 510(k) clearance databases, CMS Medicare cost report filings, and hospital capital expenditure disclosures. Bottom-up procedure volume estimates triangulate with top-down health system equipment standardization announcements.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type segmentation between flexible, rigid, capsule, and endoscopic ultrasound platforms alongside technology tiers spanning video, robotic, fiber-optic, and wireless modalities. CAGRs derive from installed base replacement cycles, ASC de novo development permits, and AI-enabled feature adoption curves. Forecast inputs incorporate gastroenterologist fellowship graduation rates and site-neutral reimbursement policy implementation velocity.
Several conditions sit outside the modeled scope, including abrupt FDA guidance revision on AI-enabled devices, state-level certificate-of-need regulation repeal, and tariff restructuring on Japanese optical components. Forecasts reflect assumptions regarding stable CMS screening coverage and continued outpatient volume migration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Polyp Biopsy Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
China Arthroscopy Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Disposable Bronchoscopes Market