
 Global Veterinary Endoscopes Market | 2026-2036
Global Veterinary Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Endoscopes Market Foresight
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over calibration, repair, and replacement part channels. KARL STORZ SE & Co. KG leverages its vertically integrated service network to capture recurring revenue from installed base maintenance. Olympus Corporation sustains competitive pressure through dedicated veterinary service contracts that lock in multi-year client relationships. Fujifilm Holdings Corporation differentiates by offering remote diagnostics integration that reduces clinic downtime.
Veterinary endoscopes are optical instruments designed for internal examination of animal patients, typically employing fiberoptic or digital image sensor technology with working channels ranging from 1.2 to 2.8 millimeters for instrument passage and irrigation. These devices enable minimally invasive visualization of gastrointestinal, respiratory, and urogenital tracts, reducing surgical trauma and recovery time in companion and production animals. Flexible endoscopes dominate procedure volumes due to their maneuverability through tortuous anatomical pathways, while single-use endoscopes represent the fastest-expanding product category as infection control protocols intensify in multi-species clinical settings. Digital processing capabilities now determine purchasing criteria across veterinary clinics and animal hospitals, with wireless connectivity emerging as a margin-differentiating feature.
FDA Center for Veterinary Medicine oversight shapes device classification and pre-market notification pathways for instruments used in food-producing animals, while CE marking under the EU MDR imposes clinical evidence and post-market surveillance obligations on manufacturers distributing in Europe. ISO 13485 certification has become a baseline qualification for supplier qualification programs at large veterinary hospital chains. Stakeholders must monitor evolving sterilization validation requirements and digital health integration standards as regulatory frameworks adapt to single-use and AI-assisted endoscopic platforms.
Market Dynamics
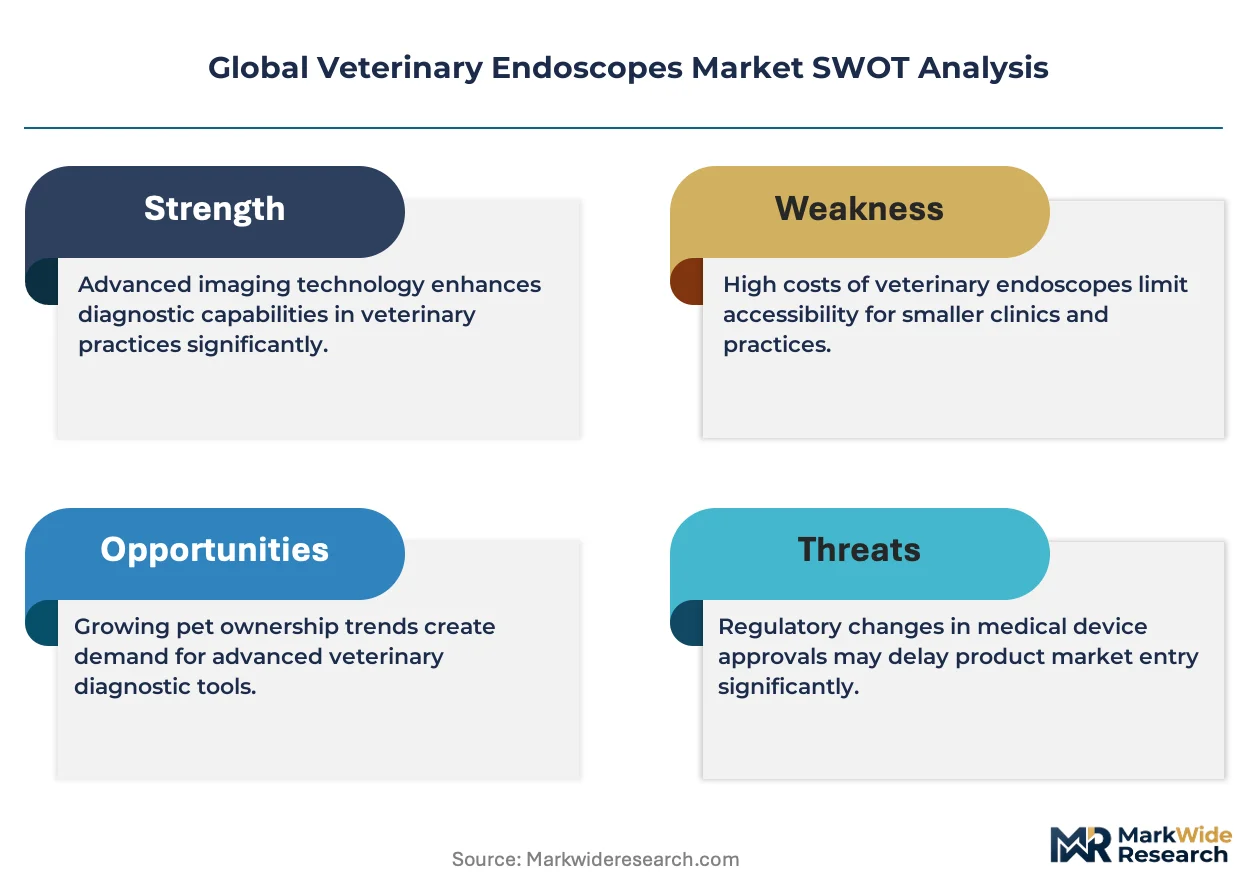
Consolidation among companion animal hospital chains is compressing vendor margins while simultaneously locking in multi-year equipment refresh cycles that favor established manufacturers with integrated service networks.
Growth Catalysts
- EU MDR CE marking acceleration:Veterinary device manufacturers are intensifying clinical evidence collection to secure European market access, expanding compliant product portfolios ahead of competitor exits.
- Minimally invasive surgical protocols:Specialty veterinary practices in the United States and Germany are standardizing flexible endoscopy for diagnostic and interventional procedures, displacing open surgical approaches.
- Single-use endoscope manufacturing scale-up:Contract manufacturers in China and South Korea are expanding cleanroom capacity to serve Western veterinary OEMs seeking infection control differentiation.
Market Restraints
- Optical component supply concentration:CCD and CMOS sensor fabrication concentrates in Taiwanese and Japanese foundries, exposing veterinary endoscope assemblers to semiconductor allocation volatility.
- Veterinarian training pipeline constraints:Accredited residency programs in diagnostic imaging and minimally invasive surgery produce fewer diplomates than hospital expansion requires, throttling procedure volume growth.
- Reimbursement code fragmentation:Private pet insurance plans in the United States and Germany maintain inconsistent coverage for endoscopic procedures, creating price sensitivity at the point of care.
Strategic Opportunities
- Artificial intelligence-assisted polyp detection:Machine vision algorithms trained on human endoscopy datasets are transferring to veterinary gastrointestinal applications, enabling automated pathology screening.
- Telemedicine-integrated remote diagnostics:Wireless endoscope systems with real-time video streaming allow centralized specialists to guide procedures at rural clinics, extending geographic reach.
- Brazilian and Mexican specialty practice formation:Emerging middle-class pet ownership in Latin America is financing the first wave of dedicated veterinary endoscopy centers outside OECD markets.
Industry Challenges
- ISO 13485 quality management system maintenance:Small veterinary device manufacturers struggle to sustain auditor-mandated documentation burdens as notified body capacity tightens under EU MDR.
- Legacy fiberoptic instrument obsolescence:Clinics with substantial capital investment in non-digital endoscope inventories face write-down pressure as image sensor technology becomes standard.
- Cross-species sterilization validation:Multi-species hospitals must demonstrate lethal efficacy against prion, viral, and bacterial agents across divergent endoscope channel geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Endoscopes Market |
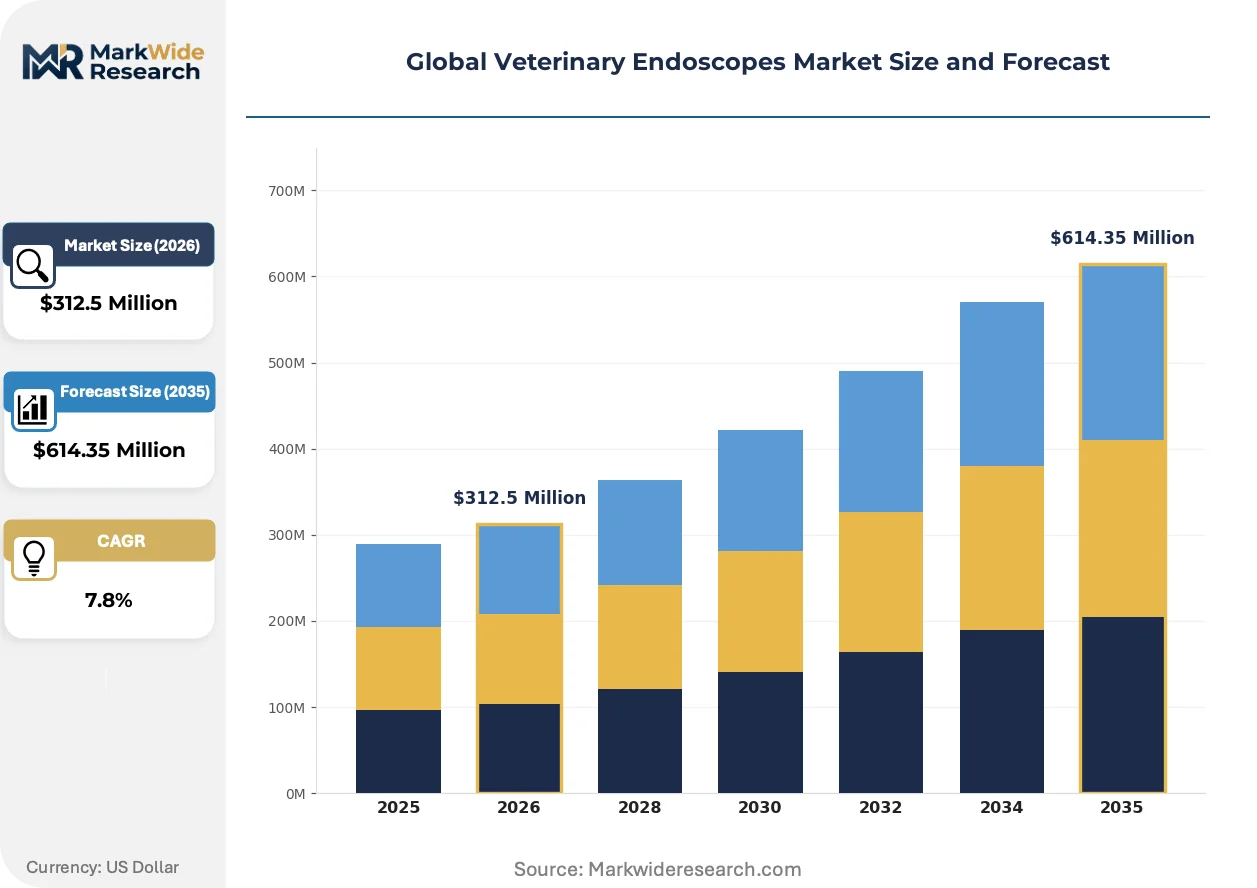
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Single-Use Endoscopes Application: Gastrointestinal Procedures, Respiratory Examinations, Urogenital Inspections, Surgical Assistance, Orthopedic Assessments End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Mobile Veterinary Services, Wildlife Rehabilitation Centers Technology: Imaging Systems, Light Source Types, Miniaturization Techniques, Wireless Connectivity, Digital Processing |
| Companies Covered | KARL STORZ SE & Co. KG, Olympus Corporation, Steris, Biovision Veterinary Endoscopy, Dr. Fritz Endoscopes GmbH, Eickemeyer, Fujifilm Holdings Corporation, Endoscopy Support Services, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Endoscopes Market Shifts & Advancements
Digital image sensor technology is collapsing the cost-performance frontier between human and veterinary endoscopy, while regulatory frameworks and procurement models adapt to single-use and connected device categories.
Disposable endoscope technology is collapsing the capital-labor tradeoff that previously constrained small-practice adoption. Single-use flexible scopes with integrated CMOS sensors now achieve optical parity with reusable systems at per-procedure costs below reprocessing labor plus depreciation. Veterinary hospital chains in Germany and Japan are piloting subscription models that bundle instrument supply with procedure training, compressing the traditional equipment financing cycle from seven years to monthly operational expenditure.
CE marking under the EU MDR is forcing veterinary endoscope manufacturers to construct clinical evidence packages previously reserved for human devices. The regulation's post-market surveillance requirements mandate systematic complaint handling and periodic safety updates that strain quality management resources at mid-tier suppliers. German and Swiss manufacturers with existing human-device regulatory infrastructure are absorbing compliance costs more efficiently than pure-play veterinary specialists, reshaping competitive positioning in European distribution channels.
After-sales service unbundling is fragmenting the traditional OEM-captive maintenance model. Third-party repair technicians with ISO 13485-certified facilities are capturing calibration and refurbishment volume from manufacturers attempting to enforce proprietary parts channels. This shift is most visible in the United States, where antitrust scrutiny of repair restrictions and right-to-repair legislation in multiple states are accelerating independent service organization formation.
Global Veterinary Endoscopes Market Segmentation
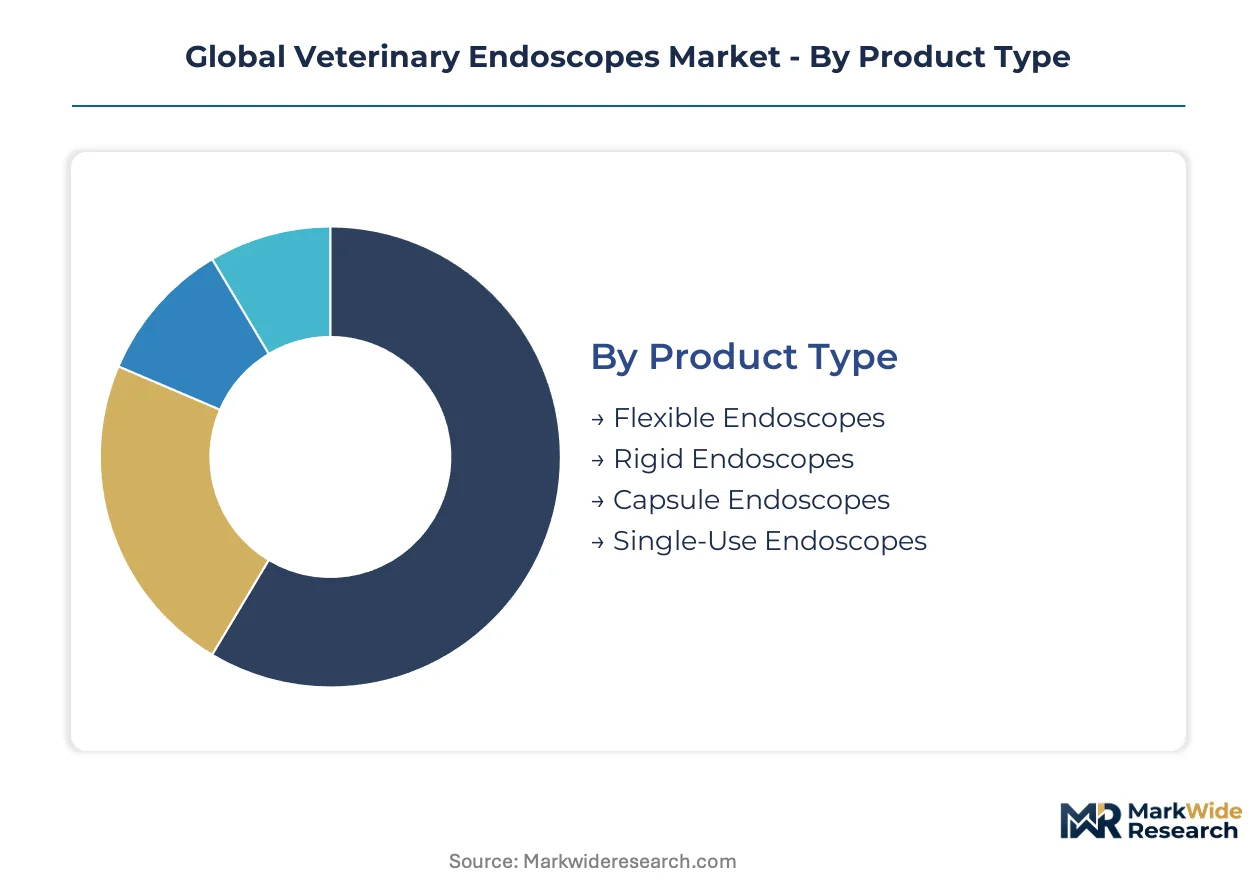
Veterinary endoscope procurement cycles vary dramatically across product categories, with capital-intensive flexible systems turning over every five to seven years while disposable alternatives rotate monthly. Understanding these differential replacement rhythms enables manufacturers to align service contracts and inventory financing with actual utilization patterns.
Product Type:
Cycle times diverge sharply: reusable flexible and rigid systems depreciate over multi-year horizons while single-use alternatives convert capital expenditure to per-procedure operational costs.
- Flexible Endoscopes:Fiberoptic or video-based instruments with articulating distal tips navigate tortuous gastrointestinal and respiratory anatomy in companion animals. Demand concentrates in United States and German specialty hospitals where minimally invasive diagnostic protocols displace exploratory surgery.
- Single-Use Endoscopes:Polymer-bodied disposable scopes with integrated CMOS sensors eliminate reprocessing labor and cross-contamination risk in multi-species settings. Veterinary chains in Japan and the United Kingdom are piloting subscription supply models that compress procurement from capital cycles to monthly operational expenditure.
- Rigid Endoscopes:Stainless steel optical systems with fixed angles serve orthopedic and laparoscopic interventions where instrument durability matters.
- Capsule Endoscopes:Ingestible wireless imagers transmit gastrointestinal video during natural transit, limited by retrieval requirements in non-food animal species.
Flexible endoscopes anchor the volume base while single-use alternatives gain share at the steepest rate.
Application:
Procedure reimbursement patterns and clinical training availability determine which applications absorb capital investment versus remain underserved.
- Gastrointestinal Procedures:Esophagogastroduodenoscopy and colonoscopy represent the highest-volume indication category, enabled by established veterinary residency training pipelines in diagnostic imaging. United States university teaching hospitals drive protocol standardization that filters to private specialty practices.
- Respiratory Examinations:Bronchoscopy and tracheoscopy enable minimally invasive sampling of pulmonary pathology in canine and feline patients. German and Japanese referral centers are expanding interventional capabilities beyond diagnosis to include foreign body retrieval and stent placement.
- Urogenital Inspections:Cystoscopy and vaginoscopy support reproductive and lower urinary tract assessment in breeding and companion animal populations.
- Surgical Assistance:Laparoscopic and thoracoscopic visualization guides minimally invasive soft tissue and orthopedic procedures.
- Orthopedic Assessments:Arthroscopy permits direct joint visualization for ligament and cartilage evaluation in equine and small animal sports medicine.
Gastrointestinal applications generate the installed base concentration while respiratory examinations expand procedure mix most rapidly.
End User:
Customer scale and case complexity create tiered demand profiles from high-volume institutional purchasers to dispersed mobile operators.
- Animal Hospitals:Multi-specialty referral institutions with dedicated surgery and internal medicine departments maintain the deepest endoscope inventories. Consolidated United States chains like Mars Veterinary Health and independent German Tierkliniken drive standardized equipment specifications across facility networks.
- Veterinary Clinics:General practice settings with limited specialist access concentrate demand on flexible gastrointestinal systems for routine diagnostic screening. Japanese companion animal clinics are adopting compact video endoscope systems with tablet-based displays to overcome space constraints.
- Research Institutes:Academic and pharmaceutical research facilities utilize endoscopy for longitudinal toxicology studies and device development validation.
- Mobile Veterinary Services:Ambulatory practitioners serving rural and agricultural populations prioritize portable, battery-powered rigid systems for field reproductive and basic surgical applications.
- Wildlife Rehabilitation Centers:Non-profit and governmental facilities treating injured native species require specialized small-diameter flexible scopes adapted to avian and exotic mammal anatomy.
Animal hospitals command the capital deployment volume while mobile veterinary services represent the most underserved penetration opportunity.
Technology:
Component sophistication and integration depth separate premium-tier systems from value-oriented alternatives across the procurement spectrum.
- Digital Processing:High-definition and 4K image signal processors with advanced noise reduction and color enhancement algorithms now define purchasing criteria at leading institutions. United States specialty practices are demanding HDMI and USB-C output compatibility for seamless integration with practice management software and telemedicine platforms.
- Wireless Connectivity:Bluetooth and Wi-Fi enabled scopes transmit real-time video to tablets and centralized displays, eliminating cable management constraints in compact procedure suites. German manufacturers are embedding encrypted transmission protocols to satisfy EU GDPR requirements for patient data protection.
- Imaging Systems:CCD and CMOS sensor architectures determine optical resolution and low-light performance characteristics.
- Light Source Types:LED and xenon illumination systems affect tissue color rendering and heat generation at the distal tip.
- Miniaturization Techniques:Advanced polymer extrusion and micro-machining enable sub-2mm working channels in pediatric and exotic species applications.
Digital processing capabilities anchor purchasing decisions while wireless connectivity features differentiate margin tiers most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States companion animal hospitals deploy flexible endoscopy for routine diagnostic screening at substantially higher per-capita rates than German or Japanese counterparts, where interventional capabilities and capital-intensive specialty centers dominate procurement patterns.
United States
Consolidated veterinary hospital chains like Mars Veterinary Health drive standardized equipment specifications across multi-state networks, compressing vendor negotiation cycles. FDA Center for Veterinary Medicine oversight shapes device classification pathways for instruments used in food-producing animals. University teaching hospitals in California and North Carolina anchor protocol standardization that filters to private specialty practices nationwide.
Germany
Tierkliniken referral centers expand interventional bronchoscopy capabilities beyond diagnosis to foreign body retrieval and stent placement. CE marking under the EU Medical Device Regulation imposes clinical evidence and post-market surveillance obligations that strain quality management resources at mid-tier suppliers. Manufacturing clusters in Baden-Württemberg and Bavaria absorb compliance costs more efficiently than pure-play veterinary specialists.
Japan
Companion animal clinics adopt compact video endoscope systems with tablet-based displays to overcome space constraints in dense urban markets. METI standards influence digital health integration requirements for wireless connectivity features. Tokyo and Osaka metropolitan areas concentrate the first wave of subscription-based single-use endoscope pilots that compress procurement from capital cycles to monthly operational expenditure.
United Kingdom
Veterinary chains pilot subscription supply models for single-use flexible scopes with integrated CMOS sensors. GDPR requirements shape encrypted transmission protocol adoption for wireless-enabled systems. The Southeast England corridor concentrates specialty practice formation that locks in multi-year equipment refresh cycles favoring established manufacturers.
Brazil
Emerging middle-class pet ownership finances the first wave of dedicated veterinary endoscopy centers outside OECD markets. ANVISA regulatory pathways for imported medical devices influence distributor selection criteria for multinational OEMs. São Paulo state anchors specialty practice formation with capital equipment procurement patterns tracking five to seven years behind United States adoption curves.
Global Veterinary Endoscopes Market Competitive Landscape
Capability concentration sits with vertically integrated human-device manufacturers; scale advantage sits with veterinary-focused specialists and contract assemblers. The market structure splits between premium-tier players with integrated service networks and value-oriented challengers leveraging Chinese and South Korean manufacturing scale. Three archetypes dominate: human-endoscopy incumbents extending veterinary lines, pure-play veterinary device specialists, and contract manufacturers supplying private-label instruments. Competitive moves center on tightening aftermarket service control and accelerating single-use manufacturing scale-up.
Among German-origin manufacturers with human-device regulatory infrastructure, KARL STORZ SE & Co. KG and Dr. Fritz Endoscopes GmbH occupy positions exemplifying vertically integrated service network strategies. Olympus Corporation and Fujifilm Holdings Corporation represent the Japanese-tier archetype of imaging technology leverage into veterinary applications. These named entities anchor the competitive landscape without constraining the full participant set.
| Leading Market Players |
|---|
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Steris |
| Biovision Veterinary Endoscopy |
| Dr. Fritz Endoscopes GmbH |
| Eickemeyer |
| Fujifilm Holdings Corporation |
| Endoscopy Support Services |
| Richard Wolf GmbH |
| Others |
Supply & Pricing Matrix
Taiwanese CMOS sensor foundries in Hsinchu Science Park anchor optical component availability, with allocation volatility in semiconductor fabrication translating directly into tiered pricing power for veterinary endoscope assemblers serving North American and European hospital chains.
Pricing Analysis
Long-term service contracts with multi-year calibration commitments dominate procurement for reusable flexible systems, while spot-market per-unit transactions govern single-use disposable procurement. Three-tier pricing structure across premium, standard, and economy levels separates OEM-captive service bundles from third-party refurbished alternatives and private-label imports. Cost compression in mid-tier digital systems is intensifying because contract manufacturers in South Korea are expanding cleanroom capacity. General veterinary clinics exhibit highest price sensitivity due to limited procedure volumes, while consolidated specialty hospital chains absorb premium pricing for integrated wireless connectivity features.
Supply Chain Analysis
Export-control restrictions on advanced CMOS image sensors limit technology flows from Japanese and Taiwanese fabrication facilities to Chinese contract assemblers, constraining veterinary OEM sourcing flexibility. Component supply draws from Japan, Taiwan, and South Korea for sensors; Germany and Switzerland for precision optics; and China for polymer extrusion housings. Raw material dependencies encompass rare-earth phosphors for LED illumination, medical-grade stainless steel for rigid scopes, and specialized polymers for disposable channels. Single-source vulnerability concentrates in 4K image signal processor supply from a limited qualified vendor base. Distribution runs through authorized dealer networks for capital equipment and direct-to-hospital subscription platforms for single-use consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based platform economics for single-use endoscopes is displacing traditional capital-equipment financing, with interoperability standards for wireless video streaming creating ecosystem lock-in comparable to human-device markets.
For Market Incumbents: Insulate installed base revenue by tightening proprietary calibration protocols and expanding in-house production of replacement image sensors to offset third-party repair channel erosion. Consolidated hospital chains in Germany and Japan represent the most defensible revenue pools against emerging contract manufacturers. CE marking investment under EU MDR serves as the priority certification lever to exclude mid-tier competitors lacking clinical evidence infrastructure. For New Entrants and Emerging Players: Brazilian specialty practice formation offers the most penetrable geographic entry point, with São Paulo state veterinary centers tracking five to seven years behind United States adoption curves for interventional bronchoscopy capabilities. Mobile veterinary services in rural North America represent underserved demand for portable rigid systems with battery-powered illumination. Subscription supply partnerships with regional distributors circumvent capital-intensive direct sales force requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated human-device manufacturers with existing regulatory infrastructure over pure-play veterinary specialists facing ISO 13485 documentation burdens. Long-term viability across the analysis window hinges on single-use manufacturing scale and wireless platform integration rather than legacy fiberoptic service networks. The signal to monitor is hospital chain procurement standardization that locks out non-integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter out mid-tier competitors lacking quality management infrastructure. |
| Hospital System Partnership | Consolidated chains like Mars Veterinary Health drive standardized specifications across multi-state networks. |
| Software Companion Development | AI-assisted polyp detection algorithms trained on human datasets transfer to veterinary gastrointestinal applications. |
| Reimbursement Strategy | Private pet insurance coverage expansion in Germany and the United States reduces point-of-care price sensitivity. |
| Backward Integration | In-house CMOS sensor sourcing mitigates Taiwanese foundry allocation volatility for premium-tier manufacturers. |
Research Methodology
Operator-level perspectives from veterinary practice owners, biomedical equipment technicians, GPO contracts managers, and specialty hospital procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine device classification databases, EU MDR notified body guidance documents, ISO 13485 certification registries, and veterinary hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Scenario-bracketing framed demand trajectories across conservative, baseline, and expansion cases over the projection horizon. Segmentation dimensions encompassed product type flexibility, application specialization, end-user scale tier, and technology integration depth. CAGRs derived from installed base turnover rates, procedure volume elasticity, and pricing trend extrapolation. Industry-specific inputs included veterinarian diplomate training pipeline output, pet insurance penetration rates, and regulatory transition timelines for digital health integration standards.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by contract manufacturers or rapid single-use subscription adoption by hospital chains would shift outcomes. Material shifts in semiconductor export controls, EU MDR notified body capacity constraints, or wireless data protection regulatory frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
AI in Endoscopy Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Global Endoscope Reprocessing Market