
 China Arthroscopy Market | 2026-2036
China Arthroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
China Arthroscopy Market Intelligence
Aftermarket service revenue for arthroscopy visualization systems is reshaping margin distribution between domestic and foreign manufacturers. Zhejiang Shendasiao Medical Instrument leverages in-house optical component production to capture service contracts. Smith & Nephew plc anchors its position through specialized training programs for Chinese surgeons. Johnson & Johnson competes by extending its sterilization logistics network into provincial capitals.
Arthroscopy encompasses minimally invasive diagnostic and surgical procedures using fiber-optic cameras, irrigation pumps, and motorized shavers to visualize, debride, and repair intra-articular structures through portals less than five millimeters in diameter. High-definition camera systems with 4K resolution and 3D depth perception now dominate new installations in Chinese tier-one hospitals. Surgical instruments, particularly reusable shavers and disposable cannulas, generate recurring revenue streams that outperform capital equipment sales. Orthopedic centers represent the fastest-growing end-user channel as outpatient joint procedures expand under diagnosis-related group payment reforms.
NMPA's medical device registration requirements and GB standards for surgical endoscopes shape product entry timelines and clinical trial obligations for both domestic and imported systems. The country's dual carbon goals pressure manufacturers to reduce single-use plastic waste in disposable instrument packaging. Stakeholders must monitor how provincial centralized procurement platforms consolidate arthroscopy device purchasing power and compress distributor margins.
Market Dynamics
NMPA's updated medical device classification rules are compressing product entry timelines and forcing domestic manufacturers to accelerate GB standards compliance before foreign competitors can establish service networks.
Growth Catalysts
- Outpatient procedure expansion:Beijing's orthopedic surgery clusters are converting inpatient knee arthroscopies to same-day procedures under diagnosis-related group payment reforms, expanding addressable procedure volume.
- GB standards harmonization:NMPA's streamlined registration pathways for Class II surgical endoscopes are reducing clinical trial obligations for domestic visualization system manufacturers.
- Private hospital network buildout:Shanghai's private hospital networks are installing 4K camera systems at three times the rate of public tier-two facilities, creating concentrated demand pockets for capital equipment.
Market Restraints
- Optical component import dependence:Domestic manufacturers remain tethered to German and Japanese suppliers for high-resolution image sensors, exposing margin structures to yen and euro volatility.
- Provincial procurement consolidation:Centralized purchasing platforms in Jiangsu and Guangdong are compressing distributor markups below sustainable levels for mid-tier equipment vendors.
- Reusable shaver degradation limits:Current stainless steel alloys permit only 15-20 sterilization cycles before edge retention fails, constraining total cost-of-ownership advantages over disposable alternatives.
Strategic Opportunities
- Western province penetration:Sichuan and Shaanxi healthcare infrastructure spending is outpacing coastal saturation, creating first-mover advantages for service-capable manufacturers in Chengdu and Xi'an.
- Sports medicine-orthopedics convergence:Tertiary hospital departments are merging joint repair and athletic injury units, demanding cross-trained visualization platforms that handle both diagnostic and surgical workflows.
- Dual carbon packaging mandates:MEE pressure to reduce single-use plastic waste in disposable instrument packaging is opening market share for manufacturers with biodegradable sterilization barrier technologies.
Industry Challenges
- Surgeon training pipeline gaps:Fellowship programs produce only 400 arthroscopy-specialized surgeons annually against demand for 1,200, forcing manufacturers to absorb training costs directly.
- Legacy system integration friction:Tier-one hospitals with 2015-era 1080p camera towers face incompatible data formats when upgrading to 4K-3D visualization, delaying replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Arthroscopy Market |
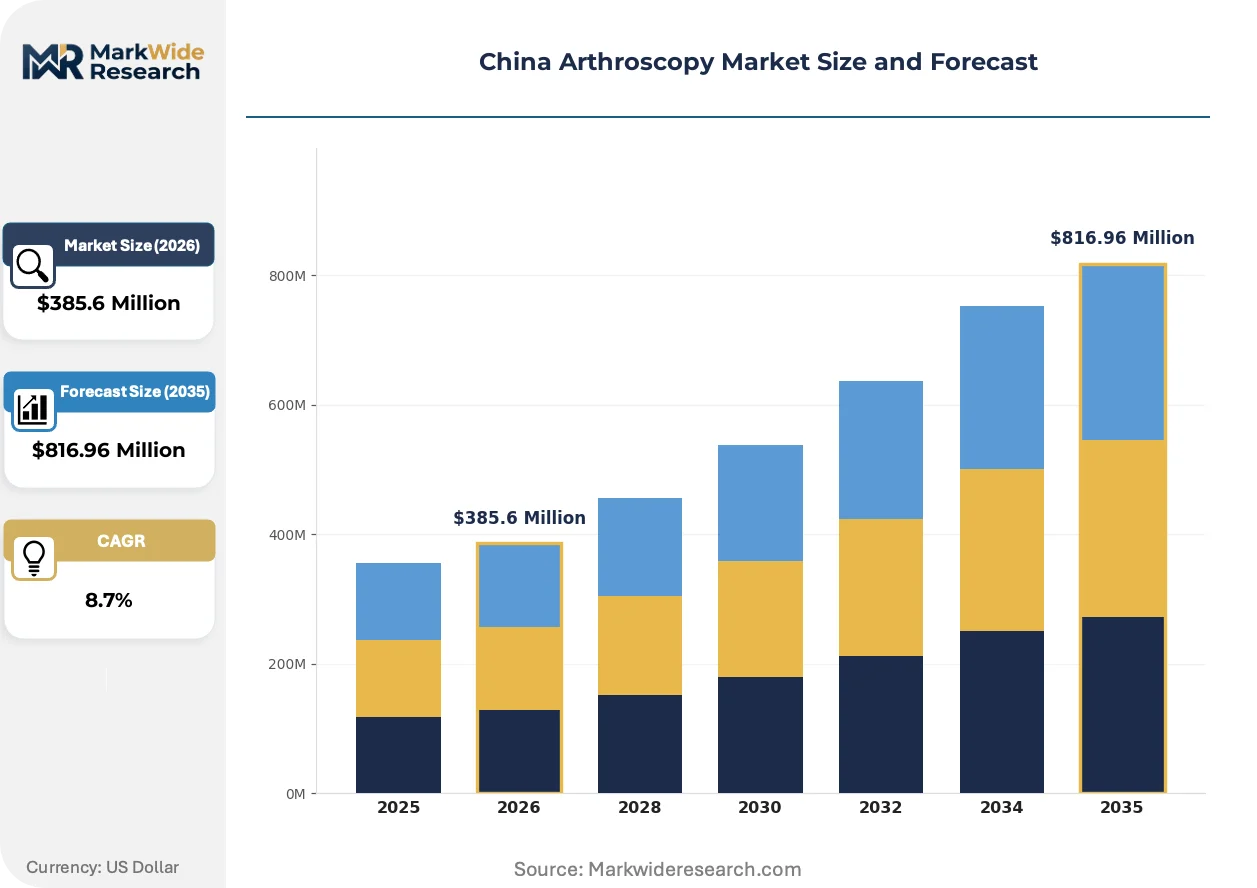
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Surgical Instruments, Reusable Instruments, Disposable Instruments End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Orthopedic Centers Technology: 3D Imaging, High-Definition Cameras, Wireless Technology, Robotics Delivery Mode: In-Person, Telehealth, Hybrid, Mobile Units |
| Companies Covered | Zhejiang Shendasiao Medical Instrument Co., Ltd., TITMED, Shrek, Xuzhou Hengjia Electronic Technology Co., Ltd., Tonglu Wanhe Medical Instrument Co., Ltd., Stryker, Smith & Nephew plc, Zimmer Biomet, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Arthroscopy Market Strategic Shifts & Innovations
Digital surgical workflows are virtualizing physical infrastructure across Chinese arthroscopy suites, compressing capital requirements while expanding remote diagnostic capabilities.
Cloud-native surgical video platforms are virtualizing on-premise storage and analysis infrastructure. Tier-one hospitals in Beijing and Shanghai are piloting these systems for multi-site case review and resident training. This technology is virtualizing the traditional PACS architecture, reducing per-procedure IT capital intensity by shifting compute loads to subscription models.
NMPA's 2023 guidance on software-as-medical-device classification is creating compliance uncertainty for AI-assisted image analysis tools. Manufacturers must now submit algorithm training datasets for review, extending registration timelines. Orthopedic centers deploying computer-aided detection for meniscal tears face the steepest adaptation costs as they revalidate workflows under the new framework.
Service contract unbundling is separating hardware sales from maintenance and training revenue streams. Private hospital groups in the Yangtze River Delta are demanding à-la-carte support tiers rather than bundled multi-year agreements. This shift is most visible among Shanghai's sports medicine-focused facilities, which prioritize rapid technician response times over preventive maintenance schedules.
China Arthroscopy Market Segmentation
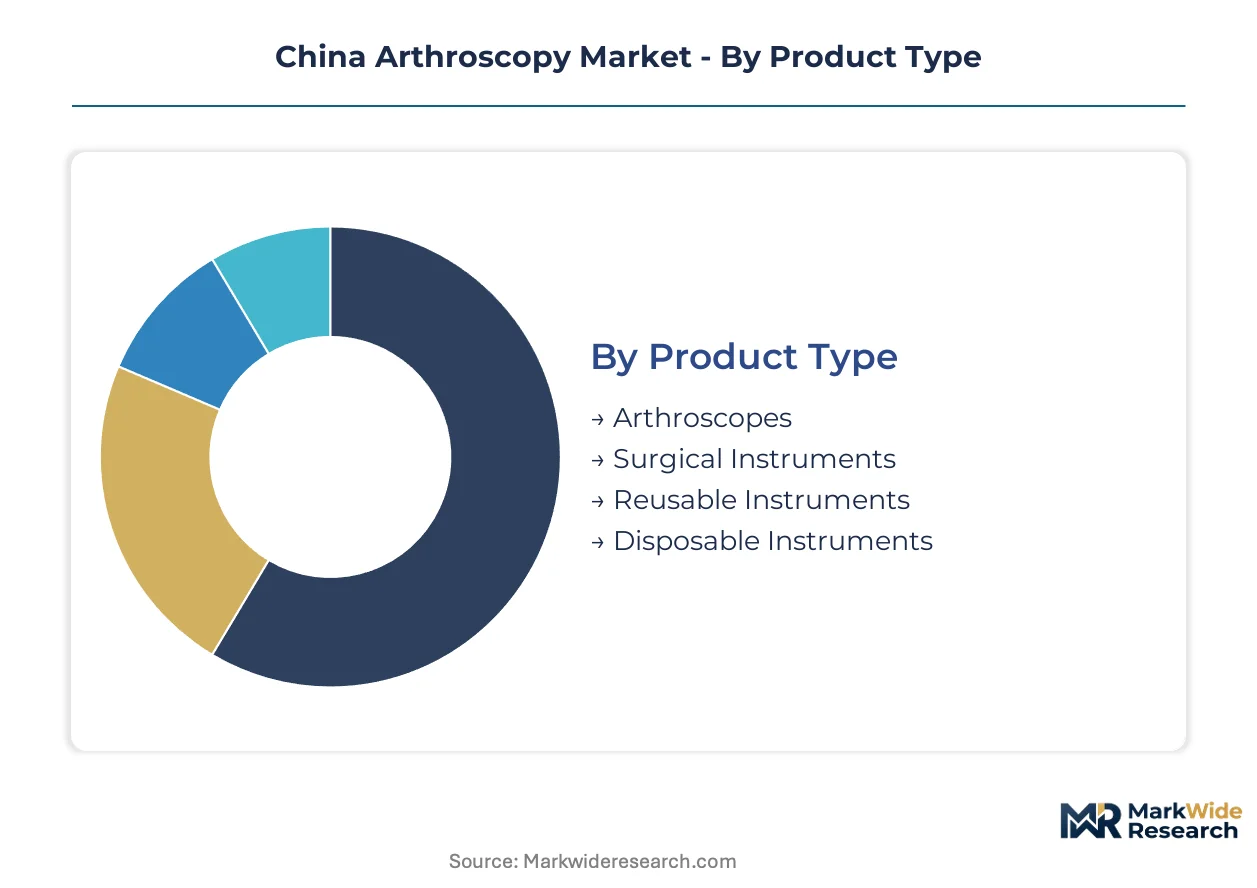
Segmentation in the China arthroscopy market reveals how procurement power concentrates across distinct buyer types and technology tiers. Understanding these divisions exposes where NMPA compliance costs bite hardest and where service revenue potential clusters.
Product Type:
Mature visualization hardware competes against emerging disposable instrument portfolios for capital allocation in Chinese hospital budgets.
- Arthroscopes:Fiber-optic visualization systems with 4K resolution and 3D depth perception dominate new installations in Beijing's tier-one orthopedic clusters. NMPA's GB standards for surgical endoscopes extend registration timelines for imported systems, advantaging domestic manufacturers with in-house optical component production.
- Surgical Instruments:Motorized shavers, burrs, and ablation probes generate recurring revenue streams that outperform capital equipment sales. Demand concentrates in Shanghai's private hospital networks where outpatient procedure volume expands under diagnosis-related group payment reforms.
- Reusable Instruments:Stainless steel shavers and cannulas face sterilization cycle limits of 15-20 uses before edge retention degrades. Zhejiang and Jiangsu procurement platforms are compressing distributor margins on mid-tier reusable portfolios.
- Disposable Instruments:Single-use cannulas and shaver blades eliminate cross-contamination risk but trigger MEE scrutiny over plastic waste packaging. Biodegradable sterilization barrier technologies are gaining traction among environmentally pressured hospital procurement committees.
Arthroscopes handle the majority of throughput; disposable instruments are expanding most quickly on share.
End User:
Customer type determines pricing power, with public procurement platforms squeezing mid-tier vendors while private networks prioritize service responsiveness over capital cost.
- Hospitals:Tertiary facilities in Beijing and Shanghai anchor demand for 4K-3D visualization systems. Sports medicine departments are merging with orthopedic units, demanding cross-trained platforms that handle both diagnostic arthroscopy and surgical repair workflows.
- Ambulatory Surgery Centers:Same-day knee arthroscopy procedures are expanding fastest in coastal provinces where diagnosis-related group payment reforms incentivize outpatient conversion. These centers prioritize compact, mobile-compatible equipment with rapid sterilization turnaround.
- Specialty Clinics:Focused sports medicine practices in the Yangtze River Delta are piloting cloud-native surgical video platforms for multi-site case review. Subscription-based IT models reduce per-procedure capital intensity compared to traditional PACS architecture.
- Orthopedic Centers:Dedicated joint repair facilities represent the fastest-growing channel as procedure volume shifts from inpatient to outpatient settings. These centers absorb the steepest training costs due to surgeon pipeline gaps, forcing manufacturers to fund fellowship programs directly.
Hospitals command the dominant procurement volume; orthopedic centers are climbing the fastest on procedure throughput expansion.
Technology:
Cost tier stratification separates premium visualization systems from emerging automation platforms in Chinese hospital capital budgets.
- 3D Imaging:Depth-perception visualization systems reduce operative time in complex meniscal repair procedures. Tier-one hospitals with 2015-era 1080p towers face data format incompatibility when upgrading, delaying replacement cycles.
- High-Definition Cameras:4K resolution systems now dominate new installations, though legacy integration friction constrains upgrade velocity. Domestic manufacturers are capturing share through localized image sensor supply chains.
- Wireless Technology:Cable-free camera heads reduce OR clutter and sterilization burden. Adoption concentrates in Shanghai's private networks where rapid equipment turnover justifies premium pricing.
- Robotics:Automated instrument positioning systems remain nascent in China due to NMPA's 2023 software-as-medical-device classification uncertainty. Algorithm training dataset submission requirements extend registration timelines for AI-assisted platforms.
High-definition cameras anchor current procurement; robotics holds the steepest expansion trajectory pending regulatory clarity.
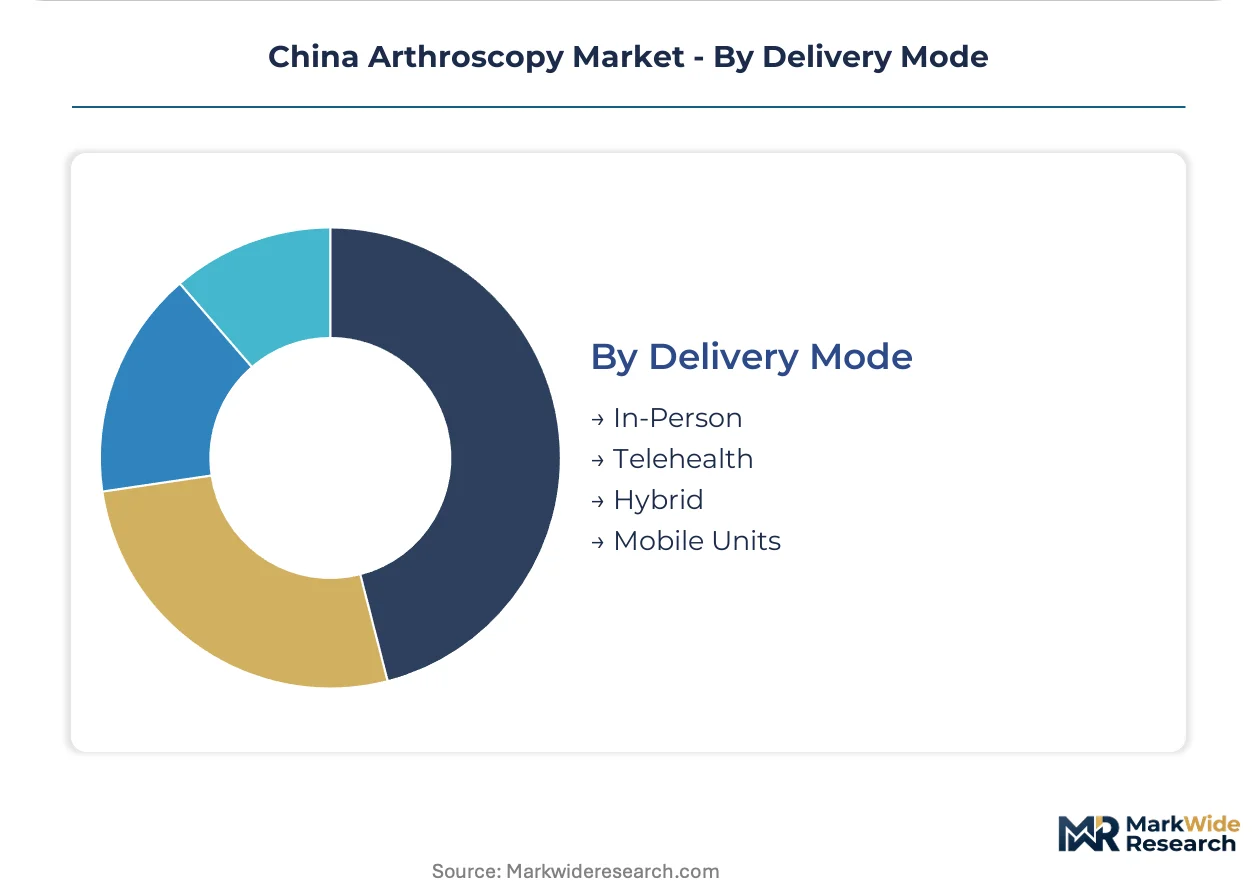
Delivery Mode:
Geography shapes access models, with coastal saturation driving mobile and hybrid formats into western provinces.
- In-Person:Traditional OR-based arthroscopy remains the default in tertiary hospital clusters. Beijing's orthopedic surgery hubs maintain the highest per-facility procedure density nationally.
- Telehealth:Remote pre-operative assessment and post-operative monitoring are expanding in Sichuan and Shaanxi where specialist density lags coastal provinces. Cloud-native video platforms enable multi-site case review without physical infrastructure duplication.
- Hybrid:Blended in-person and remote workflows are piloting in Yangtze River Delta private hospital groups. These models unbundle service contracts into à-la-carte support tiers prioritizing technician response speed.
- Mobile Units:Transportable arthroscopy suites are penetrating Chengdu and Xi'an healthcare infrastructure buildouts. Western province spending growth is outpacing coastal saturation, creating first-mover advantages for service-capable manufacturers.
In-person delivery retains the dominant procedure volume; mobile units are gaining share fastest on western province infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial healthcare infrastructure spending patterns in China create distinct consumption profiles, with coastal provinces prioritizing 4K-3D visualization upgrades while western provinces emphasize mobile-compatible and telehealth-integrated systems for specialist access.
Beijing-Tianjin-Hebei
Tertiary orthopedic surgery clusters in Beijing drive demand for high-definition camera systems with 3D depth perception capabilities. NMPA's streamlined registration pathways for Class II surgical endoscopes reduce clinical trial burdens for domestic manufacturers seeking entry. The capital's sports medicine departments are merging with joint repair units, requiring cross-trained visualization platforms.
Yangtze River Delta
Shanghai's private hospital networks install 4K camera systems at triple the rate of public tier-two facilities, creating concentrated demand pockets. MEE pressure to reduce single-use plastic waste in disposable instrument packaging is shifting procurement toward biodegradable sterilization barriers. Cloud-native surgical video platforms are piloting across multi-site case review networks in the region.
Pearl River Delta
Guangdong's centralized procurement platforms compress distributor markups below sustainable levels for mid-tier equipment vendors. GB standards harmonization for surgical endoscopes accelerates local manufacturing compliance timelines. Shenzhen and Guangzhou healthcare infrastructure is converting inpatient knee arthroscopies to same-day procedures under diagnosis-related group reforms.
Sichuan-Chongqing
Chengdu's healthcare infrastructure spending growth outpaces coastal saturation, creating first-mover advantages for service-capable manufacturers. Remote pre-operative assessment and post-operative monitoring expand where specialist density lags coastal provinces. Mobile arthroscopy suites penetrate western province buildouts as transportable solutions gain traction.
Shandong Peninsula
Jiangsu procurement consolidation pressures mid-tier reusable instrument portfolios through aggressive distributor margin compression. Zhejiang manufacturers leverage in-house optical component production to capture service contracts in regional hospital networks. Qingdao and Jinan orthopedic centers absorb steep training costs due to surgeon pipeline gaps, forcing equipment vendors to fund fellowship programs.
China Arthroscopy Market Key Industry Players
Capability concentration sits with domestic optical specialists; scale advantage sits with multinational service networks. The vendor base stratifies across three tiers: integrated visualization system manufacturers with captive component supply, pure-play surgical instrument specialists, and diversified orthopedic conglomerates with sterilization logistics extensions. Dominant competitive moves include backward integration into image sensor supply chains and geographic expansion of technician service networks into provincial capitals.
Within the domestic specialist tier, Zhejiang Shendasiao Medical Instrument Co., Ltd. exemplifies the integrated manufacturer archetype through its in-house optical production capabilities. Smith & Nephew plc occupies a position anchoring multinational service infrastructure, while Johnson & Johnson represents the diversified healthcare conglomerate model with sterilization logistics extensions. These three players illustrate how competitive positioning in China's arthroscopy market depends on whether capability depth or operational scale drives customer procurement decisions.
| Leading Market Players |
|---|
| Zhejiang Shendasiao Medical Instrument Co., Ltd. |
| TITMED |
| Shrek |
| Xuzhou Hengjia Electronic Technology Co., Ltd. |
| Tonglu Wanhe Medical Instrument Co., Ltd. |
| Stryker |
| Smith & Nephew plc |
| Zimmer Biomet |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Optical component import dependence from German and Japanese suppliers determines both the spread between domestic and imported system pricing tiers and the geographic configuration of arthroscopy supply chains in China. NMPA's GB standards compliance timelines compress margins for foreign manufacturers while creating captive supply advantages for domestic optical specialists.
Pricing Analysis
Long-term service contracts dominate capital equipment transactions, with bundled multi-year agreements giving way to à-la-carte support tiers demanded by Shanghai's private hospital networks. Price differentiation hinges on NMPA registration tier and after-sales technician network density, with provincial centralized procurement platforms driving cost compression in mid-tier reusable instrument categories. Pricing pressure stems from Jiangsu and Guangdong procurement consolidation, compressing distributor markups below sustainable thresholds. Public tier-two facilities exhibit highest price sensitivity; private sports medicine centers prioritize rapid response service over capital cost.
Supply Chain Analysis
Contract manufacturing capacity for high-resolution image sensors concentrates in Japan, Germany, and South Korea, with domestic Chinese manufacturers dependent on imported CMOS and CCD components. Raw material dependencies span optical glass substrates, precision-machined stainless steel alloys, and medical-grade polymers for disposable cannulas. Supply chain risk centers on yen and euro volatility exposing margin structures to exchange rate swings. Distribution runs through provincial medical device procurement platforms that consolidate purchasing power and compress intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated provincial procurement platforms, fragmenting pricing power among equipment vendors while concentrating volume leverage in the hands of public hospital networks.
For Market Incumbents: Entrench service infrastructure in western provinces before domestic competitors establish technician networks in Chengdu and Xi'an. Secure backward integration into optical component supply chains to reduce yen-denominated input exposure. Prioritize NMPA Class II registration pathway optimization to compress domestic product entry timelines against foreign rivals. For New Entrants and Emerging Players: Sichuan and Shaanxi healthcare infrastructure spending growth represents the most penetrable geographic white space, with mobile-compatible equipment demand outpacing coastal saturation. Target orthopedic centers converting inpatient procedures to outpatient settings under diagnosis-related group reforms. Pursue cloud-native surgical video platform partnerships as a low-capital entry vector. For Investors and Strategic Acquirers: NMPA's 2023 software-as-medical-device classification guidance reshapes the acquisition landscape, extending registration timelines for AI-assisted platforms and favoring targets with validated algorithm training datasets. Long-term viability favors integrated visualization manufacturers with captive optical production over pure-play instrument specialists. Monitor provincial procurement platform consolidation velocity as an inflection indicator for distributor margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Registration Pathway Optimization | Streamlined GB standards compliance accelerates domestic product entry timelines against imported systems. |
| Backward Integration into Optical Component Supply | In-house image sensor production reduces yen volatility exposure and captures service contract margins. |
| Western Province Service Network Expansion | First-mover technician infrastructure in Chengdu and Xi'an secures share in fastest-growing demand pockets. |
| Cloud-Native Surgical Video Platform Development | Subscription-based IT models reduce per-procedure capital intensity for orthopedic center customers. |
| Biodegradable Sterilization Barrier Technology | MEE packaging mandates create procurement preference for environmentally compliant disposable instruments. |
Research Approach
Cross-validation between primary interviews with orthopedic surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers and secondary sources including NMPA registration databases, provincial procurement platform disclosures, and hospital equipment tender records anchors the qualitative findings. Bottom-up procedure volume estimates from tier-one and tier-two hospital clusters triangulate against top-down capital equipment shipment data from domestic and multinational manufacturers.
Calibration against historical NMPA approval timelines and provincial procurement award patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and delivery mode, with CAGRs derived from procedure volume elasticity to outpatient conversion rates and capital replacement cycle analysis. Forecast inputs incorporate diagnosis-related group payment reform implementation pace and dual carbon packaging mandate compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive service network expansion by domestic optical specialists or accelerated NMPA software-as-medical-device enforcement would shift outcomes. Quarterly review of provincial procurement platform award volumes and NMPA registration backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Nasopharyngoscope Market