
 Global Disposable Endoscope Market | 2026-2036
Global Disposable Endoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Endoscope Market Foresight
Asset-light leasing and per-procedure rental models are reshaping competitive dynamics in disposable endoscopy, lowering capital barriers for mid-tier hospitals and ambulatory chains. Ambu A/S leverages vertical integration across polymer molding and sterile packaging to sustain margin control at volume. Boston Scientific Corporation anchors North American hospital contracts through bundled procedural economics. Olympus Corporation dominates legacy flexible endoscope replacement cycles, converting installed base customers to single-use platforms.
A disposable endoscope is a single-use visualization instrument comprising a lens train, illumination fiber or CMOS sensor, and disposable sheath, manufactured through insert molding and cleanroom assembly to eliminate cross-contamination between patients. Its primary purpose is diagnostic and therapeutic visualization of hollow organs and cavities without reprocessing infrastructure. Flexible endoscopes lead procedure volume across gastroenterology and pulmonology applications where bending radius and channel diameter determine clinical utility. CMOS sensor technology is displacing legacy CCD architectures in new product development due to lower power draw and miniaturization headroom. Capsule endoscopes occupy a distinct niche in small-bowel examination where patient compliance limits traditional scope tolerance.
The FDA enforces reprocessing validation requirements under 510(k) pathways while the EU MDR imposes stricter clinical evidence standards for class IIa and IIb single-use devices. Japan's PMDA maintains rigorous biocompatibility testing protocols that shape polymer selection and sterilization method validation for manufacturers seeking market access. Stakeholders must monitor evolving reimbursement codes for single-use procedures across CMS, NHS England, and Germany's G-BA to anticipate volume inflection points.
Market Dynamics
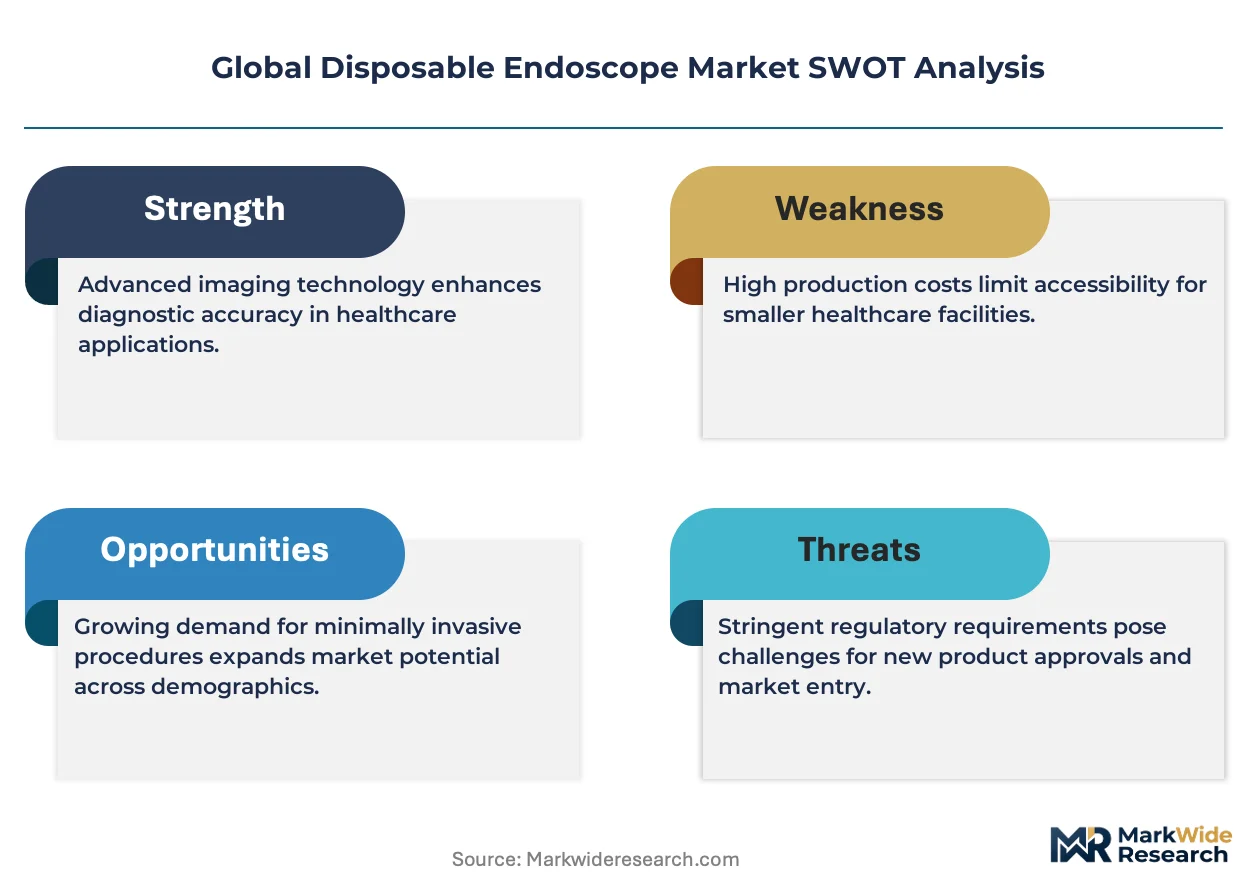
CMOS sensor miniaturization is collapsing the cost floor for high-definition disposable visualization, enabling single-use platforms to match reusable optical performance at one-fifth the manufacturing complexity. This technological inflection is redrawing competitive boundaries between polymer specialists and legacy endoscope incumbents.
Growth Catalysts
- FDA Reprocessing Mandates:Updated 510(k) validation requirements for duodenoscopes are forcing hospital systems to abandon reusable platforms. The guidance eliminates liability ambiguity for infection control officers.
- Ambulatory Surgery Center Expansion:Freestanding GI and pulmonology clinics in the United States are adopting single-use bronchoscopes to bypass capital-intensive sterilization infrastructure. Per-procedure economics favor disposables at volumes below 200 cases monthly.
- Polymer Molding Automation:Cleanroom insert molding advances are reducing unit production costs for flexible distal tips. German and Japanese equipment suppliers are shipping turnkey lines that compress assembly labor by 60 percent.
Market Restraints
- High-Performance Polymer Supply Concentration:Medical-grade PEEK and liquid silicone rubber for flexible sheaths concentrate among three Japanese chemical conglomerates. Any disruption to Kobe or Nagoya port logistics cascades through OEM production schedules.
- EU MDR Clinical Evidence Burden:Class IIb single-use endoscopes now require prospective clinical data for CE marking. Small manufacturers lack the capital to fund 500-patient equivalence studies.
- Reusable Endoscope Refurbishment Networks:Third-party reprocessors in the United States and Germany extend reusable scope lifecycles to 7-10 years. These networks compete on total cost of ownership in high-volume academic medical centers.
Strategic Opportunities
- India Tier-II Hospital Penetration:Nascent infection control litigation and government hospital accreditation standards are creating first-mover advantages for single-use urology and ENT platforms. Domestic distributors seek exclusive regional partnerships.
- AI-Assisted Polyp Detection Integration:Real-time computer vision algorithms are converging with disposable colonoscope hardware. OEMs that bundle FDA-cleared software modules command premium positioning in gastroenterology.
- Japan PMDA Streamlined Pathway:The Sakigake designation accelerates review timelines for novel single-use devices with superior biocompatibility profiles. Manufacturers qualifying for this track gain 12-month market access advantages.
Industry Challenges
- Cleanroom Technician Scarcity:ISO 14644 Class 7 assembly operations require certified operators with polymer bonding and sensor alignment skills. Training pipelines in Massachusetts and Bavaria cannot match OEM hiring velocity.
- Legacy EMR Integration Complexity:Disposable scope platforms must transmit imaging data to hospital PACS and proprietary documentation systems. Each integration project demands 6-9 months of IT co-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Endoscope Market |
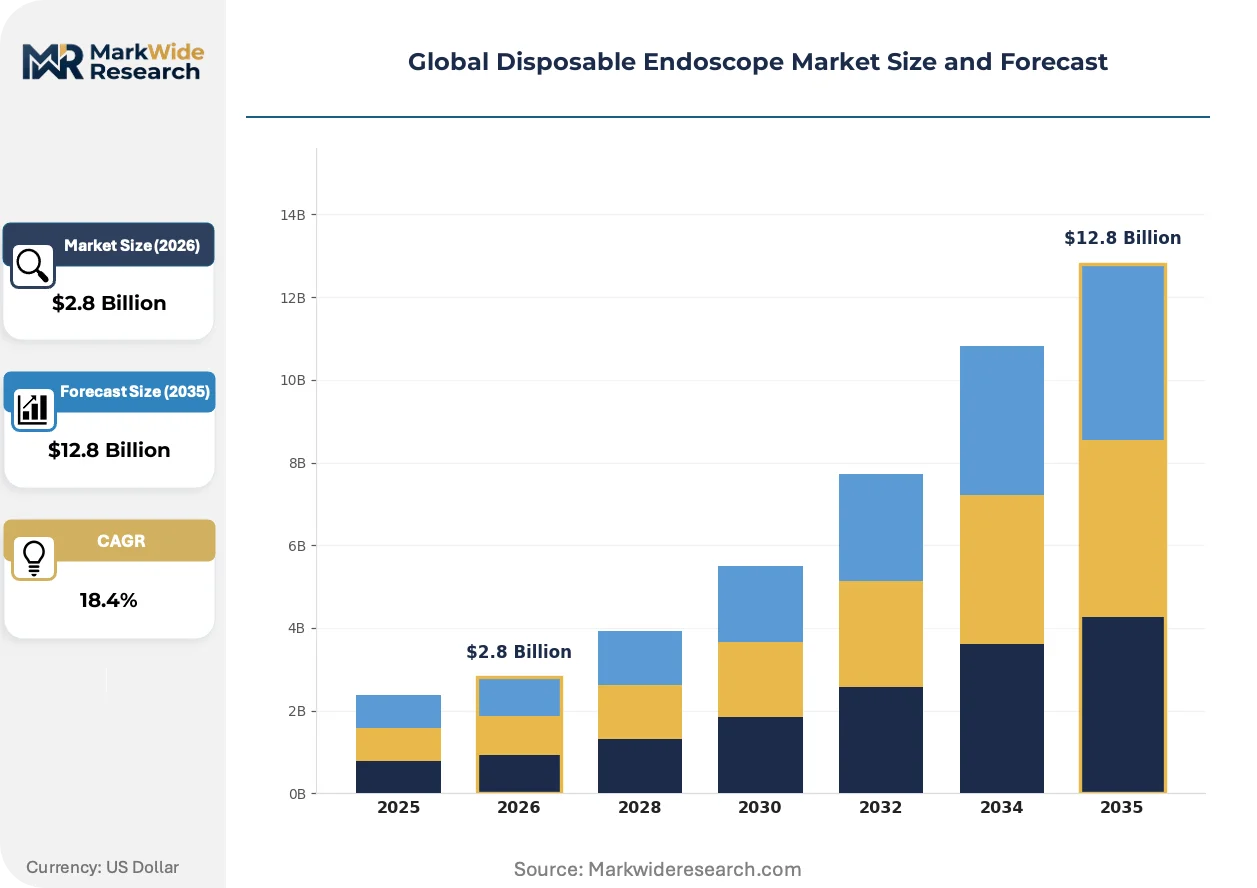
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Video Endoscopes Application: Gastroenterology, Pulmonology, Urology, ENT Procedures, Gynecology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Labs, Specialty Clinics Technology: Fiber Optic, CMOS Sensor, CCD Sensor, 3D Imaging, Wireless Transmission |
| Companies Covered | Ambu A/S, Boston Scientific Corporation, Olympus Corporation, KARL STORZ SE and Co. KG, Flexicare Medical Limited, Medtronic Plc, Acteon Group Ltd., obp Medical Corporation, CooperSurgical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Endoscope Market Shifts & Advancements
Disposable endoscopy is undergoing simultaneous compression on three fronts: component economics, regulatory stringency, and procurement rationalization. These forces are accelerating product architecture standardization while fragmenting go-to-market strategies.
CMOS-based distal chip technology is collapsing the historical cost-performance tradeoff between single-use and reusable visualization systems. Ambulatory surgery centers in Germany and the United States are adopting these platforms for routine bronchoscopy and cystoscopy procedures. The elimination of CCD fiber bundles reduces both unit cost and failure rates during bending maneuvers.
EU MDR Article 61 clinical evaluation requirements are extending time-to-market for novel single-use gastroenterology devices. Manufacturers must now submit prospective human factors data and post-market surveillance plans with initial registrations. Japanese OEMs with existing PMDA clinical dossiers are leveraging this documentation to satisfy European notified body demands.
Hospital procurement departments are consolidating endoscope purchasing under value-analysis committees rather than individual physician preference. These committees evaluate total cost of ownership including reprocessing labor, liability insurance, and turnover downtime. The shift is most pronounced in integrated delivery networks across Texas, Florida, and Pennsylvania where standardization incentives override brand loyalty.
Global Disposable Endoscope Market Segmentation
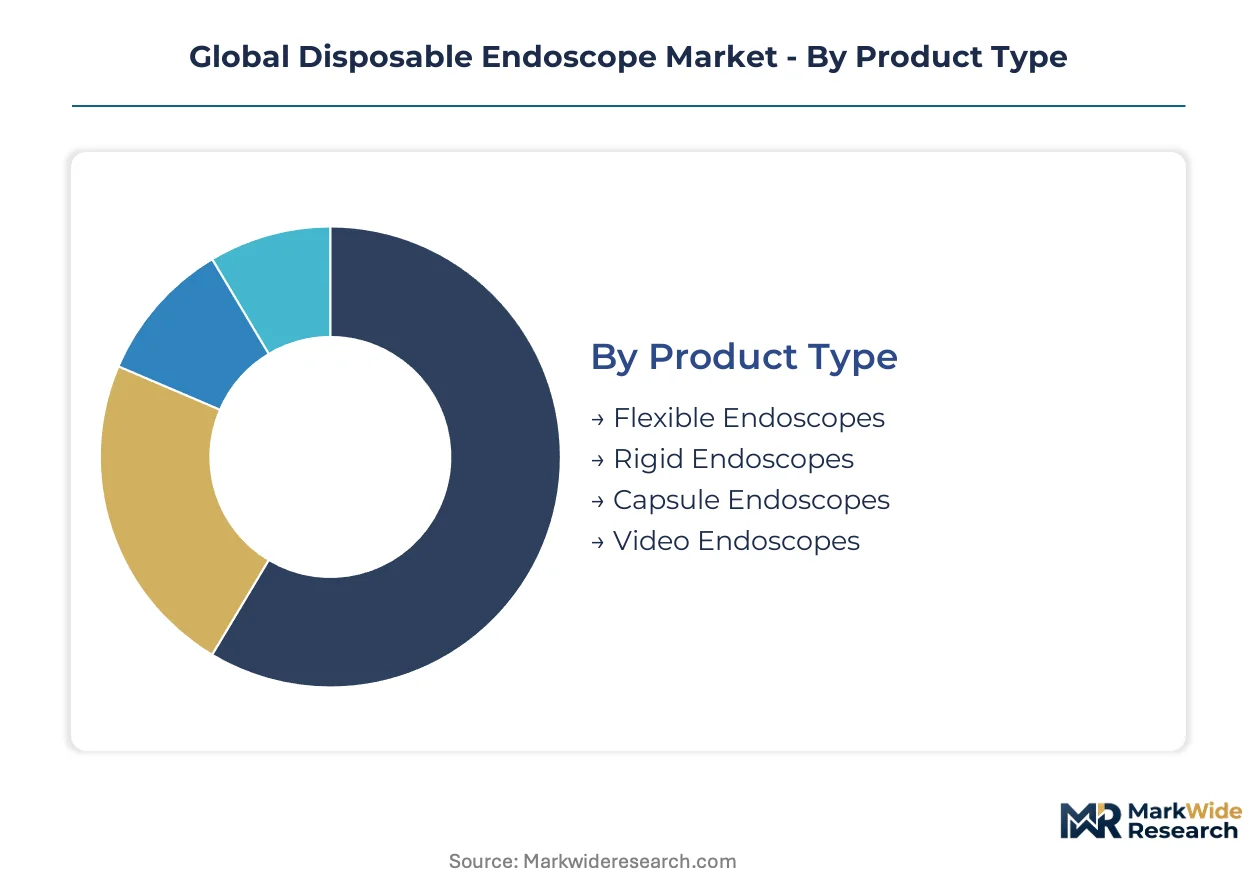
Disposable endoscope segmentation reveals divergent replacement cycles across product architectures, with flexible platforms requiring quarterly replenishment while rigid systems sustain annual turnover. Understanding these velocity differences shapes inventory planning and manufacturing capacity allocation for OEMs serving heterogeneous clinical environments.
Product Type:
Flexible endoscopes turn over fastest due to mechanical fatigue in bending segments, while capsule endoscopes maintain the longest effective lifecycle given their passive transit design.
- Flexible Endoscopes:These single-use instruments incorporate polymer-sheathed articulating distal tips with integrated working channels for biopsy forceps and suction. Demand clusters in United States ambulatory surgery centers performing routine bronchoscopy, where per-procedure economics eliminate reprocessing infrastructure investments. The FDA's duodenoscope reprocessing mandates accelerate hospital conversions to disposable gastroenterology platforms.
- Capsule Endoscopes:Ingestible visualization systems encasing CMOS sensors, LED illumination, and wireless transmitters within biocompatible polymer shells. German diagnostic labs favor these for small-bowel examination where patient compliance limits traditional scope tolerance. Capsule retrieval and data download create distinct workflow integration requirements.
- Rigid Endoscopes:Stainless steel or polymer shafts with fixed optical paths for arthroscopy and laparoscopy applications.
- Video Endoscopes:Integrated display systems combining distal sensors with onboard image processing and video output capabilities.
Flexible endoscopes dominate installed base. Capsule endoscopes are where expansion concentrates.
Application:
Procedure volume and reimbursement density create tiered margin profiles across clinical specialties, with pulmonology offering the steepest expansion trajectory.
- Pulmonology:Single-use bronchoscopes for airway examination and bronchoalveolar lavage. Japanese tertiary hospitals adopt these platforms to eliminate cross-contamination risks in immunocompromised patient populations. Per-procedure rental models lower capital barriers for mid-tier institutions.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures using disposable platforms with integrated irrigation and insufflation channels. United States integrated delivery networks in Texas and Florida consolidate purchasing under value-analysis committees evaluating total cost of ownership.
- Urology:Cystoscopy and ureteroscopy applications where sterile field requirements favor single-use sheaths.
- ENT Procedures:Nasopharyngoscopy and laryngoscopy for otolaryngology clinics.
- Gynecology:Hysteroscopy and falloposcopy platforms for reproductive health applications.
Gastroenterology commands the largest procedure volume. Pulmonology is climbing the fastest.
End User:
Capital availability and case volume thresholds determine adoption timing across facility types, with ambulatory chains moving earliest on per-procedure economics.
- Ambulatory Surgery Centers:Freestanding GI and pulmonology clinics in Germany and the United States bypass sterilization infrastructure through single-use platforms. Per-procedure economics favor disposables at volumes below 200 cases monthly.
- Hospitals:Academic medical centers and community hospitals converting duodenoscope fleets to disposable alternatives under FDA reprocessing guidance. Infection control litigation exposure drives standardization across integrated delivery networks.
- Diagnostic Labs:Independent pathology and imaging centers requiring capsule endoscopy services.
- Specialty Clinics:Urology and ENT focused practices with concentrated procedure mixes.
Hospitals retain the deepest installed base. Ambulatory surgery centers are gaining share fastest.
Technology:
Sensor architecture choices determine manufacturing complexity and optical performance ceilings, with CMOS platforms collapsing cost floors fastest.
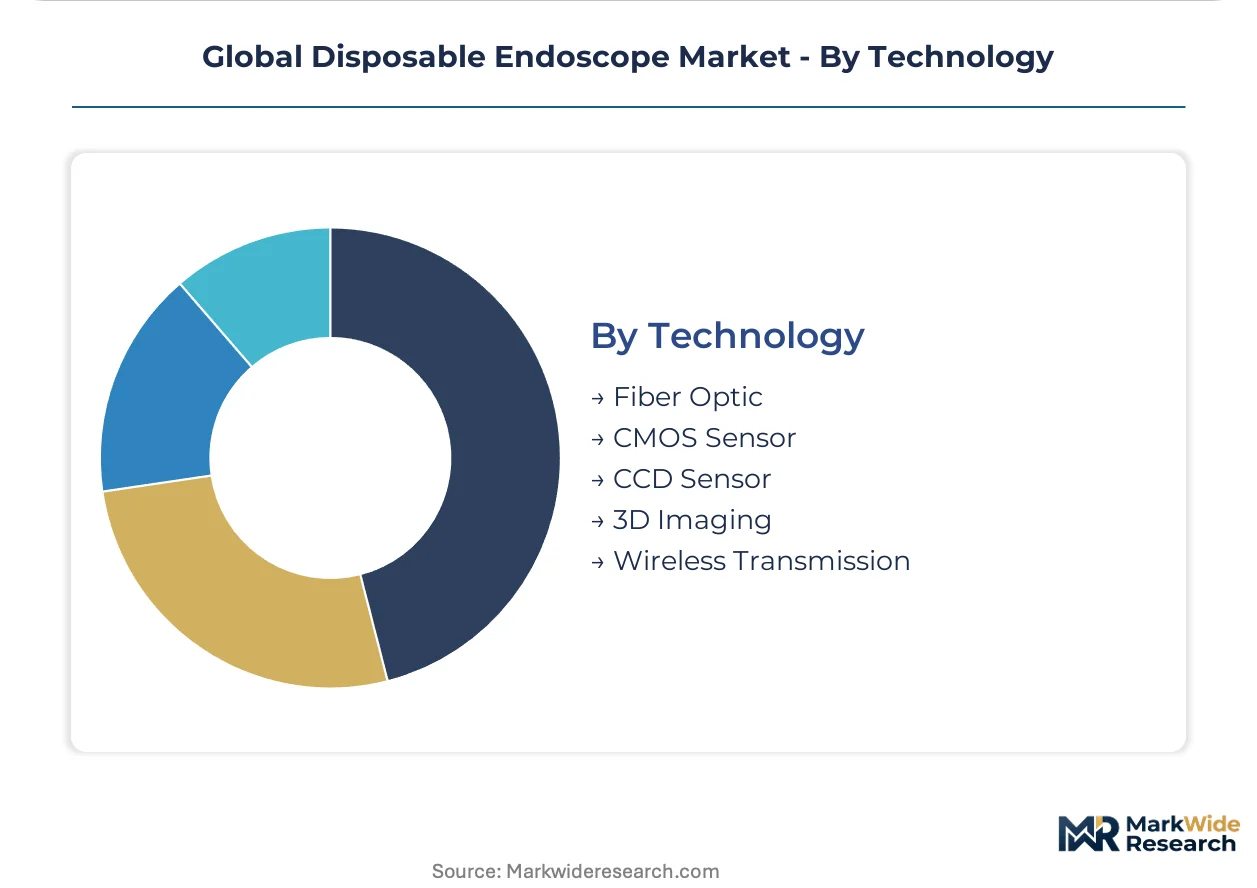
- CMOS Sensor:Complementary metal-oxide-semiconductor imaging chips enabling high-definition visualization at reduced power draw and miniaturization headroom. Massachusetts and Bavaria cleanroom facilities scale assembly automation for distal chip-on-tip configurations.
- Fiber Optic:Traditional glass fiber bundles transmitting illumination and image data through flexible shafts. Legacy systems persist in cost-sensitive markets where optical performance requirements remain modest.
- CCD Sensor:Charge-coupled device architectures being displaced by CMOS alternatives in new product development.
- 3D Imaging:Stereoscopic visualization systems for surgical navigation and depth perception.
- Wireless Transmission:Radio-frequency or Bluetooth data links for capsule endoscope image relay.
CMOS sensor platforms dominate new product development. Wireless transmission represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports substantial volumes of CMOS sensors and medical-grade polymers while exporting finished disposable endoscopes to Canada and Western Europe. Germany and Japan maintain trade surpluses in precision molding equipment and optical components respectively. China's domestic production capacity is expanding fastest, though quality certification lags.
United States
Ambulatory surgery centers in Texas and Florida drive single-use bronchoscope demand through per-procedure rental models. FDA duodenoscope reprocessing mandates eliminate liability ambiguity for hospital infection control officers. Massachusetts cleanroom clusters near Boston specialize in CMOS distal chip assembly automation.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia consolidate purchasing under value-analysis committees evaluating total cost of ownership. EU MDR Article 61 clinical evidence requirements extend time-to-market for novel gastroenterology devices. Stuttgart industrial zones supply turnkey polymer molding lines compressing assembly labor by sixty percent.
Japan
Tertiary hospitals in Tokyo and Osaka adopt single-use platforms to eliminate cross-contamination risks in immunocompromised populations. PMDA biocompatibility testing protocols shape polymer selection and sterilization validation for manufacturers. Nagoya chemical conglomerates concentrate medical-grade PEEK and liquid silicone rubber supply.
India
Tier-II hospitals in Maharashtra and Karnataka seek exclusive regional partnerships for single-use urology platforms. Government hospital accreditation standards and nascent infection control litigation create first-mover advantages. Domestic distributors in Delhi-NCR and Chennai bridge OEMs to emerging clinic networks.
United Kingdom
NHS England reimbursement code evolution for single-use procedures shapes volume inflection points across gastroenterology and pulmonology. MHRA alignment with EU MDR clinical evidence standards filters market access for smaller manufacturers. London procurement consortia standardize specifications across integrated care systems.
Global Disposable Endoscope Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling polymer molding and sensor supply. The vendor base concentrates among three archetypes: diversified medical device conglomerates with installed base conversion strategies, pure-play disposable specialists with vertical manufacturing control, and contract manufacturers serving private-label entrants. Consolidation pressure intensifies as per-procedure economics commoditize hardware differentiation. Strategic moves center on cleanroom capacity expansion in Massachusetts and Bavaria, plus Sakigake pathway qualification in Japan.
Within the diversified conglomerate tier, Olympus Corporation exemplifies legacy flexible endoscope incumbents converting installed base customers to single-use platforms. Ambu A/S occupies the pure-play specialist position with backward integration across polymer molding and sterile packaging. Boston Scientific Corporation anchors North American hospital contracts through bundled procedural economics. These three entities represent distinct competitive vectors: legacy conversion, manufacturing control, and commercial bundling respectively.
| Leading Market Players |
|---|
| Ambu A/S |
| Boston Scientific Corporation |
| Olympus Corporation |
| KARL STORZ SE and Co. KG |
| Flexicare Medical Limited |
| Medtronic Plc |
| Acteon Group Ltd. |
| obp Medical Corporation |
| CooperSurgical Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in Massachusetts cleanroom facilities is tightening polymer bonding technician availability and compressing margin structures for flexible distal tip assemblies. This utilization squeeze forces OEMs to prioritize high-volume hospital contracts while ambulatory buyers face extended lead times and reduced pricing flexibility.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through value-analysis frameworks evaluating total cost of ownership. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with AI modules from basic bronchoscope configurations. Cost compression in mid-tier segments is intensifying because German and Japanese equipment suppliers are shipping turnkey automation lines. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with infection control litigation exposure show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between United States and China dominates risk planning for CMOS sensor procurement. Medical-grade PEEK and liquid silicone rubber concentrate among Nagoya chemical conglomerates, while CMOS imaging chips draw from Taiwanese foundries and South Korean packaging houses. Single-source vulnerability in Japanese polymer supply creates cascading disruption potential through Kobe port logistics. Distribution runs through domestic distributors in Delhi-NCR and Chennai bridging OEMs to emerging clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Per-procedure rental models and software companion modules are expanding recurring-revenue pools faster than disposable hardware unit sales. Service-attach economics now determine enterprise valuations more than manufacturing scale.
For Market Incumbents: Insulate market position by securing captive supply of medical-grade PEEK through backward integration into Nagoya chemical partnerships. Expand cleanroom capacity in Bavaria to preempt technician scarcity bottlenecks. Priority lever: hospital EMR integration capabilities that lock in switching costs against emerging entrants. For New Entrants and Emerging Players: Tier-II hospitals in Maharashtra and Karnataka represent the most penetrable geographic underpenetration, where government accreditation standards and nascent infection control litigation create first-mover windows. Target single-use urology platforms through exclusive regional distributor partnerships. Go-to-market angle: per-procedure economics bypassing capital-intensive sterilization infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators bundling AI-assisted polyp detection software with disposable colonoscope hardware. Five-to-ten year viability favors OEMs with PMDA Sakigake pathway qualification and existing clinical dossiers. Acquisition target archetype: pure-play disposable specialists with vertical manufacturing control. Signal to watch: CMS reimbursement code evolution for single-use gastroenterology procedures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) pathway clearance eliminates liability ambiguity for hospital infection control officers. |
| CE Marking Pathway | EU MDR Article 61 compliance extends market access across German integrated delivery networks. |
| Hospital System Partnership | Value-analysis committee relationships override physician preference in Texas and Florida procurement. |
| Software Companion Development | FDA-cleared AI polyp detection modules command premium positioning in gastroenterology. |
| Reimbursement Strategy | CMS and NHS England code evolution shapes volume inflection points across pulmonology applications. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance. Bottom-up procedure volume estimates triangulated against top-down polymer consumption data.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included product architecture, clinical application, end-user facility type, and sensor technology tier. CAGRs derived from historical conversion rates of reusable to disposable platforms, adjusted for regulatory mandate timing and reimbursement policy shifts. Forecast inputs incorporated cleanroom capacity expansion schedules and PMDA review timeline differentials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical device conglomerates or pure-play disposable specialists would shift outcomes. Regulatory delays, polymer supply disruptions, or reimbursement code freezes represent specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Bronchoscopy Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Endoscopy Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Colonic Stents Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Global Mobile Endoscopic Workstations Market