
 Spain Endoscopy Devices Market | 2026-2036
Spain Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Endoscopy Devices Market Analytics
Ambulatory surgical centers is repositioning Spain's endoscopy device demand away from traditional hospital-centric procurement. Olympus Corporation dominates flexible endoscope supply through direct service contracts with regional health consortia. Johnson & Johnson leverages its advanced energy portfolio to compete in surgical endoscopy suites. Karl Storz anchors the rigid endoscope segment through specialized visualization systems for urology and gynecology applications.
Endoscopy devices are instrument systems incorporating fiber-optic or digital imaging channels, illumination sources, and operative channels for diagnostic and therapeutic visualization of hollow organs and body cavities. These systems typically employ charge-coupled device or complementary metal-oxide-semiconductor sensors delivering high-definition video output to external processing units for real-time tissue assessment and minimally invasive intervention. Flexible endoscopes lead installed base volumes across Spanish healthcare facilities due to their versatility in gastroenterology and pulmonology workflows. Robotic endoscopy represents the fastest-expanding technology segment as hospitals integrate computer-assisted navigation for precision-guided biopsies and polypectomies. Capsule endoscopes occupy a niche position with concentrated demand from diagnostic centers seeking non-invasive small bowel examination capabilities.
Spain's national pharmaceutical and medical device regulator, AEMPS, enforces CE marking compliance under the EU Medical Device Regulation for all endoscopy equipment commercialized within the country. The Spanish Ministry of Health coordinates with regional health services to standardize procurement specifications, creating tiered product qualification requirements that filter market access. Healthcare technology assessment bodies in autonomous communities evaluate cost-effectiveness metrics before granting reimbursement codes for novel endoscopic procedures. Stakeholders must monitor regional procurement consolidation timelines and evolving MDR transition deadlines to align product registration and commercial strategies with Spanish market access requirements.
Market Dynamics
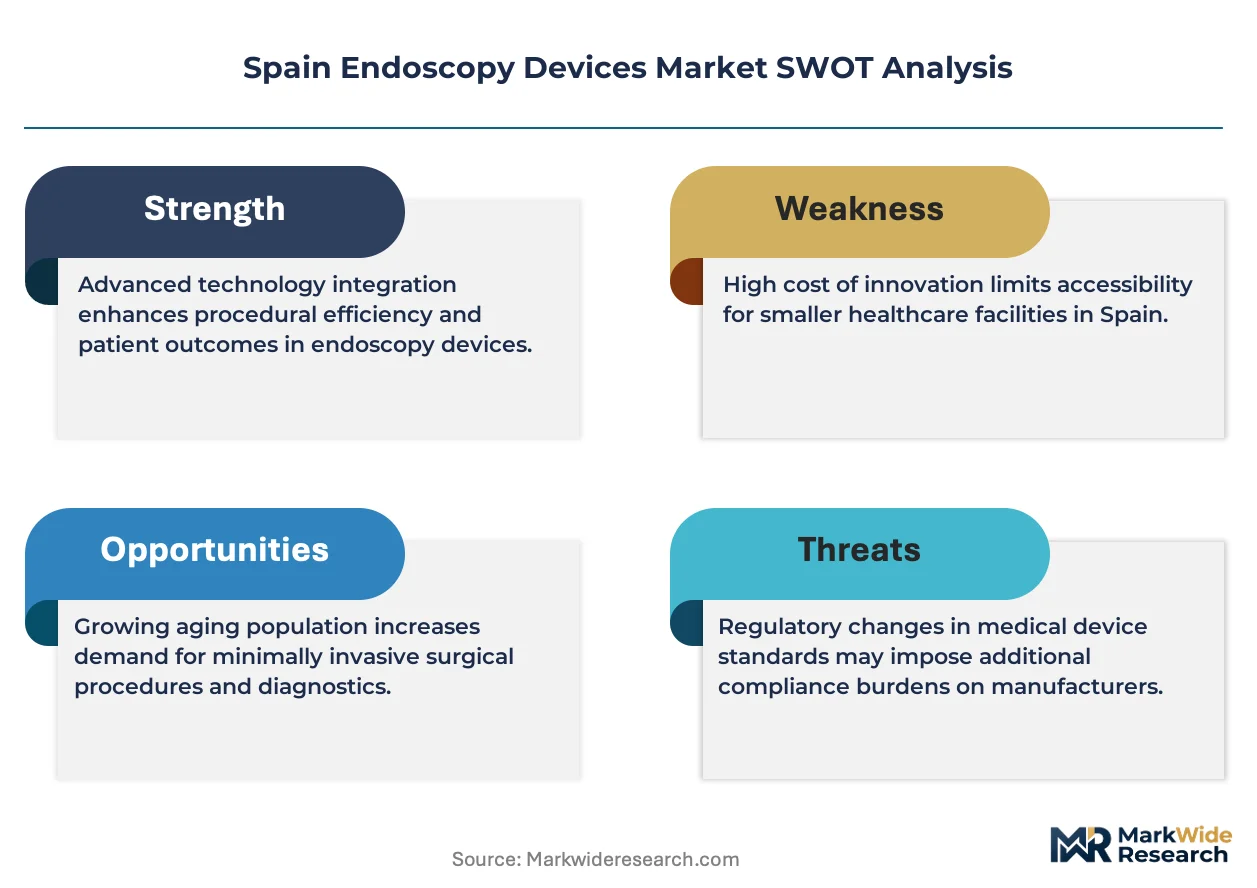
Hospital consolidation across Spain's autonomous communities is concentrating procurement authority into regional health consortia, compressing vendor access windows and elevating service-contract terms as decisive competitive levers.
Growth Catalysts
- EU MDR transition:Stricter CE marking requirements under the Medical Device Regulation are filtering out marginal suppliers and elevating compliant manufacturers with established quality management systems.
- Ambulatory surgical center expansion:Catalonia and Madrid are licensing new outpatient facilities, creating dedicated capital budgets for compact endoscopy suites outside traditional hospital infrastructure.
- Single-use endoscope adoption:Cross-contamination risk protocols are accelerating demand for disposable bronchoscopes and cystoscopes in high-turnover diagnostic workflows.
Market Restraints
- Optical component supply concentration:CMOS sensor fabrication depends on Taiwanese and South Korean foundries, exposing Spanish distributors to semiconductor allocation delays.
- Reimbursement lag for robotic platforms:AEMPS cost-effectiveness assessments trail technology introduction by 18-24 months, freezing capital deployment for computer-assisted systems.
- Capital intensity of visualization infrastructure:4K and 3D imaging towers require €150,000-€400,000 per installation, constraining adoption in smaller Castile-León and Galician hospitals.
Strategic Opportunities
- Andalusian healthcare modernization:Seville and Málaga hospital clusters are consolidating procurement under Servicio Andaluz de Salud, creating volume contracts for integrated endoscopy platforms.
- Artificial intelligence integration:Computer-aided polyp detection algorithms are converging with existing Olympus and Pentax processor units, opening software licensing revenue streams.
- Basque Country manufacturing incentives:SPRI-Basque government's industrial policy offers equipment depreciation allowances for medical technology investments in Bilbao and San Sebastián facilities.
Industry Challenges
- Specialized technician scarcity:Flexible endoscope repair and reprocessing requires certified biomedical engineering staff, with training programs at Universidad Politécnica de Madrid producing insufficient graduates for replacement demand.
- Legacy system integration friction:Hospitals running 2015-era processor towers face compatibility barriers when attaching wireless capsule endoscopy data streams to existing PACS infrastructure.
- MDR technical documentation burden:Clinical evaluation report requirements for novel indication claims consume 12-18 months of regulatory affairs capacity, delaying product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Endoscopy Devices Market |
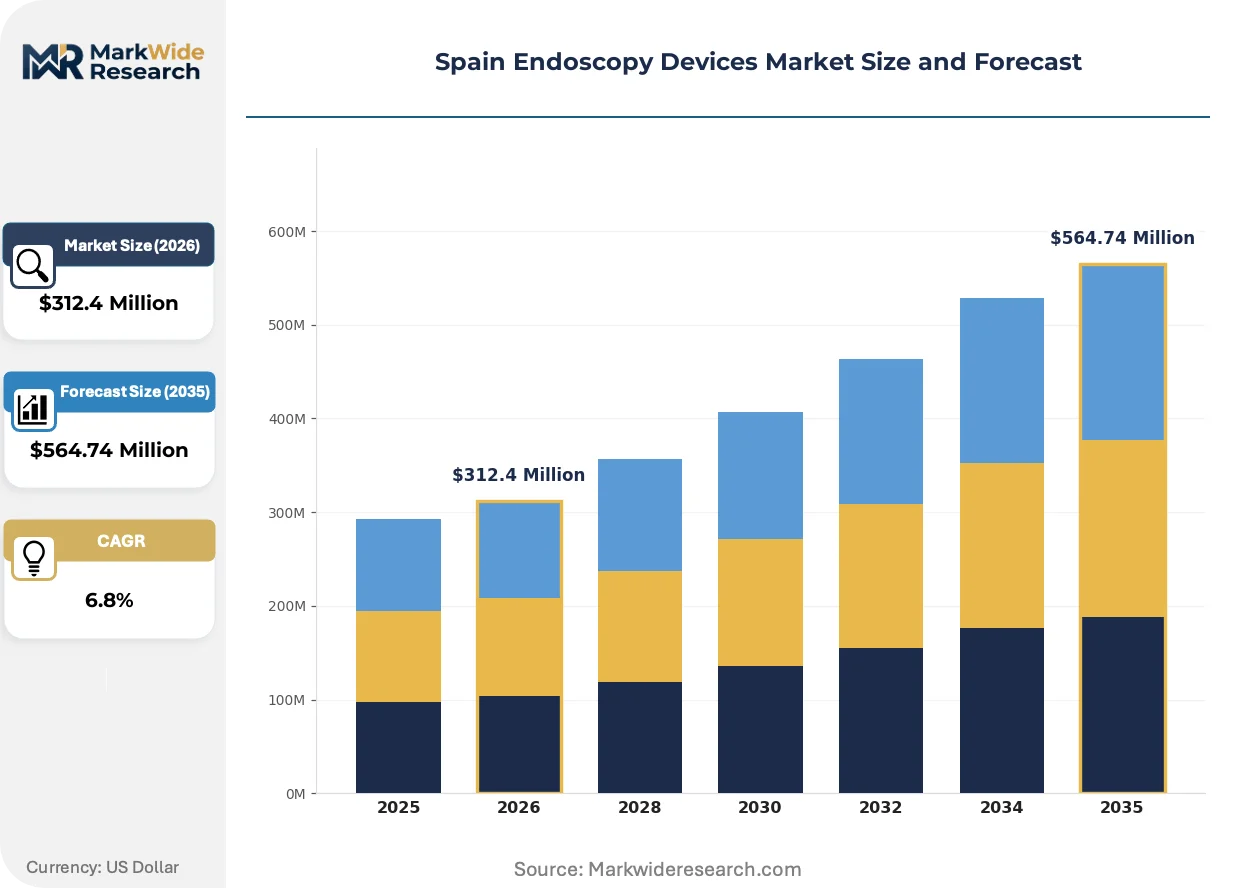
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Surgical Endoscopes Technology: Video Endoscopy, Ultrasound Endoscopy, Optical Endoscopy, Robotic Endoscopy End User: Hospitals, Clinics, Diagnostic Centers, Ambulatory Surgical Centers Application: Gastroenterology, Urology, Pulmonology, Gynecology |
| Companies Covered | Johnson & Johnson, FUJIFILM Corporation, Olympus Corporation, Cook Group, Stryker Corporation, Boston Scientific Corporation, Karl Storz, HOYA Corporation, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Endoscopy Devices Market Evolving Landscape
Digital imaging pipelines and disposable instrument formats are restructuring capital deployment patterns across Spanish healthcare procurement. These shifts compress equipment lifecycles while elevating software and service components in vendor contracts.
Modular processor architecture is modularizing the traditional all-in-one endoscopy tower. Basque Country hospitals and Catalan ambulatory centers are adopting component-separated systems that permit independent upgrade of light sources, video processors, and documentation modules. This approach is modularizing capital replacement cycles from seven-year full-tower swaps to targeted two-year component refreshes, reducing total cost of ownership for stretched regional budgets.
AEMPS enforcement of EU MDR post-market surveillance requirements is intensifying clinical follow-up obligations for high-risk endoscopic accessories. Manufacturers must now maintain systematic literature review protocols and periodic safety update reports for reusable biopsy forceps and polypectomy snares. The surgical endoscopy segment bears the heaviest documentation burden, with Johnson & Johnson and Boston Scientific restructuring Spanish regulatory affairs teams to manage expanded vigilance reporting.
After-sales service unbundling is fragmenting traditional bundled contracts in Madrid and Barcelona hospital systems. Procurement departments are separating equipment purchase from maintenance agreements, soliciting independent service providers for preventive maintenance and repair. This behavior is most pronounced in Valencian Community facilities, where Conselleria de Sanitat standardization directives encourage multi-vendor maintenance pools to reduce single-source dependency.
Spain Endoscopy Devices Market Segmentation
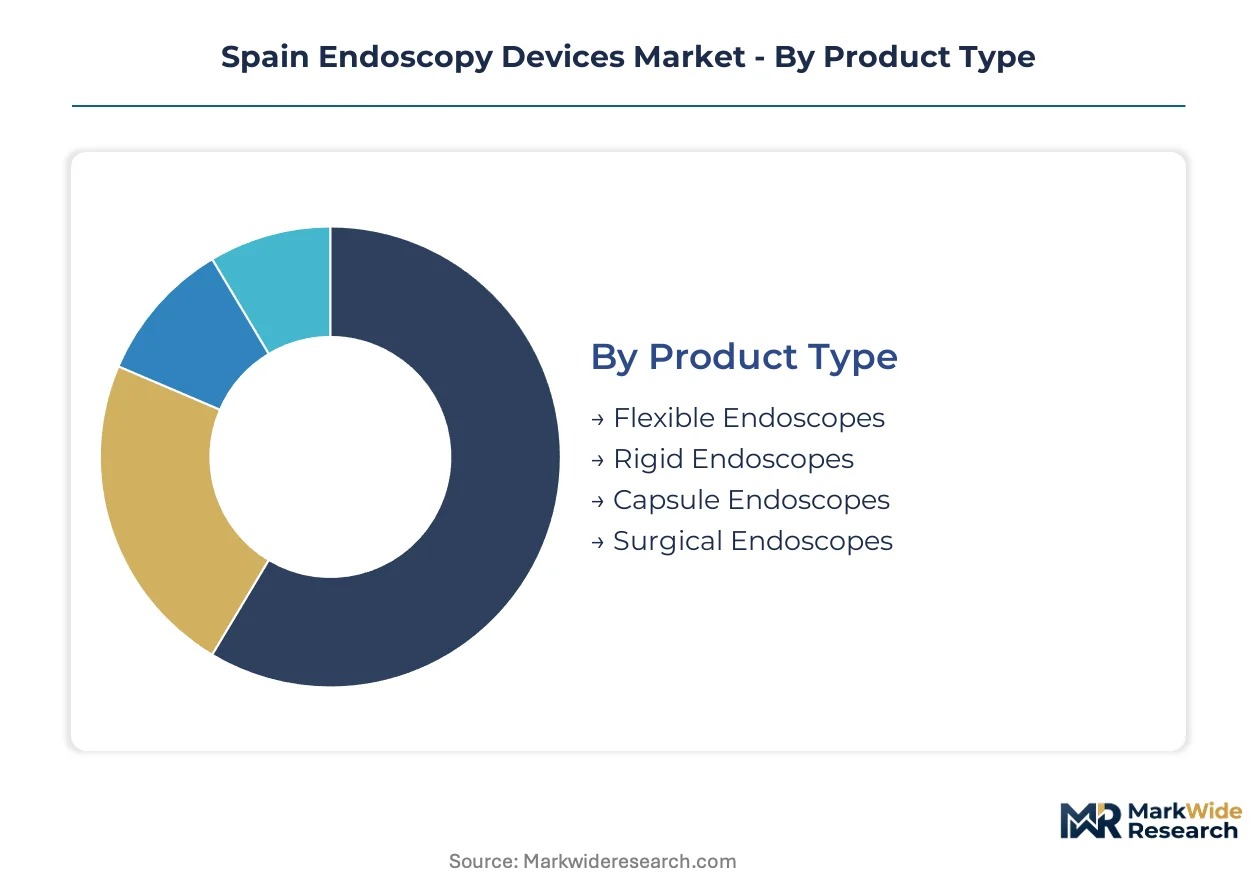
Endoscopy device segmentation in Spain reveals distinct procurement patterns across product formats, with integration depth determining whether systems deploy as standalone platforms or embedded surgical workflows. Understanding these structural divisions illuminates how regional health consortia allocate capital between versatile diagnostic tools and specialized therapeutic instruments.
Product Type:
Flexible systems dominate standalone diagnostic deployments, while rigid and surgical variants embed into integrated operative environments requiring precision mechanical stability.
- Flexible Endoscopes:Fiber-optic or digital imaging channels navigate tortuous anatomical pathways through steerable distal tips. Demand concentrates in Catalonia and Madrid hospital networks, where gastroenterology and pulmonology departments prioritize versatile single-platform solutions for high-throughput screening programs.
- Rigid Endoscopes:Stainless steel shaft constructions with fixed optical pathways deliver superior image stability for confined spaces. Urology suites in Andalusian and Valencian Community hospitals drive procurement, constrained by sterilization infrastructure requirements that limit ambulatory deployment.
- Capsule Endoscopes:Ingestible wireless imaging systems with CMOS sensors and LED illumination for small bowel examination.
- Surgical Endoscopes:Operative-channel configurations supporting energy delivery and instrument manipulation during laparoscopic and arthroscopic procedures.
Volume placements concentrate in Flexible Endoscopes; the faster expansion belongs to Surgical Endoscopes.
Technology:
Cost stratification separates premium visualization tiers from foundational optical systems, with capital intensity determining accessibility across regional budget tiers.
- Video Endoscopy:CCD or CMOS sensor-based digital imaging with external processor towers and high-definition display output. Basque Country and Madrid procurement clusters favor these systems, though AEMPS reimbursement lag for 4K upgrades constrains replacement cycles in Castile-León facilities.
- Robotic Endoscopy:Computer-assisted navigation platforms with haptic feedback and precision instrument positioning for complex polypectomies. Catalan hospital consortia lead adoption, facing 18-24 month capital freeze periods pending cost-effectiveness assessments.
- Ultrasound Endoscopy:Combined endoscopic and ultrasonic imaging for submucosal tissue characterization.
- Optical Endoscopy:Traditional fiber-optic light transmission systems with eyepiece or basic video coupling.
Video Endoscopy captures the largest installed base; Robotic Endoscopy climbs the fastest despite reimbursement friction.
End User:
Customer type segmentation tracks the migration of endoscopic procedures from centralized hospital infrastructure toward distributed outpatient settings.
- Hospitals:Comprehensive endoscopy departments with dedicated reprocessing facilities and 24-hour emergency therapeutic capability. Consolidated procurement under regional health consortia in Madrid and Barcelona compresses vendor access windows while elevating service-contract terms.
- Ambulatory Surgical Centers:Licensed outpatient facilities with compact procedure suites and same-day discharge protocols. Catalonia and Madrid licensing expansions create dedicated capital budgets outside traditional hospital infrastructure.
- Clinics:Limited-scope diagnostic practices with referral-dependent therapeutic pathways.
- Diagnostic Centers:Imaging-focused facilities prioritizing non-invasive examination capabilities.
Hospital procurement maintains volume leadership; Ambulatory Surgical Centers gain share fastest through provincial licensing expansion.
Application:
Procedure volume distribution across medical specialties determines equipment configuration requirements and utilization intensity.
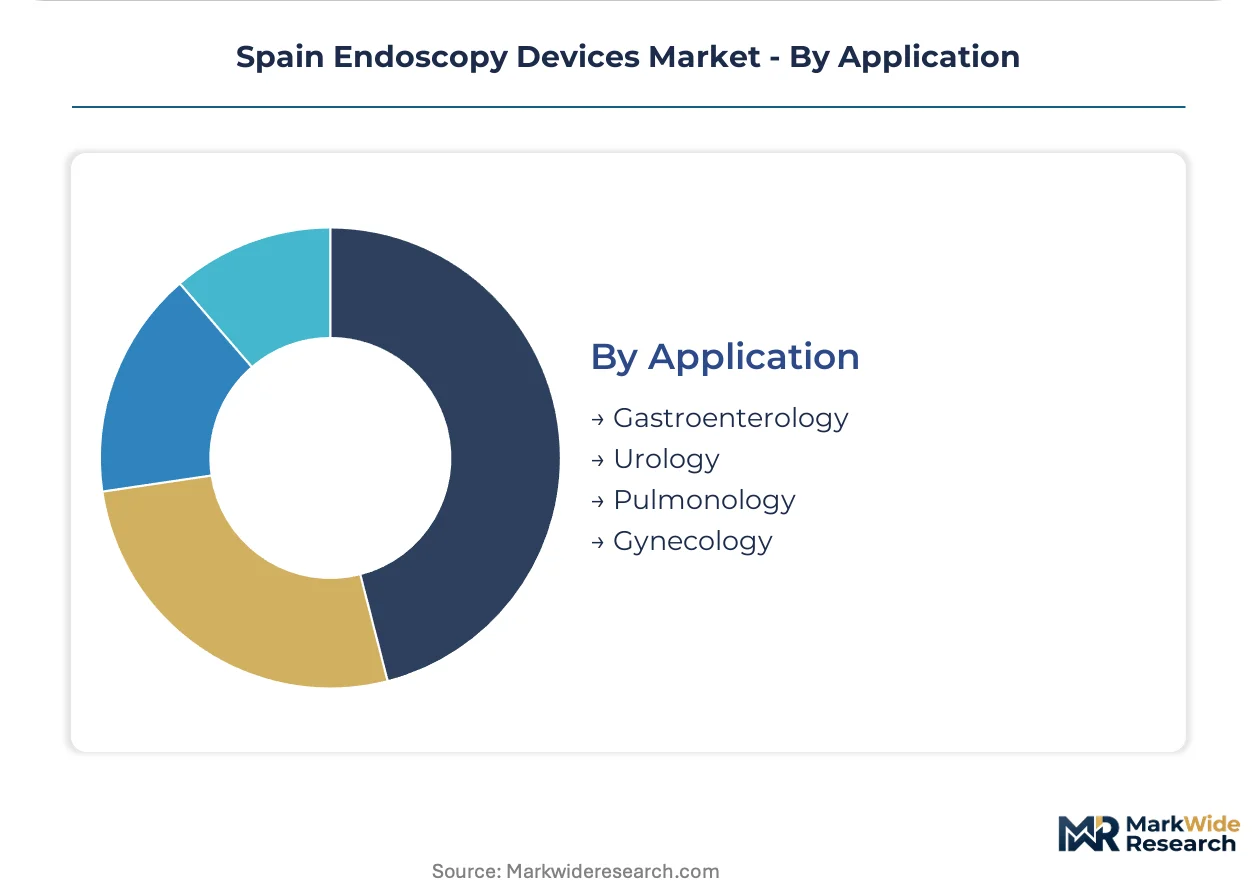
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy workflows with polypectomy and biopsy capabilities. Screening program mandates in multiple autonomous communities sustain the highest procedure volumes, with AI-assisted polyp detection now integrating into existing processor platforms.
- Urology:Cystoscopy and ureteroscopy procedures requiring rigid or semi-rigid instrument configurations. Karl Storz visualization systems anchor demand through specialized equipment for minimally invasive stone and tumor management.
- Pulmonology:Bronchoscopic airway examination with transbronchial biopsy and lavage functionality.
- Gynecology:Hysteroscopic and laparoscopic procedures for diagnostic and operative interventions.
Gastroenterology procedures generate the highest equipment utilization; Urology applications show the steepest expansion trajectory through specialized visualization adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain consumes endoscopy devices through regional health consortia while domestic production concentrates in Basque Country medical technology clusters. Manufacturing capacity remains limited, forcing reliance on German, Japanese, and US imports for core visualization systems.
Catalonia
Barcelona hospital networks drive flexible endoscope procurement volumes through consolidated Servicio Catalán de la Salud contracts. Catalan health authorities enforce EU MDR compliance timelines through regional health technology assessment protocols. Girona and Tarragona ambulatory surgical centers expand licensing, creating distributed demand outside metropolitan hospital infrastructure.
Madrid
The capital region concentrates Spain's highest endoscopy procedure density through Hospital Universitario La Paz and Hospital Clínico San Carlos installations. Madrid's regional health service standardizes procurement specifications, filtering vendor access through pre-qualification requirements. Alcorcón and Móstoles hospital clusters consolidate purchasing under Servicio Madrileño de Salud, compressing negotiation windows for equipment suppliers.
Basque Country
Bilbao and San Sebastián anchor Spain's domestic medical device manufacturing through SPRI-Basque government industrial incentives. Basque health technology firms supply specialized rigid endoscope components to regional hospitals while importing complete systems from German and Japanese vendors. Vitoria-Gasteiz hospital procurement integrates with Basque Country manufacturing depreciation allowances, channeling capital toward local equipment investments.
Andalusia
Seville and Málaga hospital clusters consolidate procurement under Servicio Andaluz de Salud, creating volume contracts for integrated endoscopy platforms. Andalusian regional authorities coordinate with AEMPS on EU MDR transition timelines for existing device installations. Córdoba and Granada diagnostic centers expand gastroenterology screening programs, elevating flexible endoscope utilization rates.
Valencia
Conselleria de Sanitat standardization directives encourage multi-vendor maintenance pools across Valencian Community hospitals. Valencia and Alicante surgical suites prioritize surgical endoscope configurations for urology and gynecology applications. Castellón ambulatory facilities license new outpatient endoscopy services, diverting procedural volume from traditional hospital departments.
Spain Endoscopy Devices Market Competitive Landscape
Top-tier vendors anchor hospital procurement through direct service contracts, while mid-tier specialists compete on ambulatory surgical center configurations. The market structure consolidates around manufacturers with established EU MDR quality management systems and regional service networks. Three archetypes dominate: diversified medical technology conglomerates with broad surgical portfolios, specialized endoscope manufacturers with dedicated visualization expertise, and disposable instrument innovators targeting cross-contamination protocols. Competitive dynamics center on M&A activity absorbing compliant smaller players and strategic partnerships linking hardware vendors with AI software developers.
Among diversified conglomerates, Johnson & Johnson and Medtronic PLC occupy positions spanning surgical energy and visualization portfolios. Olympus Corporation anchors the specialized tier through flexible endoscope supply relationships with Catalan and Madrid health consortia. Boston Scientific Corporation exemplifies the therapeutic intervention archetype, with product configurations targeting polypectomy and biopsy workflows.
| Leading Market Players |
|---|
| Johnson & Johnson |
| FUJIFILM Corporation |
| Olympus Corporation |
| Cook Group |
| Stryker Corporation |
| Boston Scientific Corporation |
| Karl Storz |
| HOYA Corporation |
| Medtronic PLC |
| Others |
Value Network & Pricing Analysis
Japanese and German conglomerate-owned manufacturers anchor Spain's endoscopy supply base, translating captive component production into pricing discipline that resists commoditization despite regional procurement consolidation. Their direct service contracts with Catalan and Madrid health consortia embed multi-year pricing stability clauses that insulate installed base revenues from spot-market volatility.
Pricing Analysis
Cost-down pressure on mid-tier visualization platforms accelerates because AEMPS reimbursement lag freezes 4K upgrade cycles in Castile-León and Galician hospitals. Three-tier pricing structure across premium robotic systems, standard video towers, and economy optical configurations separates Olympus and Karl Storz flagship offerings from disposable bronchoscope challengers. Brand premium and CE-MDR certification tier differentiate vendor access to Servicio Madrileño de Salud pre-qualification lists. Ambulatory surgical centers exhibit highest price sensitivity due to compact capital budgets, while consolidated regional hospital consortia leverage volume scale for service-contract concessions.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Amsterdam feed Spanish hospital procurement through hub-and-spoke patterns that concentrate inventory risk with authorized distributors. CMOS sensor fabrication draws from Taiwanese and South Korean foundries, while German optical glass and Japanese fiber-optic bundles anchor rigid and flexible endoscope production. Single-source vulnerability in semiconductor allocation exposes Spanish distributors to foundry capacity constraints. Distribution runs through Olympus and Johnson & Johnson direct service networks rather than independent medical device wholesalers, preserving vendor control over installation and maintenance pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's endoscopy market is becoming a vertical-integration race as manufacturers pursue backward control over CMOS sensor supply and captive reprocessing service capacity to lock out modular competitors.
For Market Incumbents: Deploy AI software licensing as a recurring revenue anchor against disposable endoscope challengers eroding capital equipment attach rates. Deepen backward integration into CMOS sensor sourcing through strategic foundry partnerships, reducing exposure to Taiwanese allocation delays. Fortify direct service contracts with Servicio Andaluz de Salud and Servicio Catalán de la Salud to preempt independent maintenance pool fragmentation. For New Entrants and Emerging Players: Begin with single-use bronchoscope and cystoscope configurations targeting Valencian Community diagnostic centers, where cross-contamination protocols outpace capital budget constraints for reusable systems. Exploit the reimbursement assessment window for robotic platforms by positioning computer-assisted navigation as software upgrades to existing processor towers rather than standalone capital requests. Pursue GPO contracts with emerging Andalusian ambulatory surgical centers before regional consolidation matures. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-compliant mid-cap specialists with established AEMPS registrations and Basque Country manufacturing footprints. Long-term viability hinges on software-hardware integration depth rather than standalone instrument margins. Monitor AEMPS cost-effectiveness assessment publication velocity as the inflection signal for robotic platform capital deployment thaw.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | AEMPS MDR compliance filters market access to consolidated regional health consortia. |
| Hospital System Partnership | Direct service contracts with Servicio Madrileño de Salud secure multi-year installed base lock-in. |
| Software Companion Development | AI polyp detection algorithms integrate with existing Olympus processor units for recurring licensing revenue. |
| Backward Integration | Captive CMOS sensor sourcing insulates production from Taiwanese foundry allocation delays. |
| Reimbursement Strategy | Early AEMPS health technology assessment engagement compresses 18-24 month robotic platform approval lag. |
Research Methodology
Document review covered AEMPS regulatory filings, EU MDR technical documentation databases, and regional health service procurement records, complemented by interviews with hospital biomedical engineers, GPO contracts managers, and regulatory affairs leads at visualization system manufacturers. Secondary validation drew from Servicio Andaluz de Salud annual reports, Catalan health technology assessment publications, and Basque Country industrial incentive disclosures. Bottom-up equipment installation tracking across Madrid and Barcelona hospital networks was cross-referenced with top-down vendor revenue segmentation.
Historical procurement volume trajectories were cross-referenced against panel input from procurement directors at consolidated regional health consortia. The analytical framework modeled product type, technology tier, end-user facility category, and application specialty across the projection horizon. CAGRs were derived from segmented procedure volume growth and equipment replacement cycle compression. Forecast inputs incorporated EU MDR transition timelines, ambulatory surgical center licensing expansion rates, and AI software adoption curves in gastroenterology screening programs.
Underlying measurement precision varies by segment; flexible endoscope installed base estimates carry tighter precision than robotic platform projections due to consolidated procurement visibility. Forecasts reflect documented assumptions regarding reimbursement policy continuity and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that AEMPS assessment delays or foundry allocation shocks could materially revise capital deployment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Duodenoscope Market