
 Submucosal Injections Market | 2026-2036
Submucosal Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Submucosal Injections Market Analytics
Consolidation among hospital procurement networks is repositioning how submucosal injection systems reach end users. Boston Scientific leverages its integrated endoscopy portfolio to secure multi-year supply agreements with IDN purchasing coalitions. Medtronic sustains competitive pressure through its broad interventional GI franchise and direct hospital contracting infrastructure. ERBE Elektromedizin GmbH differentiates via specialized electrosurgical and injection platforms tailored to European procedural protocols.
Submucosal injections deliver pharmaceutical or lifting agents beneath the mucosal layer to create tissue elevation, typically employing saline-epinephrine mixtures, hyaluronic acid formulations, or dyed viscous solutions that enable precise endoscopic dissection and lesion resection. The technique serves primarily to prevent perforation during endoscopic mucosal resection and endoscopic submucosal dissection by separating mucosa from muscularis propria. Biologics and local anesthetics represent the most dynamic product categories, with biologics commanding premium positioning due to complex cold-chain handling and specialized administration training. Auto-injector and syringe delivery modes dominate current utilization, though needle-free systems are gaining traction in outpatient settings where clinician ergonomics and patient throughput matter most.
FDA oversight of combination products, combined with EMA's Medical Device Regulation requirements and Japan's PMDA pharmaceutical affairs standards, shapes approval timelines and clinical evidence demands across major markets. These frameworks elevate barriers for new entrants while rewarding manufacturers with established quality management systems and robust post-market surveillance capabilities. Stakeholders must monitor evolving reimbursement decisions by CMS and analogous national payers, as coverage determinations for advanced endoscopic resection techniques will dictate capital allocation toward submucosal injection platform development.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating technical performance requirements for submucosal injection platforms. Integrated delivery networks now demand single-source contracts covering endoscopes, electrosurgical units, and lifting agents, forcing manufacturers to bundle hardware with proprietary pharmaceutical formulations.
Growth Catalysts
- FDA Combination Product Guidance:The agency's clarified framework for device-drug combinations accelerates 510(k) pathways for integrated injection systems, reducing premarket review timelines for manufacturers with established quality systems.
- Academic Medical Center Protocol Standardization:Leading US teaching hospitals are formalizing ESD training curricula that mandate specific submucosal lifting agents, creating institutional lock-in for approved suppliers.
- Hyaluronic Acid Formulation Advances:Next-generation viscoelastic solutions with extended elevation duration enable complete en-bloc resection in complex gastric lesions, expanding addressable procedure volume.
Market Restraints
- Saline-Epinephrine Cost Floor:Generic lifting agent availability caps pricing power for premium viscous formulations, compressing margin expansion in commodity-sensitive hospital segments.
- Japanese PMDA Pharmaceutical Affairs Standards:Stringent stability testing requirements for biologic lifting agents extend registration timelines, delaying market entry for novel formulations.
- Needle Reprocessing Economics:Single-use injection needle mandates in German endoscopy centers elevate per-procedure supply costs, constraining adoption in budget-constrained outpatient settings.
Strategic Opportunities
- India CDSCO Fast-Track Registration:The regulator's abbreviated review pathway for devices with US or EU approval enables accelerated entry into Asia's fastest-growing endoscopy market.
- Ambulatory Surgery Center Channel Development:Outpatient GI facilities represent underpenetrated demand, requiring compact, pre-filled injection systems that eliminate pharmacy compounding steps.
- Needle-Free Jet Injection Convergence:Integration of gas-powered delivery with standard endoscope channels eliminates sharps handling, addressing clinician ergonomic concerns in high-throughput settings.
Industry Challenges
- ESD Technical Skill Acquisition:Extended learning curves for endoscopic submucosal dissection limit qualified operator pools, constraining procedure volume growth despite available equipment.
- Cold-Chain Biologics Handling:Temperature-sensitive hyaluronic acid formulations require validated distribution infrastructure that many regional distributors lack, creating fulfillment gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submucosal Injections Market |
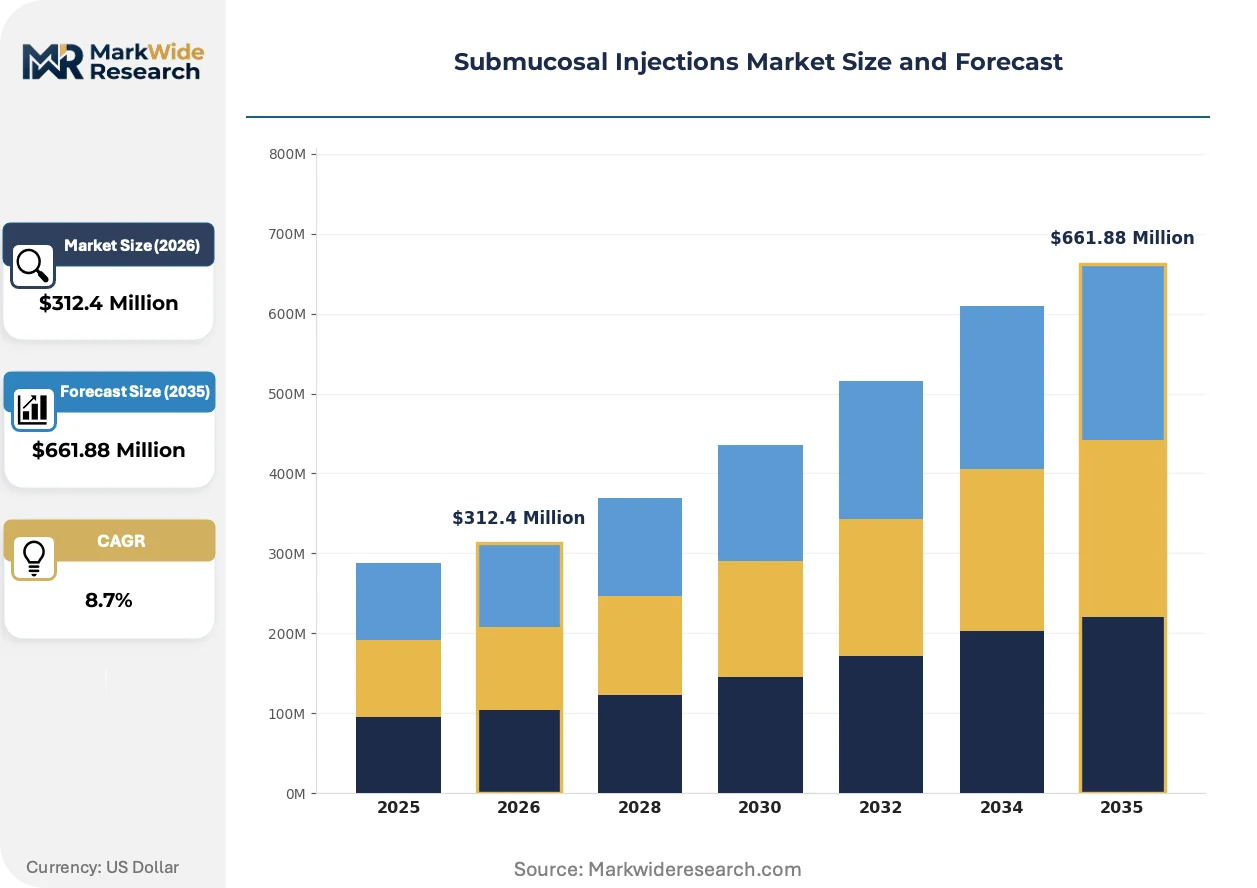
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Biologics, Vaccines, Local Anesthetics Therapy Area: Diabetes, Oncology, Anesthesia, Immunology End User: Hospitals, Outpatient Clinics, Home Care, Specialty Pharmacies Delivery Mode: Syringe, Auto-Injector, Needle-Free, Infusion Pump |
| Companies Covered | Seikagaku, GI Supply, Boston Scientific, ERBE Elektromedizin GmbH, Cosmo Pharmaceuticals, Medtronic, Ovesco Endoscopy, Micro-Tech Endoscopy, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submucosal Injections Market Evolving Landscape
Submucosal injection technology is fragmenting into specialized platforms optimized for specific lesion morphologies and procedural settings. Manufacturers are responding with configurable delivery systems that accommodate multiple lifting agent viscosities through common hardware interfaces.
Modular cartridge systems for submucosal injection is modularizing equipment purchasing decisions across hospital systems. Academic medical centers in the United States are piloting platform-agnostic delivery units that accept proprietary, standard, and compounded lifting agents interchangeably. This flexibility is compressing vendor lock-in effects while elevating performance benchmarking transparency.
EMA Medical Device Regulation recertification requirements are elevating clinical evidence standards for legacy injection platforms. Manufacturers must now submit post-market surveillance data demonstrating sustained mucosal elevation performance across diverse lesion types. European hospital procurement committees are prioritizing MDR-compliant suppliers in tender evaluations, disadvantaging smaller manufacturers with limited regulatory affairs capacity.
Direct contracting between manufacturers and integrated delivery networks is displacing traditional distributor relationships in the United States. IDN supply chain executives are negotiating multi-year agreements that bundle injection systems with training credits and outcome guarantees. This concentration is most visible in the Northeast and Midwest, where Catholic health systems and academic consortia command substantial endoscopy procedure volume.
Submucosal Injections Market Segmentation
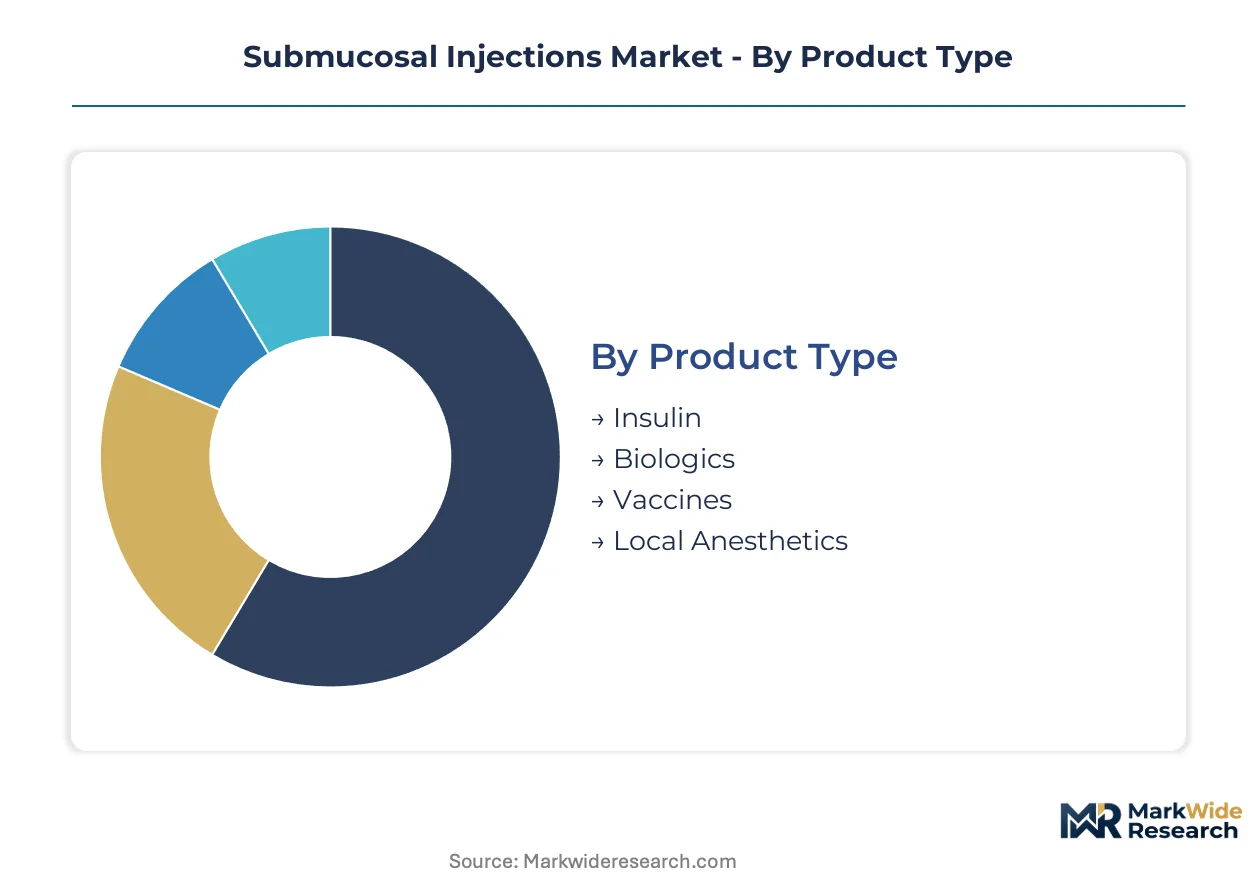
Submucosal injection platforms serve distinct clinical workflows that demand tailored formulation viscosities, delivery precision, and handling protocols. Understanding how product specifications align with procedural settings enables manufacturers to prioritize R&D investments and distribution partnerships.
Product Type:
Formulation chemistry determines elevation duration, tissue compatibility, and cold-chain requirements across endoscopic resection procedures.
- Biologics:Hyaluronic acid and collagen-based matrices provide sustained submucosal cushion for complex en-bloc resections. Academic medical centers in the United States favor these formulations for gastric ESD despite premium pricing and validated distribution requirements.
- Local Anesthetics:Lidocaine-epinephrine combinations enable rapid mucosal elevation with concurrent analgesia during colonoscopic polypectomy. Outpatient GI facilities concentrate procurement here due to immediate availability and minimal pharmacy preparation.
- Insulin:Specialized viscous carriers for research applications in submucosal drug delivery studies.
- Vaccines:Investigational mucosal immunization platforms utilizing submucosal deposition for enhanced lymphatic uptake.
Mature deployment sits with local anesthetics. Newer deployment is concentrated in biologics.
Therapy Area:
Procedural indication dictates lesion morphology, resection complexity, and lifting agent performance specifications.
- Anesthesia:Peri-procedural pain management integration drives co-formulation with lifting agents. Japanese endoscopy centers lead protocol development here, influenced by PMDA pharmaceutical affairs standards for combination product safety.
- Oncology:Early-stage GI neoplasia resection demands precise submucosal plane definition to achieve negative margins. German university hospitals anchor European demand through formalized ESD training curricula.
- Diabetes:Submucosal delivery research for metabolic peptide administration.
- Immunology:Mucosal immune modulation studies leveraging submucosal lymphatic access.
Volume concentrates in anesthesia applications. Steepest expansion trajectory appears in oncology as ESD adoption broadens.
End User:
Facility infrastructure and case complexity determine delivery system configuration and supply chain requirements.
- Hospitals:Integrated surgical suites with dedicated endoscopy units manage high-complexity ESD procedures requiring multi-viscosity agent portfolios. IDN procurement coalitions in the United States negotiate bundled contracts covering hardware and pharmaceutical supply.
- Outpatient Clinics:Ambulatory GI centers prioritize single-use, pre-filled systems that eliminate pharmacy compounding and accelerate room turnover. Cost sensitivity here favors saline-epinephrine formulations.
- Home Care:Limited applicability for submucosal injection; confined to research settings.
- Specialty Pharmacies:Cold-chain biologics distribution and compounding services for hospital networks lacking in-house pharmacy infrastructure.
Procurement authority rests with hospitals. Patient throughput priorities are elevating outpatient clinic requirements fastest.
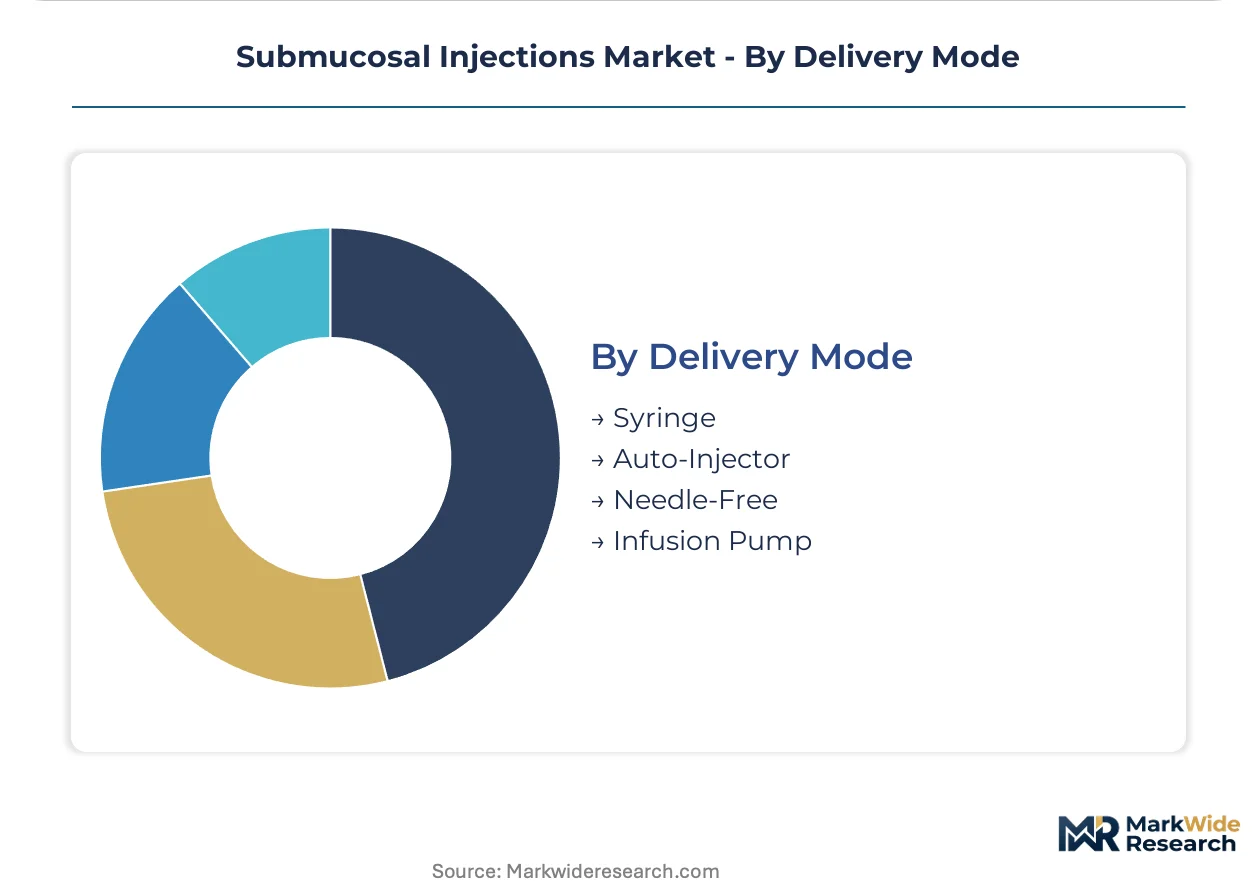
Delivery Mode:
Mechanism of agent deposition shapes clinician ergonomics, procedural safety, and capital equipment requirements.
- Syringe:Standard endoscope-compatible injection needles offer lowest per-procedure cost and broad agent compatibility. German endoscopy centers face elevated supply costs from single-use needle mandates under national infection control protocols.
- Auto-Injector:Spring-powered systems standardize injection depth and volume for operators with variable experience. United States academic centers specify these in training curricula to reduce technical variability.
- Needle-Free:Gas-powered jet injection eliminates sharps handling and enables rapid sequential deployment. Outpatient settings with high lesion burden are piloting these systems for throughput gains.
- Infusion Pump:Continuous submucosal perfusion for extended dissection procedures; limited current utilization.
Installed base concentrates in syringe systems. Fastest capability investment flows toward needle-free platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers concentrate demand for advanced submucosal injection platforms, driving protocol standardization that ripples through procurement networks worldwide. Japan and Germany anchor specialized technique development through formalized ESD training curricula. Emerging markets in India and Brazil are accelerating regulatory harmonization to capture technology transfer from established manufacturing hubs.
United States
Integrated delivery networks in the Northeast and Midwest negotiate bundled contracts covering endoscopes, electrosurgical units, and lifting agents. FDA combination product guidance accelerates 510(k) pathways for device-drug integrated systems. The Cleveland Clinic and Mayo Clinic anchor protocol development for hyaluronic acid formulations in complex gastric ESD procedures.
Japan
University hospitals in Tokyo and Osaka lead global ESD volume through formalized operator certification programs. PMDA pharmaceutical affairs standards impose stringent stability testing requirements for biologic lifting agents. The National Cancer Center Hospital drives clinical evidence generation for next-generation viscoelastic solutions with extended elevation duration.
Germany
University hospitals in Berlin and Munich anchor European demand through standardized ESD training curricula and infection control protocols. Single-use injection needle mandates elevate per-procedure supply costs in outpatient endoscopy centers. ERBE Elektromedizin GmbH maintains headquarters in Tübingen, shaping regional electrosurgical and injection platform specifications.
India
Metro hospital chains in Mumbai and Delhi expand endoscopy service lines to capture rising GI cancer screening volume. CDSCO fast-track registration enables accelerated market entry for devices with US or EU approval. Apollo Hospitals and Fortis Healthcare pilot platform-agnostic delivery units that accept multiple lifting agent formulations.
Brazil
São Paulo and Rio de Janeiro concentrate private hospital investment in advanced endoscopic resection capabilities. ANVISA regulatory alignment with FDA and EMA standards reduces registration friction for imported platforms. Hospital Israelita Albert Einstein and Hospital Sírio-Libanês anchor technique adoption through international training partnerships.
Submucosal Injections Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in electrosurgical integration and formulation chemistry respectively. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with integrated endoscopy portfolios, specialized electrosurgical equipment manufacturers, and pharmaceutical-focused formulation suppliers. Competitive dynamics center on multi-year IDN supply agreements and M&A activity targeting complementary injection platform technologies.
Within the diversified medtech tier, Boston Scientific Corporation and Medtronic exemplify scale-driven positioning through broad interventional GI franchises and direct hospital contracting infrastructure. ERBE Elektromedizin GmbH occupies a specialized position among European manufacturers, with its Tübingen headquarters reflecting deep regional integration into German and broader European procedural protocols. These three anchors represent distinct competitive vectors: conglomerate breadth, specialized electrosurgical expertise, and formulation-led pharmaceutical positioning.
| Leading Market Players |
|---|
| Seikagaku |
| GI Supply |
| Boston Scientific |
| ERBE Elektromedizin GmbH |
| Cosmo Pharmaceuticals |
| Medtronic |
| Ovesco Endoscopy |
| Micro-Tech Endoscopy |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
Hyaluronic acid premium tier divergence from saline-epinephrine commodity baseline manifests in both pricing power and supply chain configuration. Academic medical centers in the United States absorb premium markups for validated cold-chain biologics, while outpatient clinics in Germany and India source generic formulations through regional distributors with minimal handling infrastructure.
Pricing Analysis
Volume concentrates in saline-epinephrine commodity tiers where generic availability caps margin expansion, while margin concentrates in hyaluronic acid biologics commanding premium positioning through extended elevation duration and specialized training requirements. Price differentiation hinges on FDA combination product classification tier and validated cold-chain certification status. Pricing pressure stems from IDN procurement consolidation bundling hardware with proprietary pharmaceutical formulations. Outpatient clinics exhibit highest price sensitivity, while academic medical centers demonstrate lowest sensitivity due to protocol standardization mandates.
Supply Chain Analysis
Single-source vulnerability sits with hyaluronic acid raw material suppliers concentrated in Japan and South Korea, where fermentation-based production requires specialized bioreactor capacity. Finished device assembly draws from Germany, the United States, and China for electrosurgical components and injection needle manufacturing. Supply chain risk centers on PMDA pharmaceutical affairs stability testing delays extending registration timelines for novel biologic formulations. Distribution runs through IDN procurement coalitions in the United States, hospital purchasing committees in Germany, and metro hospital chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation functions as a consolidation play, forcing smaller formulation suppliers without IDN contracting infrastructure toward acquisition or exit.
For Market Incumbents: Lock in multi-year IDN supply agreements before competitor formulation suppliers achieve MDR recertification, securing preferred vendor status through bundled training credits and outcome guarantees. Deepen backward integration into hyaluronic acid fermentation capacity to insulate margin from raw material single-source exposure. Prioritize CE marking pathway acceleration for next-generation viscoelastic solutions. For New Entrants and Emerging Players: Ambulatory surgery center channel partners represent the most penetrable entry vector, requiring compact pre-filled systems that eliminate pharmacy compounding steps. Target India's CDSCO fast-track registration pathway for devices with existing US or EU approval, leveraging Apollo Hospitals and Fortis Healthcare pilot programs for platform-agnostic delivery units. Pursue needle-free jet injection convergence as the primary go-to-market angle, addressing clinician ergonomic concerns in high-throughput outpatient settings. For Investors and Strategic Acquirers: Re-rating potential sits with specialized electrosurgical equipment manufacturers given EMA MDR recertification elevating clinical evidence standards for legacy injection platforms. Long-term viability favors suppliers with established quality management systems and robust post-market surveillance capabilities across the 5-10 year regulatory tightening horizon. Acquisition target archetype: European manufacturers with limited regulatory affairs capacity facing MDR compliance pressure. Signal to watch: CMS reimbursement determinations for advanced endoscopic resection techniques dictating capital allocation toward submucosal injection platform development.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Device-Drug Combination | Accelerated premarket review timelines reward manufacturers with established quality systems under FDA combination product guidance. |
| CE Marking Pathway Under MDR | Post-market surveillance data requirements disadvantage smaller European manufacturers with limited regulatory capacity. |
| Hospital System Partnership with IDN Procurement Coalitions | Bundled contracts covering endoscopes, electrosurgical units, and lifting agents secure multi-year supply agreements. |
| Software Companion Development for Injection Depth Guidance | Standardized injection parameters reduce technical variability for operators with variable ESD experience. |
| Reimbursement Strategy Alignment with CMS Coverage Determinations | Capital allocation toward platform development depends on Medicare coverage for advanced mucosal therapies. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA filings, EMA submissions, and hospital procurement databases. Bottom-up procedure volume estimates triangulate against top-down market sizing from device manufacturer revenue disclosures.
Comparable-period anchoring to historical ESD adoption curves and hyaluronic acid formulation penetration rates structures the forecast window. Segmentation dimensions modeled include formulation chemistry, therapy area, end user facility type, and delivery mode across the projection horizon. CAGRs derive from weighted average of procedure volume growth, pricing trajectory by tier, and technology substitution rates. Industry-specific inputs incorporate PMDA registration timeline assumptions and IDN procurement consolidation velocity.
Caveats apply where CMS reimbursement decisions, PMDA stability testing requirement changes, or needle-free system clinical validation could materially shift the outlook. Forecasts reflect assumptions about ESD training curriculum standardization and cold-chain distribution infrastructure expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phoropters Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Global Bone Cement Market
Medical Devices
Global Nebulizers Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Global Walking Assist Devices Market