
 Endoscopy Market | 2026-2036
Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Market Analysis
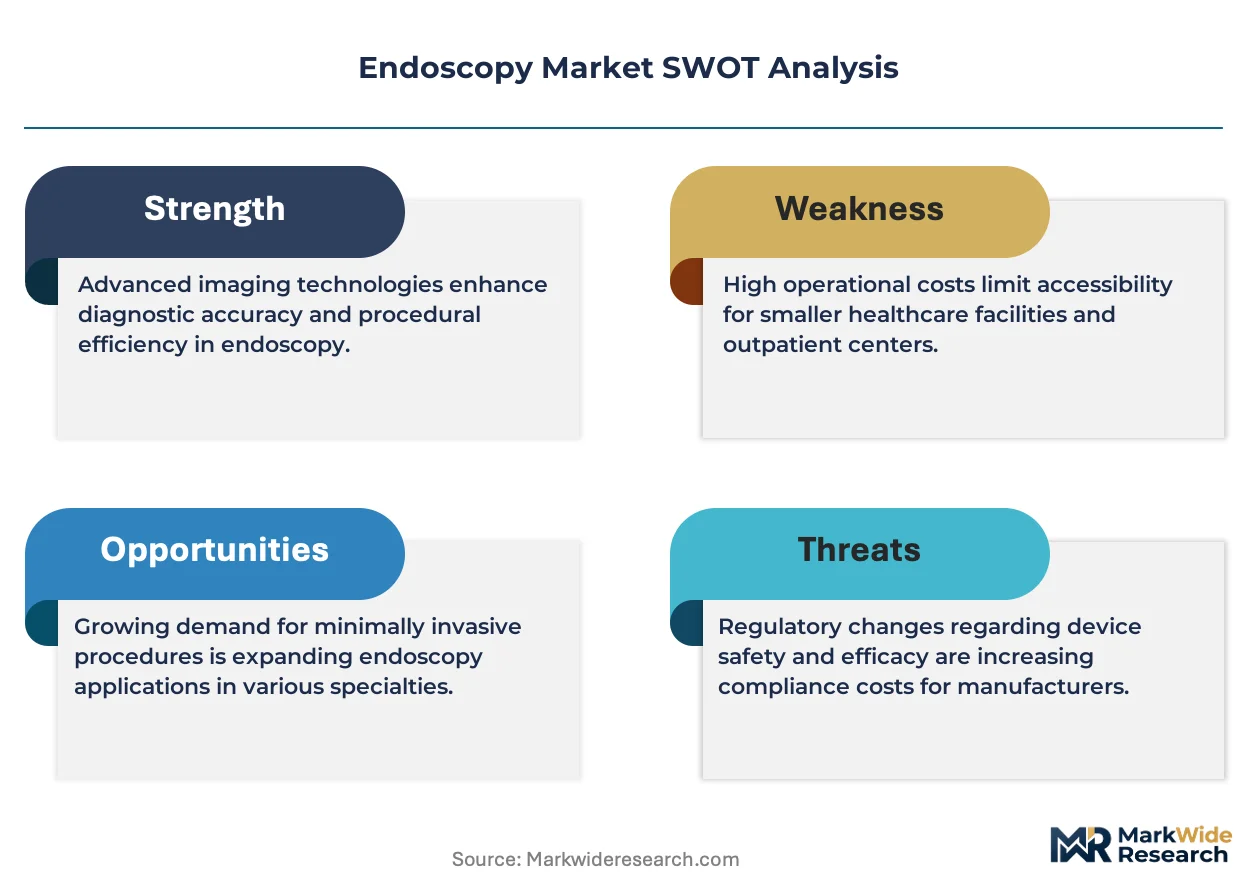
EU MDR is broadening the cost-of-entry calculus for endoscope manufacturers seeking CE marking in Europe. Olympus Corporation leverages its vertically integrated optical component supply chain to sustain margin control across rigid and flexible systems. Karl Storz SE & Co. KG anchors its position through precision-engineered surgical endoscopes for minimally invasive procedures. Boston Scientific Corporation competes in the single-use segment with disposable bronchoscopes that eliminate reprocessing liability.
Endoscopy encompasses the insertion of illuminated, optically or digitally enhanced instruments through natural orifices or small incisions to visualize, diagnose, and treat internal organs and cavities, with modern systems employing CMOS or CCD sensors delivering resolutions exceeding 1080p for real-time tissue differentiation. The technology serves gastrointestinal screening, oncological staging, and therapeutic intervention across outpatient and inpatient settings. Flexible endoscopes occupy the largest installed base due to their versatility across gastroenterology and pulmonology applications, while single-use endoscopes represent the fastest-expanding product category as infection control protocols tighten. Video endoscopy dominates technology deployment, though robotic endoscopy is gaining traction for procedures requiring enhanced dexterity and stability.
FDA reprocessing guidelines, EU MDR conformity requirements, and ISO 13485 quality management standards collectively elevate compliance burdens and reshape product development priorities for manufacturers. These frameworks drive capital allocation toward disposable platforms and automated cleaning validation systems rather than incremental improvements to reusable architectures. Stakeholders must weigh the trade-off between per-procedure cost economics and liability exposure when configuring endoscope portfolios for hospital and ambulatory customers.
Market Dynamics
The FDA's updated reprocessing guidance is compressing the viable lifespan of reusable endoscope architectures while accelerating capital reallocation toward disposable platforms across ambulatory surgical centers and hospital systems.
Growth Catalysts
- EU MDR compliance mandates:Stricter CE marking requirements for reusable devices are elevating the total cost of ownership, tilting procurement evaluations toward single-use alternatives that bypass reprocessing validation burdens.
- Ambulatory surgical center expansion:Freestanding outpatient facilities in the United States are prioritizing infection control protocols that favor disposable bronchoscopes and colonoscopes to eliminate cross-contamination liability exposure.
- CMOS sensor diffusion:Solid-state imaging components are displacing legacy CCD architectures, enabling thinner instrument diameters and improved maneuverability in gastroenterology and pulmonology procedures.
Market Restraints
- Optical component supply concentration:Precision lens and fiber optic suppliers in Germany and Japan control critical upstream capacity, creating bottleneck risk for manufacturers lacking backward integration into optical supply chains.
- Reprocessing infrastructure sunk costs:Hospital systems with substantial capital deployed in automated endoscope reprocessors face switching friction that slows disposable platform adoption despite regulatory pressure.
- Biomaterial cost volatility:Medical-grade polymers and specialized coatings subject to petrochemical feedstock fluctuations compress margins on single-use instruments where material costs dominate unit economics.
Strategic Opportunities
- Robotic endoscopy integration:Convergence of haptic feedback systems with flexible instrument platforms is opening procedural applications requiring enhanced dexterity and stability beyond human manual control capabilities.
- Semi-disposable hybrid architectures:Modular designs separating reusable control bodies from disposable insertion tubes address both infection control mandates and capital efficiency concerns in budget-constrained hospital systems.
- India outpatient procedural expansion:Underpenetrated gastrointestinal screening infrastructure in tier-2 and tier-3 cities creates whitespace for portable, lower-cost video endoscopy systems as CDSCO streamlines medical device registration pathways.
Industry Challenges
- ISO 13485 quality management implementation:Manufacturers transitioning from reusable to disposable production lines face compressed certification timelines and heightened documentation burdens for design controls and risk management files.
- Legacy IT integration complexity:New visualization systems must interface with hospital PACS and EMR architectures that vary widely across integrated delivery networks, extending deployment cycles and elevating technical support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Market |
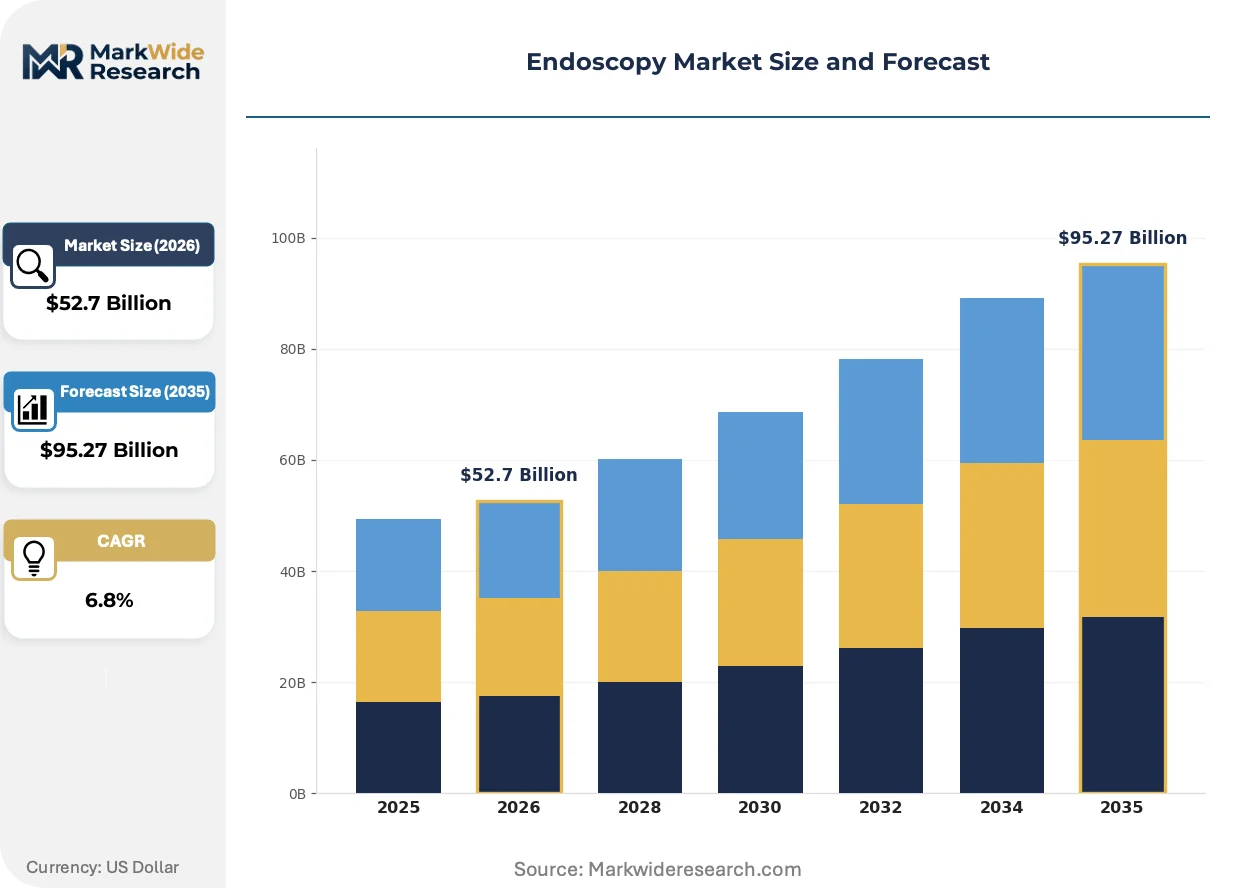
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Single-Use Endoscopes Application: Gastroenterology, Pulmonology, Urology, Gynecology End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Clinics, Research Laboratories Technology: Fiber Optics, Video Endoscopy, Wireless Endoscopy, Robotic Endoscopy |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Stryker Corporation, Boston Scientific Corporation, Medtronic, Fujifilm Holdings Corporation, Ambu A/S, PENTAX Medical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Market Emerging Trajectories
Digital imaging pipelines and regulatory pressure on reprocessing protocols are converging to reshape instrument architecture, procurement evaluation criteria, and the geographic locus of manufacturing investment across the endoscopy value chain.
Disposable endoscope platforms are modularizing around standardized control units and procedure-specific insertion modules. Ambulatory surgical centers in the United States are adopting these systems at accelerating pace to eliminate reprocessing staff and infrastructure overhead. The architecture is compressing the traditional reusable instrument service revenue model while shifting margin capture toward consumable cartridge suppliers.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for reusable endoscope manufacturers seeking CE marking renewal. The regulation is elevating clinical evidence burdens and post-market surveillance obligations that disproportionately affect mid-tier suppliers lacking regulatory affairs scale. European hospital procurement committees are responding by tightening supplier qualification criteria and consolidating vendor panels.
Integrated delivery networks in the United States are consolidating endoscope procurement through centralized supply chain functions that unbundle device acquisition from service contracts. Purchasing committees now evaluate total cost of ownership spanning capital outlay, reprocessing labor, sterilization consumables, and liability exposure rather than per-unit instrument pricing alone. This behavioral shift is most pronounced in multi-hospital systems spanning California, Texas, and Florida where standardization across facilities drives volume aggregation.
Endoscopy Market Segmentation
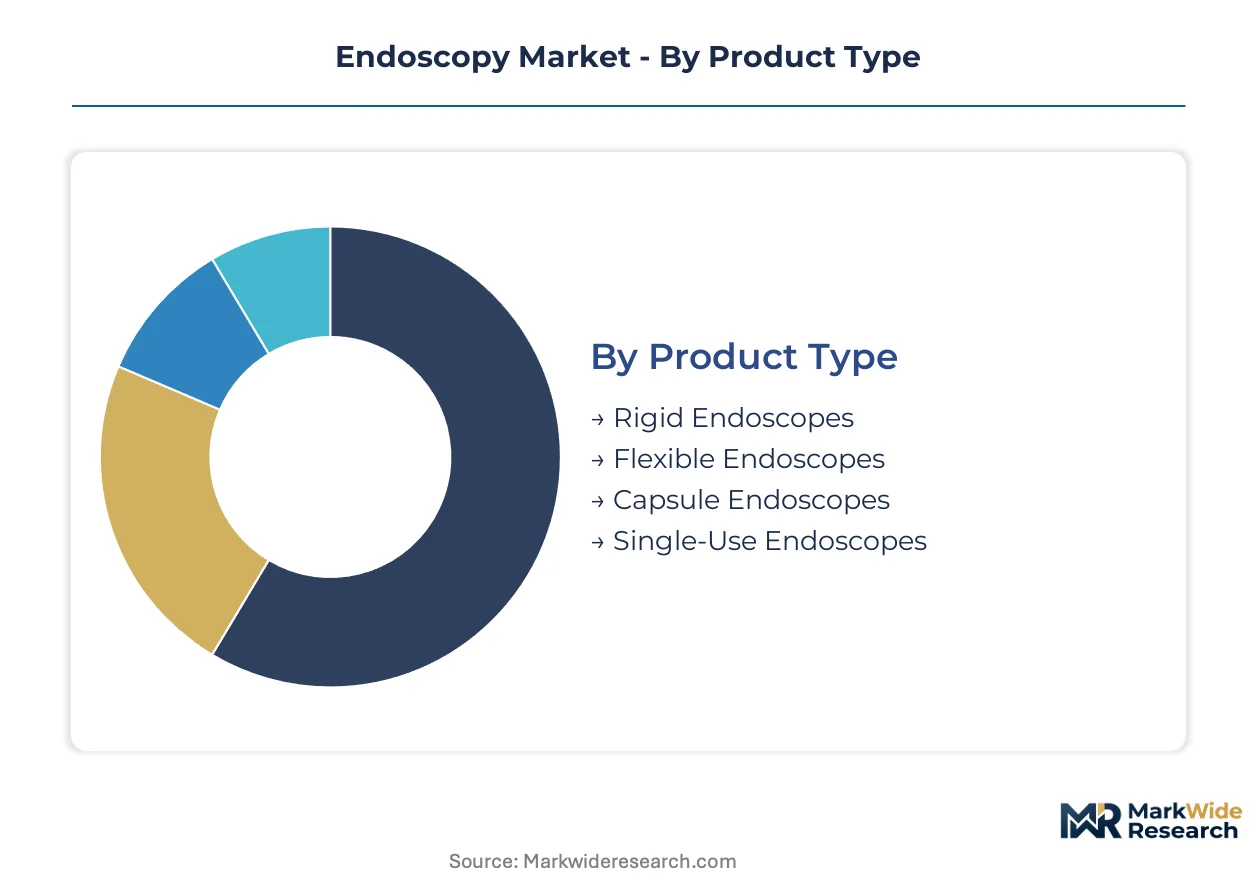
Endoscope procurement decisions hinge on balancing capital intensity against infection control mandates. Segmentation reveals divergent growth trajectories between reusable architectures facing regulatory compression and disposable platforms capturing ambulatory volume.
Product Type:
Flexible endoscopes command the largest installed base while single-use alternatives capture the steepest expansion trajectory as reprocessing liability reshapes hospital economics.
- Flexible Endoscopes:Articulating insertion tubes with steerable distal tips enable navigation through tortuous anatomical pathways in gastroenterology and pulmonology. Demand concentrates in United States hospital systems where procedure volume justifies capital investment despite rising reprocessing compliance costs.
- Single-Use Endoscopes:Polymer-based disposable architectures eliminate cross-contamination risk and bypass FDA reprocessing validation requirements entirely. Ambulatory surgical centers in Texas and Florida are adopting these systems fastest to remove sterilization infrastructure overhead and staff training burdens.
- Rigid Endoscopes:Stainless steel optical systems with fixed straight or angled viewing directions serve arthroscopy, laparoscopy, and ENT applications requiring structural rigidity.
- Capsule Endoscopes:Ingestible wireless imaging pills transmit gastrointestinal imagery during natural transit, addressing small bowel visualization beyond conventional scope reach.
Today's leader: Flexible Endoscopes. Tomorrow's challenger: Single-Use Endoscopes.
Application:
Gastroenterology procedures generate the highest absolute instrument utilization while pulmonology applications face intensifying scrutiny over bronchoscope-related infection clusters.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures drive the bulk of flexible endoscope deployment across screening and therapeutic indications. United States integrated delivery networks centralize procurement of advanced visualization systems for colorectal cancer screening programs.
- Pulmonology:Bronchoscopy for lung cancer staging and interventional procedures has become the focal point for disposable platform adoption following FDA safety communications on reprocessing failures. Academic medical centers in California are piloting single-use bronchoscopes to eliminate duodenoscope-type outbreak risks.
- Urology:Cystoscopy and ureteroscopy procedures employ both rigid and flexible instrument configurations for diagnostic and stone management applications.
- Gynecology:Hysteroscopy and laparoscopy procedures utilize specialized rigid and semi-rigid optical systems for diagnostic and operative interventions.
Gastroenterology sustains current revenue concentration. Pulmonology is gaining share fastest as infection control protocols tighten.
End User:
Hospital systems anchor capital equipment demand while ambulatory surgical centers are shifting procurement toward consumable-heavy disposable platforms.
- Hospitals:Comprehensive medical centers maintain diversified endoscope fleets spanning rigid, flexible, and advanced robotic configurations across multiple service lines. These institutions face sunk-cost friction from existing reprocessing infrastructure even as FDA guidance elevates compliance burdens.
- Ambulatory Surgical Centers:Freestanding outpatient facilities prioritize operational simplicity and liability minimization over per-procedure cost optimization. Centers in Florida and Texas are eliminating reusable bronchoscope programs entirely in favor of disposable alternatives.
- Diagnostic Clinics:Specialized gastrointestinal and pulmonary screening facilities concentrate procedure volume in lower-acuity settings without overnight capacity.
- Research Laboratories:Academic and commercial research settings employ specialized endoscopic platforms for preclinical studies and device development validation.
Hospitals retain procurement volume leadership. Ambulatory Surgical Centers are expanding most quickly as site-of-care migration accelerates.
Technology:
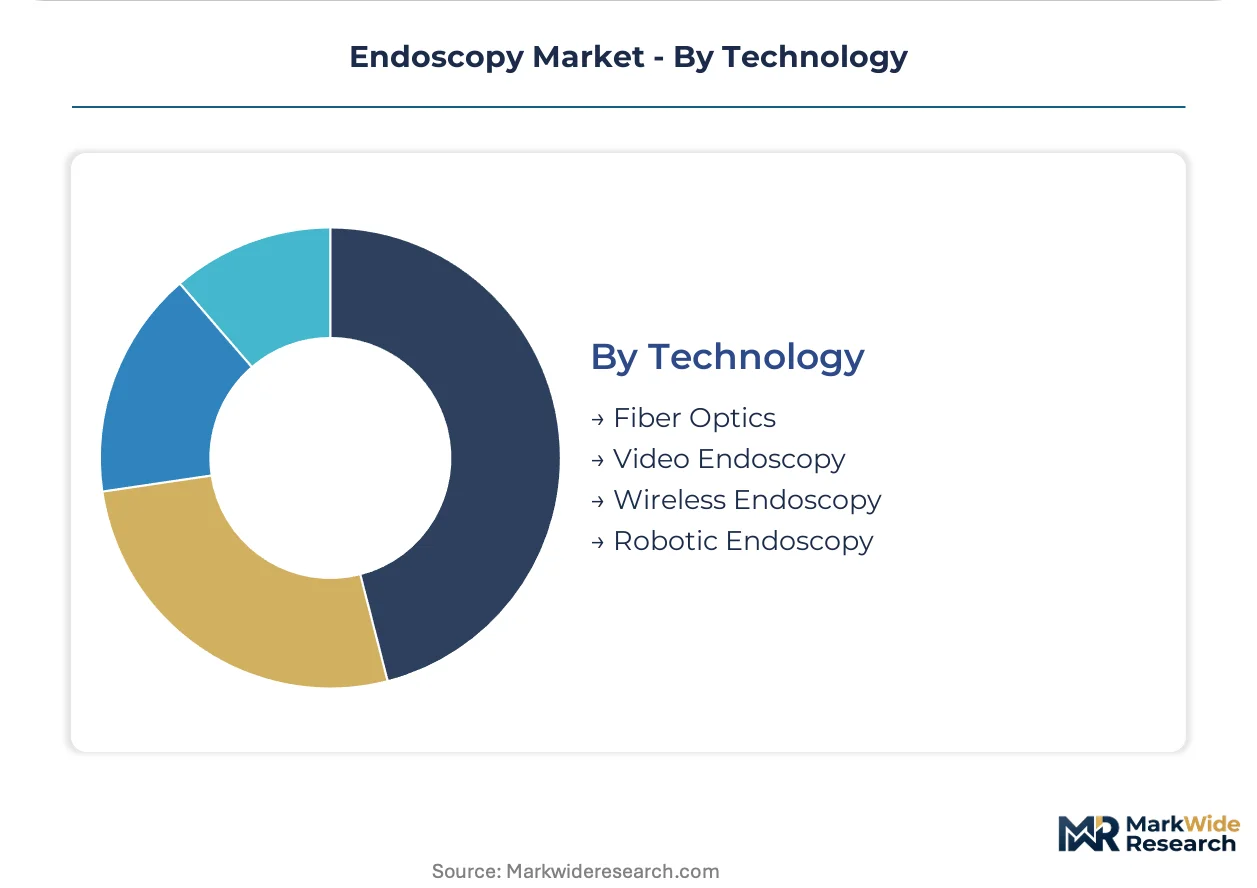
Video endoscopy dominates current deployment while robotic platforms capture development investment for procedures exceeding manual dexterity limits.
- Video Endoscopy:CMOS and CCD sensor-based systems delivering high-definition digital imagery have displaced fiber optic architectures across mainstream applications. United States hospital procurement committees now specify 1080p minimum resolution for new flexible system acquisitions.
- Robotic Endoscopy:Motorized instrument platforms with haptic feedback and stabilized tip control enable procedures requiring submillimeter precision beyond human manual capability. Academic medical centers in California and Massachusetts are piloting these systems for NOTES and complex interventional applications.
- Fiber Optics:Legacy illumination and image transmission through coherent fiber bundles persists in cost-sensitive rigid instrument configurations.
- Wireless Endoscopy:Capsule-based and tetherless platforms transmit imagery without physical insertion tube constraints, addressing anatomical regions inaccessible to conventional scopes.
Video Endoscopy anchors current installed base. Robotic Endoscopy holds the steepest expansion trajectory as procedural complexity demands exceed manual control limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endoscopy technicians and biomedical engineers concentrate in metropolitan medical hubs across Germany, Japan, and the United States, anchoring regional innovation capacity. These talent clusters support precision manufacturing and advanced visualization system development.
United States
Ambulatory surgical centers in Texas and Florida are eliminating reusable bronchoscope programs entirely in favor of disposable alternatives. FDA reprocessing guidance compresses viable lifespans for reusable architectures while accelerating capital reallocation toward single-use platforms. Integrated delivery networks in California centralize procurement through supply chain functions that unbundle device acquisition from service contracts.
Germany
Precision lens and fiber optic suppliers in Baden-Württemberg and Bavaria control critical upstream capacity for optical component manufacturing. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines for reusable endoscope manufacturers seeking CE marking renewal. The Stuttgart and Munich industrial clusters sustain vertically integrated optical supply chains that support both rigid and flexible system production.
Japan
CMOS sensor diffusion from Japanese component manufacturers enables thinner instrument diameters and improved maneuverability. PMDA regulatory frameworks align with international standards while maintaining distinct quality management expectations for device approval. The Tokyo-Osaka corridor hosts concentrated endoscope manufacturing facilities serving domestic and export markets.
India
Underpenetrated gastrointestinal screening infrastructure in tier-2 and tier-3 cities creates whitespace for portable video endoscopy systems. CDSCO streamlines medical device registration pathways while BIS standards govern electrical safety and electromagnetic compatibility. Manufacturing investment concentrates in Maharashtra and Karnataka as domestic production scales to serve South Asian demand.
China
Domestic manufacturers are capturing share in cost-sensitive rigid endoscope segments through localized production and government procurement preferences. NMPA medical device registration requirements are harmonizing with international standards while maintaining distinct clinical evidence expectations. The Yangtze River Delta and Pearl River Delta clusters host assembly operations serving hospital systems undergoing rapid infrastructure expansion.
Endoscopy Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple technology vectors in the endoscopy market. The vendor base spans vertically integrated optical conglomerates, disposable platform innovators, and precision surgical instrument engineers. Three strategic archetypes dominate: optical technology conglomerates with captive component supply, single-use disposable specialists, and precision surgical instrument engineers. Competitive moves concentrate on M&A for technology access and geographic expansion into underpenetrated outpatient markets.
Among optical technology conglomerates, Olympus Corporation and Fujifilm Holdings Corporation exemplify the vertically integrated archetype with in-house production of imaging sensors and optical components. Karl Storz SE & Co. KG anchors the precision-engineered surgical instrument tier through its German GmbH structure. Boston Scientific Corporation and Ambu A/S occupy positions within the single-use disposable segment, representing the shift toward platforms that eliminate reprocessing liability entirely.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic |
| Fujifilm Holdings Corporation |
| Ambu A/S |
| PENTAX Medical |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Medical-grade polymer price indices cascade through endoscope manufacturing tiers, compressing margins on single-use platforms while amplifying price premiums for German and Japanese optical components in reusable systems. Procurement committees at United States integrated delivery networks now unbundle device acquisition from reprocessing service contracts, forcing suppliers to price transparently across capital and consumable line items.
Pricing Analysis
The bundled-versus-unbundled service split separates legacy reusable endoscope vendors from disposable platform specialists. Premium-mid-economy pricing differentiation tracks ISO 13485 certification tiers and FDA 510(k) clearance pathways, with academic medical centers absorbing brand premiums while ambulatory surgical centers prioritize per-procedure cost minimization. Price erosion runs through mid-tier flexible endoscopes as CMOS sensor commoditization erodes optical component scarcity rents. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, whereas California academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Precision lens and CMOS sensor supply rests on Japanese component manufacturers and German optical engineering clusters in Baden-Württemberg and Bavaria. Medical-grade polycarbonate and specialized illumination fibers draw from petrochemical feedstock networks in the United States, Germany, and Japan. Single-source vulnerability concentrates in coherent fiber bundle production, where two Stuttgart-area suppliers control critical capacity. Distribution runs through hospital GPO contracts and ambulatory surgical center direct purchasing channels, with integrated delivery networks consolidating volume aggregation functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in endoscopy hinges on disposable platform adoption accelerating faster than polymer cost inflation, with premium-tier visualization systems capturing pricing power from CMOS sensor performance differentiation.
For Market Incumbents: Cement optical component captive supply through backward integration into Japanese CMOS sensor partnerships or German precision lens acquisitions. Expand automated reprocessing validation service revenue to defend installed base against disposable platform displacement at United States hospital systems with sunk capital in AER infrastructure. For New Entrants and Emerging Players: Capture whitespace in India tier-2 and tier-3 city outpatient clinics with portable video endoscopy systems priced below CDSCO-registered import alternatives. Target pulmonology disposable bronchoscope demand at California academic medical centers piloting single-use protocols to eliminate duodenoscope-type outbreak liability. For Investors and Strategic Acquirers: Asymmetric upside sits with semi-disposable hybrid architecture developers bridging infection control mandates and capital efficiency demands. Long-term viability favors modular platform innovators separating reusable control bodies from disposable insertion tubes. Watch FDA reprocessing guidance expansion beyond duodenoscopes to flexible colonoscopes as inflection indicator for disposable adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking renewal timelines extend competitive moats for regulatory affairs-scaled incumbents against mid-tier challengers. |
| Semi-Disposable Hybrid Platform Development | Modular architectures address both FDA infection control mandates and hospital capital constraints across integrated delivery networks. |
| CMOS Sensor Backward Integration | In-house imaging component production secures margin control and instrument miniaturization roadmaps against Japanese supplier concentration. |
| Ambulatory Surgical Center Direct Contracts | Bypassing GPO intermediaries captures disposable volume growth in Texas and Florida outpatient facilities. |
| Robotic Endoscopy Regulatory Pathway | FDA de novo and breakthrough device designations accelerate commercialization timelines for haptic-enabled flexible platforms. |
Methodological Framework
Bottom-up ambulatory surgical center and hospital system modeling reconciled against top-down optical component production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineering directors, and ambulatory center administrators combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare procedure databases, and hospital procurement platform records. Triangulation across supply-side manufacturing capacity and demand-side procedural volume estimates anchors forecast integrity.
Historical trendline analysis of flexible endoscope shipments, single-use adoption curves, and CMOS sensor diffusion patterns informed projection framework construction across the analysis window. Segmentation dimensions span product architecture, application specialty, end-user facility type, and technology platform, with procedural volume intensity and regulatory compliance burden as industry-specific forecast inputs. CAGRs derive from installed base turnover rates and ambulatory site-of-care migration velocity rather than extrapolated linear trends.
EU MDR implementation delays, FDA reprocessing guidance scope expansion, and polymer feedstock price volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding disposable platform cost parity achievement and hospital capital budget allocation priorities. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Bronchoscopy Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Global Colonoscopes Market