
 Body Contouring Devices and Procedures Market | 2026-2036
Body Contouring Devices and Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Body Contouring Devices and Procedures Market Analysis
CE marking under the EU Medical Device Regulation is recalibrating the cost-of-entry calculus for body contouring platforms seeking European market access. Cynosure leverages its established notified body relationships to sustain faster certification cycles across multiple device modalities. Alma Lasers anchors its competitive position through geographic dominance in Middle Eastern and Asian aesthetic markets. InMode differentiates by specializing in radiofrequency-based minimally invasive technologies that occupy a distinct clinical positioning between non-invasive and surgical alternatives.
Body contouring devices and procedures encompass technologies that selectively reduce adipose tissue, tighten skin, or reshape anatomical contours through thermal, cryogenic, acoustic, or mechanical energy delivery, typically operating at wavelengths between 600 nm and 10,600 nm or temperatures between minus 11°C and 65°C depending on modality. These systems serve commercial purposes across cosmetic dermatology, plastic surgery, and wellness sectors where patient outcomes depend on precise energy dosing and tissue selectivity. Non-surgical procedure types now lead volume as clinics prioritize zero-downtime offerings that protect appointment throughput, while cryolipolysis device types command margin pools due to consumable attachment cycles and premium pricing structures. Medical spas represent the fastest-growing end user channel as they expand supervised aesthetic services beyond traditional dermatology and plastic surgery settings.
FDA 510(k) clearance requirements and the EU MDR clinical evaluation framework shape product development roadmaps, reimbursement positioning, and international market sequencing for device manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain design choices and manufacturing site qualifications. Brazil's national health surveillance agency and comparable regulators in Mexico and South Korea impose additional testing protocols that filter market participants by capital depth and regulatory expertise. Stakeholders must monitor evolving classification boundaries between wellness and medical claims as enforcement actions redefine permissible marketing language across direct-to-consumer channels.
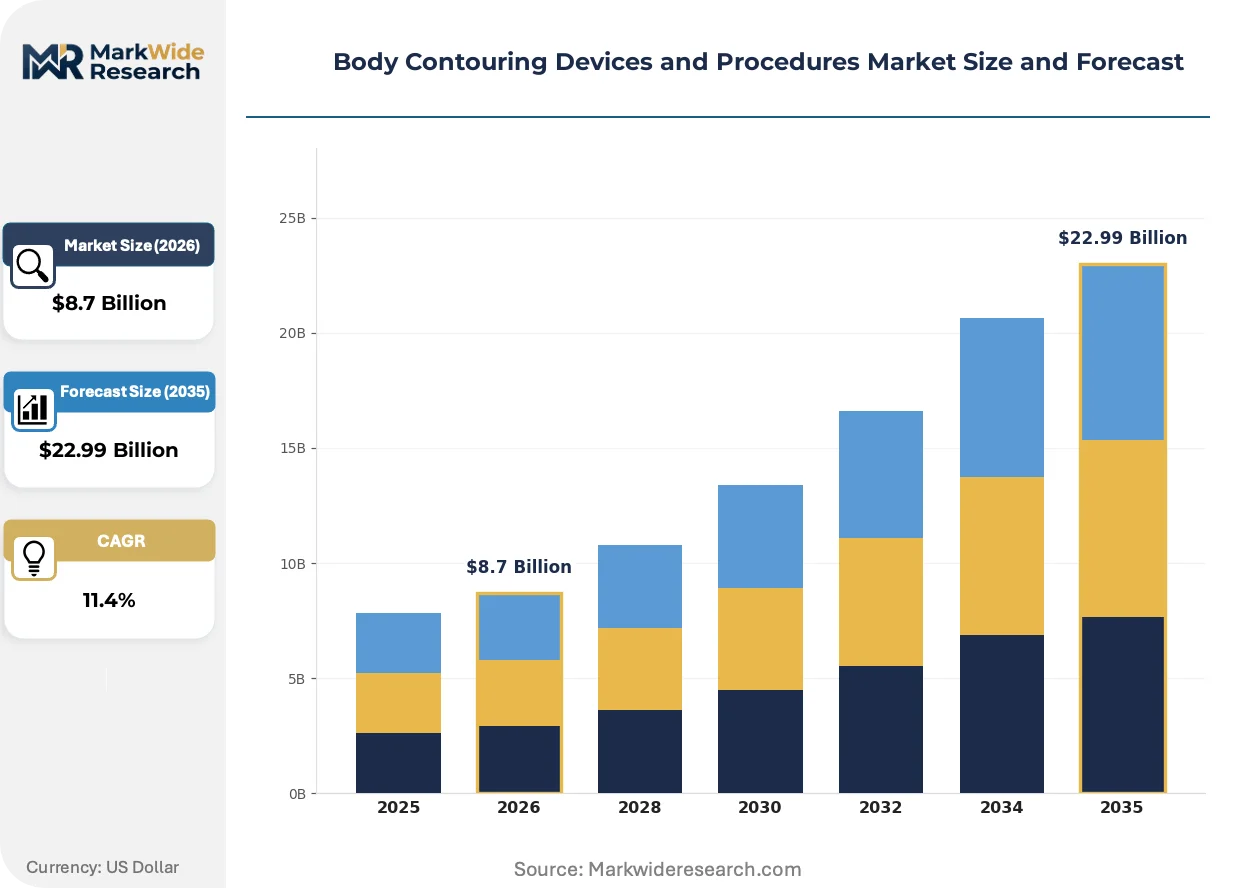
Market Dynamics
Medical spas across the United States are compressing the competitive cycle by expanding supervised aesthetic services beyond traditional dermatology and plastic surgery settings, forcing device manufacturers to recalibrate distribution strategies and training protocols.
Growth Catalysts
- FDA 510(k) clearance compression:Streamlined pathways for radiofrequency and cryolipolysis platforms are accelerating product development timelines for manufacturers targeting rapid commercialization.
- Brazil medical tourism infrastructure:Premium device placement concentrates where aesthetic procedure volume and international patient flows create sustained utilization rates.
- Zero-downtime procedure preference:Patient demand for same-day return to normal activities drives clinic investment in non-surgical modality portfolios.
Market Restraints
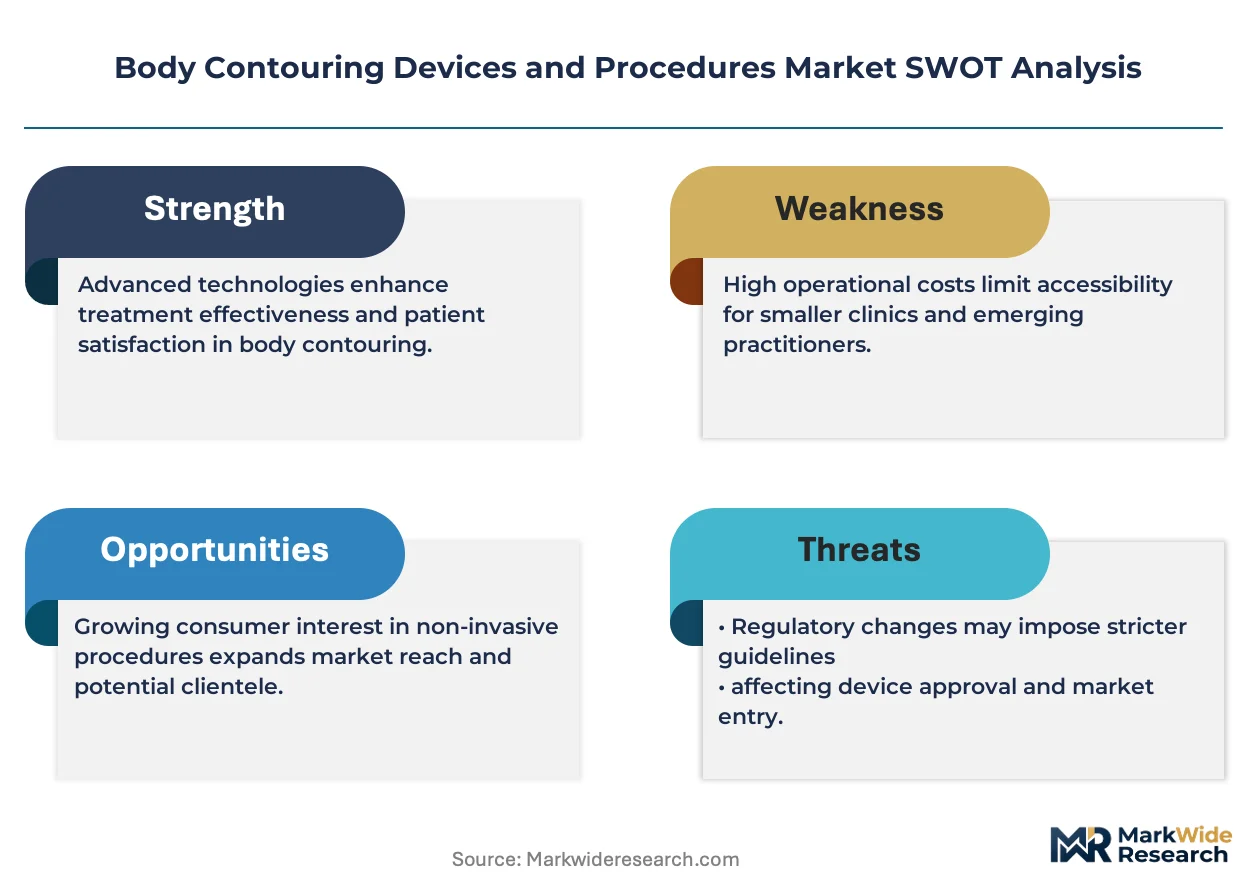
- EU MDR clinical evaluation costs:CE marking recalibration under the Medical Device Regulation elevates capital requirements for European market entry.
- Consumable attachment dependency:Cryolipolysis margin pools rely on proprietary applicator cycles that lock clinics into single-manufacturer supply relationships.
- Temperature and wavelength precision requirements:Operating parameters between minus 11°C and 65°C or 600 nm to 10,600 nm demand specialized engineering talent and quality control infrastructure.
Strategic Opportunities
- Middle Eastern aesthetic market expansion:Geographic dominance in high-margin wellness tourism corridors supports premium pricing for radiofrequency platforms.
- Radiofrequency-ultrasound convergence:Hybrid energy delivery systems occupy clinical positioning between non-invasive and surgical alternatives.
- South Korea testing protocol alignment:MFDS regulatory frameworks filter competitors by capital depth while rewarding early compliance investment.
Industry Challenges
- Notified body relationship scarcity:Established certification partnerships concentrate among incumbent manufacturers, extending timeline risk for new entrants.
- Marketing language enforcement actions:Evolving classification boundaries between wellness and medical claims require continuous legal monitoring across direct-to-consumer channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Contouring Devices and Procedures Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser, Cryolipolysis, Radiofrequency, Ultrasound Procedure Type: Non-Surgical, Surgical, Minimally Invasive, Liposuction Target Area: Abdomen, Thighs, Arms, Buttocks End User: Clinics, Medical Spas, Hospitals, Home Users |
| Companies Covered | Cynosure, Alma Lasers, AbbVie, Cutera, Bausch Health Companies, InMode, Candela Medical, Lumenis, Merz Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Contouring Devices and Procedures Market Emerging Trajectories
Device manufacturers are embedding intelligence into energy delivery systems while regulatory frameworks tighten clinical evidence requirements and procurement patterns fragment across institutional and retail channels.
Radiofrequency-based tissue tightening technology is automating real-time impedance monitoring to adjust power delivery during procedures. Medical spas in the United States are adopting these platforms at accelerated rates to protect appointment throughput. This capability is automating the standardization of treatment outcomes previously dependent on operator experience, compressing training requirements and reducing variability liability.
EU MDR clinical evaluation frameworks are mandating expanded post-market surveillance for body contouring platforms. Manufacturers must now maintain systematic clinical data collection across all member states where devices are deployed. Class IIa and IIb device categories face the steepest compliance burden, driving consolidation among smaller notified body clients toward established regulatory consultancies.
After-sales service unbundling is separating hardware ownership from maintenance contracts and software update subscriptions. Independent medical spa chains in Brazil are negotiating à la carte service tiers rather than comprehensive manufacturer agreements. This pattern concentrates in São Paulo and Rio de Janeiro metropolitan markets where multi-site operators command sufficient volume to dictate procurement terms.
Body Contouring Devices and Procedures Market Segmentation
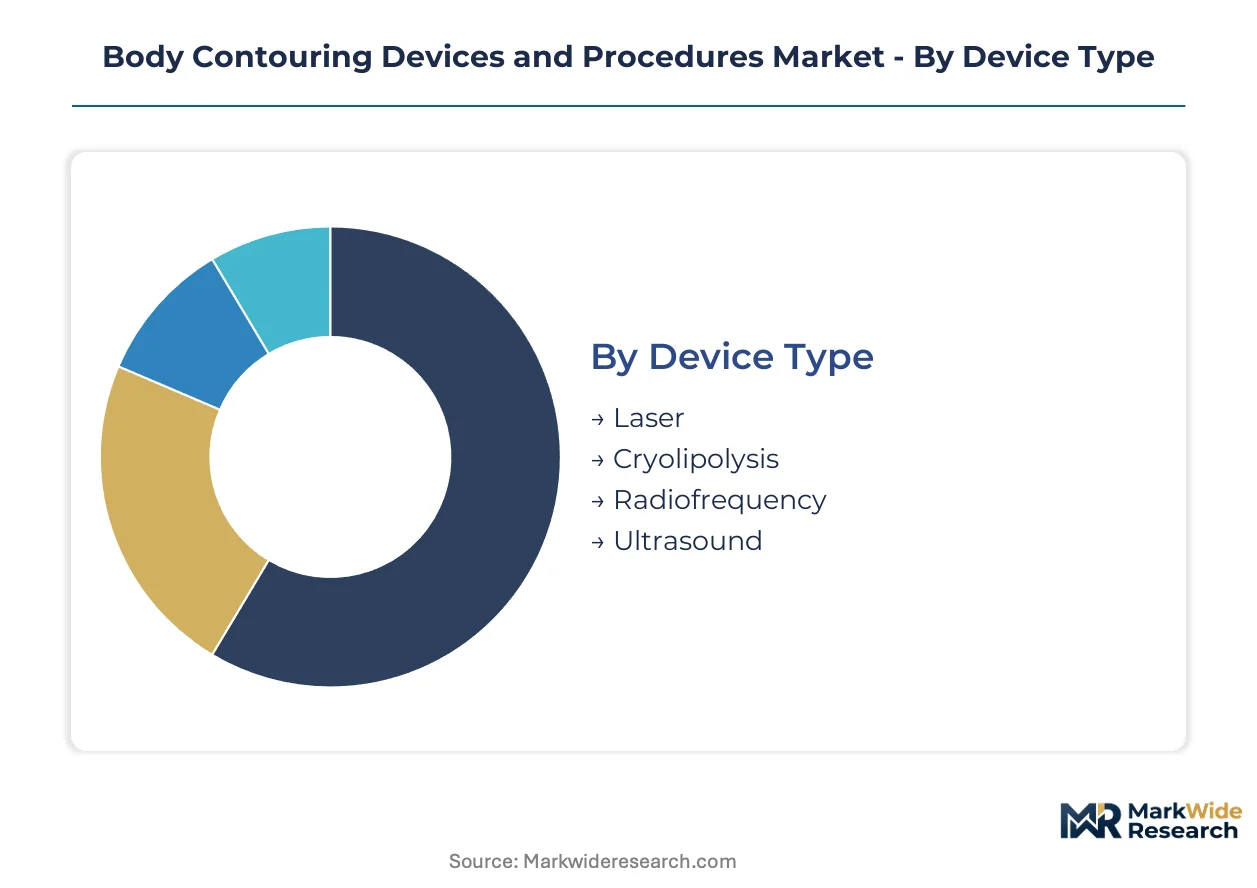
Body contouring markets fragment across energy modalities, clinical settings, and anatomical applications. Certification requirements diverge sharply between surgical and non-surgical segments, reshaping manufacturer investment priorities and geographic sequencing strategies.
Device Type:
FDA 510(k) pathways compress timelines for radiofrequency and cryolipolysis platforms, while laser systems face additional IEC 60601-2-22 ophthalmic safety testing that extends European notified body review cycles.
- Radiofrequency:Delivers thermal energy at 1-40 MHz to induce collagen contraction and adipocyte apoptosis through controlled impedance monitoring. Medical spas in the United States concentrate procurement here as zero-downtime protocols protect appointment throughput. Real-time feedback systems are automating operator-dependent variability.
- Cryolipolysis:Applies controlled cooling at minus 11°C to selectively crystallize subcutaneous fat without epidermal damage. Brazil's medical tourism corridors sustain premium device placement where international patient flows guarantee utilization rates. Proprietary applicator cycles lock clinics into single-manufacturer consumable dependencies.
- Laser:Operates across 600 nm to 10,600 nm wavelengths for photothermolysis of adipose tissue or skin tightening.
- Ultrasound:Deploys focused acoustic energy for mechanical fat disruption at depths up to 5 cm.
Leading the category by volume: Radiofrequency. Growing fastest: Cryolipolysis.
Procedure Type:
Cost stratification separates premium surgical suites from high-throughput retail channels, with minimally invasive modalities capturing margin pools between these tiers.
- Non-Surgical:Encompasses all energy-based treatments requiring no incision or anesthesia. Medical spas across the United States are expanding these services beyond traditional dermatology settings to capture consumer preference shifts.
- Minimally Invasive:Combines micro-incision access with energy delivery for localized fat reduction and skin contraction. This segment occupies distinct clinical positioning between non-invasive and surgical alternatives, commanding premium pricing in Middle Eastern wellness tourism corridors.
- Surgical:Requires operating room infrastructure and general anesthesia for comprehensive tissue resection.
- Liposuction:Remains the reference standard for volume fat removal despite recovery time penalties.
Expanding most quickly: Minimally Invasive. Dominating by procedure volume: Non-Surgical.
Target Area:
Anatomical application drives device specification requirements, with abdomen protocols demanding larger treatment zones and buttocks procedures requiring specialized contouring applicators.
- Abdomen:Represents the highest absolute procedure volume across all modalities, with cryolipolysis platforms configuring multi-applicator arrays for comprehensive coverage.
- Thighs:Requires bilateral treatment symmetry protocols that extend session duration and consumable utilization.
- Arms:Demands precision energy delivery to avoid nerve proximity complications in the brachial region.
- Buttocks:Concentrates demand in Brazil where aesthetic procedure volume and cultural emphasis on gluteal contouring support specialized device configurations.
Commanding highest procedure volume: Abdomen. Gaining share fastest: Buttocks.
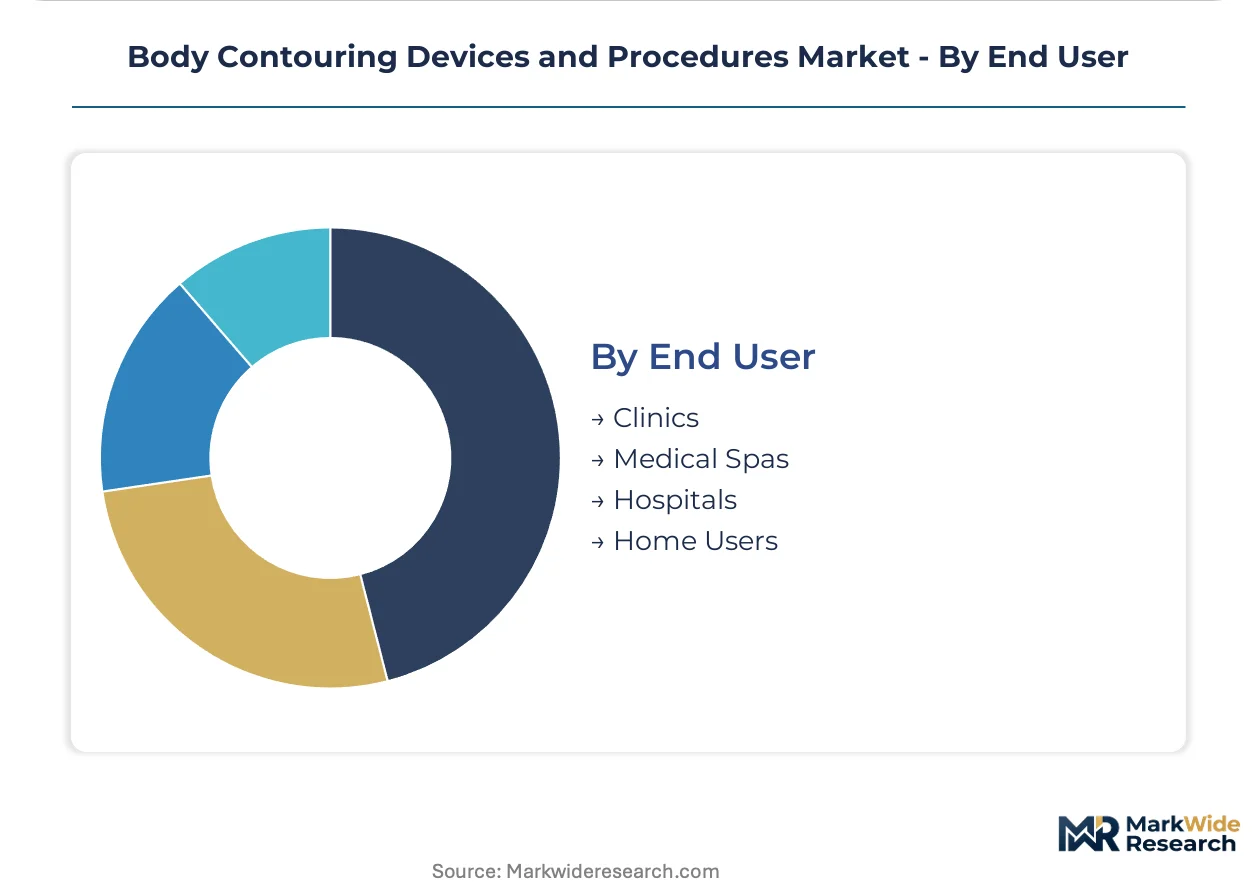
End User:
Customer type determines procurement pattern, training infrastructure, and regulatory exposure across institutional and retail channels.
- Medical Spas:Supervised aesthetic services operating beyond traditional dermatology and plastic surgery settings. These channels are compressing competitive cycles by expanding non-surgical menus and negotiating à la carte service tiers rather than comprehensive manufacturer agreements.
- Clinics:Dermatology and plastic surgery practices maintaining surgical and non-surgical portfolios under physician supervision.
- Hospitals:Require operating room integration and anesthesia support for surgical and minimally invasive modalities.
- Home Users:Consumer-grade devices operating at reduced power parameters with Class I or wellness regulatory classification.
Steepest expansion trajectory: Medical Spas. Maintaining highest average revenue per device: Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Dubai and São Paulo are accelerating device distribution hub concentration for aesthetic technology manufacturers seeking tax-advantaged logistics platforms.
United States
Medical spa chains in Florida and California are driving cryolipolysis device procurement volumes as supervised aesthetic services expand beyond traditional dermatology settings. FDA 510(k) clearance pathways for radiofrequency platforms compress product development timelines for domestic manufacturers. The Miami-Dade and Orange County corridors concentrate multi-site operators negotiating à la carte service tiers with device suppliers.
Brazil
Medical tourism infrastructure in São Paulo and Rio de Janeiro sustains premium device placement where international patient flows guarantee utilization rates for body contouring platforms. ANVISA testing protocols filter market participants by capital depth and regulatory expertise. The Jardins and Ipanema clinic clusters command specialized gluteal contouring applicator configurations reflecting cultural aesthetic preferences.
Germany
Precision engineering capabilities in Baden-Württemberg and Bavaria support quality control infrastructure for temperature and wavelength precision requirements. CE marking recalibration under EU MDR elevates capital requirements for European market entry, favoring established notified body relationships. The Stuttgart and Munich medical device manufacturing zones concentrate IEC 60601 electrical safety specification expertise.
South Korea
MFDS regulatory frameworks filter competitors by capital depth while rewarding early compliance investment in body contouring device categories. Seoul Capital Area aesthetic clinics are adopting hybrid radiofrequency-ultrasound platforms at accelerated rates. The Gangnam and Seocho medical districts anchor demand for minimally invasive modalities occupying clinical positioning between non-invasive and surgical alternatives.
United Arab Emirates
Wellness tourism corridors in Dubai and Abu Dhabi support premium pricing for radiofrequency platforms serving high-margin aesthetic service demand. MOHAP registration requirements impose additional testing protocols that concentrate procurement among capital-deep manufacturers. The Dubai Healthcare City and Abu Dhabi Corniche clinic clusters are expanding supervised aesthetic services beyond traditional plastic surgery settings.
Body Contouring Devices and Procedures Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across body contouring device categories, producing a tiered market structure where regulatory expertise and notified body relationships determine competitive positioning. The vendor base concentrates among manufacturers maintaining ISO 13485 quality management standards and multi-jurisdiction certification capabilities. Three strategic archetypes dominate: diversified medical technology conglomerates with broad aesthetic portfolios, laser and energy-based device pure-plays with specialized modality depth, and emerging Asian manufacturers leveraging cost-advantaged production. Competitive moves center on M&A activity for regulatory asset acquisition and geographic expansion into medical tourism corridors.
Within the pure-play specialist tier, Cynosure and Alma Lasers exemplify manufacturers leveraging established notified body relationships to sustain faster certification cycles across multiple device modalities. InMode occupies a distinct positioning among radiofrequency-focused specialists, anchoring the minimally invasive modality segment where clinical positioning between non-invasive and surgical alternatives commands premium pricing. These three companies represent the archetype of regulatory expertise as competitive moat in a market where CE marking and FDA clearance timelines determine commercial sequencing.
| Leading Market Players |
|---|
| Cynosure |
| Alma Lasers |
| AbbVie |
| Cutera |
| Bausch Health Companies |
| InMode |
| Candela Medical |
| Lumenis |
| Merz Pharma |
| Others |
Supply Flow & Price Mechanics
Captive after-sales service networks anchor pricing power for cryolipolysis device manufacturers, locking clinics into proprietary consumable cycles that sustain margin pools across Brazil and United States medical spa chains. This backward integration into maintenance contracts and software subscriptions concentrates procurement leverage among multi-site operators in São Paulo and Miami-Dade corridors.
Pricing Analysis
Short lead times for FDA 510(k) cleared radiofrequency platforms command premium positioning against extended-cycle laser systems facing IEC 60601-2-22 ophthalmic safety testing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in consumable-dependent cryolipolysis tiers is intensifying as independent Brazilian chains negotiate à la carte service tiers. Medical spa chains exhibit highest price sensitivity; hospital systems maintain lowest sensitivity due to capital budget insulation.
Supply Chain Analysis
Dual-sourcing requirements for precision temperature control components mandate multi-supplier qualification across German and South Korean engineering hubs. Device assembly draws from semiconductor substrates in Taiwan, precision optics in Germany, and RF generator components in South Korea. Single-source vulnerability concentrates in cryolipolysis compressor modules sourced from specialized Japanese manufacturers. Distribution runs through Dubai and São Paulo free trade zones serving medical tourism corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evaluation cost escalation is forcing consolidation among notified body-dependent manufacturers, eliminating capital-constrained competitors from European market sequencing.
For Market Incumbents: Deploy regulatory asset accumulation to accelerate CE marking cycles ahead of MDR enforcement tightening. Acquire smaller notified body clients to consolidate certification pipeline capacity against emerging Asian cost competitors. Channel control through exclusive training academy networks protects appointment throughput in United States medical spa expansion zones. For New Entrants and Emerging Players: Capture South Korean MFDS compliance as a beachhead for Asian market legitimacy before scaling to Middle Eastern wellness tourism corridors. Target hybrid radiofrequency-ultrasound modalities where clinical positioning between non-invasive and surgical alternatives remains underdeveloped. Pursue direct hospital system partnerships bypassing distributor margin stacking. For Investors and Strategic Acquirers: Exit pathways concentrate in regulatory consultancy acquisitions by device manufacturers seeking notified body relationship depth. Long-term viability favors platforms with multi-jurisdiction certification capabilities and software subscription revenue anchoring. Watch ANVISA enforcement intensity in Brazil as inflection indicator for medical tourism corridor profitability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recalibration elevates capital barriers for European market entry. |
| Hospital System Partnership | Direct procurement relationships bypass medical spa distributor margin compression. |
| Software Companion Development | Real-time impedance monitoring automates operator-dependent outcome variability. |
| Reimbursement Strategy | Coding alignment with minimally invasive procedures unlocks payor channel access. |
| FDA Submission | 510(k) clearance compression accelerates commercialization timelines for RF platforms. |
Methodological Framework
FDA 510(k) filings, EU MDR notified body registers, and ANVISA device approval databases formed the secondary backbone for regulatory pathway mapping. Primary interviews with biomedical engineers, medical spa operations directors, GPO contracts managers, and plastic surgery clinic procurement leads combined with secondary validation across customs records and hospital procurement databases. Bottom-up device shipment modeling and top-down procedure volume estimation provided cross-verification.
Historical trendline analysis of aesthetic procedure volumes and device placement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include energy modality, procedure invasiveness tier, anatomical application zone, and end-user channel type. CAGRs derived from polynomial curve fitting against regulatory approval velocity and medical tourism infrastructure development. Forecast inputs incorporated MFDS compliance timelines and Dubai Healthcare City expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement intensity and Brazil medical tourism policy shifts. Deviation in notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Clear Aligners Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Spirometers Market
Medical Devices
BFS Syringes Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Organoids Kits Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Orthodontic Headgear Market