
 Mexico Endoscopy Devices Market | 2026-2036
Mexico Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Endoscopy Devices Market Foresight
Modular endoscopy system bundling is consolidating purchasing decisions across Mexican hospital networks. Olympus Corporation leverages its service infrastructure to anchor long-term maintenance contracts with public sector buyers. Boston Scientific Corporation competes through specialized interventional endoscopy portfolios targeting gastroenterology departments in major metropolitan hospitals. Karl Storz SE & Co. KG differentiates via rigid endoscope precision manufacturing that sustains premium positioning among surgical centers.
Mexico endoscopy devices comprise instrument systems designed for minimally invasive internal visualization, typically incorporating fiber-optic or digital image sensors with working channels ranging from 1.2mm to 6.0mm diameter for therapeutic intervention. These systems serve diagnostic and surgical applications across gastrointestinal, pulmonary, and urological procedures where direct tissue access reduces patient recovery time. Flexible endoscopes occupy the dominant revenue position due to their versatility across multiple anatomical pathways and established reimbursement pathways. Capsule endoscopy represents the fastest-expanding technology segment as ambulatory screening protocols expand beyond traditional colonoscopy workflows. Visualization systems command concentrated margin pools because proprietary image processing software locks hospitals into recurring upgrade cycles.
COFEPRIS maintains medical device registration requirements that shape import timelines and quality certification obligations for foreign manufacturers entering Mexico. NOM standards for electrical safety and biocompatibility further constrain product configurations available to Mexican healthcare providers. Stakeholders must monitor how procurement centralization through INSABI and state health secretariats alters vendor qualification criteria and tender participation rules.
Market Dynamics
Public hospital procurement centralization through INSABI is compressing vendor negotiation timelines and favoring suppliers with established Mexican service infrastructure over import-only distributors.
Growth Catalysts
- COFEPRIS Registration Streamlining:The regulator's 2024 digital submission portal for Class II medical devices has cut approval timelines for endoscopy visualization systems, accelerating foreign manufacturer market entry.
- Tertiary Care Network Modernization:State health secretariats in Jalisco and Nuevo León are replacing aging fiber-optic scopes with digital platforms, driving replacement demand in Guadalajara and Monterrey metropolitan clusters.
- Ambulatory Surgery Center Expansion:Mexico's private healthcare chains are building same-day endoscopy facilities in Mexico City suburbs, creating pull for portable capsule endoscopy systems.
Market Restraints
- Import Duty Structure:NOM compliance testing and 15-20% tariffs on finished endoscopy systems inflate landed costs for Japanese and German manufacturers.
- Single-Source Visualization Dependency:Proprietary image processing software from dominant platform vendors locks hospitals into captive upgrade cycles, limiting price competition.
- Biocompatibility Certification Bottleneck:COFEPRIS requires Mexico-specific sterilization validation studies that add 8-12 months to product registration for reusable instrument channels.
Strategic Opportunities
- Monterrey Industrial Corridor:The northern manufacturing hub's emerging medical device assembly sector offers tariff-advantaged production for re-export to Central American markets.
- AI-Assisted Polyp Detection:Integration of real-time computer vision algorithms with existing colonoscopy platforms represents uncontracted white space in Mexican gastroenterology departments.
- Telemedicine-Enabled Remote Interpretation:Capsule endoscopy data transmission to radiology networks in Mexico City creates service revenue models for equipment vendors.
Industry Challenges
- Gastroenterologist Training Pipeline:Mexico produces fewer than 80 new endoscopy specialists annually, constraining procedure volume growth regardless of equipment availability.
- Legacy System Integration:Public hospitals operate mixed fleets of 1990s-era fiber-optic and modern digital scopes, complicating sterilization workflow standardization and maintenance contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Endoscopy Devices Market |
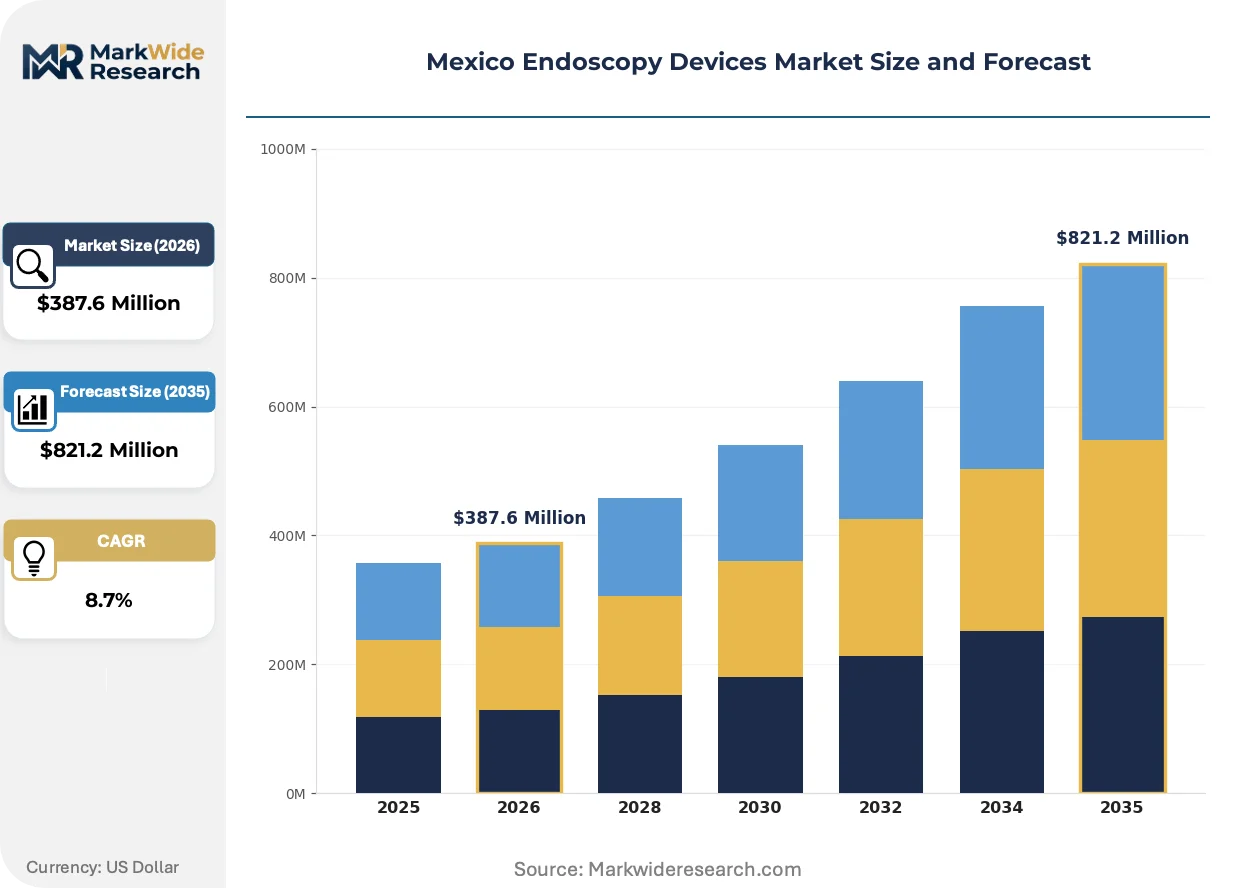
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Accessories, Visualization Systems End User: Hospitals, Clinics, Surgical Centers, Diagnostic Laboratories Technology: Video Endoscopy, Ultrasonic Endoscopy, Capsule Endoscopy, Robotic Endoscopy Application: Gastroenterology, Pulmonology, Urology, Gynecology |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Fujifilm Holdings, Karl Storz SE & Co. KG, Stryker Corporation, Medtronic, Johnson & Johnson, Conmed Corporation, Richard Wolf, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Endoscopy Devices Market Shifts & Advancements
Digital image sensor technology is displacing fiber-optic transmission in Mexican hospital procurement specifications, while regulatory data requirements and buyer consolidation are reshaping competitive positioning.
Single-use endoscope technology is consolidating market share in infection-sensitive procedures across Mexican private hospital chains. Hospital epidemiologists in Mexico City tertiary centers are specifying disposable bronchoscopes for immunocompromised patient populations. This shift is consolidating procurement decisions toward vendors with sterile manufacturing partnerships rather than traditional reprocessing service providers.
COFEPRIS implemented updated biocompatibility testing requirements for reusable endoscope channels in 2024, mandating ISO 10993-5 cytotoxicity documentation for all new registrations. Foreign manufacturers must now submit Mexico-specific sterilization validation data, extending registration timelines. Gastroenterology equipment distributors are responding by pre-positioning regulatory dossiers ahead of tender cycles.
Hospital network procurement committees are unbundling maintenance contracts from initial equipment purchases in Mexico City, Monterrey, and Guadalajara. Third-party service providers with ISO 13485-certified repair facilities are capturing post-warranty visualization system contracts. This restructuring is most visible in ISSSTE and IMSS hospital networks, where multi-year total cost of ownership models now dominate capital allocation decisions.
Mexico Endoscopy Devices Market Segmentation
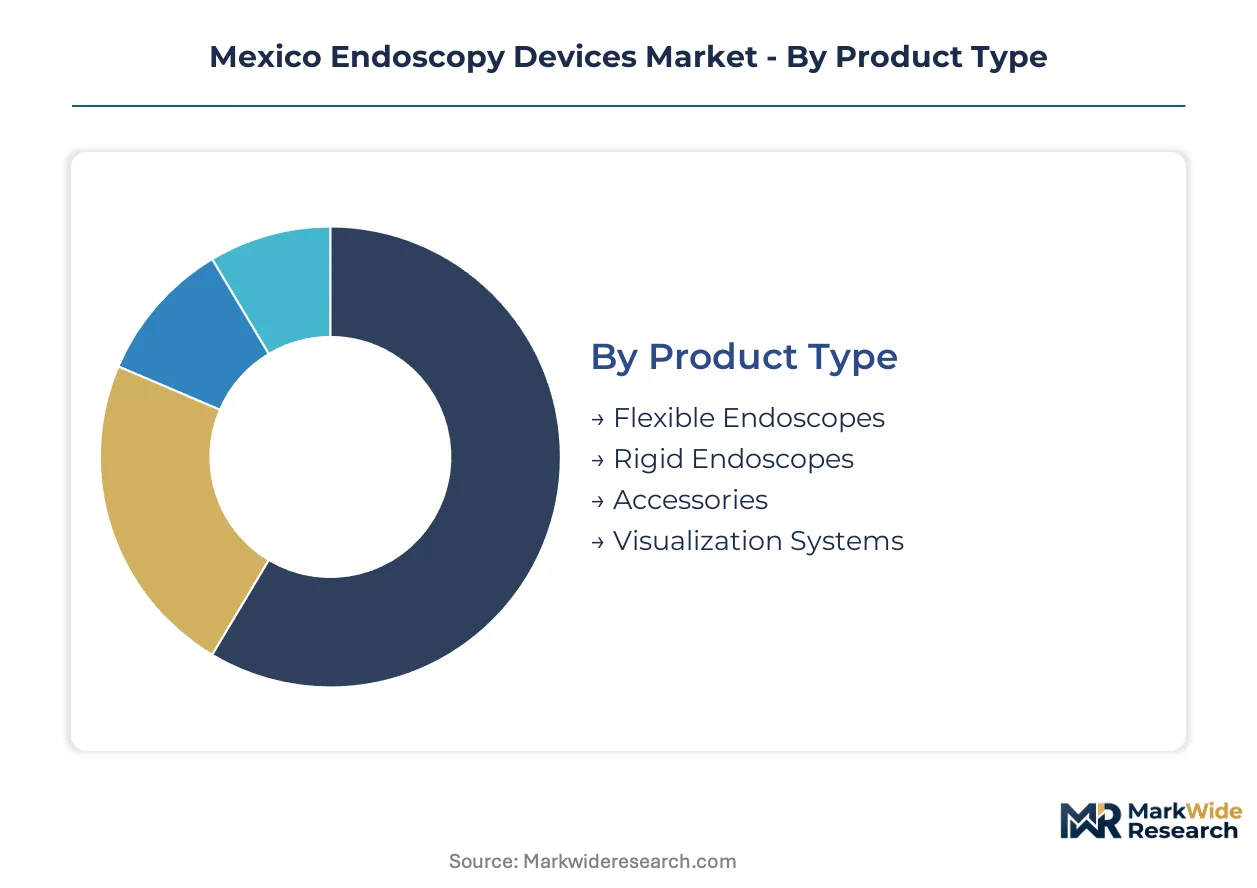
Hospital procurement committees in Mexico City, Monterrey, and Guadalajara evaluate endoscopy investments through multi-dimensional segmentation frameworks. Replacement cycles for aging fiber-optic fleets create divergent demand patterns across product configurations and clinical settings.
Product Type:
Upgrade momentum from analog to digital platforms is reshaping capital allocation across Mexican hospital networks.
- Flexible Endoscopes:Fiber-optic or digital systems with articulating distal tips navigate tortuous anatomical pathways through natural orifices. Demand clusters in IMSS tertiary centers across Mexico City where gastroenterology procedure volumes justify multi-scope purchases. COFEPRIS registration timelines for reusable instrument channels constrain vendor selection.
- Visualization Systems:Proprietary image processors and LED light sources deliver high-definition output to surgical displays. Procurement centralization through INSABI favors suppliers with Mexican-based technical service teams capable of same-day response. Software licensing locks hospitals into recurring upgrade commitments.
- Rigid Endoscopes:Stainless steel laparoscopic and arthroscopic instruments with rod-lens optical chains.
- Accessories:Biopsy forceps, irrigation pumps, and insufflation units with disposable or reusable configurations.
Volume placements concentrate in Flexible Endoscopes; the faster expansion belongs to Visualization Systems.
End User:
Facility reimbursement tiers determine equipment sophistication levels across Mexico's mixed public-private landscape.
- Hospitals:Tertiary care institutions with 24-hour surgical capabilities and dedicated sterilization departments. ISSSTE facilities in Nuevo León and Jalisco are replacing 1990s-era fiber-optic inventories with 4K digital platforms. Maintenance contract unbundling is shifting post-warranty service to third-party ISO 13485-certified providers.
- Surgical Centers:Ambulatory facilities focused on same-day procedures with streamlined throughput requirements. Private chains in Mexico City suburbs are specifying portable capsule endoscopy systems for colonoscopy screening programs. Capital constraints favor leasing arrangements over outright purchase.
- Clinics:Primary and secondary care settings with limited procedure volumes.
- Diagnostic Laboratories:Independent pathology and imaging centers with endoscopy referral relationships.
Capital deployment tilts toward Hospitals; Surgical Centers are climbing the fastest as ambulatory volume expands.
Technology:
Digital sensor displacement of fiber-optic transmission is reordering competitive positioning among equipment vendors.
- Video Endoscopy:CMOS and CCD sensor-based systems with digital image transmission eliminating fiber-optic bundles. Monterrey metropolitan hospitals specify 1080p and 4K resolution platforms for laparoscopic surgery suites. NOM electrical safety certification requirements filter import availability.
- Capsule Endoscopy:Ingestible wireless cameras with real-time data transmission to external receivers. Guadalajara private networks are piloting telemedicine-enabled remote interpretation to radiology hubs. Patient acceptance for non-invasive screening exceeds traditional colonoscopy in affluent demographics.
- Ultrasonic Endoscopy:Combined endoscopic ultrasound for tissue characterization and fine-needle aspiration.
- Robotic Endoscopy:Computer-assisted navigation platforms with haptic feedback and autonomous scope advancement.
Installed base dominance rests with Video Endoscopy; Capsule Endoscopy is gaining share fastest as screening protocols evolve.
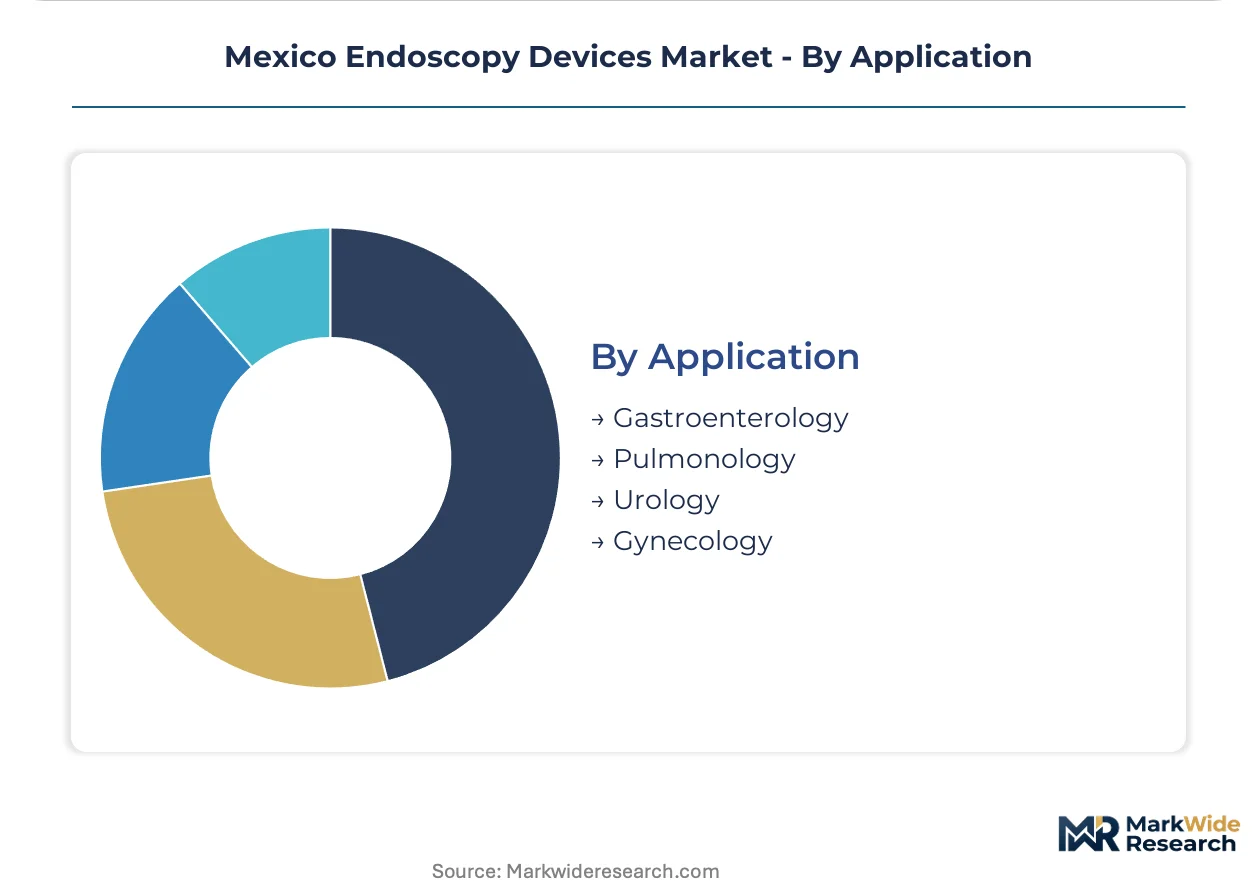
Application:
Specialist training pipeline constraints limit procedure volume growth regardless of equipment availability.
- Gastroenterology:Colonoscopy, upper endoscopy, and ERCP procedures for digestive tract pathology. Mexico produces fewer than 80 new endoscopy specialists annually, capping expansion potential. AI-assisted polyp detection algorithms represent uncontracted white space for equipment vendors.
- Pulmonology:Bronchoscopy and thoracoscopy for airway and pleural interventions. Mexico City tertiary centers specify single-use bronchoscopes for immunocompromised patient populations. COFEPRIS biocompatibility updates mandate ISO 10993-5 documentation for reusable channel registrations.
- Urology:Cystoscopy and ureteroscopy for lower and upper urinary tract visualization.
- Gynecology:Hysteroscopy and laparoscopy for reproductive tract diagnostic and surgical access.
Procedure concentration sits with Gastroenterology; Pulmonology shows the steepest expansion trajectory as interventional techniques advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Mexico's northern border concentrate endoscopy device distribution and service infrastructure, with IMMEX maquiladora programs reducing landed costs for visualization system imports. Tax incentives in these corridors attract regional headquarters for multinational equipment vendors.
Mexico City Metro
ISSSTE and IMSS tertiary hospitals drive replacement demand for aging fiber-optic fleets across the metropolitan cluster. COFEPRIS maintains its headquarters here, streamlining Class II medical device registration through digital submission portals. Hospital networks in Coyoacán and Tlalpan districts unbundle maintenance contracts from initial equipment purchases.
Nuevo León
Monterrey's industrial corridor anchors medical device assembly operations serving Central American re-export markets. State health secretariat procurement specifications favor 4K digital platforms for laparoscopic surgery suites. San Pedro Garza García hosts concentrated private hospital chains specifying single-use bronchoscopes.
Jalisco
Guadalajara metropolitan hospitals pilot telemedicine-enabled capsule endoscopy data transmission to radiology hubs. State-level modernization programs replace 1990s-era visualization systems with CMOS sensor-based platforms. Zapopan's ambulatory surgery centers drive portable screening equipment demand.
Bajío Region
Querétaro and Guanajuato automotive manufacturing spillover supports precision component fabrication for rigid endoscope supply chains. Regional health secretariats operate mixed fleets complicating sterilization workflow standardization. León's private clinic networks favor leasing arrangements over capital purchases.
Northern Border States
Baja California and Chihuahua IMMEX facilities enable tariff-advantaged reprocessing of imported visualization components. Cross-border patient flows from California and Texas create demand for English-compatible equipment interfaces. Tijuana maquiladoras assemble disposable endoscope channels for North American distribution.
Mexico Endoscopy Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's procurement landscape, creating a tiered structure where scale advantages clash with service responsiveness. The market consolidates around vendors with established Mexican technical infrastructure rather than import-only distributors. Three archetypes dominate: integrated visualization platform providers, rigid instrument precision manufacturers, and interventional portfolio specialists. Competitive moves center on maintenance contract anchoring and regulatory dossier pre-positioning ahead of INSABI tender cycles.
Among Japanese-headquartered conglomerates, Olympus Corporation exemplifies the integrated platform archetype through its service infrastructure investments. Boston Scientific Corporation represents the interventional specialist tier with concentrated gastroenterology positioning. Karl Storz SE & Co. KG anchors the German precision manufacturing segment, occupying a premium position among surgical centers requiring rigid endoscope reliability.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Fujifilm Holdings |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Medtronic |
| Johnson & Johnson |
| Conmed Corporation |
| Richard Wolf |
| Others |
Supply & Pricing Matrix
Monterrey's precision optics engineering workforce concentration anchors manufacturing cost differentials that widen pricing-tier spreads between premium German-engineered visualization systems and mid-tier Asian alternatives. Labor-cost advantages in Nuevo León's medical device corridor compress assembly expenses for reusable instrument channels while COFEPRIS compliance investments inflate landed costs for import-dependent distributors.
Pricing Analysis
Short lead-time premiums of 15-25% apply to digital visualization platforms stocked in Mexican IMMEX facilities versus spot inventory held in Asian distribution hubs. Three-tier pricing structure across premium, standard, and economy levels separates Olympus and Karl Storz service-bundled offerings from Fujifilm's mid-market positioning and emerging Chinese manufacturers. Pricing pressure stems from INSABI procurement centralization favoring total cost of ownership models over upfront capital expenditure. Public hospital networks exhibit highest price sensitivity; private tertiary centers in San Pedro Garza García prioritize service responsiveness over unit cost.
Supply Chain Analysis
CMOS image sensor supply rests on Japanese and South Korean specialty semiconductor producers, with Sony and Samsung dominating high-definition medical-grade components. German and Japanese optical glass manufacturers feed rigid endoscope rod-lens fabrication, while Chinese stainless steel suppliers anchor disposable instrument channel production. Single-source vulnerability concentrates in proprietary LED light source modules locked to specific visualization platform architectures. Distribution runs through COFEPRIS-authorized import agents in Mexico City before regional allocation to hospital networks and surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through its gastroenterologist training bottleneck, with fewer than 80 annual specialist graduates propping pricing power for procedure-capable equipment regardless of hardware availability.
For Market Incumbents: Anticipate single-use endoscope substitution threats by anchoring long-term service contracts with sterilization workflow integration. Defensive consolidation through ISO 13485-certified repair facility acquisitions in Guadalajara and Monterrey locks out third-party post-warranty competitors. Capacity addition in Nuevo León's IMMEX corridor preserves tariff advantages against Asian import-only challengers. For New Entrants and Emerging Players: COFEPRIS's 2024 digital submission portal for Class II medical devices in Mexico opens a window for AI-assisted polyp detection software vendors to bypass hardware-heavy incumbent relationships. Capsule endoscopy telemedicine interpretation services in Jalisco represent the most penetrable white-space target. Go-to-market acceleration through hospital network pilot programs with remote radiology connectivity outpaces traditional capital sales cycles. For Investors and Strategic Acquirers: The window for entry favors third-party service providers with captive ISO 13485 repair infrastructure. Five-to-ten year viability hinges on maintenance contract unbundling momentum across ISSSTE and IMSS networks. The signal to watch is INSABI tender specification shifts toward total cost of ownership scoring versus upfront equipment pricing.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Digital Registration Pre-Positioning | Accelerated approval timelines through 2024 portal submission reduce foreign manufacturer entry barriers. |
| ISO 13485 Repair Facility Acquisition | Third-party service providers capture post-warranty visualization contracts from hospital network unbundling. |
| AI-Assisted Polyp Detection Development | Computer vision algorithms create uncontracted white space in Mexican gastroenterology departments. |
| Telemedicine-Enabled Capsule Endoscopy | Remote interpretation services to Guadalajara radiology hubs generate recurring revenue streams. |
| Monterrey IMMEX Assembly Expansion | Tariff-advantaged production for Central American re-export markets reduces landed cost exposure. |
Research Methodology
Multi-period observation of hospital procurement tender awards, COFEPRIS registration timelines, and state health secretariat modernization budgets anchored the trend analysis, supplemented by interviews with biomedical engineering directors, GPO contracts managers, hospital purchasing committee members, and endoscopy specialists across Mexico City, Monterrey, and Guadalajara. Secondary validation drew from INSABI procurement databases, COFEPRIS medical device registration filings, IMSS and ISSSTE capital expenditure disclosures, and NOM standards documentation. Bottom-up equipment placement tracking triangulated against top-down healthcare infrastructure investment flows.
Segment-weighting approaches distributed value projections across product type, end user facility tier, technology platform, and application specialty dimensions throughout the forecast period. CAGRs derived from replacement cycle analysis of aging fiber-optic fleets, ambulatory surgery center expansion trajectories, and capsule endoscopy protocol adoption curves. Procedure volume constraints from gastroenterologist training pipeline limitations and sterilization workflow standardization challenges informed demand elasticity assumptions.
Caveats apply where COFEPRIS regulatory enforcement intensity, INSABI procurement centralization pace, or single-use endoscope technology cost curves could materially shift the outlook. Forecasts embed assumptions regarding NOM electrical safety certification continuity and IMMEX program stability. A small set of named triggers—gastroenterologist graduation rates, biocompatibility certification bottlenecks, and AI diagnostic reimbursement rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscopy Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Colonic Stents Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Endorectal Balloon Market