
 Global Endoscopes Market | 2026-2036
Global Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopes Market Analysis
The EU Medical Device Regulation (MDR) is shifting procurement priorities toward reusable endoscopes with validated sterilization cycles. Olympus Corporation leverages its vertically integrated manufacturing footprint in Japan to sustain cost advantages in flexible gastrointestinal scopes. Karl Storz SE & Co. KG anchors its competitive position through rigid endoscope specialization for arthroscopy and urology. Ambu A/S differentiates via single-use endoscope portfolios that eliminate reprocessing liability for hospitals.
An endoscope is a slender, tubular instrument incorporating fiber-optic or digital imaging bundles, illumination channels, and instrument ports, typically manufactured with medical-grade stainless steel sheaths and polymer distal tips to enable visual examination of hollow organs or body cavities. Its primary purpose is to facilitate minimally invasive diagnostic inspection, tissue biopsy, and therapeutic intervention without open surgery. Flexible endoscopes dominate gastrointestinal and pulmonology applications due to anatomical navigation requirements, while robot-assisted endoscopes represent the fastest-expanding technology segment as health systems invest in precision-guided platforms for complex procedures. Capsule endoscopes occupy a niche growth corridor in small-bowel diagnostics where conventional scope insertion proves difficult.
The FDA enforces strict reprocessing validation under 21 CFR Part 820 quality system regulations, while the EU MDR mandates enhanced clinical evidence and post-market surveillance for all active endoscopic devices. Japan's PMDA applies JIS T 0601 electromagnetic compatibility standards that influence design specifications for video processor integration. Stakeholders must monitor evolving single-use reimbursement codes and sterilization chemical residue limits as these factors will determine portfolio allocation between disposable and reusable platforms.
Market Dynamics
Reprocessing liability costs and sterilization validation requirements are restructuring procurement decisions across hospital systems, tilting capital allocation toward single-use platforms that eliminate cross-contamination risk and compliance documentation burdens.
Growth Catalysts
- EU MDR sterilization mandates:Enhanced clinical evidence requirements for reusable devices are accelerating hospital adoption of disposable endoscopes that bypass post-market surveillance obligations.
- Ambulatory surgical center expansion:Freestanding outpatient facilities in Germany and Japan are prioritizing compact, single-use bronchoscopes to minimize infrastructure investment.
- Robot-assisted precision platforms:Integration of haptic feedback and AI-guided navigation is expanding addressable procedures in complex urological and thoracic interventions.
Market Restraints
- Optical component supply concentration:Specialized CMOS sensors and fiber-optic bundles depend on concentrated manufacturing clusters in East Asia, creating vulnerability to trade disruption.
- Reimbursement code lag:Single-use endoscopes lack established CPT codes in several markets, forcing hospitals to absorb full device cost without pass-through compensation.
- Technical limitation in small-bowel access:Conventional flexible scopes cannot navigate the entire small intestine, restricting therapeutic intervention capability in gastroenterology.
Strategic Opportunities
- Underpenetrated Indian hospital networks:Tier-2 and Tier-3 cities lack adequate endoscopy infrastructure, creating whitespace for mobile screening units and leasing models.
- Capsule-to-scope convergence:Combining ingestible capsule imaging with magnetic steering represents an emerging application for complete small-bowel visualization.
- Japan's PMDA fast-track pathway:Breakthrough device designation for AI-integrated endoscopes offers accelerated approval timelines for novel diagnostic algorithms.
Industry Challenges
- Biocompatibility certification timelines:Novel polymer distal tips require extended ISO 10993 testing cycles that delay product launches by 18-24 months.
- Integration complexity with legacy video processors:Hospitals face capital write-downs when upgrading to 4K imaging systems incompatible with existing processor towers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopes Market |
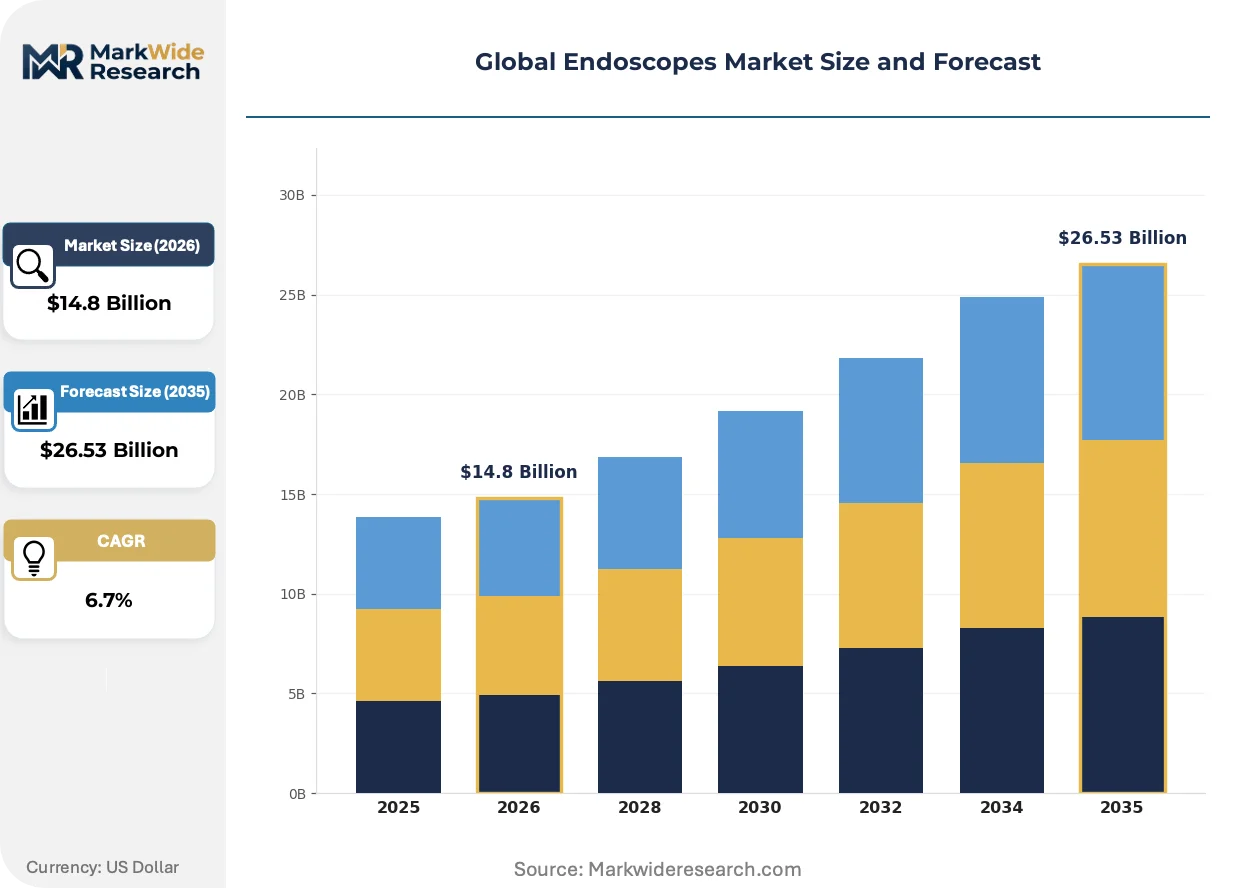
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Robot-Assisted Endoscopes Technology: Optical Endoscopy, Video Endoscopy, Transnasal Endoscopy, Digital Endoscopy End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Application: Gastroenterology, Urology, Pulmonology, Otolaryngology |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Karl Storz SE & Co. KG, FUJIFILM Holdings Corporation, Stryker Corporation, Medtronic plc, PENTAX Medical, Ambu A/S, STERIS plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopes Market Emerging Trajectories
Digital imaging and disposable platforms are converging to redefine clinical workflows, with regulatory pressure and cost accounting driving simultaneous innovation in both hardware miniaturization and service delivery models.
Disposable bronchoscopes with integrated suction channels are expanding into emergency departments and intensive care units where rapid turnaround and infection control override capital equipment economics. Pulmonology departments in US academic medical centers are adopting these devices for bedside procedures, compressing the traditional reprocessing infrastructure footprint and enabling point-of-care deployment without central sterile supply dependency.
The FDA's updated reprocessing guidance under 21 CFR Part 820 is forcing manufacturers to submit validated sterilization protocols with every 510(k) filing. Rigid endoscope suppliers serving arthroscopy markets are responding by redesigning instrument channels to eliminate biofilm-trapping crevices, while EU manufacturers face parallel pressure from MDR post-market surveillance requirements that demand real-world performance data.
Hospital procurement departments are unbundling service contracts from device purchases, negotiating separate maintenance agreements and reprocessing service fees rather than accepting bundled pricing. This shift is most visible in German university hospitals where purchasing cooperatives aggregate volume across multiple campuses to extract transparency in lifecycle cost accounting, displacing traditional manufacturer-captive service models with third-party sterilization validation providers.
Global Endoscopes Market Segmentation
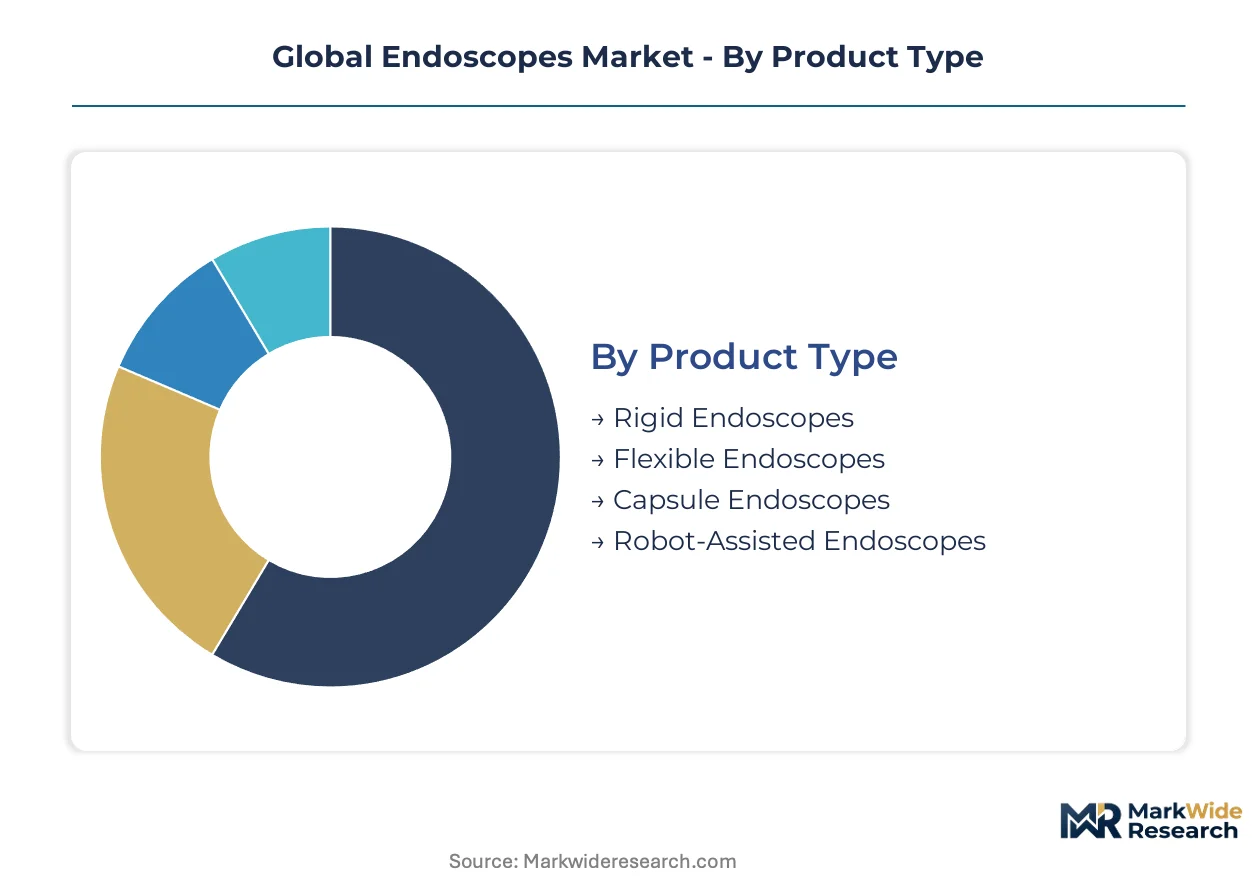
Endoscope segmentation reflects divergent regulatory pathways and capital intensity across clinical settings. Product type determines sterilization burden and FDA 510(k) versus EU MDR filing requirements, while technology choice locks hospitals into specific video processor ecosystems with decade-long replacement cycles.
Product Type:
Certification requirements split sharply across this dimension: rigid and flexible scopes face EU MDR post-market surveillance for reusable devices, while single-use alternatives bypass clinical evidence obligations but require novel biocompatibility testing under ISO 10993.
- Rigid Endoscopes:Stainless steel sheathed instruments with rod-lens optical systems dominate arthroscopy and laparoscopy suites in German university hospitals. Procurement concentrates in orthopedic service lines where sterilization validation costs are absorbed across high procedure volumes, though reprocessing liability has begun shifting preference toward disposable alternatives in ambulatory settings.
- Flexible Endoscopes:Fiber-optic or digital imaging bundles encased in polymer jackets enable gastrointestinal and pulmonology navigation through tortuous anatomy. Demand clusters in Japan and the United States where hospital procurement budgets for minimally invasive equipment sustain premium pricing, with gastrointestinal applications commanding the largest installed base of any product category.
- Capsule Endoscopes:Ingestible imaging platforms with wireless data transmission occupy small-bowel diagnostics where conventional scope insertion fails.
- Robot-Assisted Endoscopes:Precision-guided platforms with haptic feedback and AI navigation represent the steepest expansion trajectory in complex urological interventions.
Flexible endoscopes sit at the top of the volume ranking, with robot-assisted platforms climbing the fastest.
Technology:
Cost tiering separates legacy optical systems from digital platforms requiring complete video processor replacement, creating stranded asset risk for hospitals with recent capital investments.
- Video Endoscopy:CMOS sensor-based imaging with 4K resolution output has become the standard of care in US academic medical centers. The technology locks purchasers into proprietary processor towers, with Japanese manufacturers leveraging JIS T 0601 electromagnetic compatibility standards to create integration barriers against third-party peripherals.
- Digital Endoscopy:Fully digital signal chains from distal tip to display eliminate analog conversion artifacts and enable AI algorithm deployment for polyp detection. Adoption concentrates in tertiary hospitals with capital budgets for complete system overhauls, though backward compatibility limitations force parallel infrastructure during transition periods.
- Optical Endoscopy:Traditional fiber-optic bundles persist in resource-constrained settings.
- Transnasal Endoscopy:Ultrathin scope designs for unsedated upper GI examination reduce anesthesia costs in outpatient workflows.
Video endoscopy captures the dominant revenue share, while digital platforms are gaining share fastest through replacement demand.
End User:
Customer type dictates pricing power and service contract structure, with hospital purchasing cooperatives extracting unbundled maintenance agreements that displace manufacturer-captive service models.
- Hospitals:Integrated delivery networks with centralized sterile processing departments sustain reusable endoscope economics through scale. German university hospitals have pioneered cooperative procurement that aggregates volume across multiple campuses, forcing transparency in lifecycle cost accounting and reprocessing validation fees.
- Ambulatory Surgical Centers:Freestanding outpatient facilities prioritize single-use bronchoscopes and colonoscopes to eliminate infrastructure investment. These settings in Japan and the United States are accelerating adoption of disposable platforms that compress the traditional reprocessing footprint and enable point-of-care deployment.
- Clinics:Physician office laboratories with limited capital budgets favor leasing models and mobile screening units.
- Diagnostic Laboratories:Reference labs with high throughput requirements concentrate demand for capsule endoscopy reading services.
Hospitals retain the largest installed base, with ambulatory surgical centers expanding most quickly through greenfield construction.
Application:
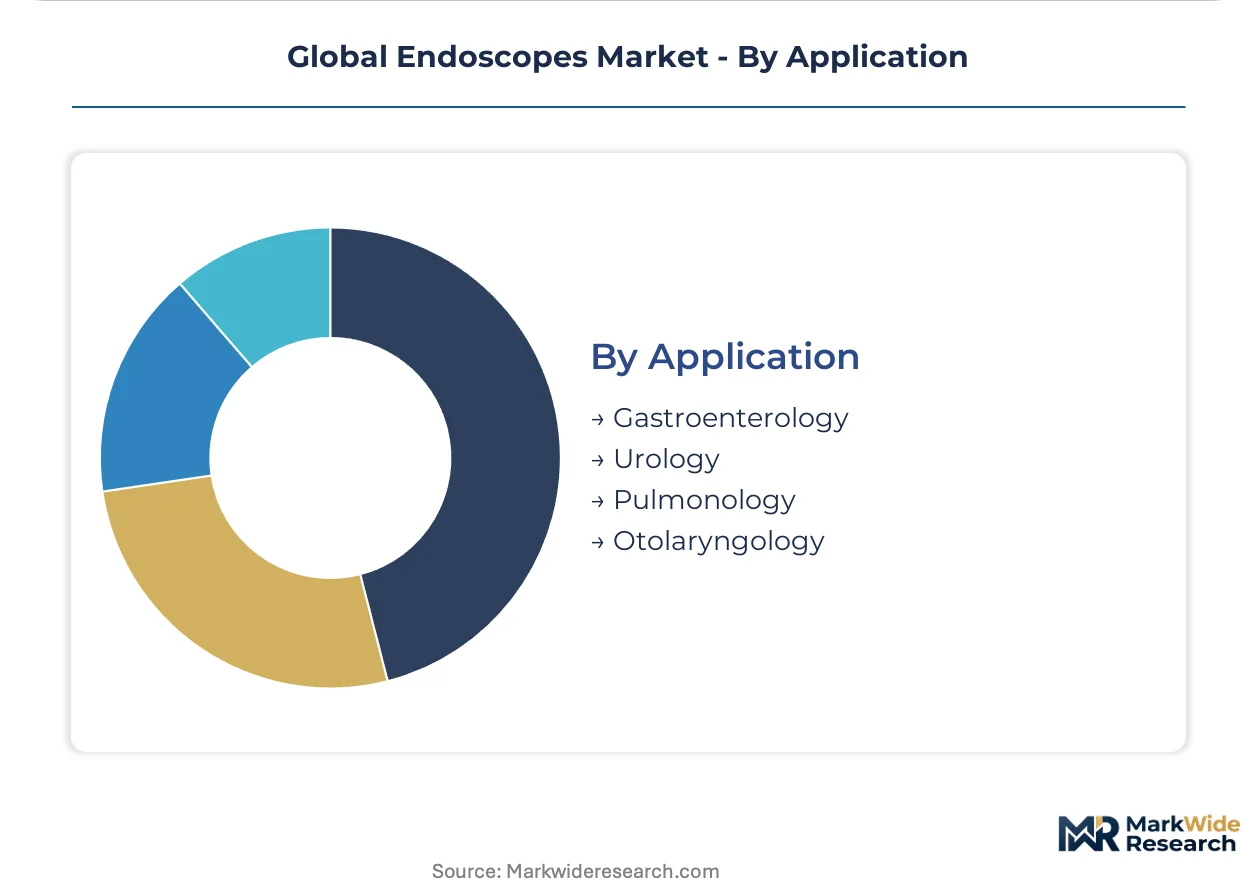
Maturity gradients separate well-penetrated gastrointestinal screening from emerging therapeutic applications in pulmonology where interventional techniques are still diffusing.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy represent the most mature application with established screening protocols in the United States and Germany. The segment absorbs the highest absolute volume of flexible endoscopes, though reimbursement pressure on screening colonoscopy is flattening growth trajectories.
- Pulmonology:Bronchoscopy for lung cancer staging and interventional procedures is expanding fastest as electromagnetic navigation and robotic platforms enable peripheral lesion access. US academic medical centers are adopting disposable bronchoscopes for bedside procedures in emergency departments and intensive care units.
- Urology:Cystoscopy and ureteroscopy maintain steady replacement demand.
- Otolaryngology:Rigid laryngoscopes and sinuscopes serve concentrated ENT specialist practices.
Gastroenterology sits at the top of the volume ranking, with pulmonology climbing the fastest through interventional procedure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endoscopy technicians and biomedical engineers cluster in Germany, Japan, and the United States, anchoring regional innovation capacity. Hospital procurement networks in these markets sustain premium equipment demand through established minimally invasive surgery programs. Regulatory divergence between FDA, EU MDR, and Japan's PMDA is fragmenting product approval pathways.
United States
Academic medical centers in Boston and the Research Triangle drive demand for robot-assisted precision platforms. The FDA enforces reprocessing validation under 21 CFR Part 820, accelerating hospital adoption of single-use bronchoscopes. Minneapolis-St. Paul hosts concentrated medical device engineering talent supporting video processor integration.
Germany
University hospital purchasing cooperatives in Bavaria and North Rhine-Westphalia aggregate procurement volume across multiple campuses. The EU MDR mandates enhanced post-market surveillance for reusable devices, shifting preference toward disposable alternatives in ambulatory settings. Tuttlingen remains the global cluster for rigid endoscope manufacturing.
Japan
Tokyo and Osaka metropolitan areas concentrate gastrointestinal screening demand with established national health insurance coverage. The PMDA applies JIS T 0601 electromagnetic compatibility standards that shape video processor design specifications. Olympus Corporation leverages vertically integrated manufacturing in Hachioji to sustain cost advantages in flexible scopes.
India
Tier-2 and Tier-3 cities lack adequate endoscopy infrastructure, creating whitespace for mobile screening units. The CDSCO regulates device imports under Medical Device Rules 2017, with recent notifications reclassifying endoscopes as higher-risk devices. Hyderabad and Bengaluru emerge as hubs for third-party sterilization validation services.
China
Provincial hospital networks in the Yangtze River Delta expand minimally invasive surgery capacity. The NMPA implements GB standards for electromagnetic compatibility that influence domestic manufacturer design choices. Shenzhen clusters CMOS sensor suppliers serving regional digital endoscope assembly.
Global Endoscopes Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the endoscope supply chain, with integrated manufacturers maintaining in-house optical component fabrication while specialists outsource sensor procurement. The vendor base concentrates around three strategic archetypes: diversified conglomerates with medical device divisions, pure-play endoscope specialists, and single-use disposable innovators. Competitive moves center on M&A for regulatory pathway acceleration and capacity expansion in polymer distal tip manufacturing.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation represent integrated manufacturers with captive optical component supply. Karl Storz SE & Co. KG exemplifies the specialist archetype through rigid endoscope concentration. Ambu A/S occupies a position exemplifying the single-use disposable vector, eliminating reprocessing liability for hospital customers.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Karl Storz SE & Co. KG |
| FUJIFILM Holdings Corporation |
| Stryker Corporation |
| Medtronic plc |
| PENTAX Medical |
| Ambu A/S |
| STERIS plc |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Tuttlingen and Hachioji anchor rigid endoscope production, their conservative balance sheets limiting price volatility even as polymer distal tip costs fluctuate. Their financing discipline translates into stable contract pricing for German university hospitals while insulating against raw material spikes.
Pricing Analysis
The bundled-vs-unbundled service split is restructuring hospital procurement economics across major markets. Pricing stratifies across premium, standard, and economy tiers, with EU MDR certification grade and after-sales service bundling as the primary differentiation drivers. Cost compression in standard-tier flexible scopes is intensifying because Japanese manufacturers are absorbing video processor R&D across broader installed bases. Ambulatory surgical centers exhibit highest price sensitivity, while US academic medical centers with NIH funding streams demonstrate lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework and India's CDSCO notification are reshaping sourcing patterns for CMOS sensors and fiber-optic bundles. Manufacturing concentrates in Japan, Germany, and China, with specialized optical component fabrication drawing from concentrated East Asian sensor foundries and German precision glassworks. Single-source vulnerability in CMOS sensor supply creates exposure to trade disruption. Distribution runs through hospital purchasing cooperatives in Germany and group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in endoscopy rests on polymer distal tip cost-down curves and the premium-tier shift toward robot-assisted platforms with AI navigation capabilities.
For Market Incumbents: Anticipate single-use disposable entrants eroding service contract attach rates by accelerating backward integration into polymer distal tip manufacturing and securing JIS T 0601 certification for next-generation video processors. Lock hospital systems into decade-long processor upgrade cycles before 4K imaging compatibility becomes mandatory. For New Entrants and Emerging Players: Tier-2 Indian cities with mobile screening unit demand represent the most penetrable white-space target, followed by US emergency departments seeking bedside bronchoscopy without central sterile supply infrastructure. Pursue leasing-model go-to-market structures that bypass capital budget approval cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among rigid endoscope specialists with arthroscopy concentration and underutilized Tuttlingen manufacturing footprints. Long-term viability over a 5-10 year window favors assets with EU MDR technical documentation already filed. Watch FDA 510(k) clearance velocity for AI-integrated diagnostic algorithms as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation accelerates hospital procurement decisions in German cooperatives. |
| Hospital System Partnership | Integrated delivery network contracts displace fragmented regional distributor relationships. |
| Software Companion Development | AI polyp detection algorithms lock purchasers into proprietary video processor ecosystems. |
| Reimbursement Strategy | CPT code establishment for single-use bronchoscopes determines ambulatory surgical center adoption velocity. |
| Backward Integration | In-house polymer distal tip production reduces ISO 10993 testing cycle delays and supplier concentration risk. |
Methodological Framework
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and sterile processing department supervisors grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Bottom-up installed base estimates triangulated against top-down capital equipment spending forecasts.
Segment-level value outputs across product type, technology tier, end-user category, and application area were modeled over the projection horizon. CAGRs were derived from procedure volume growth trajectories and replacement cycle dynamics, with Japanese gastrointestinal screening protocol adherence and German ambulatory surgical center construction permits serving as key forecast inputs.
Underlying measurement precision varies by segment; robot-assisted endoscope forecasts carry tighter precision than capsule endoscopy projections given earlier commercialization stage. Forecasts reflect assumptions around regulatory clearance timelines and reimbursement code establishment. Supply chain disruption in CMOS sensor manufacturing or shifts in EU MDR post-market surveillance enforcement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Sigmoidoscope Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
China Arthroscopy Market
Endoscopy
Hysteroscopy Procedures Market