
 Spain Contraceptive Devices Market | 2026-2036
Spain Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Contraceptive Devices Market Analytics
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape for contraceptive devices in Spain. Bayer AG leverages its hormonal IUD portfolio to sustain dominance in prescription channels, while Cooper Surgical Inc anchors its position through specialized intrauterine device manufacturing. CEX Internacional S A competes on geographic proximity, controlling distribution networks across Iberian retail pharmacies.
Contraceptive devices encompass barrier, hormonal, and long-acting reversible technologies engineered from medical-grade latex, silicone elastomers, or polyethylene teraphthalate, designed to prevent pregnancy through mechanical obstruction, spermicidal action, or sustained hormone release. Intrauterine devices lead product type revenue due to extended duration of efficacy and higher per-unit pricing, while online delivery mode expands fastest as telehealth platforms integrate prescription workflows. Silicone-based materials command premium positioning in implant segments where biocompatibility and five-year efficacy profiles justify elevated manufacturing costs.
Spain's national health system and the Spanish Agency for Medicines and Health Products enforce post-market surveillance and reimbursement eligibility for contraceptive devices, directly shaping which products reach public hospital formularies. The EU Medical Device Regulation tightens clinical evidence requirements, forcing manufacturers to intensify post-market follow-up studies for implantable contraceptives. Stakeholders must monitor how regional autonomous health services negotiate centralized procurement contracts for long-acting reversible contraceptives.
Market Dynamics
The Spanish Agency for Medicines and Health Products enforces EU Medical Device Regulation compliance, bifurcating competitive positioning between CE-marked innovators and legacy distributors struggling with clinical evidence requirements for implantable contraceptives.
Growth Catalysts
- Public Reimbursement Expansion:The Ministry of Health's inclusion of long-acting reversible contraceptives in national coverage reshapes prescribing patterns toward IUDs and implants.
- Telehealth Integration:Digital prescription workflows through specialized family planning clinics in Madrid and Barcelona accelerate patient access to hormonal devices.
- Silicone Elastomer Advances:Five-year biocompatibility profiles in implant segments justify premium positioning and expand addressable patient cohorts.
Market Restraints
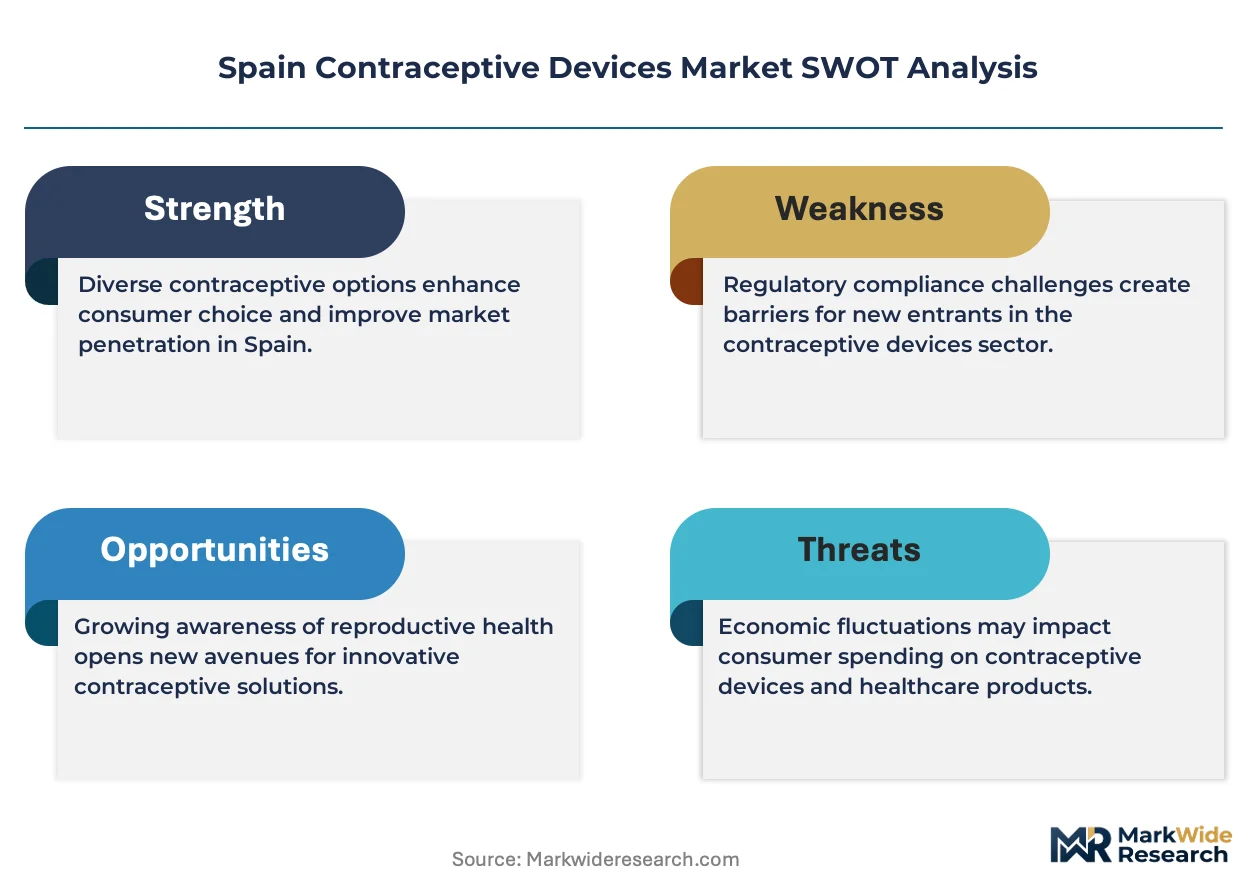
- Clinical Evidence Burden:EU MDR post-market surveillance requirements force manufacturers to intensify follow-up studies, compressing margins for mid-tier players.
- Regional Procurement Fragmentation:Autonomous health services negotiate decentralized contracts, creating pricing inconsistency across Catalonia, Andalusia, and Basque Country.
- Barrier Method Substitution:Male condom accessibility through retail pharmacies without prescription siphons price-sensitive demand from device categories.
Strategic Opportunities
- Underpenetrated Autonomous Communities:Castilla-La Mancha and Extremadura lack specialized family planning infrastructure, creating whitespace for clinic-network expansion.
- Online Channel Development:Pharmacy-integrated telehealth platforms enable direct-to-patient delivery of barrier devices, bypassing traditional hospital formulary gatekeepers.
- Hormonal-Mechanical Convergence:Combination IUD technologies merging copper spermicidal action with localized hormone release address unmet efficacy preferences.
Industry Challenges
- Specialized Gynecological Training Gaps:Insertion competency for implantable devices concentrates in urban hospital systems, limiting rural deployment.
- CE Marking Timeline Compression:Notified body backlog under EU MDR extends certification cycles for polyethylene teraphthalate IUD variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Contraceptive Devices Market |
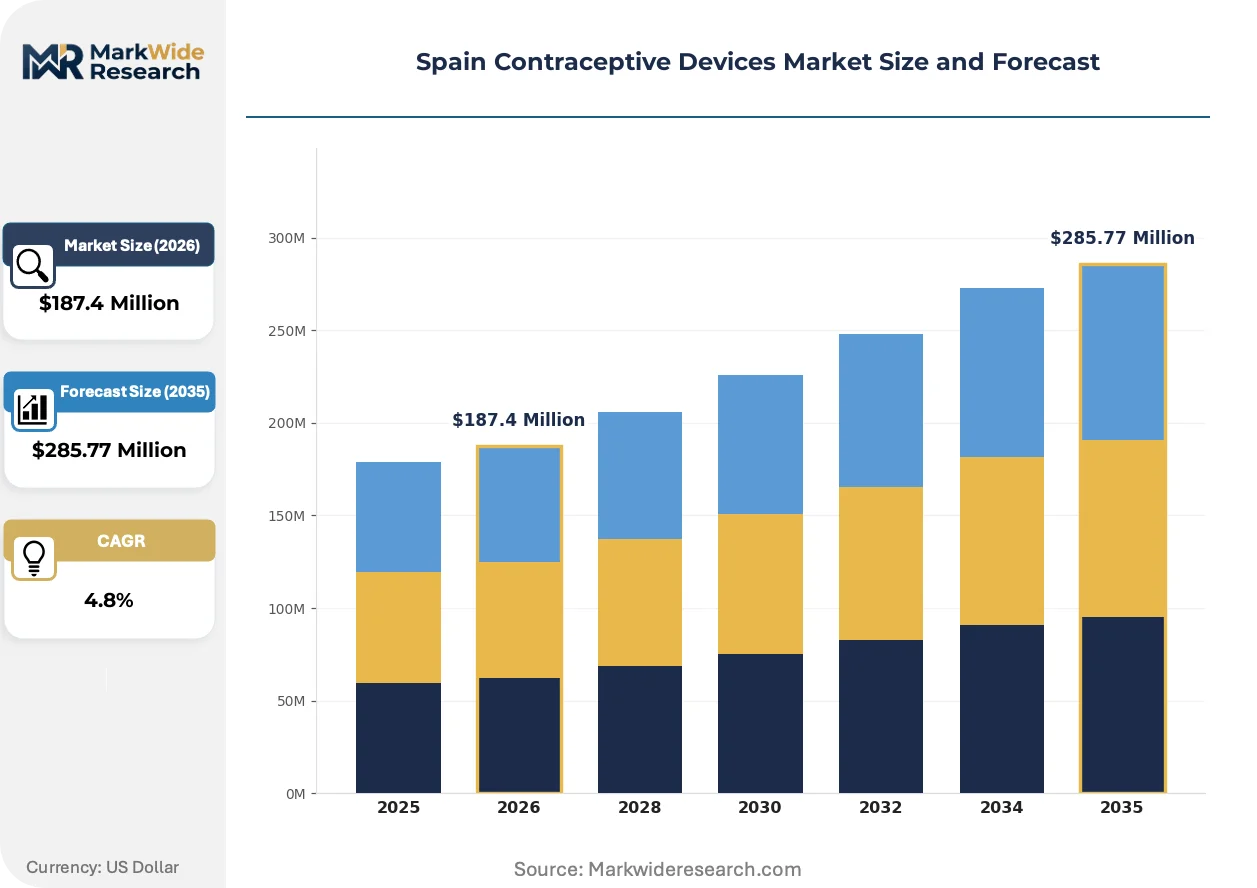
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Intrauterine Devices, Implants, Diaphragms Delivery Mode: Over-the-Counter, Prescription, Online, Clinics End User: Women, Healthcare Providers, Pharmacies, Hospitals Material: Latex, Polyurethane, Silicone, Plastic |
| Companies Covered | AbbVie (Allergan PLC), Bayer AG, Cooper Surgical Inc, Viatris Inc, Pfizer Inc, Teva Pharmaceutical Industries Ltd, CEX Internacional S A, GAUTEX MEDICA, Reckitt Benckiser, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Contraceptive Devices Market Evolving Landscape
Silicone-based manufacturing and digital care pathways are compressing traditional distribution hierarchies while elevating biocompatibility standards across Spanish contraceptive procurement.
Bioresorbable implant materials are miniaturizing delivery systems for subdermal contraceptives. Specialized family planning clinics in Barcelona adopt these formats within six-month procurement cycles. The technology is miniaturizing patient discomfort complaints and expanding same-day insertion capacity.
EU Medical Device Regulation tightens clinical evidence requirements for Class III implantable devices. Manufacturers must submit post-market follow-up data to notified bodies annually. Hormonal IUD portfolios face extended review timelines, favoring incumbents with established surveillance infrastructure.
Patient preference gravitates toward discreet, long-acting methods that eliminate daily adherence burdens. Younger cohorts in Madrid seek five-year implant solutions through private telehealth channels, displacing traditional quarterly clinic visit patterns. This behavioral pivot concentrates revenue in subscription-based digital pharmacy platforms.
Spain Contraceptive Devices Market Segmentation
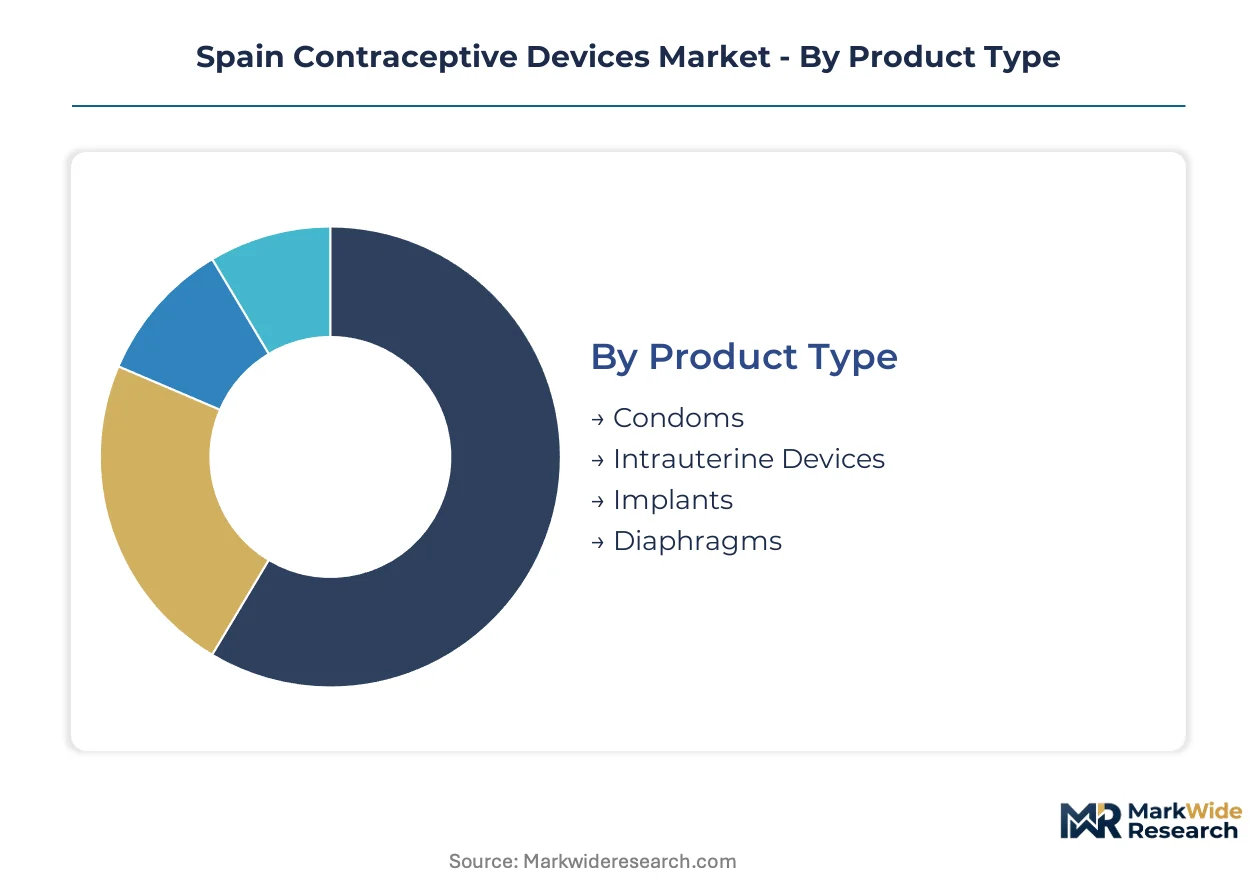
CE marking under EU MDR creates divergent compliance burdens across device categories, fragmenting competitive positioning by technical classification. Segmentation reveals where regulatory stringency concentrates margin pressure and where channel evolution unlocks access expansion.
Product Type:
EU MDR Class III designation for implantable devices forces hormonal and mechanical categories through distinct clinical evidence pathways, bifurcating manufacturer investment requirements.
- Intrauterine Devices:Polyethylene teraphthalate or copper-based mechanical systems with five-to-ten year efficacy profiles. Madrid and Barcelona specialized clinics drive uptake through insertion competency concentration, though rural Andalusia faces access constraints from gynecological training gaps.
- Implants:Subdermal silicone elastomer rods releasing progestin over three-to-five years. Younger cohorts in urban autonomous communities seek these through private telehealth channels, displacing traditional quarterly clinic visit patterns with subscription-based digital pharmacy platforms.
- Condoms:Medical-grade latex or polyurethane barrier methods distributed through retail pharmacy networks without prescription requirements.
- Diaphragms:Silicone or latex cervical barriers requiring fitting by healthcare providers, limiting volume through service dependency.
Intrauterine Devices handle the majority of throughput; Implants are expanding most quickly among long-acting reversible categories.
Delivery Mode:
Channel economics stratify by prescription control and reimbursement eligibility, with public formulary inclusion determining volume concentration.
- Prescription:Hormonal IUDs and implants requiring medical authorization, concentrated in hospital formularies and specialized family planning clinics. Ministry of Health coverage expansion reshapes prescribing patterns toward these channels.
- Online:Pharmacy-integrated telehealth platforms enabling direct-to-patient delivery. Barcelona and Madrid digital health startups compress traditional distribution hierarchies through prescription workflow integration.
- Over-the-Counter:Barrier methods accessible without medical consultation, siphoning price-sensitive demand through retail pharmacy density.
- Clinics:Physical insertion and fitting services, with capacity concentrated in urban hospital systems and autonomous community health services.
Prescription channels capture the highest per-unit value; Online is climbing the fastest as telehealth platforms scale.
End User:
Decision-making authority fragments across patient preference, provider training, and procurement centralization in autonomous health services.
- Women:Primary decision-makers for personal contraceptive selection, with Spanish women aged 18-35 representing the fastest-expanding cohort for long-acting reversible methods.
- Healthcare Providers:Gynecologists and family planning specialists controlling insertion access and method counseling, with competency clustering in Madrid and Barcelona hospital systems.
- Pharmacies:Distribution gatekeepers for barrier methods and prescription fulfillment, with CEX Internacional S A controlling Iberian retail networks.
- Hospitals:Autonomous community health services negotiating centralized procurement contracts for implantable devices, creating pricing inconsistency across Catalonia, Andalusia, and Basque Country.
Women drive volume through direct demand formation; Healthcare Providers control access to highest-efficacy methods.
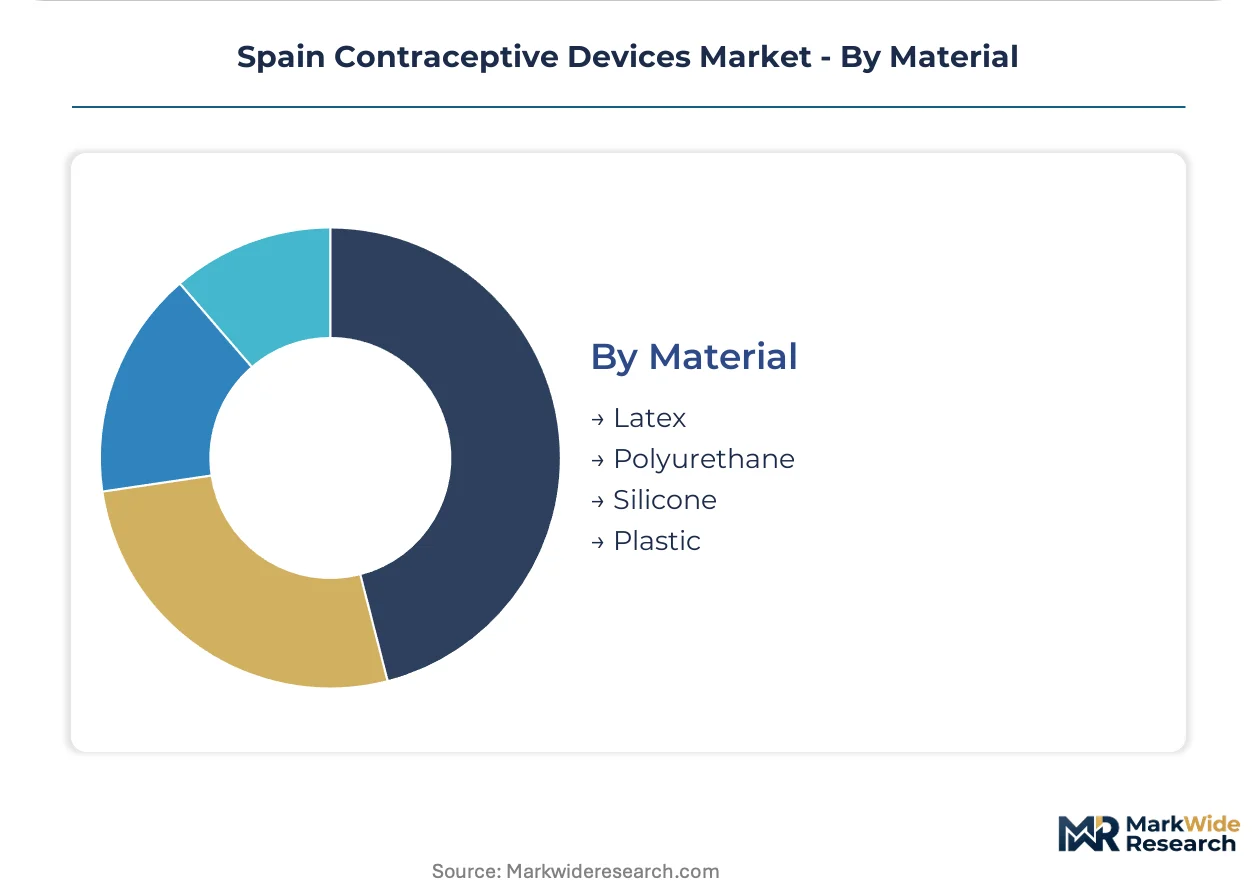
Material:
Biocompatibility standards and manufacturing cost structures segment pricing tiers, with silicone commanding premium positioning in implantable formats.
- Silicone:Medical-grade elastomers enabling five-year implant efficacy and miniaturized delivery systems. Bioresorbable variants under development in Barcelona specialized clinics reduce insertion discomfort complaints.
- Latex:Natural rubber barrier method standard, facing polyurethane substitution in allergy-sensitive segments.
- Polyurethane:Synthetic alternative for condom manufacturing, addressing latex sensitivity without mechanical performance compromise.
- Plastic:Polyethylene and polypropylene variants in non-hormonal IUD frames, subject to extended CE marking timelines under notified body backlog.
Silicone captures premium positioning in implant segments; Plastic faces regulatory timeline compression from EU MDR backlog.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Health's inclusion of long-acting reversible contraceptives in national coverage reshapes demand formation across Spanish autonomous communities. Regional procurement fragmentation creates pricing inconsistency, while specialized clinic networks concentrate in major metropolitan areas.
Madrid
Spanish women aged 18-35 in the capital region drive fastest-expanding demand for implantable devices. The autonomous community health service negotiates centralized procurement contracts that determine hospital formulary inclusion. Specialized family planning clinics in Madrid's hospital systems concentrate insertion competency and accelerate IUD uptake through same-day service capacity.
Catalonia
Barcelona anchors the online delivery mode expansion as pharmacy-integrated telehealth platforms scale prescription workflows. The Catalan health service maintains decentralized procurement autonomy, creating pricing divergence from national contracting patterns. Bioresorbable implant materials enter clinical use through Barcelona specialized clinics within accelerated six-month procurement cycles.
Basque Country
Osakidetza's autonomous health service operates independent reimbursement schedules for hormonal devices. Regional training programs address gynecological insertion competency gaps that limit rural deployment elsewhere. Bilbao and San Sebastián hospital networks maintain specialized family planning infrastructure comparable to Madrid and Barcelona concentrations.
Andalusia
Rural provinces face access constraints from gynecological training gaps that concentrate implant insertion capacity in urban hospital systems. The Andalusian health service's decentralized contracting creates procurement fragmentation across eight provinces. Seville and Málaga metropolitan areas concentrate specialized clinic capacity while interior regions remain underpenetrated for long-acting reversible methods.
Valencia
The autonomous community exhibits intermediate penetration for hormonal IUDs between leading and lagging regions. Regional health authorities negotiate procurement contracts that reference Madrid pricing benchmarks with local volume adjustments. Valencia city's hospital network maintains insertion competency while Alicante and Castellón provinces show whitespace for clinic-network expansion.
Spain Contraceptive Devices Market Competitive Landscape
Player mix skews toward multinational pharmaceutical manufacturers with established CE marking infrastructure under EU MDR. The vendor base separates into three tiers: incumbents with post-market surveillance systems, mid-tier distributors facing clinical evidence burdens, and regional pharmacy network controllers. Strategic archetypes include hormonal device innovators, mechanical IUD specialists, and Iberian distribution gatekeepers. Competitive moves concentrate on M&A for surveillance infrastructure and geographic expansion into underpenetrated autonomous communities.
Within the multinational pharmaceutical tier, Bayer AG and AbbVie occupy positions exemplifying incumbent infrastructure advantages under tightened EU MDR requirements. Cooper Surgical Inc represents specialized intrauterine device manufacturing concentration. CEX Internacional S A anchors the regional distribution archetype through Iberian retail pharmacy network control. These three companies illustrate how CE marking compliance and geographic proximity create divergent competitive positioning in Spanish procurement channels.
| Leading Market Players |
|---|
| AbbVie (Allergan PLC) |
| Bayer AG |
| Cooper Surgical Inc |
| Viatris Inc |
| Pfizer Inc |
| Teva Pharmaceutical Industries Ltd |
| CEX Internacional S A |
| GAUTEX MEDICA |
| Reckitt Benckiser |
| Others |
Value Network & Pricing Analysis
EU MDR compliance scale economies concentrate manufacturing among CE-marked incumbents with established post-market surveillance infrastructure, compressing price floors for mid-tier distributors lacking clinical evidence systems while elevating entry barriers for polyethylene teraphthalate IUD variants facing notified body backlog.
Pricing Analysis
Certification level under EU MDR creates the primary spread between premium silicone implant tiers and standard plastic IUD categories, with CE marking timelines and biocompatibility profiles driving price differentiation. Three-tier pricing structure across premium silicone implants, standard hormonal IUDs, and economy barrier methods reflects reimbursement eligibility and insertion service bundling. Pricing pressure stems from regional procurement fragmentation as autonomous health services negotiate decentralized contracts across Catalonia, Andalusia, and Basque Country. Price-sensitive demand concentrates in over-the-counter barrier segments, while least sensitivity appears in private telehealth channels for five-year implant solutions.
Supply Chain Analysis
Container availability through Barcelona and Valencia ports shapes inbound logistics costs for medical-grade silicone elastomers sourced from German and Swiss specialty chemical manufacturers. Manufacturing concentration rests on Germany for hormonal API synthesis, Ireland for implantable device assembly, and China for polyethylene teraphthalate raw materials. Single-source vulnerability concentrates in notified body certification capacity for Class III implantable devices under EU MDR. Distribution runs through CEX Internacional S A's Iberian retail pharmacy networks for barrier methods, with hospital formulary gatekeepers controlling implantable device access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Medical Device Regulation certification requirements are accelerating market disruption, with tightened clinical evidence standards favoring incumbents with surveillance infrastructure while displacing legacy distributors.
For Market Incumbents: Consolidate post-market surveillance capabilities through acquisition of specialized CRO infrastructure to defend against CE marking timeline compression for hormonal IUD portfolios. Deepen backward integration into medical-grade silicone elastomer supply to offset raw material cost volatility from German and Swiss specialty chemical dependence. For New Entrants and Emerging Players: Rural gynecological training gaps in Castilla-La Mancha and Extremadura represent the most penetrable whitespace for clinic-network expansion with same-day insertion service models. Pharmacy-integrated telehealth platforms enable direct-to-patient delivery bypassing traditional hospital formulary gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with established EU MDR compliance infrastructure and bioresorbable implant material pipelines. Long-term viability hinges on surveillance system ownership rather than device innovation alone. The signal to watch is notified body capacity expansion announcements affecting CE marking timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III designation requires annual post-market follow-up data submission to notified bodies. |
| Hospital System Partnership | Autonomous community health services negotiate centralized procurement contracts determining formulary inclusion. |
| Reimbursement Strategy | Ministry of Health coverage expansion for long-acting reversible contraceptives reshapes prescribing patterns. |
| Software Companion Development | Telehealth platform integration enables prescription workflow automation for Barcelona and Madrid digital health startups. |
| Backward Integration | In-house silicone elastomer production reduces dependence on German and Swiss specialty chemical suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gynecologists, family planning clinic directors, hospital procurement managers, biomedical engineers, and pharmacy network executives, validated against secondary sources including AEMPS regulatory filings, EU MDR notified body databases, autonomous community health service procurement records, and Spanish national health system reimbursement schedules, with bottom-up volume triangulation against top-down value estimates.
Across the projection horizon, the analytical framework modeled segmentation by product type, delivery mode, end user, and material composition, with CAGRs derived from trend extrapolation of public reimbursement expansion rates and telehealth platform penetration curves, incorporating autonomous community-level procurement contract data and silicone elastomer manufacturing capacity announcements.
Forecasts assume regulatory continuity in EU MDR implementation and AEMPS enforcement; material policy shifts such as accelerated CE marking timeline compression or reimbursement eligibility expansion would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
ADA Substitute Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Cannula Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Implantable Collamer Lens Market