
 Global Endoscope Reprocessing Market | 2026-2036
Global Endoscope Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscope Reprocessing Market Foresight
High-level disinfection validation standards is reorganizing procurement priorities across healthcare systems. STERIS plc leverages its installed base of automated reprocessors to sustain recurring consumable revenue streams. Olympus Corporation anchors its competitive stance through integrated scope-and-reprocessor bundling. Getinge AB differentiates via centralized sterile processing department solutions that span multiple clinical service lines.
Endoscope reprocessing encompasses the complete decontamination cycle for flexible and rigid endoscopes, integrating enzymatic pre-cleaning, leak testing, high-level disinfection or sterilization, drying, and secure storage to eliminate microbial bioburden and prevent patient-to-patient pathogen transmission. Automated Endoscope Reprocessors dominate capital expenditure allocations while Drying Technology segments capture disproportionate margin expansion as moisture-related contamination events drive protocol tightening. High-Level Disinfection remains the largest technology category though Contamination Monitoring Systems represent the fastest-attached growth vector as traceability mandates harden.
FDA 510(k) clearance requirements, EPA disinfectant efficacy standards, and ISO 15883 washer-disinfector specifications collectively elevate compliance costs and consolidate vendor qualification pools. The EU MDR and CSRD frameworks extend documentation and sustainability obligations for equipment placed in European member states. Stakeholders must monitor evolving hydrogen peroxide and peracetic acid residue limits as these chemistries displace glutaraldehyde in next-generation reprocessor formulations.
Market Dynamics
The transition from glutaraldehyde to hydrogen peroxide and peracetic acid chemistries is restructuring capital replacement cycles and consumable revenue models across hospital sterile processing departments.
Growth Catalysts
- Joint Commission Infection Control Mandates:US hospitals face unannounced inspections targeting endoscope reprocessing documentation, forcing automated reprocessor upgrades and staff retraining investments.
- Single-Use Endoscope Competition:Ambulatory surgery centers are adopting disposable bronchoscopes and cystoscopes, compelling reusable scope reprocessors to validate higher sterility assurance levels to retain procurement contracts.
- EPA Disinfectant Efficacy Standards:Accelerated sporicidal testing protocols are eliminating marginal chemistries from approved lists, concentrating vendor qualification pools among established automated reprocessor manufacturers.
Market Restraints
- Stainless Steel and Polymer Input Volatility:Reprocessor chassis and tubing assemblies depend on nickel-price-sensitive alloys and medical-grade fluoropolymers subject to energy-driven cost swings.
- European Vendor Concentration:Centralized sterile processing equipment manufacturing clusters in southern Germany and northern Italy create geographic supply risk for North American hospital capital budgets.
- Glutaraldehyde Workplace Exposure Limits:OSHA permissible exposure ceilings and NIOSH respiratory hazard classifications are forcing premature retirement of installed base units before full depreciation.
Strategic Opportunities
- India Diagnostic Center Expansion:Private hospital chains in Mumbai, Delhi, and Bangalore are building endoscopy capacity faster than sterile processing infrastructure, creating first-mover service contract opportunities.
- EU MDR Traceability Requirements:Unique device identification mandates for reprocessing equipment are opening software and data analytics attach revenue streams alongside hardware sales.
- AI-Assisted Leak Detection:Machine vision integration with automated reprocessors is converging robotics and diagnostic imaging to reduce manual inspection labor and false-negative rates.
Industry Challenges
- Certified Reprocessing Technician Shortage:IAHCSMM and CBSPD credentialing backlogs are extending staff onboarding timelines beyond typical capital equipment installation windows.
- Legacy Scope Compatibility Burden:Olympus, Pentax, and Karl Storz legacy connector designs require adapter development and validation testing that delays new reprocessor model launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscope Reprocessing Market |
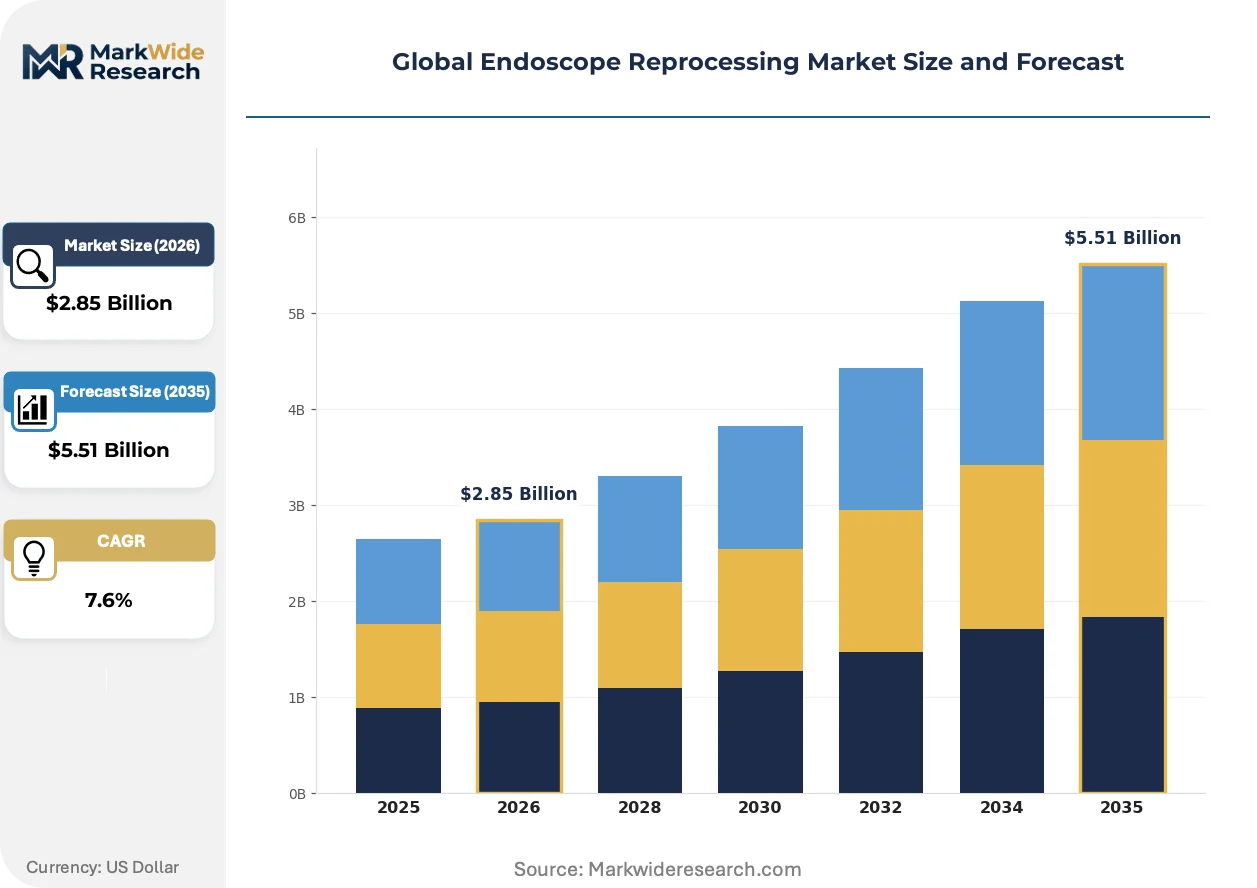
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.51 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Endoscope Reprocessors, Manual Cleaning Systems, Storage Cabinets, Drying Units, Transport Cases Technology: High-Level Disinfection, Ultrasonic Cleaning, Enzymatic Cleaning, Drying Technology, Contamination Monitoring Systems Application: Gastroenterology Procedures, Urology Diagnostics, Pulmonology Examinations, ENT Inspections, Gynecology Evaluations End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Laboratories, Infection Control Units |
| Companies Covered | STERIS plc, Olympus Corporation, Getinge AB, Ecolab Inc, ASP, Cantel Medical, HOYA Corporation, CONMED Corporation, Belimed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscope Reprocessing Market Shifts & Advancements
Digital traceability and closed-loop chemistry management are converging to transform endoscope reprocessing from a manual compliance exercise into an integrated patient safety system.
Peracetic acid-based automated reprocessors are decomposing the historical glutaraldehyde-dominant installed base in North American hospitals. Academic medical centers in Boston and Philadelphia are replacing legacy units at accelerated depreciation schedules. The shift is compressing capital replacement cycles from ten-year to seven-year intervals while elevating consumable attach rates for buffered acid formulations.
EU MDR technical documentation requirements are extending validation obligations for washer-disinfectors placed in European member states. Manufacturers must now maintain post-market surveillance systems tracking adverse events across the device lifecycle. German hospital procurement consortia are demanding ISO 15883-4 compliant drying technology as a non-negotiable specification, forcing chemistry-only vendors to partner or exit.
After-sales service unbundling is disrupting traditional capital-plus-consumable bundling in US group purchasing organization contracts. IDN supply chain executives are separating reprocessor hardware acquisition from chemistry supply agreements to optimize total cost of ownership metrics. This pattern is most visible in California and Texas health systems where centralized sterile processing department consolidation has created volume leverage for disaggregated sourcing.
Global Endoscope Reprocessing Market Segmentation
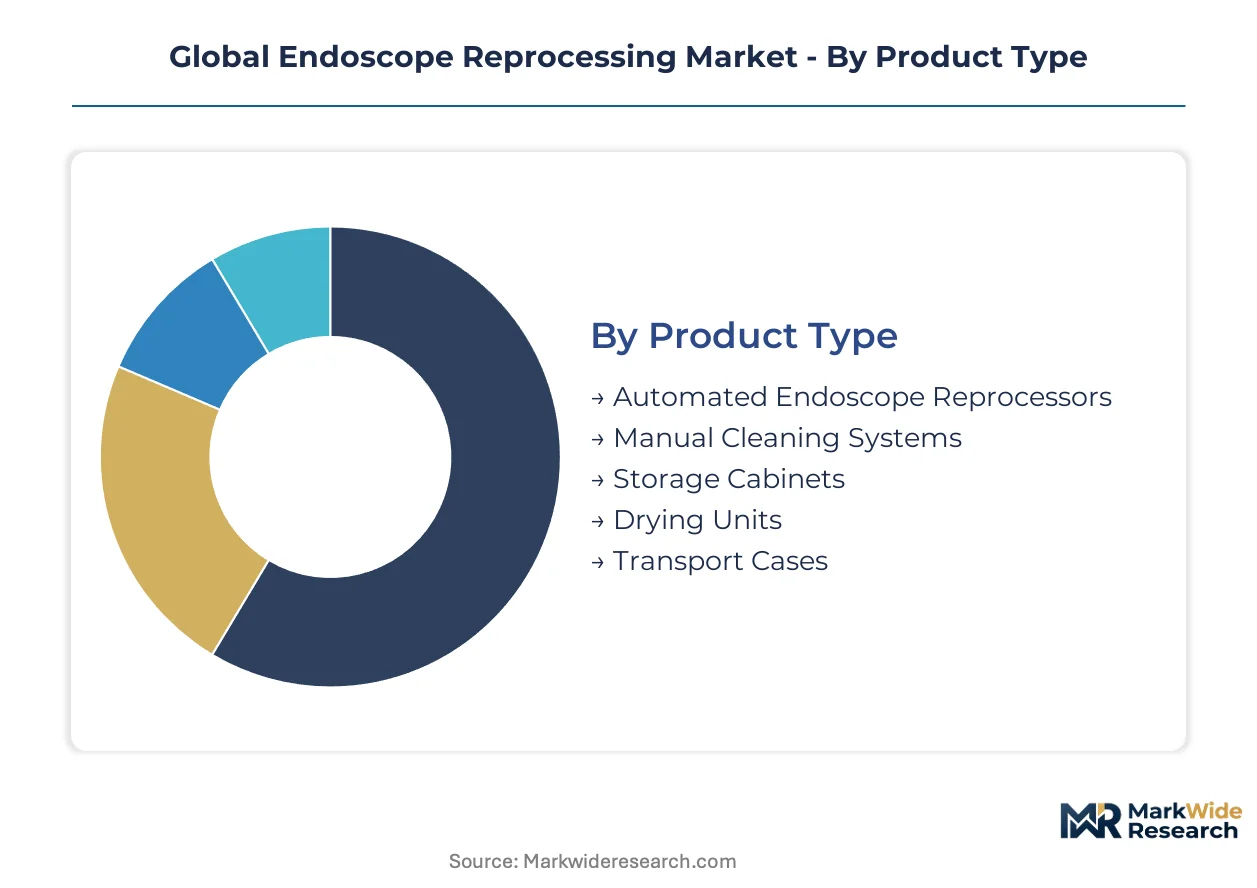
Endoscope reprocessing segmentation reveals how regulatory pressure and clinical workflow requirements fragment procurement decisions across healthcare systems. Each dimension captures distinct compliance obligations, capital intensity thresholds, and service contract structures that vendors must navigate.
Product Type:
FDA 510(k) clearance pathways and EPA disinfectant efficacy standards create divergent qualification burdens across equipment categories.
- Automated Endoscope Reprocessors:Closed-loop systems integrate leak testing, high-level disinfection, and rinse cycles under validated software control. US hospital systems in California and Texas are consolidating procurement through centralized sterile processing departments that demand ISO 15883-4 compliant units with automated chemistry dosing.
- Manual Cleaning Systems:Enzymatic soaking stations and brush-based luminal cleaning setups remain necessary for pre-cleaning and legacy scope compatibility. German hospital consortia specify manual systems as backup infrastructure for automated reprocessor downtime, particularly in Bavarian academic medical centers with mixed Olympus and Karl Storz scope fleets.
- Storage Cabinets:HEPA-filtered drying cabinets with timed forced-air circulation prevent post-reprocessing contamination.
- Drying Units:Dedicated forced-air and vacuum-assisted drying modules attach to reprocessor outputs or operate as standalone stations.
- Transport Cases:Sealed, leak-proof containers with biohazard labeling meet Joint Commission documentation requirements for soiled scope movement.
Automated Endoscope Reprocessors handle the majority of throughput; Drying Units are expanding most quickly on share as moisture-related contamination events drive protocol tightening.
Technology:
Cost tier differentiation separates capital-intensive platform technologies from attach-rate-driven consumable and monitoring categories.
- High-Level Disinfection:Peracetic acid and hydrogen peroxide chemistries achieve sporicidal efficacy against Mycobacterium tuberculosis and resistant viruses. Academic medical centers in Boston and Philadelphia are replacing glutaraldehyde-based legacy systems at accelerated depreciation schedules to meet OSHA permissible exposure limits.
- Contamination Monitoring Systems:ATP bioluminescence and protein residue testing devices provide point-of-use verification before scope release. Japanese quaternary hospitals in Tokyo and Osaka are piloting continuous monitoring integrations that feed data directly to infection control dashboards.
- Ultrasonic Cleaning:Cavitation-based pre-cleaning removes fixed bioburden from scope channels and instrument crevices.
- Enzymatic Cleaning:Protease-lipase-amylase formulations break down organic soils before disinfection cycles.
- Drying Technology:Forced-air, vacuum, and alcohol flush methods eliminate residual moisture that supports bacterial proliferation.
High-Level Disinfection commands the largest installed base investment; Contamination Monitoring Systems are climbing the fastest as traceability mandates harden.
Application:
Procedure volume and infection risk profiles determine reprocessing throughput requirements and validation stringency across clinical service lines.
- Gastroenterology Procedures:Colonoscopy and upper endoscopy generate the highest reusable scope utilization rates with documented transmission risks of carbapenem-resistant Enterobacteriaceae. US hospital endoscopy departments in Florida and New York are expanding automated reprocessor fleets to meet unannounced Joint Commission inspection protocols.
- Pulmonology Examinations:Flexible bronchoscopy presents unique channel complexity and biofilm formation risks in immunocompromised patient populations. Ambulatory surgery centers in Texas are adopting disposable bronchoscope alternatives that pressure reusable reprocessors to validate enhanced sterility assurance levels.
- Urology Diagnostics:Cystoscopy and ureteroscopy procedures require rigid and semi-rigid scope reprocessing with distinct drying protocols.
- ENT Inspections:Rigid sinus scopes and flexible laryngoscopes demand compact reprocessor footprints for office-based settings.
- Gynecology Evaluations:Hysteroscopy and colposcopy equipment reprocessing follows obstetric-specific quality management standards.
Gastroenterology Procedures absorb the greatest reprocessing capacity; Pulmonology Examinations are gaining share fastest as single-use competition forces validation upgrades.
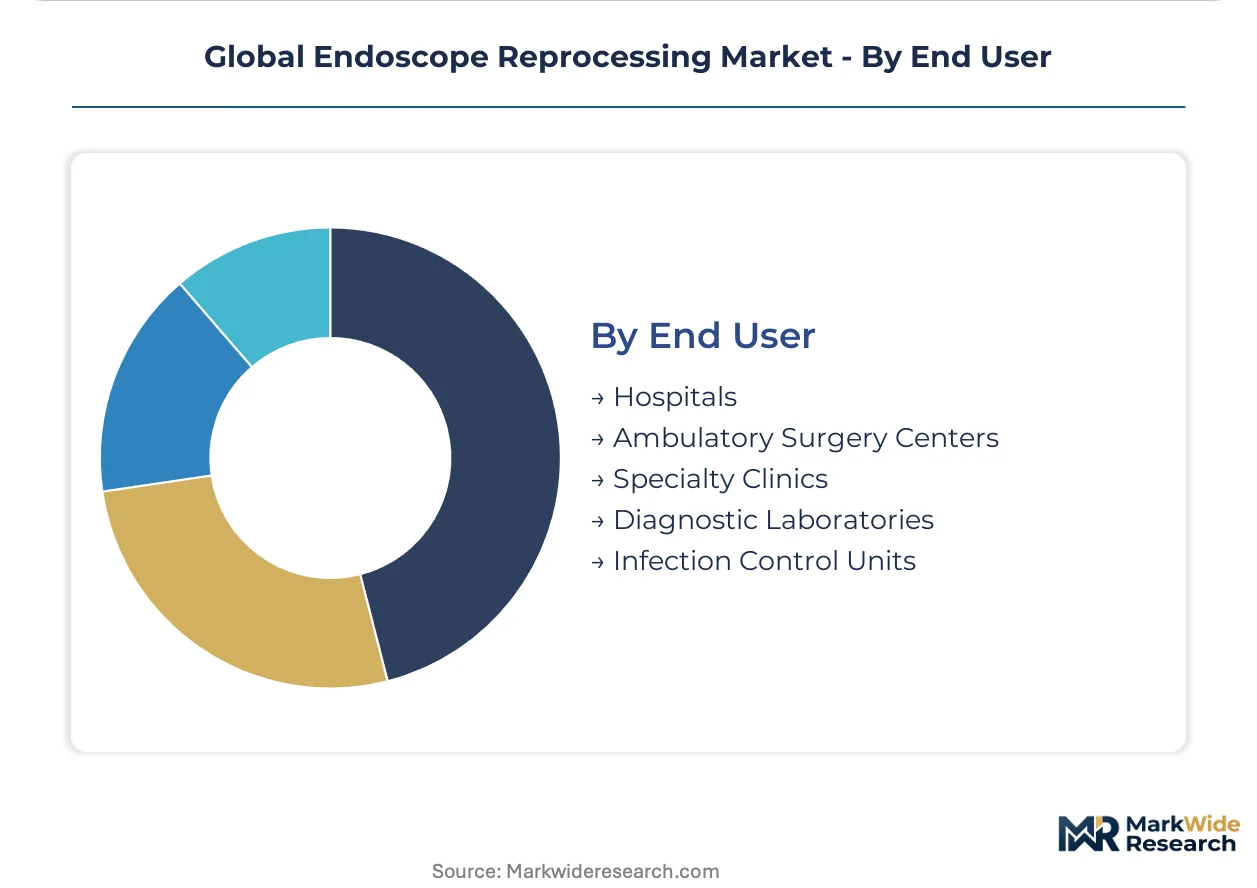
End User:
Customer type dictates capital availability, staff certification requirements, and service contract complexity.
- Hospitals:Integrated delivery networks operate centralized sterile processing departments with dedicated IAHCSMM-credentialed technicians and multi-line reprocessor inventories. German university hospitals in Heidelberg and Munich are demanding vendor-managed inventory agreements for peracetic acid consumables tied to cycle-count pricing.
- Ambulatory Surgery Centers:Limited square footage and lean staffing drive preference for compact, single-channel automated reprocessors with simplified interfaces. California and Arizona ASC chains are unbundling hardware and chemistry procurement to optimize total cost of ownership metrics.
- Specialty Clinics:Gastroenterology and urology single-specialty practices require scope-specific reprocessing with lower throughput than hospital settings.
- Diagnostic Laboratories:Research and reference lab endoscopy units prioritize contamination monitoring documentation for regulatory audit trails.
- Infection Control Units:Hospital epidemiology departments procure verification testing equipment and surveillance software independent of capital reprocessor acquisitions.
Hospitals deploy the dominant share of installed base capacity; Ambulatory Surgery Centers are expanding their reprocessing footprint fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automated reprocessing equipment reveal concentrated production clusters in Germany and the United States serving import-dependent hospital systems across Asia-Pacific and Latin America. Trade flows track regulatory stringency gradients, with FDA-cleared and CE-marked units commanding premium placement in markets lacking domestic manufacturing capacity.
United States
Joint Commission unannounced inspection protocols drive hospital capital expenditure on ISO 15883-4 compliant automated reprocessors. EPA disinfectant efficacy standards eliminate marginal chemistries, concentrating vendor qualification pools among established manufacturers. Boston and Philadelphia academic medical centers accelerate glutaraldehyde replacement cycles to meet OSHA permissible exposure limits.
Germany
University hospital procurement consortia in Heidelberg and Munich demand vendor-managed inventory agreements for peracetic acid consumables. EU MDR technical documentation requirements extend post-market surveillance obligations across washer-disinfector lifecycles. Bavarian sterile processing equipment manufacturing clusters supply integrated centralized department solutions spanning multiple clinical service lines.
Japan
Quaternary hospitals in Tokyo and Osaka pilot continuous contamination monitoring integrations feeding infection control dashboards. METI industrial standards align with PMDA device quality management requirements for imported reprocessing equipment. Domestic scope-and-reprocessor bundling patterns persist despite single-use endoscope competitive pressure.
India
Private hospital chains in Mumbai, Delhi, and Bangalore build endoscopy capacity faster than sterile processing infrastructure creates first-mover service contract opportunities. CDSCO import registration requirements for medical devices extend clearance timelines for automated reprocessor deployments. Diagnostic center expansion concentrates in metropolitan corridors with limited IAHCSMM-credentialed technician availability.
United Kingdom
NHS trust procurement frameworks emphasize total cost of ownership metrics separating hardware acquisition from chemistry supply agreements. MHRA vigilance reporting requirements track adverse events across reprocessor installed bases. London and Southeast England health systems consolidate sterile processing operations through centralized department models.
Global Endoscope Reprocessing Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment and consumable supply dimensions, producing a tiered structure where scale-driven platform vendors anchor premium positioning while regional fabricators capture service-intensive accounts. Three archetypes dominate: integrated scope-and-reprocessor bundlers, standalone automated reprocessor specialists, and chemistry-focused consumable suppliers. Competitive moves concentrate on M&A for sterile processing portfolio expansion and strategic partnerships for legacy scope compatibility adapter development.
Within the integrated systems tier, STERIS plc and Olympus Corporation exemplify divergent approaches to recurring revenue capture, with the former leveraging installed base automation for consumable attach rates and the latter anchoring competitive stance through bundled scope-reprocessor procurement contracts. Getinge AB occupies a position emphasizing centralized sterile processing department solutions that span multiple clinical service lines rather than single-modality equipment placement.
| Leading Market Players |
|---|
| STERIS plc |
| Olympus Corporation |
| Getinge AB |
| Ecolab Inc |
| ASP |
| Cantel Medical |
| HOYA Corporation |
| CONMED Corporation |
| Belimed AG |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance requirements gate both vendor qualification pools and price differentiation tiers across automated reprocessor procurement, concentrating premium positioning among established manufacturers while marginalizing uncertified competitors to commodity manual cleaning segments.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through multi-year service contracts that bundle automated reprocessor hardware with peracetic acid consumable supply. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15883-4 compliant units with integrated drying technology from basic chemistry-only systems. Pricing pressure stems from IDN supply chain executives unbundling hardware and chemistry agreements to optimize total cost of ownership metrics. Ambulatory surgery centers exhibit highest price sensitivity due to limited capital budgets, while German university hospitals demonstrate lowest sensitivity given vendor-managed inventory preferences.
Supply Chain Analysis
Germany and the United States anchor automated reprocessor manufacturing, with Bavarian sterile processing equipment clusters and Midwestern medical device production hubs supplying global hospital capital budgets. Nickel-price-sensitive stainless steel alloys and medical-grade fluoropolymers constitute critical input dependencies. Single-source vulnerability concentrates in southern German component fabricators serving North American OEM assembly operations. Distribution runs through hospital group purchasing organizations and regional equipment distributors with certified technician training obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in this market, as FDA and EU MDR validation timelines lock hospital procurement committees into incumbent vendor relationships with established clearance portfolios.
For Market Incumbents: Compound installed base advantages through backward integration into peracetic acid consumable manufacturing and accelerated adapter development for legacy scope compatibility. Single-use endoscope alternatives threaten reusable reprocessor volumes, requiring sterility assurance level upgrades to retain procurement contracts. Priority investment centers on AI-assisted leak detection modules that reduce manual inspection labor. For New Entrants and Emerging Players: Lead with contamination monitoring systems as the fastest-attaching growth vector, where traceability mandates outpace established vendor software development. Indian diagnostic center expansion presents the most penetrable geography given sterile processing infrastructure gaps in Mumbai, Delhi, and Bangalore. Go-to-market execution should emphasize service contract bundling over capital equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated reprocessor manufacturing as EU MDR documentation requirements extend post-market surveillance obligations. Long-term viability favors platforms with recurring consumable attach rates over standalone equipment vendors. Acquisition target archetype: chemistry-focused consumable suppliers with hospital formulary lock-in. Signal to watch: Joint Commission inspection frequency acceleration forcing capital replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Expedited clearance timelines capture hospital procurement windows before competitive reprocessor launches. |
| EU MDR Technical Documentation Investment | Post-market surveillance systems satisfy German procurement consortia demanding lifecycle traceability compliance. |
| Hospital System Partnership | Centralized sterile processing department consolidation in California and Texas creates volume leverage for multi-line contracts. |
| Software Companion Development | Continuous contamination monitoring integrations feed Japanese quaternary hospital infection control dashboards. |
| Reimbursement Strategy | Documentation protocols align with Joint Commission unannounced inspection mandates driving automated upgrades. |
Research Methodology
Initial hypotheses were tested against primary input from sterile processing department managers, biomedical engineers, hospital purchasing committee members, and GPO contracts managers and refined through secondary validation across FDA 510(k) filings, EPA disinfectant efficacy registrations, ISO 15883 compliance databases, and hospital procurement records. Bottom-up equipment shipment analysis triangulated against top-down healthcare capital expenditure surveys across the analysis window.
Variance-decomposition across product type, technology tier, clinical application, and end-user facility scale informed segment-level projections throughout the forecast period. CAGRs were derived from installed base replacement cycle compression and consumable attach rate trajectories. Industry-specific inputs incorporated Joint Commission inspection frequency patterns and single-use endoscope substitution elasticities.
Forecasts assume regulatory continuity in FDA clearance pathways and EU MDR enforcement; material policy shifts would require re-modeling. Specific risks include OSHA permissible exposure limit revisions for hydrogen peroxide chemistries and CDSCO import registration timeline extensions affecting Indian market deployment. Recalibration cycles align with material shifts in infection control mandate stringency and scope-and-reprocessor bundling patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
US Colonic Stents Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Endoscopy Device Market
Endoscopy
Single Use Bronchoscopes Market