
 Hydronic Radiators Market | 2026-2036
Hydronic Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Hydronic Radiators Market Analysis
Turkey's expanding radiator manufacturing base is rewriting supply dynamics for European contractors. Stelrad Limited leverages its British foundry network to sustain just-in-time delivery across Northern European housing projects. Zehnder Group differentiates through designer radiator portfolios that command premium positioning in Swiss and Austrian commercial developments. Purmo Group anchors its competitiveness via integrated valve and control systems that reduce installation labor for mechanical contractors.
Hydronic radiators are heat exchange devices constructed from steel, aluminum, cast iron, or composite materials, designed to distribute thermal energy from circulating hot water or steam into occupied spaces through convection and radiation; operating pressures typically range from 1.0 to 10 bar with output ratings measured in watts per meter or British thermal units per hour. These systems serve as terminal units in central heating architectures, converting fluid-borne energy into space heat with controllable flow regulation via thermostatic or motorized valves. Steel radiators dominate volume in European residential replacement cycles due to favorable cost-to-output ratios and compatibility with low-temperature heat pump circuits. Aluminum variants represent the fastest-growing product category, driven by lightweight handling, rapid thermal response, and corrosion-resistant surface treatments that suit renovation timelines in aging building stock. Cast iron retains margin concentration in heritage restoration and high-inertia applications where prolonged heat release outweighs first-cost sensitivity.
The EU Green Deal and F-Gas Regulation mandate efficiency thresholds that disqualify legacy boiler pairings and reward low-temperature hydronic designs compatible with heat pump sources. Ecodesign directives enforced by national market surveillance authorities in Germany, France, and Italy require minimum seasonal performance coefficients that reshape product development roadmaps. REACH compliance governs surface coating chemistries, limiting chromate pretreatments and redirecting investment toward powder-coated or epoxy-finished alternatives. Stakeholders must monitor how building performance standards evolve across member states and whether national renovation wave funding prioritizes radiator replacement alongside envelope improvements.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing a wholesale replacement of legacy boiler-radiator pairings across Central Europe, compressing product development cycles and rewiring procurement specifications toward low-temperature heat pump compatibility.
Growth Catalysts
- Heat pump integration mandates:The EU Green Deal requires seasonal performance coefficients that reward radiators engineered for sub-45°C flow temperatures, accelerating aluminum and low-mass steel adoption in German and Polish residential retrofits.
- Building renovation wave funding:National disbursement frameworks in Italy and France tie envelope improvements to heating system replacement, creating bundled demand for hydronic terminal units in multi-family housing stock.
- District heating network expansion:Copenhagen, Vienna, and Helsinki are extending fourth-generation low-temperature distribution loops that specify compact, responsive radiators over traditional cast iron configurations.
Market Restraints
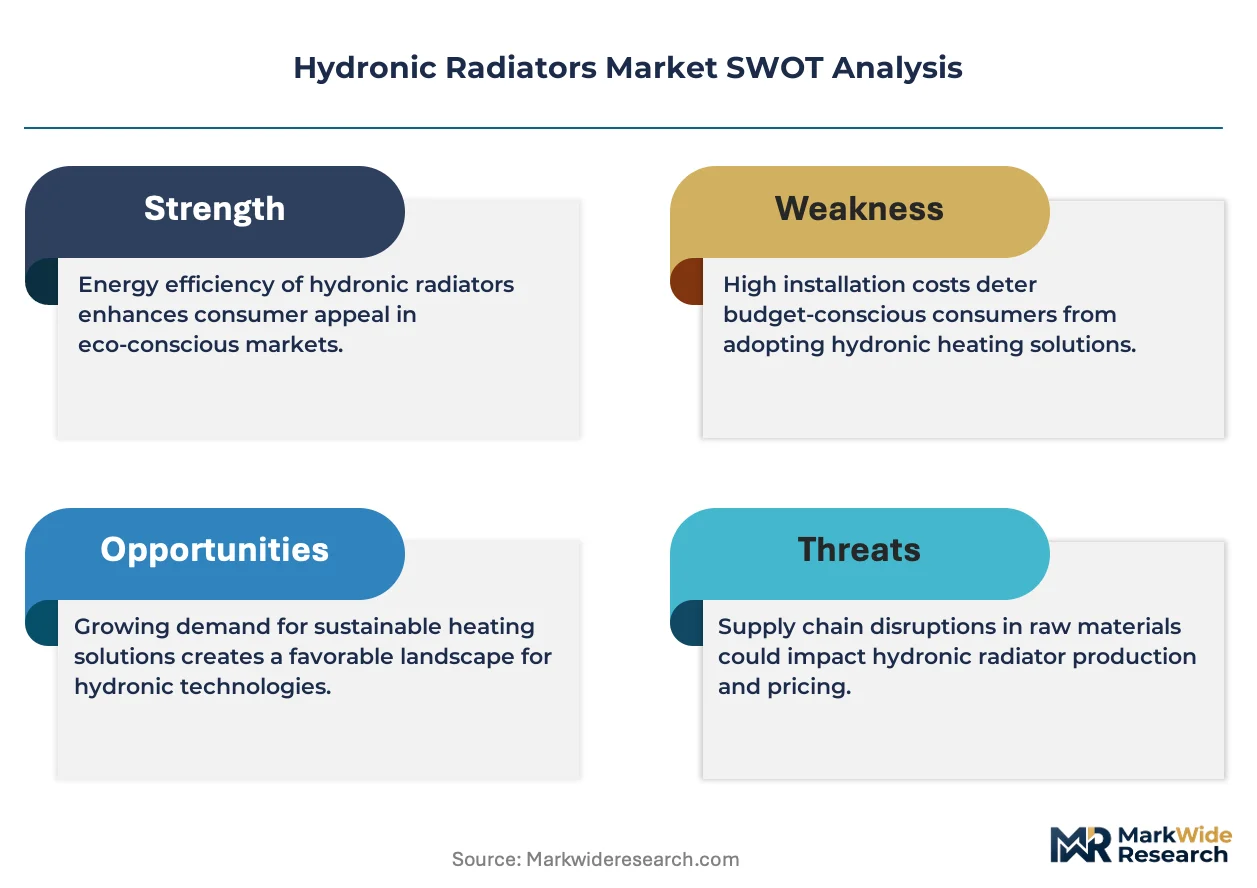
- Steel and aluminum price volatility:Input cost swings for flat-rolled steel and extruded aluminum profiles compress margin buffers for panel radiator manufacturers serving price-sensitive Central European contractors.
- Turkish supply concentration:Foundry and extrusion capacity clustering around Istanbul and Bursa creates single-source vulnerability for European distributors reliant on just-in-time replenishment of standard panel lines.
- Heat emitter substitution:Underfloor heating and fan coil units are capturing share in new Swiss and Austrian commercial construction where floor space optimization outweighs radiator first-cost advantages.
Strategic Opportunities
- Smart thermostatic valve convergence:Integration of IoT-enabled TRVs with building management systems opens premium positioning in Dutch and Belgian social housing digitization programs.
- Heritage restoration cast iron:France's Monument Historique classification and Italy's Superbonus incentives preserve demand for period-correct high-inertia radiators in protected building renovations.
- Polish and Romanian new-build penetration:Sub-15% heat pump penetration rates in these markets present first-mover advantage for low-temperature radiator portfolios ahead of anticipated Ecodesign tightening.
Industry Challenges
- Wet system commissioning expertise:Mechanical contractor shortages in balancing hydronic networks with variable-speed heat pumps delay project handoffs and generate callback costs.
- REACH coating compliance timelines:Chromate pretreatment phase-outs force reformulation of surface protection chemistries, requiring requalification cycles that extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydronic Radiators Market |
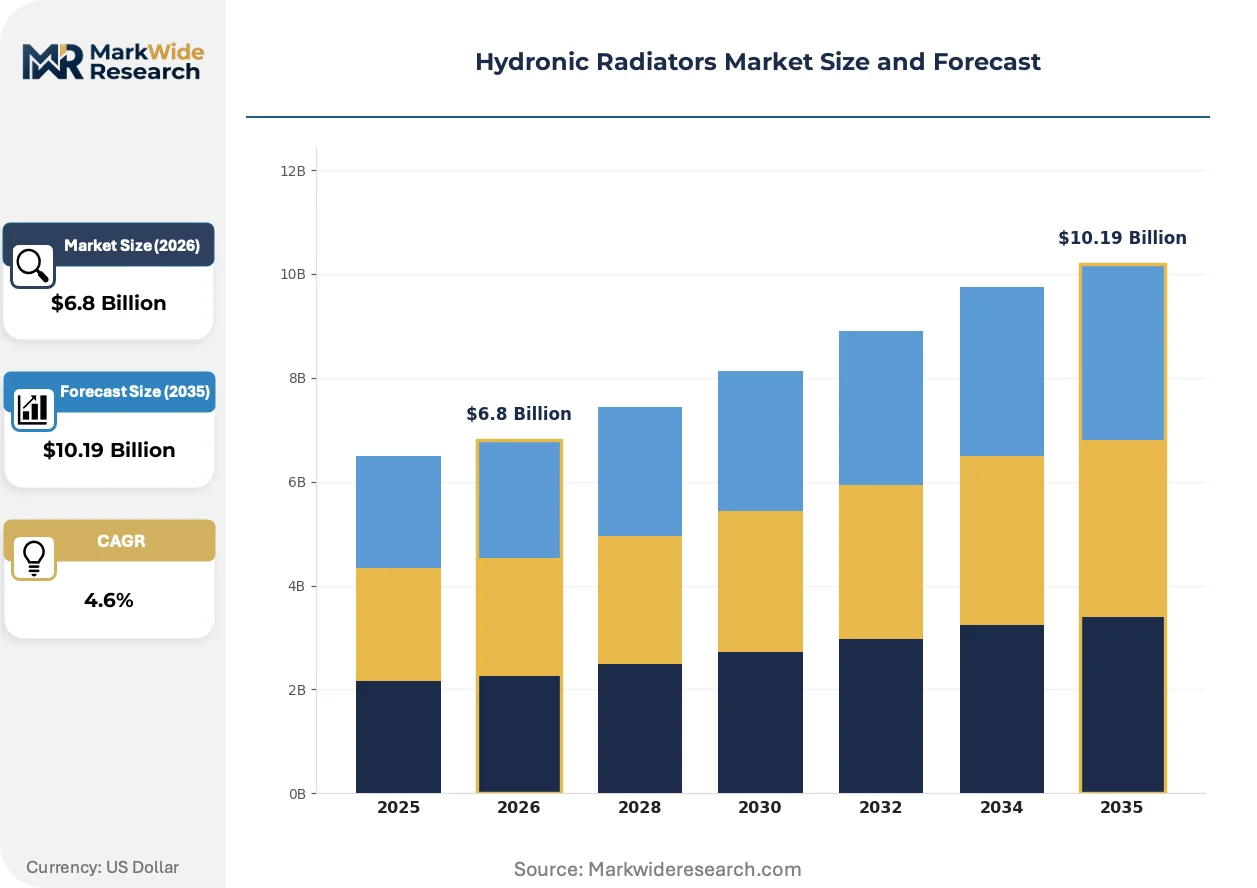
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Radiators, Aluminum Radiators, Cast Iron Radiators, Composite Radiators Application: Residential Heating, Commercial Heating, Industrial Heating, Agricultural Heating Installation Type: Wall-Mounted, Floor-Standing, Integrated, Portable Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributor Partnerships |
| Companies Covered | Stelrad Limited, Zehnder Group, Purmo Group, Runtal North America, Jaga, Ragaini Radiatori, De'Longhi Appliances, King Electric MFG. Co., Vogt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydronic Radiators Market Emerging Trajectories
Radiator technology is bifurcating between commodity panel efficiency and connected control integration, with material science and digitalization converging to redefine how thermal energy enters occupied spaces.
Low-temperature aluminum extrusion is digitizing building thermal response. These lightweight profiles achieve full output at 45°C flow temperatures, matching heat pump performance curves. German and Austrian housing associations are specifying them for EnerPHit retrofits. The technology is digitizing how quickly spaces respond to setpoint changes, compressing the gap between heat demand and supply.
REACH and the F-Gas Regulation are tightening surface treatment and refrigerant adjacent specifications. ECHA restrictions on hexavalent chromium pretreatments redirect coating investment toward epoxy-polyester powder systems. Italian manufacturers face the steepest compliance ramps as ANCCIA enforcement intensifies spot checks on imported radiators.
Specification authority is migrating from mechanical contractors to energy consultants. Dutch engineering firms now select terminal units based on dynamic building simulation outputs rather than rule-of-thumb sizing. This compresses contractor autonomy and elevates manufacturers with certified thermal modeling support capabilities.
Hydronic Radiators Market Segmentation
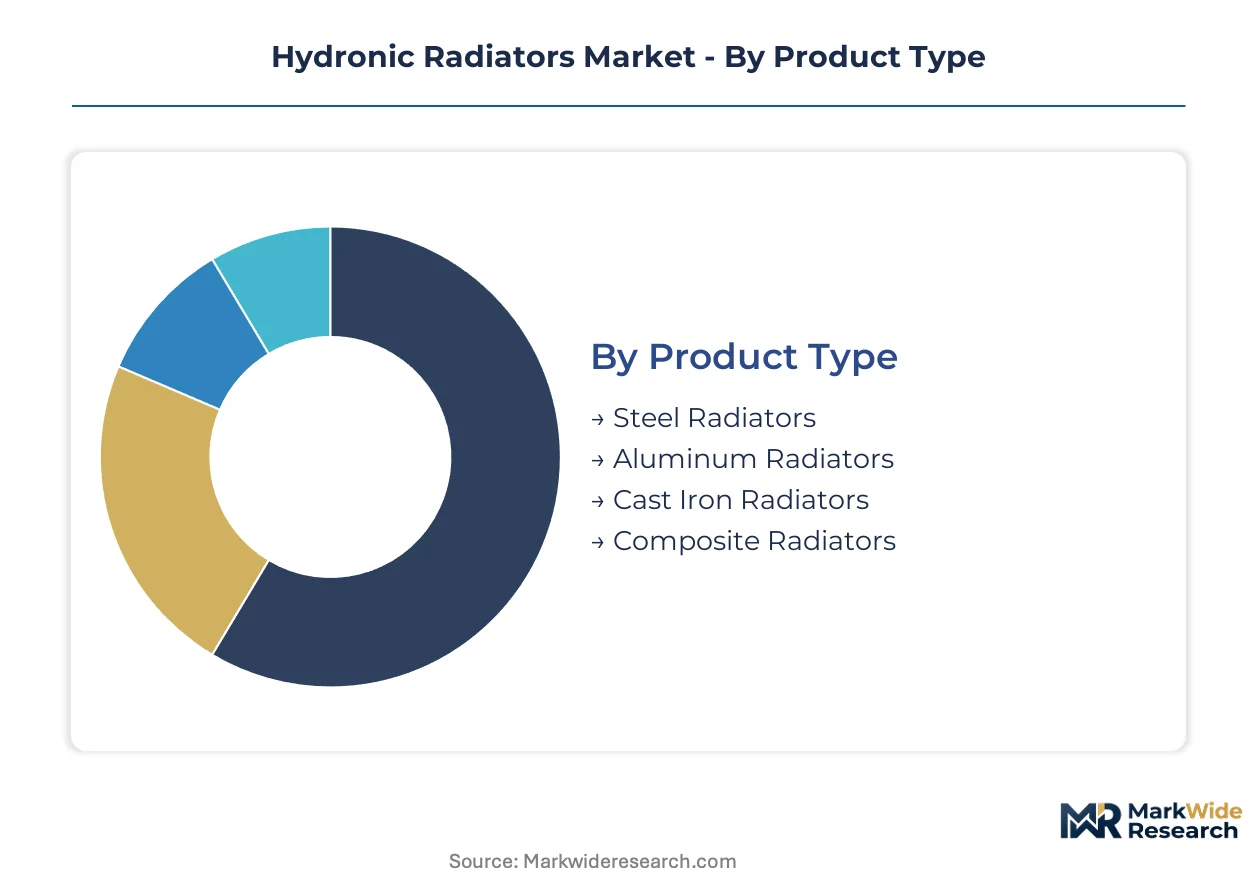
Material composition and installation flexibility determine specification authority across European heating retrofits. Segment boundaries shift as heat pump compatibility and smart control integration reshape procurement criteria.
Product Type:
Material science choices concentrate demand across distinct thermal performance and cost tiers.
- Steel Radiators:Pressed-steel panel and column constructions dominate replacement cycles in German and Polish residential stock due to favorable cost-to-output ratios and compatibility with low-temperature heat pump circuits. Contractors specify these for volume social housing projects where first-cost sensitivity outweighs thermal response speed.
- Aluminum Radiators:Extruded aluminum profiles with corrosion-resistant surface treatments achieve full output at sub-45°C flow temperatures, matching heat pump performance curves in Austrian and Swiss EnerPHit retrofits. Lightweight handling accelerates installation timelines in aging building renovations where labor constraints compress project schedules.
- Cast Iron Radiators:High thermal mass units retain demand in French Monument Historique restorations and Italian heritage building renovations where prolonged heat release outweighs first-cost sensitivity.
- Composite Radiators:Multi-material assemblies combining steel cores with aluminum fins or polymer casings serve niche applications requiring specific weight-to-output ratios.
The dominant share belongs to steel constructions, while aluminum variants are closing the gap fastest.
Application:
End-use thermal loads vary dramatically across occupancy patterns and envelope performance standards.
- Residential Heating:Single-family and multi-family dwellings in Germany, Italy, and Poland drive volume demand as EU Green Deal renovation funding accelerates replacement of legacy boiler-radiator pairings with low-temperature compatible terminal units.
- Commercial Heating:Office, retail, and hospitality spaces in Swiss and Austrian developments specify designer radiators with integrated valve systems that reduce commissioning complexity for mechanical contractors.
- Industrial Heating:Warehouses and manufacturing facilities require robust high-output units capable of maintaining setpoints in poorly insulated envelope conditions.
- Agricultural Heating:Greenhouse and livestock operations utilize corrosion-resistant constructions exposed to high-humidity environments.
Residential retrofits command the largest volume position, though commercial specifications carry the steepest premium differentiation.
Installation Type:
Mounting configurations respond to floor space constraints and renovation versus new-build timelines.
- Wall-Mounted:Standard panel and compact units attach to masonry or stud walls, preserving floor area in dense urban apartments common across Central European cities.
- Floor-Standing:Column and tubular designs serve heritage restorations and high-ceiling commercial lobbies where vertical presence complements architectural intent.
- Integrated:Built-in or recessed installations merge with facade elements in Dutch and Belgian low-energy new-builds pursuing minimal visual interruption.
- Portable:Mobile units with temporary connections address supplemental heating needs in seasonal or transitional occupancy patterns.
Wall-mounted configurations retain specification dominance, yet integrated solutions are expanding most quickly in stringent energy performance builds.
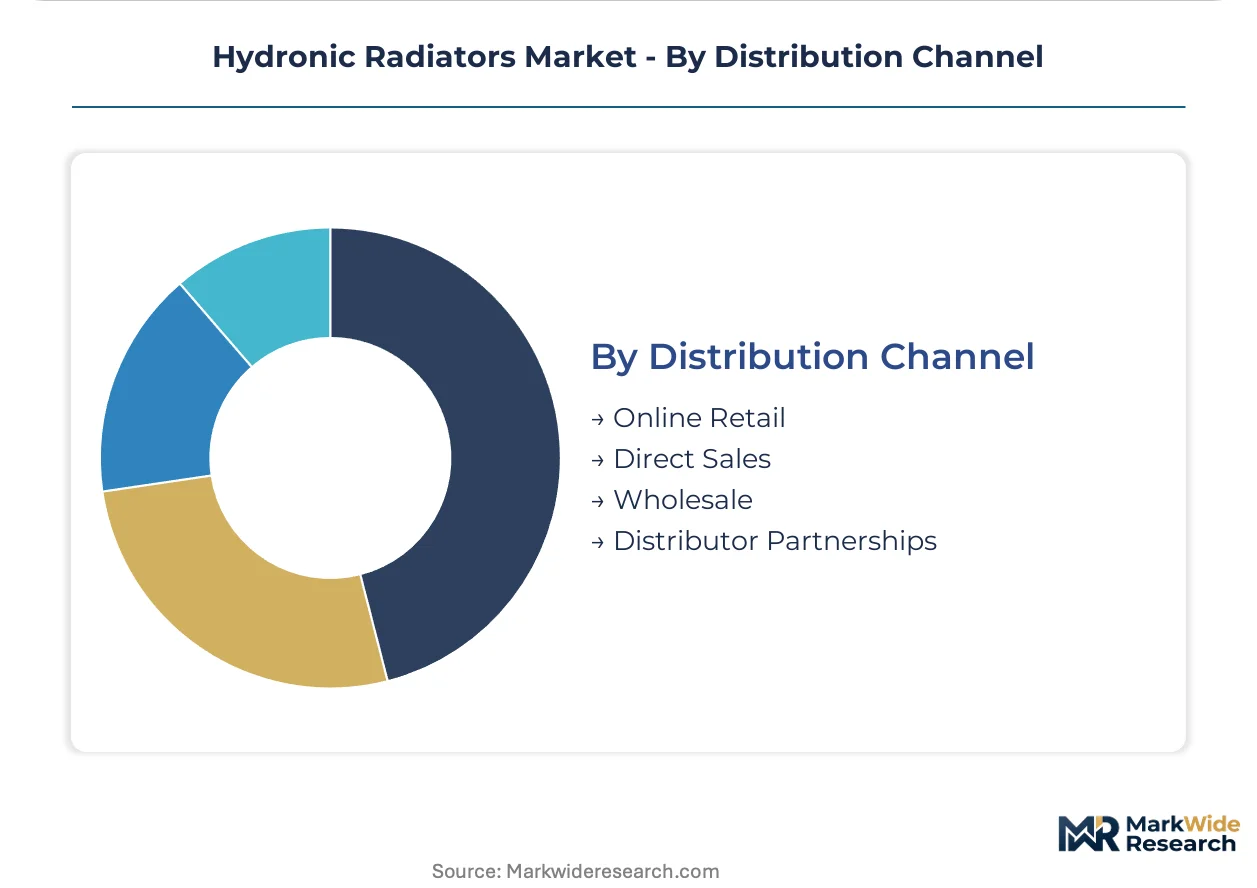
Distribution Channel:
Procurement pathways reflect project scale, technical support requirements, and inventory velocity needs.
- Online Retail:Digital platforms capture standard panel radiator sales to informed consumers and small contractors in markets with transparent sizing methodologies.
- Direct Sales:Manufacturer field teams serve large housing associations and developer portfolios requiring project-specific thermal modeling and bulk pricing frameworks.
- Wholesale:Regional plumbing and HVAC merchants maintain stocked inventory for emergency replacement and routine maintenance across contractor networks.
- Distributor Partnerships:Authorized dealer networks provide specification support, commissioning assistance, and warranty administration for complex integrated systems.
Wholesale channels handle the greatest transaction volume, while direct sales relationships are gaining share fastest in large-scale retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish foundry and extrusion capacity around Istanbul and Bursa supplies European distributors with standard panel lines, while German and Italian housing associations drive specification upgrades toward low-temperature heat pump compatibility.
Germany
Social housing associations in North Rhine-Westphalia and Bavaria are replacing legacy boiler-radiator pairings with aluminum and low-mass steel units compatible with heat pump circuits. The Federal Office for Economic Affairs and Export Control administers building renovation subsidies that tie envelope improvements to heating system replacement. Mechanical contractors in the Ruhr industrial cluster report compressed installation timelines as EnerPHit retrofits accelerate.
Italy
Superbonus incentives are preserving demand for period-correct cast iron radiators in Monument Historique-classified buildings while simultaneously funding modern low-temperature systems in multi-family housing. ANCCIA enforcement of Ecodesign directives intensifies spot checks on imported radiators at Milan and Bologna logistics hubs. Northern Italian manufacturers in Lombardy and Veneto are reformulating surface coating chemistries to meet REACH chromate phase-out deadlines.
Poland
Sub-15% heat pump penetration rates create first-mover positioning for low-temperature radiator portfolios ahead of anticipated Ecodesign tightening. The National Fund for Environmental Protection and Water Management channels EU cohesion funds into district heating network modernization in Warsaw and Kraków. Silesian industrial zones host assembly operations serving Central European contractor demand.
Turkey
Foundry capacity clustering around Istanbul and Bursa is rewriting supply dynamics for European distributors dependent on just-in-time replenishment. Turkish Standards Institute certification requirements for surface coatings are converging with REACH compliance timelines. The Marmara industrial corridor ships standard panel radiators to German and Polish wholesale channels.
Switzerland
Swiss and Austrian commercial developments specify designer radiators with integrated valve systems that reduce commissioning complexity for mechanical contractors. Swissmedic-adjacent building performance standards in Zurich and Geneva prioritize thermal modeling outputs over rule-of-thumb sizing. The Swiss Federal Office of Energy mandates seasonal performance coefficients that reward sub-45°C flow temperature designs.
Hydronic Radiators Market Vendor Landscape
Volume manufacturers and design-forward specialists split the market across distinct specification tiers. The vendor base organizes around three strategic archetypes: scale-driven panel producers serving social housing retrofits, premium-positioned design houses capturing commercial specifications, and integrated system suppliers bundling valves with terminal units. Competitive moves concentrate on geographic expansion into Polish and Romanian new-build markets and backward integration into foundry capacity to buffer input cost volatility.
Among British and Swiss-anchored fabricators, Stelrad Limited, Zehnder Group, and Purmo Group occupy positions representing these archetypes. Stelrad exemplifies the scale-driven panel producer with British foundry network utilization. Zehnder Group sits within the design-forward tier targeting premium commercial specifications. Purmo Group anchors the integrated system supplier archetype through valve and control bundling capabilities.
| Leading Market Players |
|---|
| Stelrad Limited |
| Zehnder Group |
| Purmo Group |
| Runtal North America |
| Jaga |
| Ragaini Radiatori |
| De'Longhi Appliances |
| King Electric MFG. Co. |
| Vogt |
| Others |
Supply Flow & Price Mechanics
The Istanbul-Rotterdam maritime corridor channels Turkish foundry output into Central European wholesale networks, with freight cost volatility amplifying price spreads between standard panel imports and domestically fabricated low-temperature units. Steel and aluminum input swings compress margin buffers at the manufacturing origin, while downstream contractors in Germany and Poland absorb differential pricing based on heat pump compatibility certification and installation support bundling.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across the hydronic radiator landscape. Three-tier pricing structure across premium, standard, and economy levels separates designer aluminum profiles with integrated IoT valve systems from commodity steel panels and uncoated import alternatives. Price differentiation hinges on CE-marked low-temperature performance certification and geographic proximity to district heating infrastructure hubs. Cost compression in the standard steel tier is intensifying because Turkish supply concentration exposes distributors to currency-adjusted import volatility. Social housing associations in Poland exhibit the highest price sensitivity, while Swiss commercial developers purchasing through direct manufacturer relationships show the least.
Supply Chain Analysis
Flat-rolled steel and extruded aluminum feedstock draws from Turkish foundry clusters around Istanbul and Bursa, German Ruhr industrial basin re-rollers, and Italian Lombardy surface treatment facilities. Raw material dependencies center on hot-dip galvanized steel coil, corrosion-resistant aluminum alloy billets, and REACH-compliant epoxy-polyester powder coatings. Single-source vulnerability concentrates in Turkish panel radiator extrusion capacity, where European distributors rely on just-in-time replenishment without viable short-term alternatives. Distribution runs through regional plumbing and HVAC merchant networks that maintain stocked inventory for emergency replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydronic radiator market functions as a service-attach opportunity where smart thermostatic valve subscriptions and predictive maintenance contracts expand faster than terminal unit hardware sales. Commissioning support and IoT-enabled thermal optimization layers generate recurring revenue streams that offset commodity margin erosion in the panel radiator core.
For Market Incumbents: Insulate core profitability by capturing backward integration into foundry capacity in Poland and Romania, buffering Turkish supply concentration risk. Secure REACH-compliant coating chemistry partnerships ahead of chromate pretreatment phase-outs. Deepen specification authority through certified thermal modeling support capabilities that preempt energy consultant intermediation. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian new-build residential markets where heat pump penetration remains below fifteen percent and low-temperature radiator portfolios face limited incumbent saturation. Target heritage restoration cast iron segments in France and Italy where Monument Historique classification preserves premium pricing power. Lead with integrated valve and control bundling that reduces mechanical contractor installation labor. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with under-optimized hydronic heating divisions lacking standalone scale. Long-term viability favors manufacturers with captive aluminum extrusion capacity and certified low-temperature product lines aligned with Ecodesign tightening trajectories. Watch Polish National Fund for Environmental Protection disbursement velocity as an inflection indicator for Central European retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive steel and aluminum supply buffers Turkish concentration risk for German and Polish distributors. |
| Smart Thermostatic Valve Convergence | IoT-enabled TRV integration opens Dutch and Belgian social housing digitization program specifications. |
| REACH-Compliant Coating Reformulation | Epoxy-polyester powder systems replace chromate pretreatments ahead of ECHA enforcement deadlines. |
| Heritage Restoration Cast Iron Preservation | Period-correct high-inertia units capture French Monument Historique and Italian Superbonus incentive flows. |
| Low-Temperature Heat Pump Compatibility Certification | Sub-45°C flow temperature designs qualify for Swiss Federal Office of Energy performance coefficients. |
Methodological Framework
A standing panel of mechanical contractors, housing association procurement directors, energy consultants, and foundry operations managers provided ongoing calibration across primary fieldwork and secondary source validation. Regulatory filings from the Federal Office for Economic Affairs and Export Control, ANCCIA enforcement bulletins, and Turkish Standards Institute certification databases anchored supply-side assessment. Bottom-up unit shipment analysis triangulated against top-down building renovation funding disbursement tracking.
Scenario-bracketing around heat pump penetration trajectories and Ecodesign tightening schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition, installation configuration, application type, and distribution channel structure. CAGRs derived from installed base replacement cycle analysis and district heating network expansion pipelines, with sensitivity testing against aluminum and steel price volatility assumptions.
Sensitivities concentrate around Turkish supply disruption events, REACH coating compliance timeline slippage, and mechanical contractor capacity constraints delaying retrofit project handoffs. Cross-checking against national building renovation wave funding appropriation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Wall Hung Boilers Market