
 Cooling Tower Market | 2026-2036
Cooling Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Tower Market Analysis
Multi-source procurement for engineered fill and drift eliminators is shifting toward vertically integrated tower fabricators with captive pultrusion capacity. Johnson Controls leverages its building automation integration to bundle cooling towers with chiller plant controls. Thermax anchors its position through in-house FRP manufacturing and captive supply of engineered polymer components. SPX Cooling Technologies differentiates via proprietary counterflow designs and regional service networks across North American industrial corridors.
A cooling tower is a specialized heat-rejection device that dissipates waste thermal energy to the atmosphere through evaporative or dry-bulb processes, typically operating with approach temperatures between 5°F and 15°F and circulating water volumes measured in thousands of gallons per minute. Its primary purpose centers on maintaining optimal operating temperatures for condensers, process equipment, and HVAC systems across power plants, refineries, and large commercial facilities. Wet towers dominate installed base volume due to lower capital cost and superior heat-rejection efficiency in humid climates, while hybrid configurations are gaining share in water-stressed regions where plume abatement and reduced blowdown matter. Fiberglass-reinforced polymer construction leads new order intake for corrosive chemical process environments, though concrete remains the structural standard in utility-scale power generation.
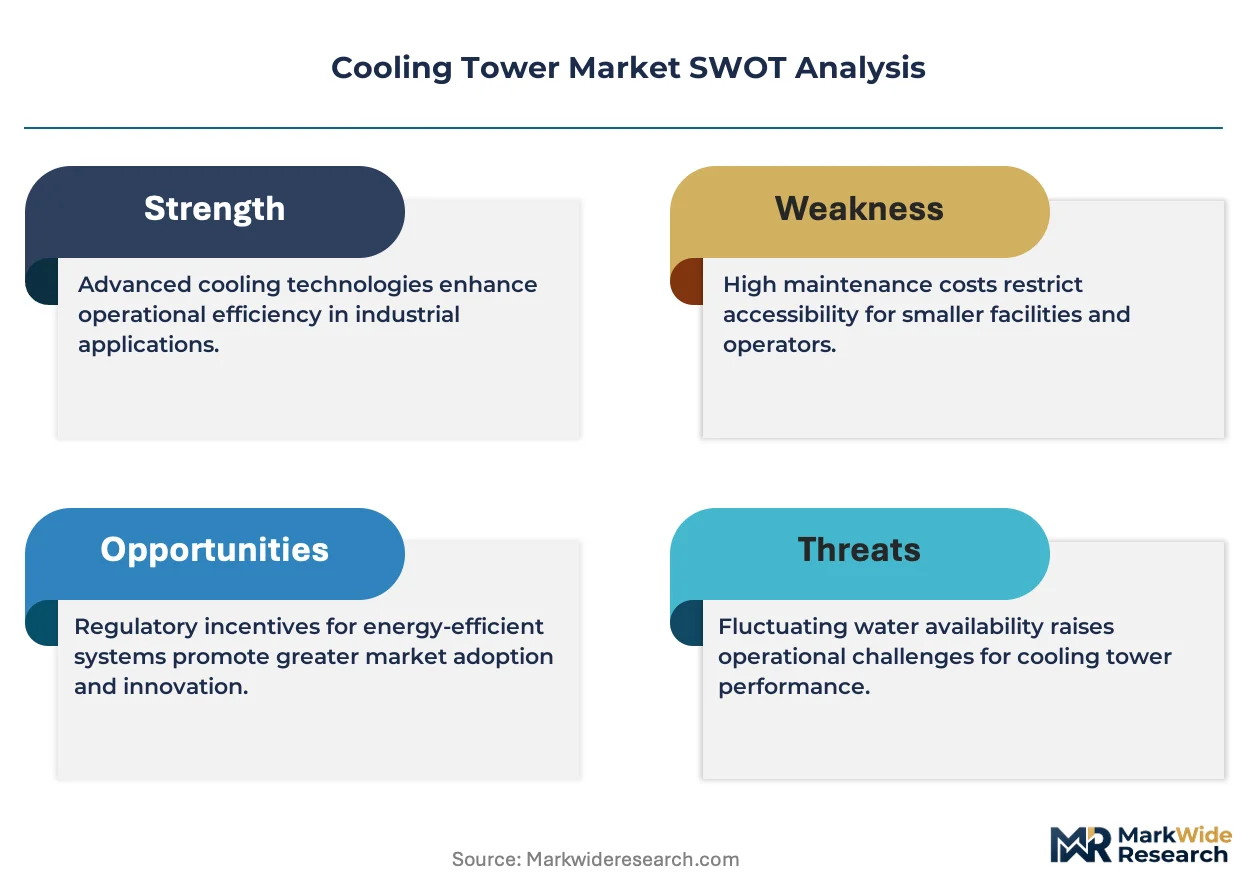
The U.S. EPA enforces Clean Water Act cooling water intake rules that restrict once-through systems and mandate closed-cycle retrofits, directly expanding addressable demand for mechanical-draft towers. China's Ministry of Ecology and Environment applies dual carbon goals and GB energy-efficiency standards that penalize older splash-fill designs while incentivizing film-fill and variable-speed fan upgrades. India's Central Electricity Authority mandates specific water-consumption benchmarks for thermal plants that favor hybrid and dry cooling architectures. Stakeholders must monitor evolving discharge-permit thresholds and efficiency benchmarks across these jurisdictions to align product portfolios with compliance-driven replacement cycles.
Market Dynamics
Closed-cycle cooling mandates under the U.S. EPA's Clean Water Act Section 316(b) are forcing thermal power operators toward mechanical-draft retrofits, while China's provincial energy commissions accelerate efficiency upgrades across industrial zones. These dual regulatory pressures are compressing replacement cycles and reshaping supplier order books.
Growth Catalysts
- Film-fill technology:China's GB energy-efficiency standards penalize splash-fill designs, driving demand for high-efficiency film-fill configurations in Jiangsu and Shandong industrial corridors.
- Hybrid tower architectures:India's Central Electricity Authority water-consumption benchmarks for thermal plants favor hybrid and dry cooling systems over once-through configurations.
- FRP material substitution:Chemical process operators in the U.S. Gulf Coast and Germany's Ruhr Valley specify fiberglass-reinforced polymer for corrosion resistance in aggressive environments.
Market Restraints
- Pultrusion capacity concentration:Engineered fill and drift eliminator supply concentrates among captive FRP manufacturers, creating input bottlenecks for independent fabricators.
- Concrete structural standards:Utility-scale power generation maintains concrete tower specifications despite FRP advances, limiting material substitution in the largest project category.
- Water-stress geography limits:Wet tower deployment faces restrictions in drought-prone regions, constraining addressable demand despite superior heat-rejection efficiency.
Strategic Opportunities
- Variable-speed fan retrofits:China's dual carbon goals incentivize motor and drive upgrades in existing installed base across provincial industrial zones.
- Plume abatement systems:Water-stressed regions in the southwestern United States and Australia specify hybrid configurations with visible plume reduction.
- Building automation integration:Chiller plant control bundling creates service attachment opportunities in commercial HVAC segments.
Industry Challenges
- Commissioning complexity:Hybrid and dry cooling architectures require specialized thermal performance verification extending project handover timelines.
- Cross-jurisdictional compliance:Multinational operators must reconcile EPA discharge permits with China's MEE effluent standards and EU F-Gas Regulation for refrigerant-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Tower Market |
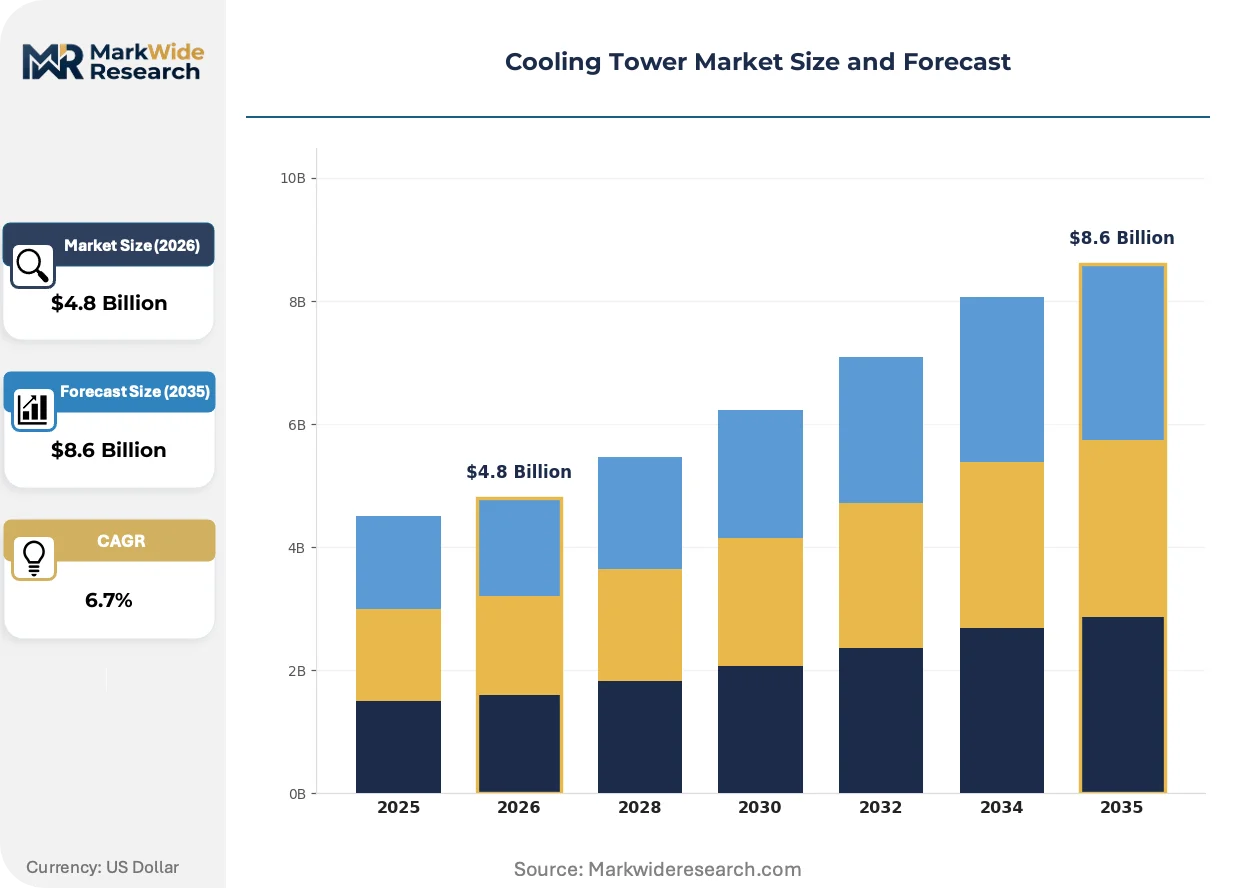
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet, Dry, Hybrid, Modular End User: Power Generation, HVAC, Manufacturing, Petrochemical Material: Fiberglass, Steel, Concrete, Plastic Application: Industrial, Commercial, Agricultural, District Cooling |
| Companies Covered | Johnson Controls, Thermax, SPX Cooling Technologies, Paharpur Cooling Towers, Hamon & Cie International, Baltimore Aircoil Company, ENGIE, Enexio, EVAPCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Tower Market Emerging Trajectories
Fan and drive technology is modularizing to enable site-specific configuration without custom engineering, while regulatory pressure on water consumption intensifies across major thermal power markets. These forces are compressing product development cycles and expanding the serviceable addressable market for upgrade solutions.
Counterflow mechanical-draft systems are modularizing through standardized cell configurations that allow capacity scaling in 500-ton increments. Power utilities in Texas and Florida specify these pre-engineered modules to reduce field construction duration. The approach is compressing project timelines from eighteen months to under twelve for brownfield retrofits.
The U.S. EPA enforces Clean Water Act Section 316(b) rules that restrict once-through cooling water intake structures at existing thermal plants. Operators must install closed-cycle mechanical-draft towers or hybrid alternatives to maintain discharge permits. The regulation most affects baseload coal and nuclear facilities in the Ohio River Valley and Great Lakes regions.
Lifecycle service contracting is displacing equipment-only procurement in utility and refining segments. Operators in Saudi Arabia and the UAE now specify fifteen-year performance guarantees bundling fill replacement, fan maintenance, and water treatment. The shift concentrates supplier relationships among vertically integrated tower fabricators with regional service networks.
Cooling Tower Market Segmentation
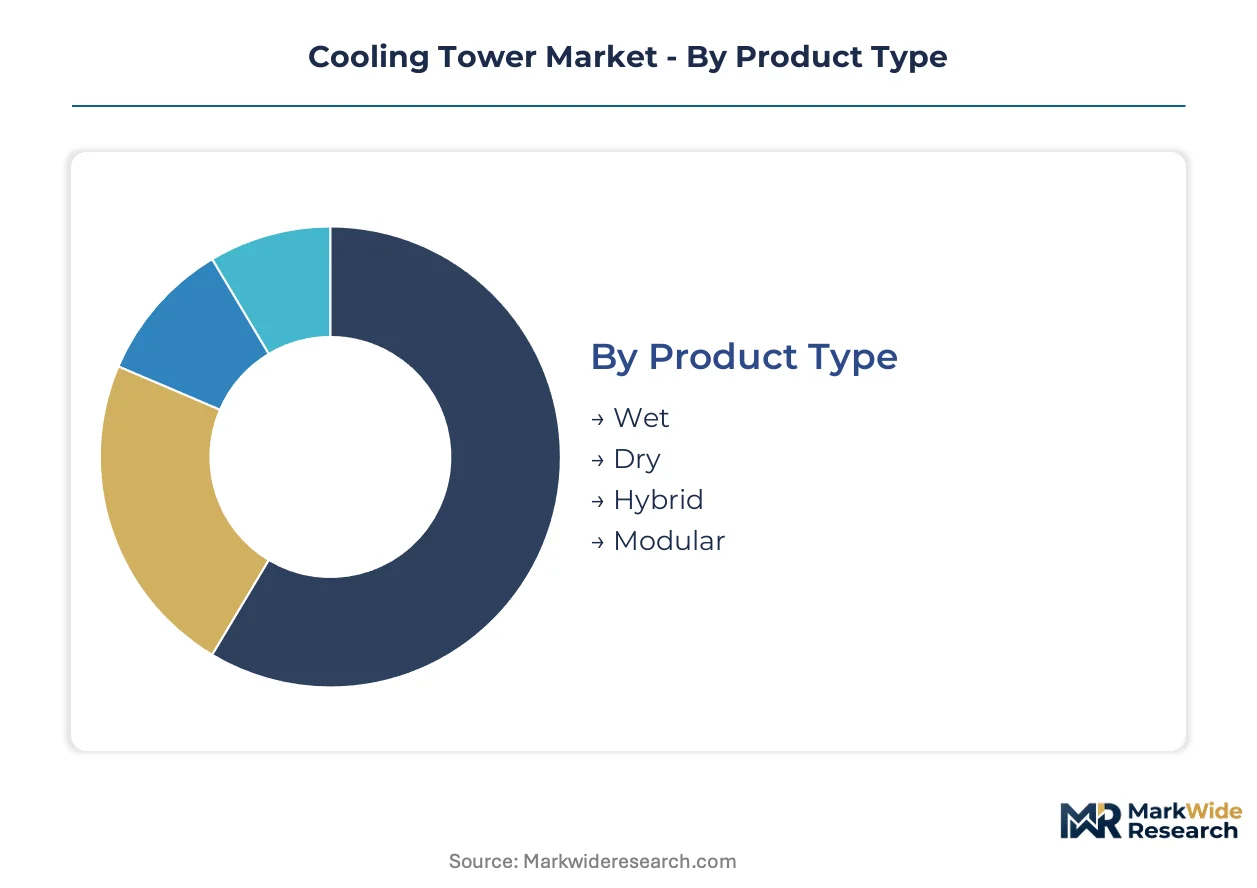
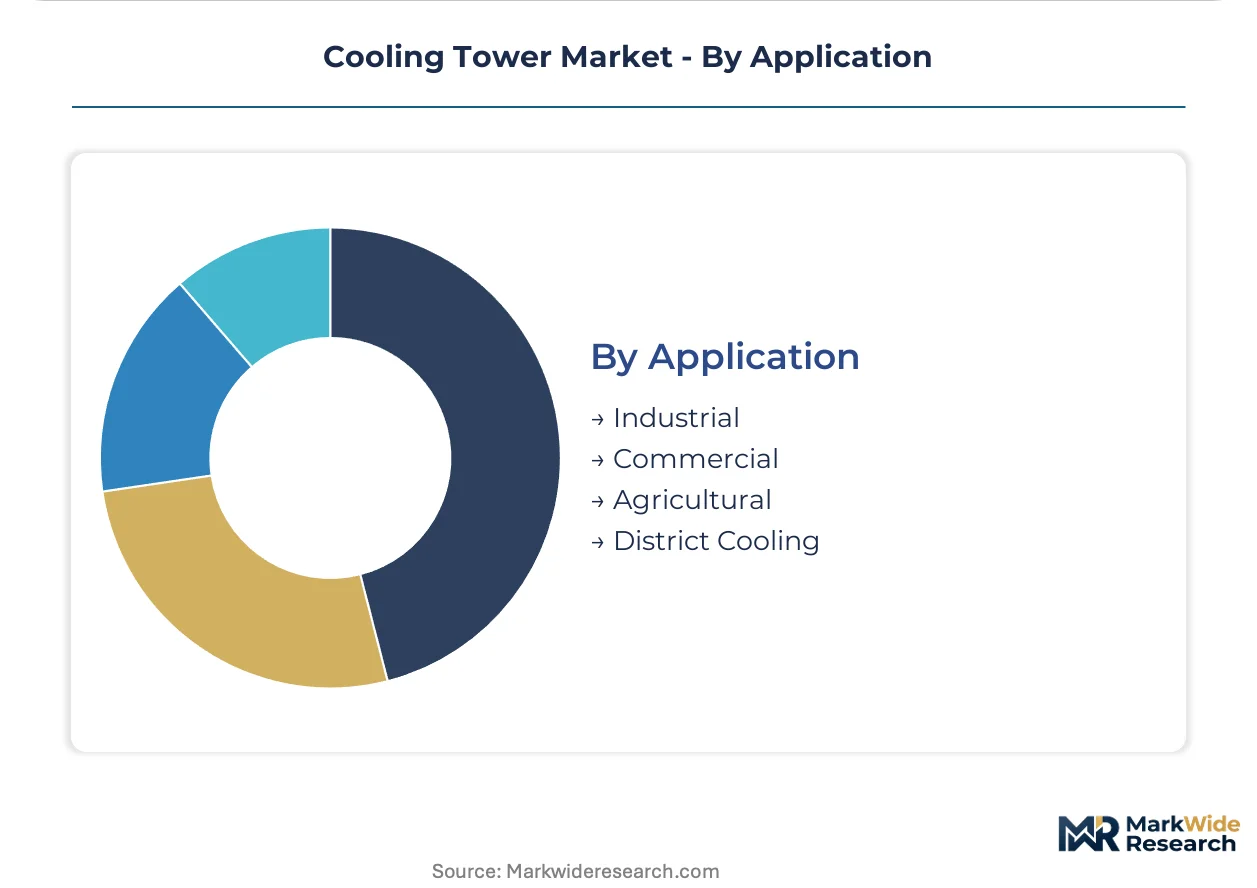
Cooling tower procurement patterns diverge sharply between capital-intensive utility retrofits and standardized commercial HVAC installations. Segmentation reveals how material specifications, thermal performance requirements, and regulatory compliance timelines reshape supplier positioning across end-use categories.
Product Type:
Wet towers command the largest installed base volume, while hybrid configurations capture premium pricing in water-stressed geographies.
- Wet:Evaporative heat rejection through direct water-to-air contact delivers superior thermal efficiency in humid climates. Power utilities in the Ohio River Valley and Great Lakes regions specify wet mechanical-draft designs to meet EPA Clean Water Act Section 316(b) closed-cycle mandates.
- Hybrid:Combined wet-dry operation reduces visible plume and blowdown discharge. Municipal utilities in Arizona and Nevada specify hybrid architectures to maintain discharge permits under severe drought conditions.
- Dry:Air-cooled designs eliminate evaporative losses entirely. Saudi Arabia's thermal plants deploy dry cooling to comply with national water-conservation benchmarks.
- Modular:Pre-engineered cell configurations enable capacity scaling in standardized increments. Texas power operators specify modular counterflow systems to compress brownfield retrofit timelines.
Mature deployment sits with wet towers across baseload thermal infrastructure. Newer deployment is concentrated in hybrid systems addressing water-stress geography limits.
End User:
Power generation dominates project value, while HVAC delivers volume through standardized commercial specifications.
- Power Generation:Utility-scale thermal plants require engineered concrete structures circulating thousands of gallons per minute. China's provincial energy commissions mandate efficiency upgrades across coal and combined-cycle installations in Jiangsu and Shandong corridors.
- HVAC:Commercial building automation integration bundles cooling towers with chiller plant controls. Large facilities in Florida and Texas specify packaged mechanical-draft units for district cooling networks.
- Manufacturing:Process cooling for heavy industry demands corrosion-resistant FRP construction. Germany's Ruhr Valley chemical clusters specify fiberglass-reinforced polymer for aggressive environments.
- Petrochemical:Refinery operations require specialized metallurgy for high-temperature hydrocarbon service. U.S. Gulf Coast refiners prioritize drift eliminator performance to protect downstream catalyst beds.
Replacement cycles concentrate in power generation under regulatory pressure. Fastest expansion trajectory belongs to HVAC bundling with building automation platforms.
Material:
Concrete maintains structural dominance in utility-scale projects, while FRP substitution accelerates in corrosive process environments.
- Fiberglass:Pultruded FRP components resist chemical attack and biological fouling. Chemical process operators in the U.S. Gulf Coast specify fiberglass-reinforced polymer fill and casing for sulfuric acid exposure.
- Concrete:Reinforced concrete hyperbolic shells support the largest thermal loads. China's utility-scale installations maintain concrete specifications despite FRP material advances in smaller capacities.
- Steel:Galvanized structural members serve moderate-duty commercial applications. Standardized HVAC towers in North American commercial corridors specify coated steel for cost-sensitive procurement.
- Plastic:Engineered polymer fill and drift eliminators optimize heat transfer surface area. Film-fill configurations in India's thermal plants replace legacy splash-fill under CEA water-consumption benchmarks.
Structural standards anchor concrete in the largest project category. Material substitution is climbing the fastest in FRP for chemical process corrosion resistance.
Application:
Industrial specifications drive engineering complexity, while commercial applications standardize through modular product platforms.
- Industrial:Process-critical cooling demands redundant capacity and specialized metallurgy. Refineries in the UAE specify fifteen-year lifecycle service contracts bundling fill replacement and fan maintenance.
- Commercial:Building-scale HVAC integration prioritizes compact footprint and acoustic control. Johnson Controls leverages automation integration to bundle tower and chiller plant controls.
- Agricultural:Greenhouse and livestock operations specify smaller wet towers for climate control. California's Central Valley operators deploy evaporative cooling for temperature-sensitive crop production.
- District Cooling:Centralized chilled water distribution serves multiple buildings through underground piping. District cooling networks in Saudi Arabia and the UAE specify large-field modular configurations.
Service attachment concentrates in industrial lifecycle contracting. Standardized deployment is expanding most quickly in commercial building automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FRP pultrusion feedstock from Jiangsu and Shandong provinces anchors Asia-Pacific tower fabrication. Concrete aggregate from the Ohio River Valley underpins North American utility-scale construction. Specialized drift eliminator polymers concentrate in Germany's Ruhr industrial corridor.
United States
Thermal plant retrofits in the Ohio River Valley and Great Lakes regions drive mechanical-draft demand. EPA Clean Water Act Section 316(b) mandates closed-cycle cooling for existing baseload coal and nuclear facilities. Texas power operators specify modular counterflow systems to compress brownfield project timelines below twelve months.
China
Provincial energy commissions in Jiangsu and Shandong mandate efficiency upgrades across coal and combined-cycle installations. The Ministry of Ecology and Environment applies dual carbon goals and GB energy-efficiency standards that penalize legacy splash-fill designs. Yangtze River Delta industrial zones accelerate film-fill and variable-speed fan retrofits.
Germany
Ruhr Valley chemical clusters specify corrosion-resistant FRP construction for aggressive process environments. The EU F-Gas Regulation shapes refrigerant-based cooling alternatives alongside traditional evaporative systems. North Rhine-Westphalia process operators prioritize drift eliminator performance to protect downstream catalyst beds.
India
Central Electricity Authority water-consumption benchmarks favor hybrid and dry cooling architectures over once-through configurations. The PLI scheme supports domestic manufacturing of engineered polymer components. Gujarat and Maharashtra thermal corridors deploy film-fill replacements under national efficiency mandates.
Saudi Arabia
National water-conservation benchmarks drive dry cooling deployment across thermal infrastructure. The country's national environmental regulator enforces discharge-permit thresholds that restrict evaporative losses. Eastern Province utilities specify fifteen-year lifecycle service contracts bundling fill replacement and fan maintenance.
Cooling Tower Market Vendor Landscape
Global majors compete with regional champions across engineering capabilities and service network density. The supplier base organizes around vertically integrated fabricators with captive FRP manufacturing, diversified industrial conglomerates with building automation platforms, and specialized cooling equipment pure-plays. Three archetypes dominate: captive-pultrusion specialists, automation-integrated providers, and regional service-network operators. Competitive moves concentrate on backward integration into engineered fill production and geographic expansion of maintenance contracting capabilities.
Among diversified industrial conglomerates, Johnson Controls exemplifies the automation-integrated archetype through building systems bundling. Thermax represents the captive-manufacturing model with in-house FRP and polymer component production. SPX Cooling Technologies anchors the specialized pure-play tier with regional service networks across North American industrial corridors.
| Leading Market Players |
|---|
| Johnson Controls |
| Thermax |
| SPX Cooling Technologies |
| Paharpur Cooling Towers |
| Hamon & Cie International |
| Baltimore Aircoil Company |
| ENGIE |
| Enexio |
| EVAPCO |
| Others |
Supply Flow & Price Mechanics
Pultrusion specialists in Jiangsu and Shandong provinces anchor engineered fill production, and labor-cost differentials between these captive manufacturers and independent fabricators drive spreads between premium bundled-service tiers and unbundled equipment-only procurement. Pricing stratifies across premium, standard, and economy tiers based on warranty coverage depth and regional service network density.
Pricing Analysis
Warranty and service-bundling terms separate premium tiers from unbundled equipment-only procurement. Project-based pricing dominates utility-scale retrofits, while standardized HVAC towers transact on per-unit contracts. Price differentiation rests on certification grade and vertical integration depth. Cost compression in economy tiers intensifies because independent fabricators lack captive pultrusion capacity. Commercial HVAC buyers exhibit highest price sensitivity; utility operators prioritize lifecycle performance guarantees over upfront capital cost.
Supply Chain Analysis
ISO 9001 and ASME certification requirements gate entry for engineered fill and drift eliminator suppliers. Geographic supply concentrates in China, India, and Germany. Raw material dependencies center on fiberglass roving, engineered polymer resins, and concrete aggregate. Single-source vulnerability concentrates in pultruded FRP components from Jiangsu-based manufacturers. Distribution runs through EPC contractors for utility projects and regional HVAC distributors for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained. Captive pultrusion capacity in China's Yangtze River Delta props pricing power for vertically integrated fabricators against input-starved independents.
For Market Incumbents: Acquire regional service network assets to defend against lifecycle-contracting displacement. Johnson Controls exemplifies automation-integrated bundling that threatens pure-play equipment margins. Backward integration into engineered polymer fill production secures input access against Jiangsu supply bottlenecks. For New Entrants and Emerging Players: Modular counterflow technology offers a technology-first wedge into Texas and Florida brownfield retrofit markets. White-space concentrates in plume-abatement hybrid configurations for Arizona and Nevada municipal utilities. Variable-speed fan retrofits in China's provincial industrial zones present the most penetrable installed-base opportunity. Partner with EPC contractors possessing EPA Section 316(b) compliance expertise to accelerate utility market entry. For Investors and Strategic Acquirers: Re-rating potential sits with captive-pultrusion specialists given regulatory compression of replacement cycles. Long-term viability favors fabricators with in-house FRP manufacturing and fifteen-year service contracting capabilities. Target acquisition archetype: regional champions with dense maintenance networks in Ohio River Valley or Great Lakes thermal corridors. Watch for EPA discharge-permit enforcement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Fill | Captive pultrusion capacity insulates against Jiangsu supply bottlenecks and secures margin control. |
| Lifecycle Service Contracting | Fifteen-year performance guarantees bundling fan maintenance and fill replacement lock in Saudi and UAE utility relationships. |
| Modular Counterflow Product Platform | Standardized 500-ton cell configurations compress Texas brownfield retrofit timelines below twelve months. |
| Building Automation Integration | Chiller plant control bundling creates attachment opportunities in Florida and Texas district cooling networks. |
| Hybrid Tower Architecture Development | Plume-abatement designs address Arizona and Nevada discharge-permit restrictions under drought conditions. |
Methodological Framework
Multi-period observation of EPA enforcement patterns, Chinese provincial energy commission mandates, and Indian CEA water-consumption benchmarks anchored the trend analysis, supplemented by interviews with thermal plant engineering directors, cooling tower procurement leads at U.S. Gulf Coast refineries, EPC contractors specializing in power sector retrofits, and aftermarket service heads at regional fabricators. Secondary validation drew from EPA discharge permit databases, China's MEE effluent standard filings, FERC interconnection queues, and SEC 10-K equipment supplier disclosures. Bottom-up project pipeline tracking triangulated against top-down regulatory mandate sizing.
Input-output matrices modeled capacity additions, replacement cycles, and efficiency upgrade mandates across wet, hybrid, dry, and modular product configurations. Segmentation dimensions included product type, end-use category, material specification, and regional regulatory framework. CAGRs were derived from regression analysis of historical procurement patterns against compliance-driven replacement timelines. Industry-specific forecast inputs incorporated thermal plant retirement schedules and GB standard enforcement trajectories.
Several conditions sit outside the modeled scope, including technological disruption from dry cooling cost parity breakthroughs and abrupt shifts in EPA enforcement intensity. Forecasts reflect documented assumptions regarding regulatory timeline adherence and material cost trajectories. A model refresh is warranted upon material change in Clean Water Act Section 316(b) implementation pace or Chinese dual carbon goal acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Air Conditioner Quilt Market