
 Strip Warmer Market | 2026-2036
Strip Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
Strip Warmer Market Insights
Procurement strategy from single-source to multi-source supply is shifting among large foodservice equipment distributors. Hatco Corporation leverages its vertical integration in heating element manufacturing to sustain margin control across North American channels. Nemco Food Equipment Ltd. competes through specialized compact designs for countertop installations. Vollrath Company anchors its position with stainless steel fabrication capabilities that extend into adjacent holding equipment categories.
A strip warmer is an electrically or gas-powered radiant heating device, typically employing calrod elements or infrared quartz tubes operating at surface temperatures between 140°F and 185°F, designed to maintain prepared food at safe serving temperatures without continued cooking. Electric strip warmers dominate institutional installations where ventilation constraints preclude gas combustion, while infrared warmers command premium positioning in exhibition cooking environments where visible heat sources enhance customer perception. Wall-mounted configurations occupy the largest installation share in retrofit restaurant builds, whereas portable units represent the fastest-growing segment among food trucks and temporary catering operations.
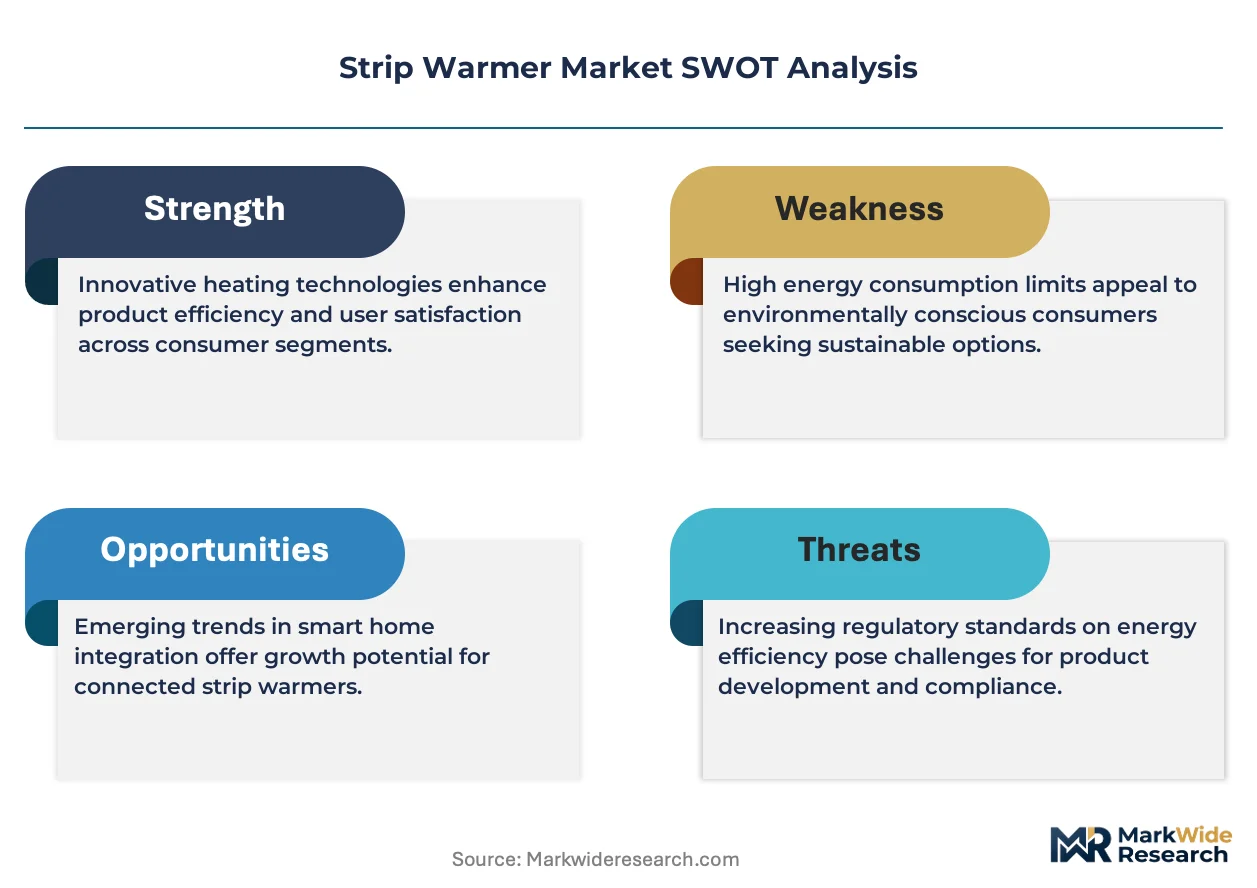
The U.S. Food and Drug Administration's Food Code establishes minimum hot-holding temperature thresholds that directly determine wattage specifications and control system requirements for commercial strip warmers. NSF International certification functions as a de facto market access gate for products sold into regulated foodservice channels across the United States. Underwriters Laboratories electrical safety standards shape heating element enclosure designs and cord specifications. Stakeholders must monitor evolving state-level energy conservation regulations that threaten to disqualify lower-efficiency resistance heating technologies from rebate-eligible procurement programs.
Market Dynamics
Quick-service restaurant chains are consolidating purchasing power through cooperative procurement networks, compressing margins for equipment manufacturers while simultaneously demanding shorter lead times and extended warranty terms.
Growth Catalysts
- Department of Energy efficiency mandates:Federal minimum efficiency standards are accelerating replacement cycles across institutional foodservice facilities, creating pull-through demand for infrared and LED-based heating systems.
- Food truck fleet expansion:Mobile catering operations in the United States are adopting portable strip warmer configurations to maintain FDA Food Code compliance without fixed ventilation infrastructure.
- Quartz infrared technology:Exhibition cooking environments favor visible radiant heat sources that enhance customer perception while reducing energy consumption versus calrod elements.
Market Restraints
- Nichrome alloy supply concentration:Heating element manufacturers face input cost volatility due to concentrated sourcing of nickel-chromium wire from limited specialty metal suppliers.
- Ventilation-constrained retrofit sites:Existing restaurant buildings without adequate hood systems cannot accommodate gas-powered units, restricting addressable market for dual-fuel product lines.
- Induction warming substitution:Drop-in induction holding bases are capturing countertop share in high-end catering operations where precise temperature control outweighs strip warmer simplicity.
Strategic Opportunities
- Utility rebate programs:State-level energy conservation incentives are creating procurement preference for NSF-certified infrared units that exceed federal efficiency baselines.
- Ghost kitchen infrastructure:Delivery-optimized commissary facilities require compact holding equipment configurations that traditional wall-mounted designs cannot address.
- Smart control integration:IoT-enabled temperature monitoring systems are converging with strip warmer hardware to enable remote compliance documentation for health inspectors.
Industry Challenges
- NSF certification timeline:Third-party testing protocols for food equipment sanitation create 4-6 month delays between design completion and commercial launch.
- Electrical contractor capacity:Installation backlogs in high-growth metropolitan markets are extending project completion dates and deferring revenue recognition for equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strip Warmer Market |
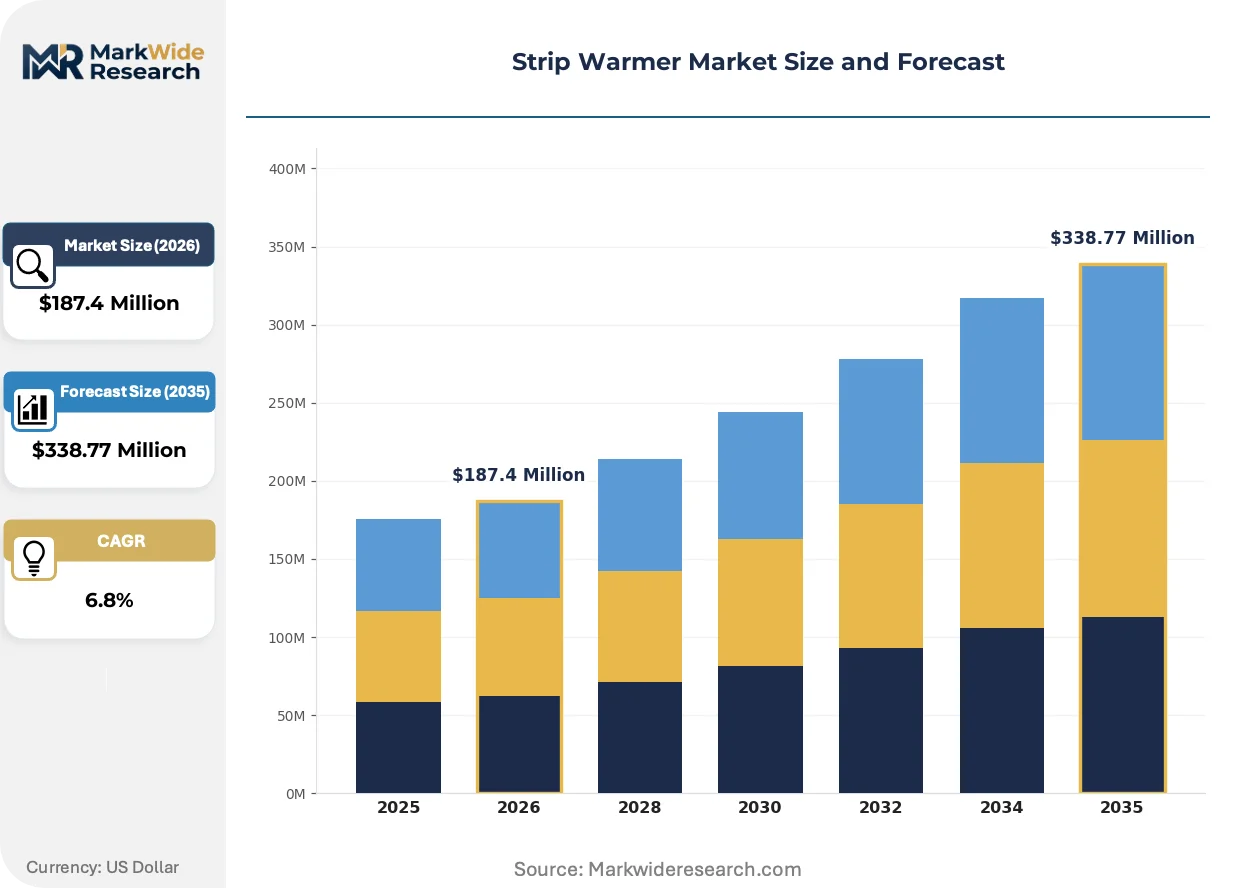
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Warmers, Electric Strip Warmers, Gas Strip Warmers, Temperature Control Warmers End User: Restaurants, Catering Services, Food Trucks, Hospitals Installation Type: Wall-Mounted, Ceiling-Suspended, Portable, Countertop Material: Stainless Steel, Aluminum, Plastic, Glass |
| Companies Covered | Hatco Corporation, Nemco Food Equipment Ltd., Vollrath Company, Wells Manufacturing, APW Wyott, Star Manufacturing, Toastmaster, Cadco Ltd., Globe Food Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strip Warmer Market Trends and Innovations
Equipment intelligence and energy performance are converging to redefine competitive differentiation, with connectivity features and thermal efficiency becoming inseparable purchase criteria rather than separate specification categories.
Quartz infrared tube technology is decentralizing heating element supply chains by enabling regional fabrication of specialized glass envelopes, reducing dependence on integrated calrod manufacturers. Mid-size foodservice distributors are adopting these modular components to assemble private-label warming equipment with localized support capabilities. The shift is compressing traditional OEM margins while expanding addressable market for aftermarket replacement parts.
REACH substance restrictions in the European Union are phasing out certain ceramic fiber insulation materials used in high-temperature strip warmer enclosures, forcing reformulation of thermal barrier systems. Manufacturers serving export markets must maintain dual material specifications to satisfy both EU chemical safety requirements and U.S. electrical codes. The regulatory divergence is increasing SKU complexity and inventory carrying costs for multinational suppliers.
Foodservice operators are consolidating vendor relationships through integrated equipment procurement platforms that bundle strip warmers with adjacent holding and serving categories. Broadline distributors are capturing specification influence that previously resided with specialized dealer networks, particularly in multi-unit chain accounts. The channel shift is most visible in the United States, where national purchasing cooperatives now dominate equipment selection for franchise systems exceeding fifty locations.
Strip Warmer Market Segmentation
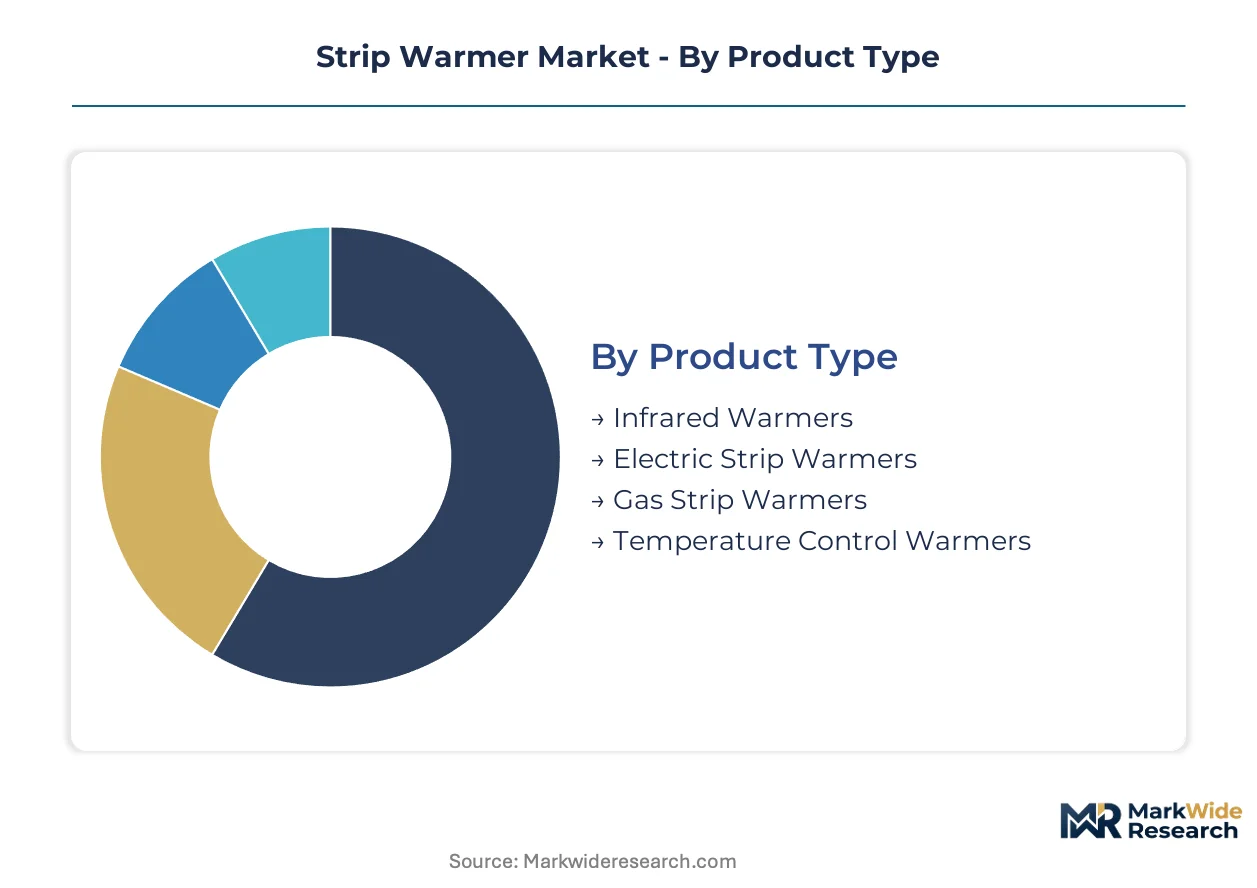
Strip warmer purchasing decisions cascade through multiple technical and operational dimensions. Product type determines energy infrastructure requirements, while installation constraints dictate physical form factor selection in retrofit versus new-build environments.
Product Type:
Integration depth varies sharply — infrared and electric units function as standalone plug-and-play systems, whereas gas configurations demand embedded hood ventilation infrastructure that constrains placement flexibility.
- Infrared Warmers:Quartz tube elements emit radiant heat at wavelengths optimized for food surface warming without moisture loss. Exhibition kitchens in Las Vegas and Orlando resorts specify these units for visible flame aesthetics that enhance customer perception during peak dining hours.
- Electric Strip Warmers:Calrod resistance elements convert electrical current to steady thermal output between 140°F and 185°F. Institutional cafeterias in Chicago and Boston school districts favor these where gas ventilation is unavailable or prohibitively expensive to install.
- Gas Strip Warmers:Open-flame burners deliver higher BTU output per linear foot than electric equivalents. These units concentrate in Texas and Arizona markets where natural gas rates undercut electricity pricing for high-volume operations.
- Temperature Control Warmers:Microprocessor-regulated systems modulate output based on food load sensors. Ghost kitchen operators in Atlanta and Dallas deploy these for precise holding compliance across variable menu mixes.
Volume placements concentrate in Electric Strip Warmers; the faster expansion belongs to Infrared Warmers.
End User:
Customer sophistication tiers separate specification authority — chains with centralized procurement teams versus independent operators making point-of-need decisions.
- Restaurants:Full-service and quick-service establishments represent the foundational demand base. National burger chains operating across California, Texas, and Florida standardize on NSF-certified wall-mounted configurations to simplify maintenance protocols.
- Catering Services:Mobile and banquet operations require rapid deployment capabilities. Off-premise catering companies in New York and Washington D.C. metropolitan areas drive portable unit adoption for venue-flexible service.
- Food Trucks:Space-constrained mobile kitchens prioritize compact footprint and electrical compatibility. Fleet operators in Portland and Austin favor 12-inch and 18-inch countertop models that fit standard service window configurations.
- Hospitals:Healthcare foodservice demands HACCP documentation and precise temperature logging. Medical center cafeterias in Cleveland and Minneapolis specify units with integrated probe connections for continuous monitoring compliance.
Restaurants account for the largest installed base; Food Trucks are climbing the fastest as municipal permitting accelerates mobile foodservice expansion.
Installation Type:
Physical mounting determines both capital cost structure and operational adaptability — fixed infrastructure versus reconfigurable assets.
- Wall-Mounted:Permanent bracket installation at 30-36 inches above service lines. Retrofit projects in Philadelphia and Detroit favor these for maximizing linear holding capacity without sacrificing floor space.
- Ceiling-Suspended:Drop-down configurations for open kitchen sightline management. Exhibition cooking stations in Miami and Seattle deploy these to eliminate visual obstruction while maintaining radiant heat coverage.
- Portable:Self-contained units on casters with integrated electrical cord management. Temporary catering operations and emergency feeding programs in Houston and Denver specify these for rapid site mobilization.
- Countertop:Surface-placed units requiring no mechanical attachment. Food truck builders in Nashville and Phoenix standardize these for compliance with vehicle weight distribution and stability regulations.
Wall-Mounted configurations dominate replacement demand; Countertop placements are gaining share fastest among mobile and compact kitchen formats.
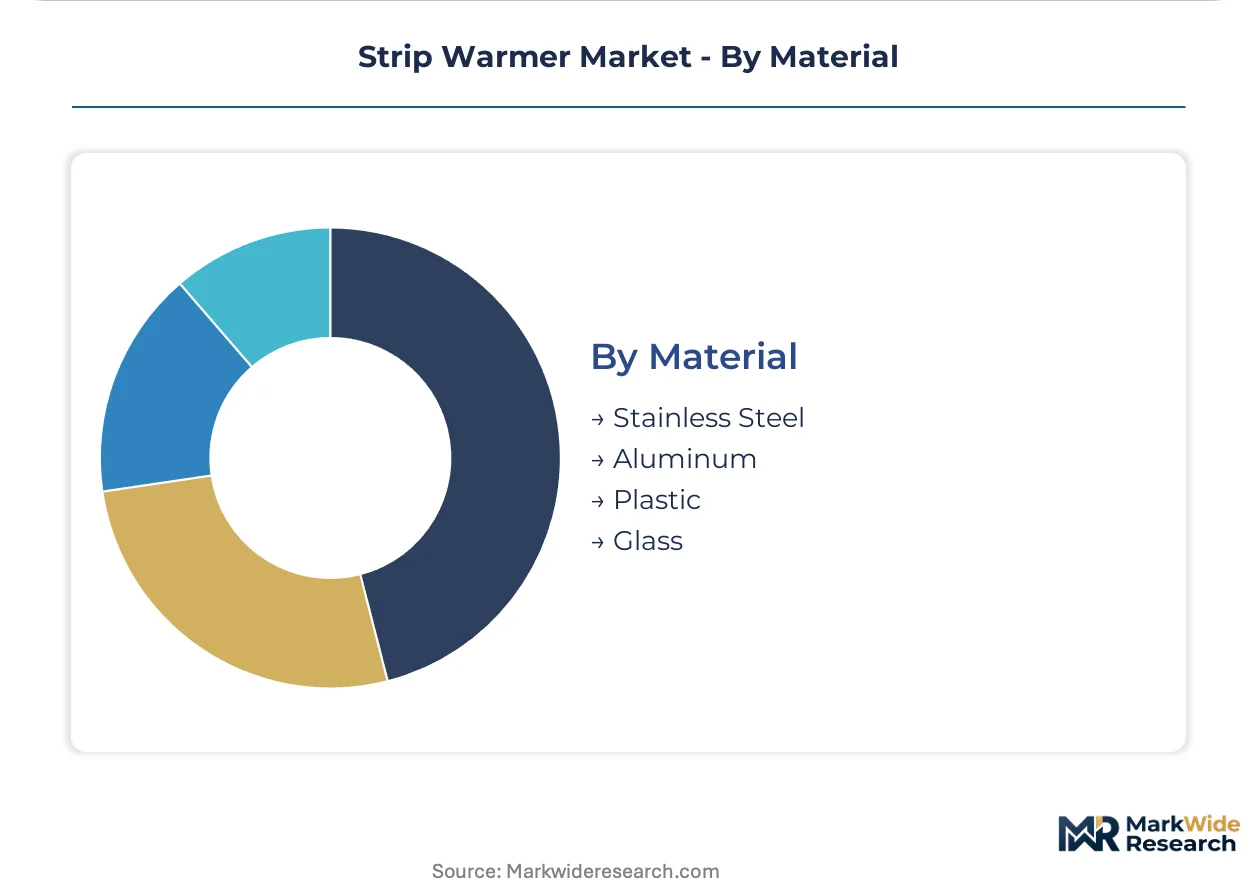
Material:
Surface composition trades off durability, thermal performance, and sanitation compliance — with cost tiering that separates premium from utility procurement.
- Stainless Steel:304 and 430 grade alloys resist corrosion and withstand aggressive cleaning chemicals. High-volume institutional kitchens in Boston and San Francisco specify 304-grade enclosures for maximum service life under continuous operation.
- Aluminum:Lightweight extrusions reduce shipping costs and simplify ceiling-suspended installations. Mid-market restaurant chains in Charlotte and Indianapolis adopt these for cost-controlled new construction projects.
- Plastic:Thermoplastic housings for low-temperature display applications and customer-facing warming stations. Quick-service salad concepts in Southern California deploy these for color-matched branding integration.
- Glass:Tempered panels for display merchandising and sneeze guard integration. Buffet operators in Las Vegas and Atlantic City casino properties favor these for visual access to held products.
Stainless Steel commands the majority of commercial procurement; Aluminum is expanding most quickly as weight and freight cost optimization priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nichrome alloy supply from specialty metal refineries in Pennsylvania and Ohio anchors North American strip warmer manufacturing, while finished equipment assembly concentrates in Wisconsin and Texas industrial corridors.
United States
Quick-service restaurant chains in California and Texas drive replacement cycles for NSF-certified infrared units. The Department of Energy's federal efficiency standards accelerate institutional procurement of LED-based heating systems. Equipment fabricators in Milwaukee and Dallas-Fort Worth expand captive production of quartz tube elements to reduce import dependence.
Germany
Commercial kitchen operators in Bavaria and North Rhine-Westphalia specify REACH-compliant thermal barrier materials for export-compatible product lines. ECHA substance restrictions phase out legacy ceramic fiber insulations, forcing reformulation of high-temperature enclosures. Manufacturing clusters around Stuttgart and Hamburg maintain dual material specifications to serve both EU and North American regulatory regimes.
China
Domestic foodservice expansion in Shanghai and Guangzhou creates demand for compact countertop warming configurations. GB standards for electrical safety shape heating element enclosure designs for the local market. Production gravity in Zhejiang and Jiangsu provinces supplies private-label equipment to mid-size distributors across Southeast Asia.
Japan
Precision temperature control requirements in Tokyo and Osaka healthcare foodservice favor microprocessor-regulated warming systems. METI energy conservation guidelines incentivize infrared technology adoption in institutional kitchens. Industrial concentration in Aichi Prefecture supports specialized glass envelope fabrication for quartz tube elements.
United Kingdom
Ghost kitchen proliferation in London and Manchester drives demand for space-optimized holding equipment configurations. CE marking requirements align product specifications with continental European export standards. Fabricators in the Midlands region assemble portable units for catering operators serving the Southeast corridor.
Strip Warmer Market Competitive Landscape
Backward integration into heating element manufacturing dominates the current landscape, with specialists consolidating control over critical input costs. The vendor base organizes around three strategic archetypes: vertically integrated OEMs with captive nichrome wire production, regional fabricators assembling modular infrared components, and broadline distributors bundling warming equipment with adjacent holding categories. M&A activity concentrates among mid-cap specialists seeking geographic expansion, while technology licensing agreements proliferate around IoT-enabled temperature monitoring systems.
Among North American equipment specialists, Hatco Corporation exemplifies the vertically integrated archetype through in-house production of heating elements. Nemco Food Equipment Ltd. occupies a position within the compact-design specialist tier. Vollrath Company anchors the stainless steel fabrication vector, with capabilities extending across adjacent holding equipment categories.
| Leading Market Players |
|---|
| Hatco Corporation |
| Nemco Food Equipment Ltd. |
| Vollrath Company |
| Wells Manufacturing |
| APW Wyott |
| Star Manufacturing |
| Toastmaster |
| Cadco Ltd. |
| Globe Food Equipment |
| Others |
Pricing and Supply Chain Analysis
Specialized glassblowers in Aichi Prefecture command wage premiums that cascade through quartz infrared tube production, widening spreads between premium NSF-certified systems and economy-grade calrod alternatives across North American distribution channels.
Pricing Analysis
Warranty bundling separates premium-tier manufacturers offering five-year component coverage from unbundled economy suppliers charging separately for field service calls. Pricing stratifies across premium, standard, and economy tiers based on NSF certification grade and infrared versus resistance heating technology. Cost compression in the standard tier is intensifying because cooperative procurement networks at quick-service chains demand extended coverage without corresponding price premiums. Independent restaurants exhibit highest price sensitivity, while ghost kitchen operators prioritize temperature-control precision over upfront equipment cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national restaurant chains, while specialized foodservice distributors serve independent operators through localized inventory positions. Manufacturing concentrates in the United States, Germany, and China, with nichrome alloy wire drawing from Pennsylvania and Ohio refineries. Production draws from quartz glass tubing, nickel-chromium heating wire, and stainless steel enclosures as core inputs. Single-source vulnerability in specialty metal supply threatens margin stability when nickel spot markets fluctuate. Distribution runs through broadline equipment distributors consolidating specification influence across multi-unit accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nichrome wire drawing capacity constraints at Pennsylvania specialty metal refineries prop pricing power for manufacturers with captive heating element supply, sustaining margin premiums across the analysis window.
For Market Incumbents: Acquire regional quartz tube fabrication capabilities to secure infrared technology supply against emerging modular component assemblers. Expand captive nichrome wire production in Ohio industrial corridors to offset alloy price volatility from concentrated specialty metal suppliers. Deepen backward integration into glass envelope manufacturing before European REACH restrictions further constrain insulation material sourcing.
For New Entrants and Emerging Players: Enter via portable strip warmer configurations for food truck fleet operators in Portland and Austin, where incumbent coverage remains thin and electrical contractor relationships are undeveloped. Target ghost kitchen infrastructure in Atlanta and Dallas with compact countertop designs that traditional wall-mounted suppliers cannot address. Pursue private-label assembly partnerships with mid-size distributors seeking localized support capabilities.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated OEMs with in-house heating element production given Department of Energy efficiency mandate acceleration. Long-term viability favors manufacturers controlling critical input costs across a five-to-ten year technology transition window. Monitor state-level utility rebate program expansions as inflection indicators for infrared technology adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive nichrome wire production insulates Hatco Corporation from Pennsylvania alloy supply volatility. |
| IoT-Enabled Temperature Monitoring Integration | Remote compliance documentation addresses FDA Food Code enforcement trends in healthcare foodservice. |
| REACH-Compliant Thermal Barrier Reformulation | Ceramic fiber substitution maintains EU market access for Wisconsin and Texas equipment fabricators. |
| Portable Configuration Development | Compact countertop designs capture food truck fleet expansion in Portland and Austin municipal permitting waves. |
| Utility Rebate Program Certification | NSF-certified infrared qualification unlocks state-level energy conservation incentive procurement channels. |
Research Methodology
Document review covered NSF International certification databases, FDA Food Code regulatory filings, and Department of Energy efficiency standard dockets, complemented by interviews with commercial kitchen equipment procurement managers, foodservice distributor category buyers, electrical contractor project supervisors, and restaurant chain facilities directors. Secondary validation drew from UL safety standard documentation, trade customs data, and SEC filings of publicly held equipment manufacturers. Bottom-up demand modeling triangulated against top-down market sizing from industry association shipment reports.
Historical volume trajectories cross-referenced against expert panel inputs on technology substitution rates and regulatory implementation timelines. Segmentation dimensions modeled include product type, end user category, installation configuration, material specification, and regional regulatory cluster. CAGRs derived from curve-fitting approaches applied to replacement cycle data and new installation permits. Industry-specific forecast inputs incorporated food truck fleet registration growth and ghost kitchen square footage expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nichrome alloy supply disruption or accelerated induction warming substitution scenarios. Projections reflect assumptions on cooperative procurement network consolidation and state rebate program adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Compressed Air Treatment Equipment Market